
 Pultrusion Products Market | 2026-2036
Pultrusion Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pultrusion Products Market Analysis
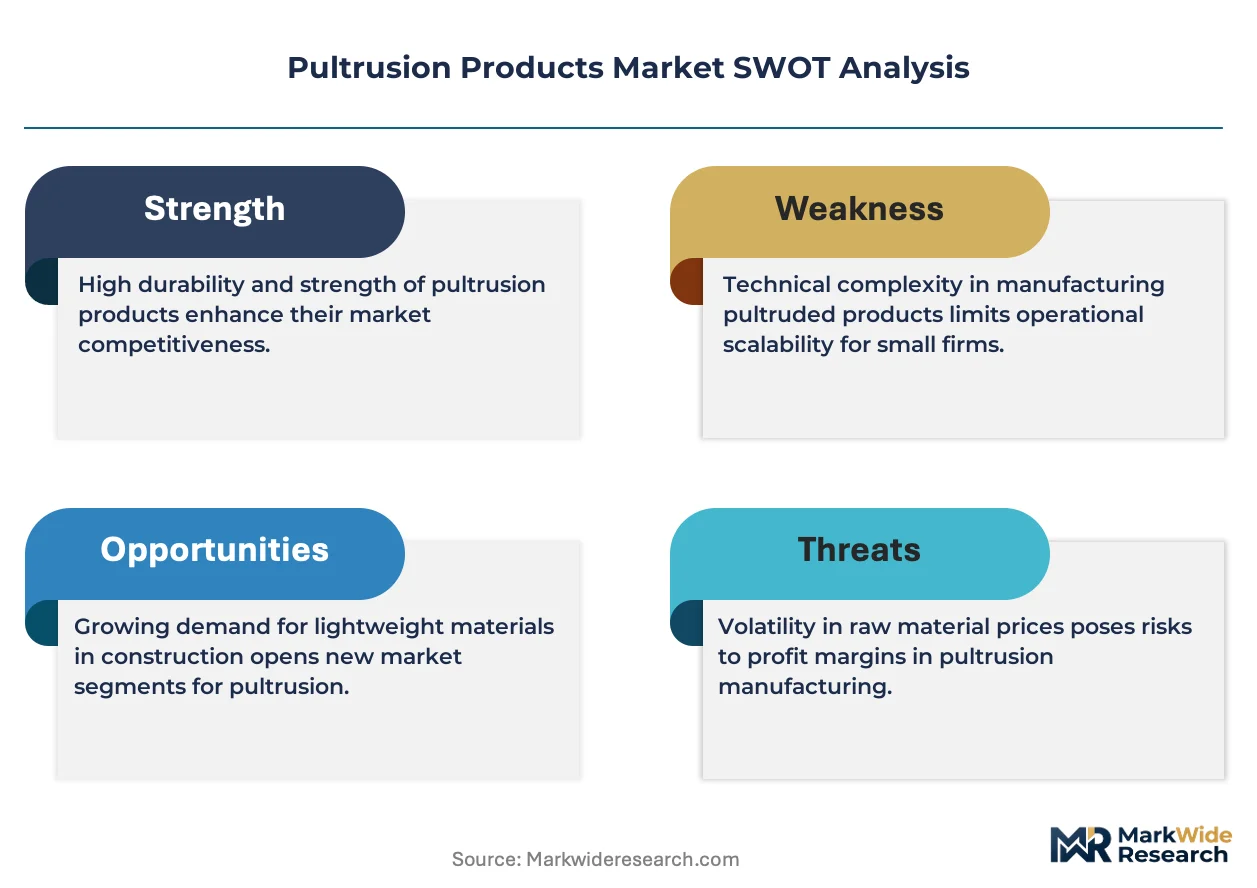
A capital-intensity divergence between automated continuous pultrusion lines and batch-oriented legacy setups is redrawing competitive boundaries in the industry. Exel Composites Oyj leverages its Nordic manufacturing footprint to dominate European wind energy and transportation contracts. Strongwell Corporation anchors North American demand through its extensive distributor network serving corrosion-resistant industrial applications. Fiberline Composites A/S differentiates via specialized carbon fiber profiles for civil engineering reinforcement projects.
Pultrusion products are fiber-reinforced polymer profiles manufactured by pulling continuous fiber rovings through a resin bath and heated die, yielding consistent cross-sectional shapes with high strength-to-weight ratios and corrosion immunity. The process typically achieves fiber volume fractions of 50-70% with thermoset matrices such as vinyl ester, polyester, or epoxy, serving structural load-bearing needs across infrastructure, electrical, and chemical processing industries. Structural profiles and tubes command the largest volume share due to their substitution of steel and aluminum in corrosive environments, while carbon fiber material grades represent the fastest-expanding margin pool as aerospace and wind turbine OEMs specify higher-performance alternatives to fiberglass. Composite rods maintain steady demand in electrical insulation and cable core applications where dielectric properties outweigh structural optimization.
REACH in Europe restricts styrene emissions and hazardous substance content in resin formulations, compelling reformulation investments across export-oriented suppliers. The FAA maintains stringent qualification protocols for composite materials in primary aircraft structures, creating certification barriers that filter supplier eligibility for aerospace components. China's GB standards and dual carbon goals are accelerating domestic substitution of steel reinforcement with fiberglass pultruded rebar in coastal construction. Stakeholders must monitor evolving building code approvals for composite materials in structural concrete applications, as code adoption velocity will determine regional demand inflection points more decisively than raw material cost movements.
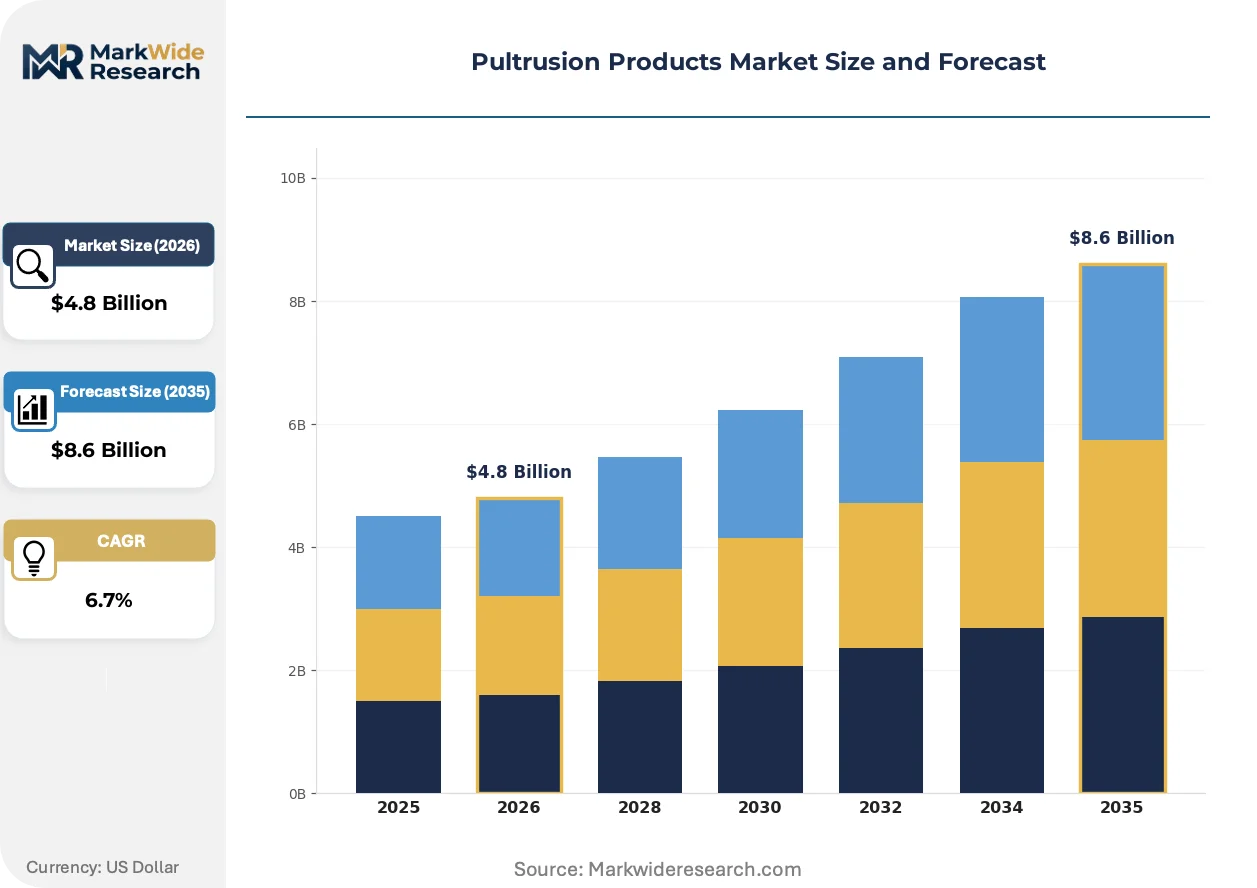
Market Dynamics
Continuous processing automation is bifurcating the pultrusion landscape between high-throughput continuous lines and batch legacy equipment, with capital requirements determining which manufacturers capture aerospace and wind energy contracts versus commoditized industrial profiles.
Growth Catalysts
- Infrastructure renewal mandates:Bridge decking and utility pole replacement programs in Germany, Japan, and the United States specify fiberglass structural profiles for corrosion resistance and extended service life.
- REACH compliance reformulation:European resin suppliers invest in low-styrene and bio-based formulations to meet ECHA emission thresholds, opening premium positioning for compliant producers.
- Wind turbine blade scaling:Carbon fiber pultruded spar caps enable longer rotor diameters as OEMs source from China's coastal manufacturing corridors.
Market Restraints
- Raw material concentration:Carbon fiber supply concentrates among Japanese and American producers, exposing pultruders to price volatility and allocation constraints.
- Building code heterogeneity:Fragmented approval pathways for composite reinforcement in structural concrete delay specification across municipal jurisdictions.
- Steel substitution economics:Commodity steel rebar maintains cost advantage in non-corrosive environments, limiting pultruded rebar penetration in inland construction.
Strategic Opportunities
- Offshore wind expansion:Floating turbine platforms in the North Sea and Asia-Pacific require corrosion-immune foundation components that pultruded profiles deliver.
- GB standard alignment:China's dual carbon goals accelerate domestic substitution of steel reinforcement with fiberglass pultruded rebar in coastal provinces.
- Resin infusion hybridization:Combining pultrusion with vacuum-assisted resin transfer enables complex geometries for automotive battery enclosures and rail interior panels.
Industry Challenges
- FAA qualification timelines:Primary aircraft structure certification requires multi-year testing protocols that filter supplier eligibility and compress margins for aerospace components.
- Die design specialization:Custom profile engineering demands CAD-CAM expertise and heated die fabrication capabilities that concentrate among legacy equipment builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pultrusion Products Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Rods, Laminated Sheets, Structural Profiles, Tubes Material: Fiberglass, Carbon Fiber, Aramid Fiber, Thermoplastics End User: Aerospace Industry, Construction Sector, Electrical Industry, Marine Applications Application: Electrical Insulation, Structural Components, Chemical Processing, Aerospace Components |
| Companies Covered | Exel Composites Oyj, Tencom Limited, Strongwell Corporation, Diversified Structural Composites, Creative Composites Group, Creative Pultrusions, Fiberline Composites A/S, Faigle Kunststoffe GmbH, Bedford Reinforced Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pultrusion Products Market Emerging Trajectories
Thermoset automation and thermoplastic processing advances are diverging equipment investment paths, while regulatory pressure on embodied carbon reshapes material selection criteria across transportation and construction verticals.
Thermoplastic pultrusion systems utilizing continuous fiber-reinforced polypropylene and PEEK matrices are fragmenting the historical thermoset dominance in structural profiles. Automotive underbody shields and aircraft interior panels specify these recyclable alternatives for end-of-life compliance. The technology is fragmenting supplier specialization between high-temperature die engineering specialists and conventional polyester-vinyl ester houses.
REACH Annex XVII restrictions on styrene monomer content compel European formulators to accelerate methacrylate and bio-epoxy resin development. Industrial hygiene compliance costs now determine facility location decisions for export-oriented suppliers. German chemical processors lead reformulation investments, while Italian and Spanish producers face consolidation pressure from compliance capital requirements.
Specification authority is migrating from general contractors to engineering-procurement-construction firms with composite design competency. EPCs now bundle pultruded structural packages with installation warranties, displacing traditional distributor relationships in chemical processing and power generation projects. This concentration is most visible in the US Gulf Coast and Rotterdam-Antwerp industrial clusters where integrated EPCs dominate capital project awards.
Pultrusion Products Market Segmentation
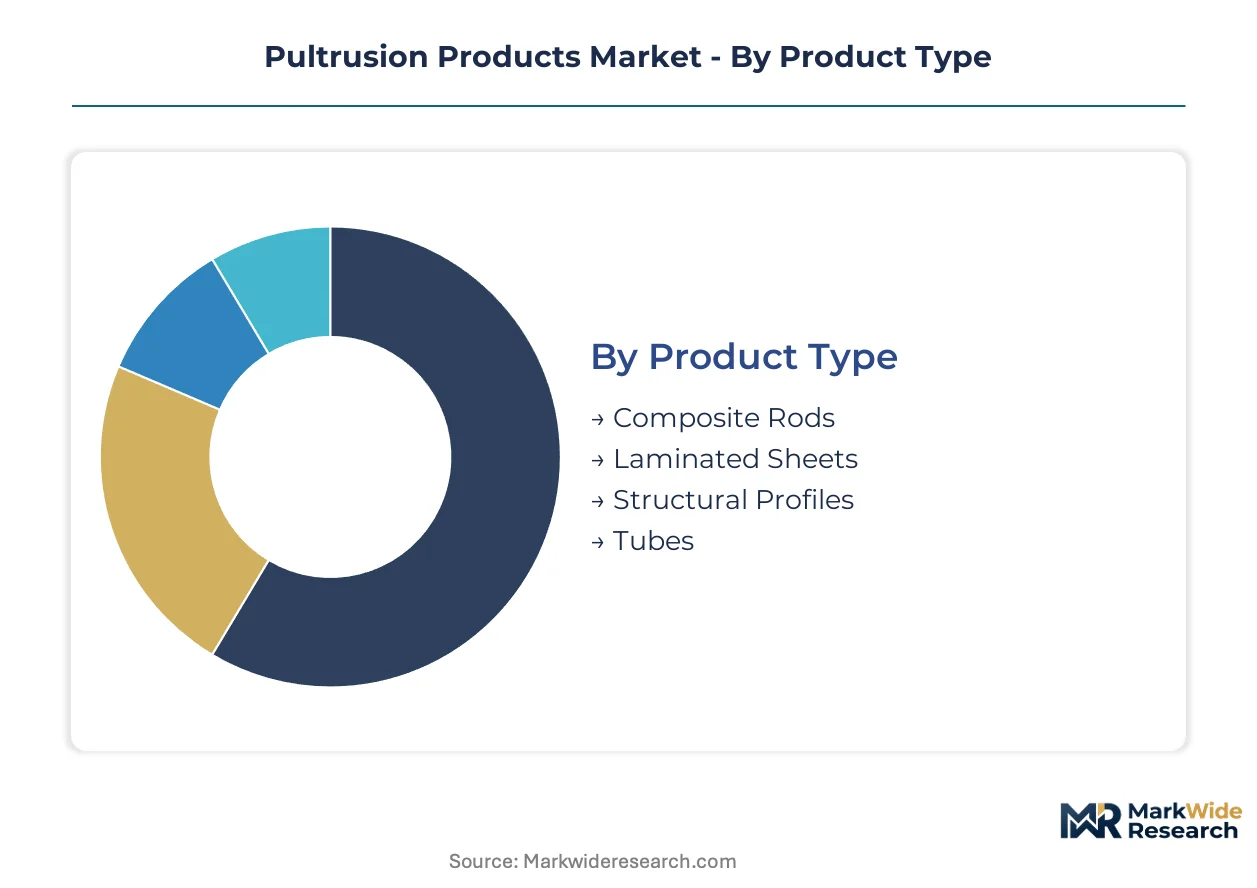
Pultrusion product specifications diverge sharply across end-use requirements, with corrosion resistance, dielectric properties, and strength-to-weight ratios determining material selection. Segmentation reveals where fiberglass substitutes for steel versus where carbon fiber commands premium positioning.
Product Type:
Substitution pressure from extruded aluminum and roll-formed steel is most acute in standard structural sections, forcing pultruders to differentiate through custom engineering and corrosion guarantees.
- Structural Profiles:I-beams, channels, and angles fabricated with 50-70% fiber volume fraction serve bridge decking and utility pole applications across Germany, Japan, and the United States. Infrastructure renewal mandates specify these profiles for 75-year service life in corrosive environments.
- Tubes:Hollow sections ranging from electrical conduits to large-diameter support columns dominate chemical processing plant construction. Demand concentrates in US Gulf Coast and Rotterdam-Antwerp industrial clusters where EPCs bundle structural packages with installation warranties.
- Composite Rods:Solid profiles with precise dielectric properties anchor electrical insulation and cable core applications.
- Laminated Sheets:Flat panels produced via modified pultrusion lines serve equipment housings and architectural cladding.
Structural profiles anchor the volume base while tubes gain share at the steepest rate.
Material:
Cost tier fragmentation separates commodity fiberglass from performance grades, with thermoplastic processing advances creating a recyclable premium tier above thermoset dominance.
- Fiberglass:E-glass and E-CR glass rovings with vinyl ester or polyester matrices deliver corrosion immunity at cost parity with coated steel. GB standards in China's coastal provinces are accelerating substitution of steel reinforcement with fiberglass pultruded rebar.
- Carbon Fiber:PAN-based and pitch-based fibers with epoxy matrices achieve fiber volume fractions exceeding 60% for aerospace primary structures and wind turbine spar caps. Japanese and American producers control supply concentration, exposing pultruders to allocation constraints.
- Aramid Fiber:Kevlar and Twaron reinforcements provide ballistic and impact resistance for specialized protective applications.
- Thermoplastics:Continuous fiber-reinforced polypropylene and PEEK matrices enable automotive underbody shields and aircraft interior panels with end-of-life recyclability.
Carbon fiber commands the highest margin tier while thermoplastics expand most quickly as REACH Annex XVII pressures reshape formulation priorities.
End User:
Application maturity varies dramatically, with electrical insulation representing decades-old specification pathways versus aerospace qualification protocols that filter supplier eligibility.
- Construction Sector:Civil engineering reinforcement, bridge decking, and coastal infrastructure specify pultruded profiles for chloride resistance. Building code heterogeneity across municipal jurisdictions delays specification in inland markets where steel rebar maintains cost advantage.
- Electrical Industry:Transmission line hardware, cable support systems, and substation structures leverage dielectric properties. Specification authority has migrated from distributors to engineering-procurement-construction firms with composite design competency.
- Aerospace Industry:Primary aircraft structures require FAA qualification protocols with multi-year testing timelines that compress margins.
- Marine Applications:Offshore wind platforms and vessel components demand corrosion-immune foundation elements.
The electrical industry provides the most stable demand base while marine applications climb the fastest as floating turbine platforms proliferate in the North Sea.
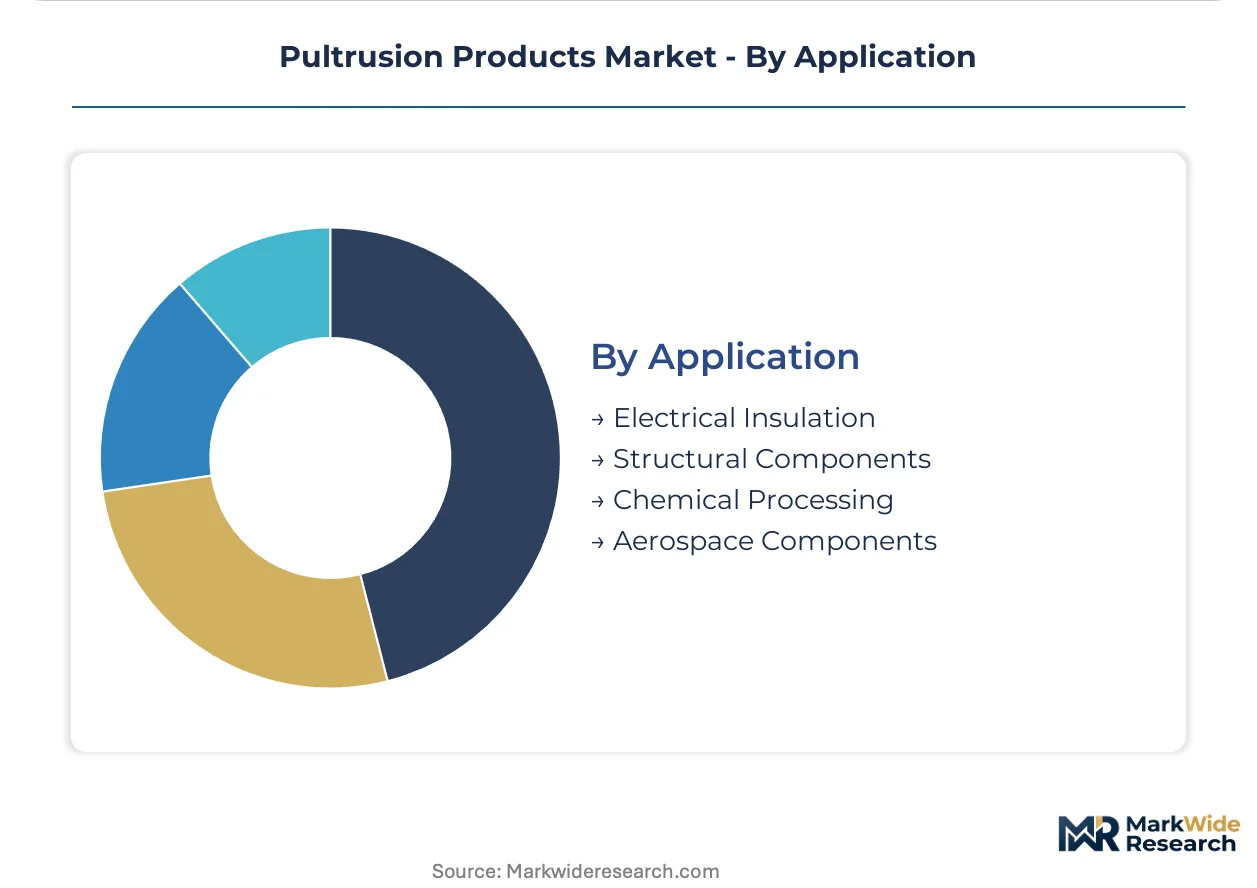
Application:
Functional performance requirements create distinct procurement patterns, with dielectric specifications tolerating less variance than structural load-bearing criteria.
- Electrical Insulation:Dielectric rods and support structures for high-voltage transmission require precise resin formulation control. REACH compliance in Europe compels low-styrene and bio-based formulation investments among export-oriented suppliers.
- Structural Components:Load-bearing profiles for infrastructure and industrial construction substitute for steel and aluminum. FAA airworthiness criteria for composite materials are reshaping resin formulation priorities among manufacturers serving transportation adjacent markets.
- Chemical Processing:Corrosion-resistant grating, handrails, and equipment supports serve petrochemical and water treatment facilities.
- Aerospace Components:Primary and secondary structures for commercial and defense aircraft demand qualification documentation.
Structural components generate the broadest revenue base while aerospace components pursue the steepest expansion trajectory as qualification barriers filter competitive entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, accepting premiums for REACH-compliant formulations and 75-year service life guarantees. Chinese wind energy OEMs operate at the highest elasticity, driving carbon fiber pultrusion costs down through concentrated coastal procurement. Infrastructure programs in the United States sit between these poles, balancing corrosion resistance specifications against municipal budget constraints.
Germany
Bridge decking renewal programs across the Rhine-Ruhr corridor specify fiberglass structural profiles for chloride resistance. ECHA enforcement of REACH Annex XVII styrene thresholds compels resin reformulation investments among Bavarian chemical processors. The Stuttgart industrial cluster hosts heated die engineering specialists serving automotive underbody shield contracts.
United States
FAA airworthiness protocols for composite primary structures filter supplier eligibility for aerospace-adjacent markets. Infrastructure mandates in coastal states accelerate utility pole replacement with corrosion-immune profiles. The US Gulf Coast petrochemical corridor concentrates demand for chemical-resistant grating and handrail systems.
China
Wind turbine OEMs in Jiangsu and Guangdong provinces source carbon fiber pultruded spar caps for next-generation rotor designs. GB standards alignment with dual carbon goals accelerates fiberglass rebar substitution in coastal construction. The Yangtze River Delta manufacturing belt concentrates automated continuous pultrusion capacity.
Japan
METI-sponsored infrastructure resilience programs specify extended-service-life materials for seismic zone applications. JIS standards for fiber-reinforced polymers create certification pathways distinct from European and American regimes. The Chubu industrial region around Nagoya hosts precision die fabrication capabilities serving automotive tier-one suppliers.
Pultrusion Products Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Automated continuous line operators capture aerospace and wind energy contracts through capital intensity, while batch-oriented legacy fabricators serve commoditized industrial profiles. Three archetypes dominate: Nordic-origin wind energy specialists, North American corrosion-application distributors, and Chinese coastal scale producers. Consolidation pressure concentrates among European formulators facing REACH compliance capital requirements, while partnership strategies proliferate between resin suppliers and heated die engineering houses.
Among Nordic-origin specialists, Exel Composites Oyj and Fiberline Composites A/S exemplify the premium-tier positioning built on carbon fiber civil engineering capabilities. Strongwell Corporation anchors the North American distributor-anchored model serving corrosion-resistant industrial applications. These three occupy positions reflecting divergent geographic and application specializations rather than direct product overlap.
| Leading Market Players |
|---|
| Exel Composites Oyj |
| Tencom Limited |
| Strongwell Corporation |
| Diversified Structural Composites |
| Creative Composites Group |
| Creative Pultrusions |
| Fiberline Composites A/S |
| Faigle Kunststoffe GmbH |
| Bedford Reinforced Plastics |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day heated die fabrication lead times concentrate pricing power among Bavarian and Nagoya engineering houses serving aerospace qualification pathways. This supply bottleneck reinforces premium capture for REACH-compliant resin formulations while batch-oriented legacy fabricators absorb margin compression in commoditized industrial profiles.
Pricing Analysis
After-sales service contracts for 75-year infrastructure warranties drive lifetime value capture across German bridge decking and Japanese utility pole programs. Three-tier pricing structure across aerospace-qualified, industrial-grade, and construction-commodity levels separates carbon fiber spar caps from E-glass structural sections. Cost compression in standard profiles intensifies as Chinese coastal manufacturers scale automated continuous lines. Wind energy OEMs in Jiangsu province demonstrate the highest price elasticity, while FAA-certified aerospace buyers accept substantial premiums for qualified material documentation.
Supply Chain Analysis
Japan and the United States anchor carbon fiber precursor supply for aerospace-grade pultrusion, while China dominates E-glass roving and vinyl ester resin production for construction applications. The supply chain draws from PAN-based fiber feedstocks, thermoset resin formulations, and precision-machined heated die tooling. Single-source vulnerability concentrates in Japanese Toray-grade carbon fiber allocations for wind turbine spar caps. Distribution runs through engineering-procurement-construction firms bundling structural packages with installation warranties across Rotterdam-Antwerp and US Gulf Coast industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FAA qualification protocols and REACH compliance create multi-year barriers that filter supplier eligibility and protect incumbent positioning.
For Market Incumbents: Fortify certification portfolios by deepening backward integration into carbon fiber precursor supply and expanding heated die engineering capacity in Stuttgart and Nagoya industrial clusters. Emerging Chinese scale producers threaten margin compression in construction-grade profiles, making aerospace qualification maintenance the priority defensive lever. For New Entrants and Emerging Players: Lead with thermoplastic pultrusion capabilities for automotive underbody shields and aircraft interior panels where end-of-life recyclability commands specification premiums. China's coastal provinces offer the most penetrable geography given GB standard alignment with dual carbon goals. Partner with European resin formulators to bypass REACH compliance capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized pultrusion assets stranded by REACH reformulation requirements. Long-term viability centers on qualification moats rather than scale economies. Watch FAA certification timeline acceleration as the signal indicating aerospace demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | ECHA Annex XVII alignment opens premium positioning for Bavarian chemical processors serving export markets. |
| Carbon Fiber Backward Integration | Upstream control over PAN precursor supply mitigates allocation risk from Japanese and American producers. |
| Thermoplastic Processing Capacity | PEEK and polypropylene matrix lines capture automotive and aerospace recyclable specification demand. |
| Heated Die Engineering Specialization | CAD-CAM expertise concentration in Nagoya and Stuttgart supports custom profile premium capture. |
| EPC Partnership Structuring | Installation warranty bundling displaces traditional distributor relationships in chemical processing clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from pultrusion plant managers, wind energy procurement leads, EPC contractors with composite design competency, and FAA certification specialists, then refined through secondary validation. Sources included customs and trade data for carbon fiber and resin flows, SEC filings from publicly traded composite manufacturers, ECHA REACH registration databases, and GB standards documentation from China's Standardization Administration. Bottom-up capacity assessments and top-down demand modeling were triangulated across these inputs.
Variance decomposition across material grade, end-use industry, geographic production hub, and regulatory compliance tier structured the analytical framework. CAGRs were derived from segmented volume and value trajectories modeled across the projection horizon. Industry-specific forecast inputs incorporated wind turbine blade scaling curves and infrastructure renewal program commit schedules from Germany, Japan, and the United States.
The analysis sits within stated boundaries; outcomes outside sustained carbon fiber supply allocation, building code adoption velocity, or FAA certification timeline stability would require recalibration. Forecasts reflect documented assumptions about resin formulation cost curves and thermoplastic processing yield improvements. Recalibration cycles align with material shifts in ECHA enforcement patterns and dual carbon goal implementation across China's coastal provinces.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Paint Knife Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
North America Industrial Fasteners Market