
 Tablet Press Tooling Market | 2026-2036
Tablet Press Tooling Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Press Tooling Market Insights
Multi-tip tooling specification upgrades is unwinding legacy single-tip capacity across high-volume pharmaceutical facilities. Natoli Engineering leverages its domestic manufacturing footprint to sustain rapid custom tool delivery for North American generic producers. Wilson Tool anchors European demand through specialized coating technologies that extend punch life in abrasive formulations. I Holland competes on precision grinding capabilities that meet narrow tolerance bands required by FDA-validated lines.
Tablet press tooling comprises precision-machined punches and dies engineered from hardened tool steel, tungsten carbide, or ceramic substrates to compress granulated material into uniform tablets under forces exceeding ten tons. The primary purpose centers on delivering dimensional consistency, surface finish integrity, and batch reproducibility across rotary tablet press operations. Flat punches occupy the largest volume share in generic pharmaceutical applications where simple tablet geometries dominate throughput economics. Tungsten carbide tooling represents the fastest-expanding material segment as manufacturers seek wear resistance for high-abrasion active pharmaceutical ingredients. Multi-tip punches command premium positioning by enabling simultaneous multi-cavity compression that doubles effective output from existing press platforms.
FDA validation requirements and EMA GMP Annex 15 guidelines mandate documented tool qualification, traceable material certificates, and preventive replacement schedules that elevate tooling procurement standards. ISO 9001 and EU MDR frameworks further tighten dimensional tolerance documentation and supplier audit protocols for European pharmaceutical manufacturers. Stakeholders must monitor how regulatory convergence between FDA and EMA on data integrity expectations reshapes supplier qualification timelines and tooling lifecycle documentation obligations.
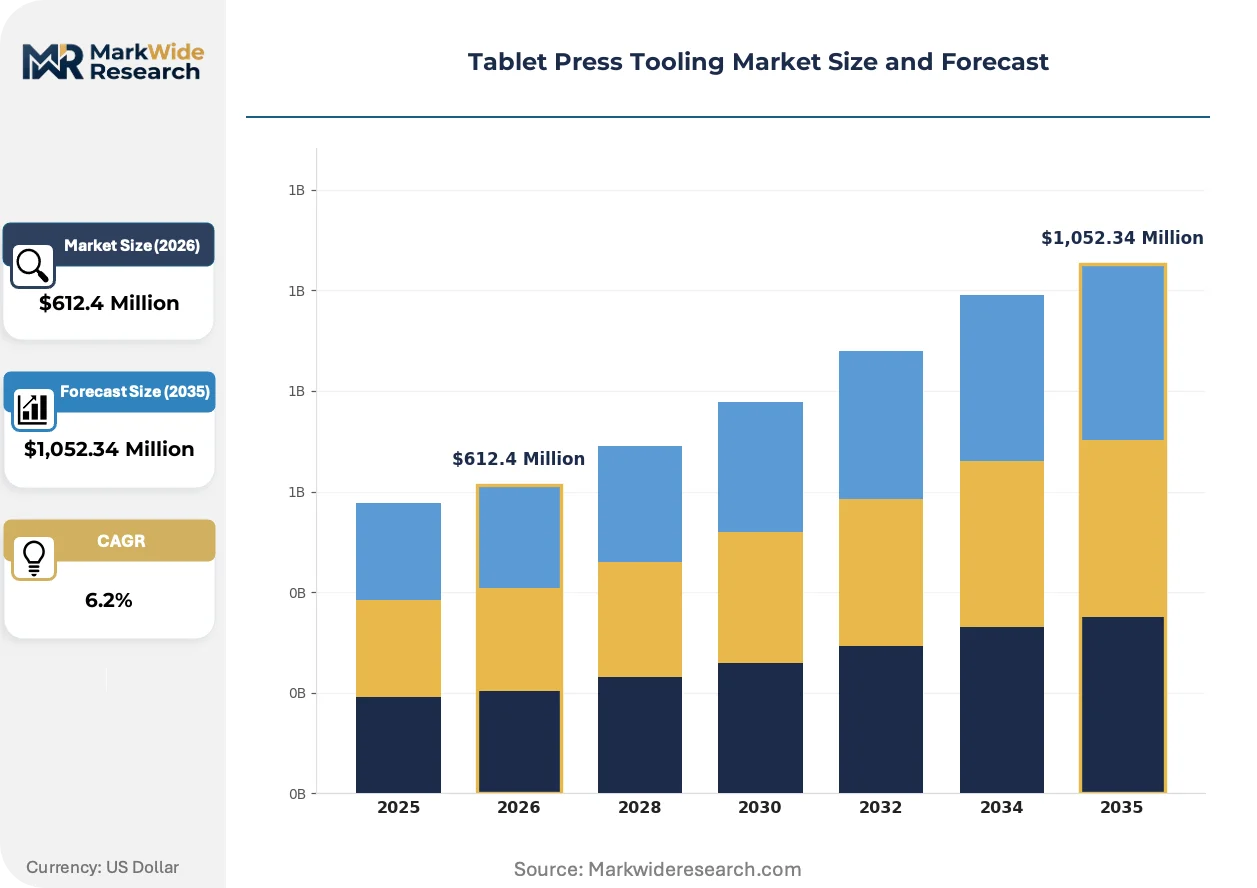
Market Dynamics
Tungsten carbide tooling is decomposing legacy steel-grade capacity as pharmaceutical manufacturers confront abrasive active ingredients and extended production runs. FDA validation timelines and EMA GMP Annex 15 documentation requirements compress replacement cycles and elevate supplier qualification barriers.
Growth Catalysts
- EMA GMP Annex 15:Mandated tool qualification and traceable material certificates force documented preventive replacement schedules that sustain recurring tooling procurement.
- Multi-tip compression technology:Simultaneous multi-cavity tooling doubles effective output from existing press platforms without capital expansion.
- Contract manufacturing clusters in India:Generic pharmaceutical production concentration drives precision tooling demand for high-volume validated lines.
Market Restraints
- Tungsten carbide input cost volatility:Raw material price swings compress margin structures for precision-machined components.
- Supplier concentration in Germany:Specialized coating and grinding capabilities cluster with limited qualified alternatives.
- ISO 9001 tolerance documentation:Extended audit protocols lengthen supplier onboarding timelines for new market entrants.
Strategic Opportunities
- United States generic producers:Domestic manufacturing footprint advantages enable rapid custom tool delivery against offshore lead times.
- Ceramic substrate tooling:Emerging material convergence with high-wear applications opens premium positioning for next-generation tablet geometries.
- Preventive maintenance service unbundling:Aftermarket tooling lifecycle management creates recurring revenue streams separate from capital equipment sales.
Industry Challenges
- Precision grinding skill scarcity:Narrow tolerance band expertise concentrates with aging specialist workforces in European manufacturing centers.
- FDA validation line integration:Legacy single-tip press platforms require complex retrofitting to accommodate multi-tip tooling specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Press Tooling Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,052.34 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Punches, Convex Punches, Concave Punches, Multi-tip Punches, Scored Punches Application: Pharmaceutical, Nutraceutical, Agrochemical, Veterinary, Chemical Processing End User: Contract Manufacturers, Brand Owners, Generic Producers, Nutraceutical Companies Material: Tool Steel, Stainless Steel, Tungsten Carbide, Ceramic, Titanium |
| Companies Covered | Natoli Engineering, Wilson Tool, I Holland, Elizabeth Companies, PACIFIC TOOLS, Pharmachine, NANNO Co., Ltd., Adamus SA, PTK-GB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Press Tooling Market Trends and Innovations
Tablet press tooling is experiencing material substitution, regulatory documentation intensification, and procurement model restructuring that collectively reshape competitive positioning.
Multi-tip tooling is decomposing legacy single-tip capacity across high-volume pharmaceutical facilities. Generic producers in India and the United States adopt simultaneous multi-cavity compression to maximize throughput economics without rotary press capital expansion. This technology is decomposing equipment replacement cycles by extracting doubled output from installed press platforms.
REACH substance restrictions and EU MDR framework convergence tighten dimensional tolerance documentation requirements for European pharmaceutical manufacturers. Suppliers must now maintain extended material traceability chains and preventive replacement audit trails. Tooling procurement in Germany and Switzerland faces elongated qualification timelines as a result.
After-sales service unbundling is separating tooling lifecycle management from capital equipment transactions. Contract manufacturers now procure preventive replacement schedules and grinding services through standalone agreements rather than bundled press purchases. This pattern concentrates in North American generic facilities seeking operational expenditure flexibility.
Tablet Press Tooling Market Segmentation
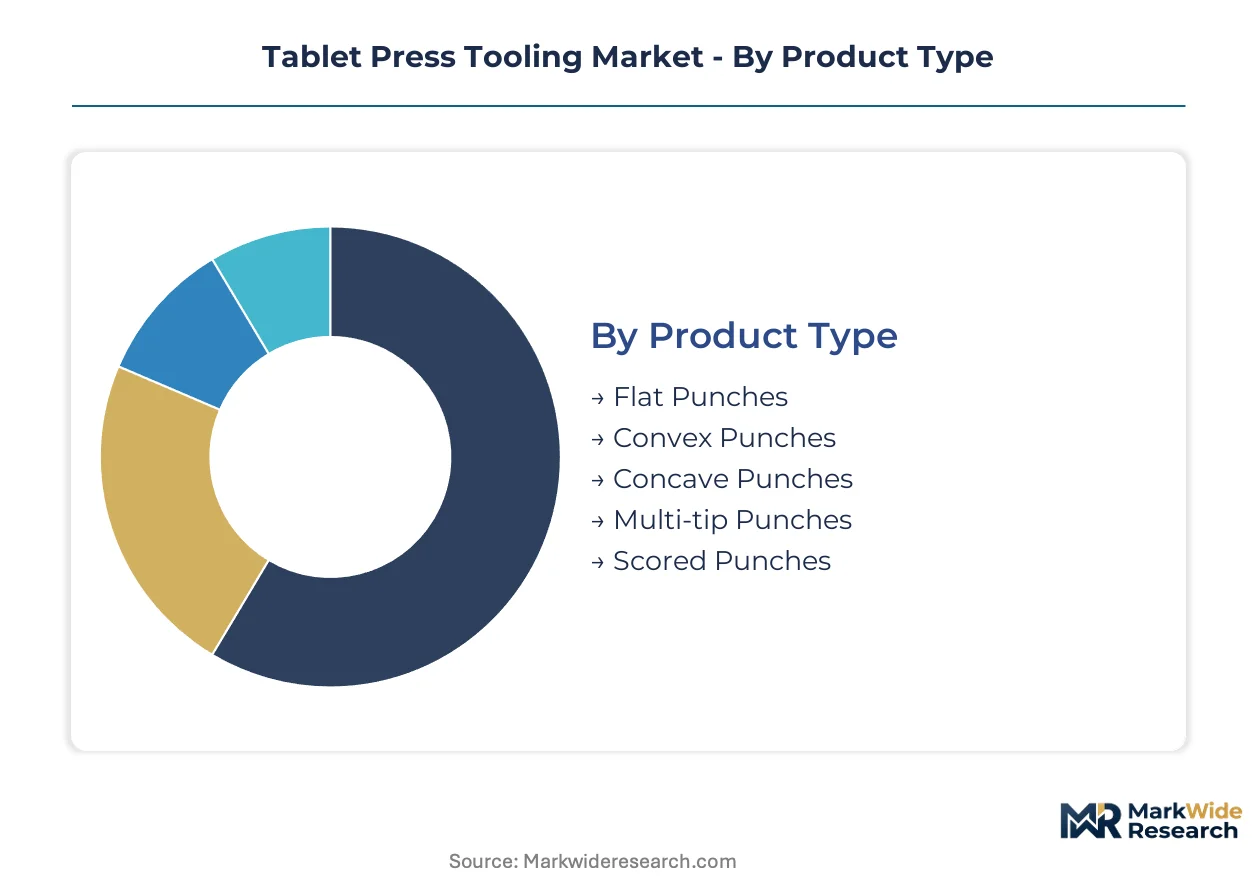
Tablet press tooling procurement patterns diverge sharply across material grades, product geometries, and end-user operational models. Understanding these segment boundaries clarifies where tungsten carbide substitution pressures concentrate versus where legacy steel grades retain defensive positions.
Product Type:
Substitution pressure from multi-tip configurations is most acute among standard single-tip geometries that dominate generic pharmaceutical throughput.
- Flat Punches:Simple planar compression faces machine from hardened tool steel for standard cylindrical tablets. Generic producers in India deploy flat punches across high-volume validated lines where FDA compliance documentation elevates replacement frequency.
- Convex Punches:Domed face profiles distribute compression force radially to prevent tablet capping in friable formulations. Demand concentrates among brand owners manufacturing coated tablets with precise crown specifications for controlled-release pharmacokinetics.
- Concave Punches:Recessed faces create convex tablet surfaces for improved swallowability in pediatric and geriatric dosages. Contract manufacturers specify these for specialty formulations requiring distinct visual identification.
- Multi-tip Punches:Simultaneous multi-cavity tooling doubles effective output from existing rotary press platforms without capital expansion. Generic producers adopt these to maximize throughput economics under EMA GMP Annex 15 validation constraints.
- Scored Punches:Raised rib configurations imprint break lines for dose splitting compliance. Veterinary applications favor scored configurations for weight-adjusted animal dosing across variable tablet sizes.
Flat punches retain volume leadership; multi-tip punches hold the steepest expansion curve.
Application:
Cost tier stratification separates validated pharmaceutical demand from price-sensitive agricultural chemical procurement.
- Pharmaceutical:FDA-validated tablet lines mandate precision-ground punches with documented material certificates and preventive replacement schedules. German contract manufacturing clusters drive premium tooling specifications for narrow tolerance band compliance.
- Nutraceutical:Dietary supplement compression tolerates wider dimensional variance, enabling standard-grade tool steel procurement. United States nutraceutical companies prioritize rapid tool changeover over extended wear resistance.
- Agrochemical:Abrasive active ingredients in pesticide formulations accelerate punch wear, creating demand for tungsten carbide and ceramic substrates. Indian agrochemical producers balance input costs against production run lengths.
- Veterinary:Large-dose tablets for livestock require reinforced punch heads to withstand elevated compression forces. Specialized geometries accommodate variable tablet weights across species-specific dosing requirements.
- Chemical Processing:Industrial catalyst tablets and detergent briquettes utilize standard tooling with minimal surface finish requirements. Procurement emphasizes unit cost minimization over precision grinding tolerances.
Pharmaceutical applications command the premium tier; agrochemical represents the most rapid material upgrade pathway.
End User:
Customer type determines whether tooling procurement flows through capital equipment bundles or standalone lifecycle management agreements.
- Contract Manufacturers:Multi-client facilities require rapid tool changeover capabilities and documented qualification trails for diverse product portfolios. Preventive maintenance service unbundling concentrates among North American contract manufacturers seeking operational expenditure flexibility.
- Brand Owners:Proprietary formulation manufacturers prioritize punch surface integrity for coated tablet aesthetics and brand differentiation. Extended production runs justify premium tungsten carbide investments for wear resistance.
- Generic Producers:High-volume throughput economics drive multi-tip adoption and compressed replacement cycles under FDA validation requirements. Indian generic clusters represent the most concentrated demand for precision-ground standard geometries.
- Nutraceutical Companies:Dietary supplement manufacturers balance rapid product line turnover against tooling inventory carrying costs. Shorter production campaigns favor standard-grade punches with expedited delivery timelines.
Generic producers generate the highest unit volume; contract manufacturers are converting fastest to unbundled service procurement.
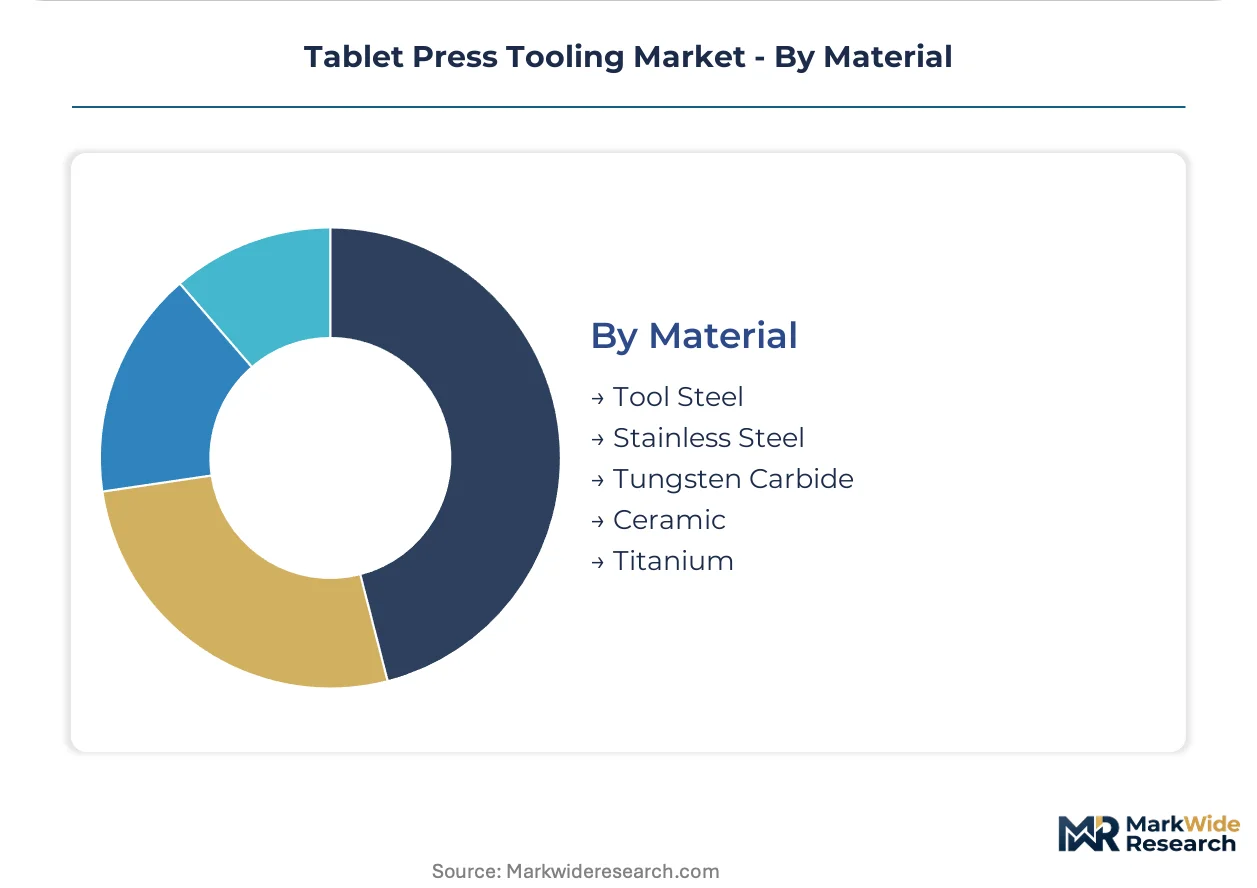
Material:
Supply concentration in specialized coating and grinding capabilities constrains material substitution timelines for European pharmaceutical manufacturers.
- Tool Steel:Conventional AISI D2 and M2 grades remain the baseline for standard tablet geometries with moderate abrasion characteristics. German tooling suppliers maintain legacy grinding capacity for validated pharmaceutical lines.
- Stainless Steel:Corrosion-resistant grades serve humid production environments and hygroscopic formulations requiring frequent washdown cycles. Nutraceutical applications favor stainless substrates for regulatory compliance flexibility.
- Tungsten Carbide:Cemented carbide compositions deliver superior wear resistance for high-abrasion active pharmaceutical ingredients and extended production runs. Raw material price volatility compresses margin structures for precision-machined components.
- Ceramic:Alumina and zirconia substrates offer extreme hardness for specialty applications where metallic contamination risks exclude conventional materials. Emerging positioning targets next-generation tablet geometries with complex embossing requirements.
- Titanium:Lightweight biocompatible grades serve niche pharmaceutical applications with stringent metallic ion leaching constraints. Limited domestic machining capability extends lead times for North American procurement.
Tool steel maintains installed base dominance; tungsten carbide is climbing the fastest as abrasive formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented tooling fabricators in Germany and Switzerland supply precision components to pharmaceutical manufacturers across North America and Asia, while India and China balance import dependence with growing domestic machining capacity for generic drug production.
United States
Generic pharmaceutical contract manufacturers in New Jersey and North Carolina drive demand for rapid custom tool delivery under FDA validation timelines. The FDA's data integrity guidance elevates supplier qualification barriers for European and Asian imports. Domestic fabricators near Philadelphia and Chicago leverage proximity advantages to serve high-volume tablet press operations with compressed lead times.
Germany
Specialized coating and precision grinding capabilities cluster around Stuttgart and Solingen, serving EMA-validated pharmaceutical lines across Europe. REACH substance restrictions and EU MDR framework convergence tighten material traceability requirements for tooling exports. Bavarian contract manufacturing hubs source premium tungsten carbide punches for abrasive active ingredient formulations.
India
Hyderabad and Ahmedabad generic drug clusters represent the fastest-expanding procurement volume for multi-tip tooling configurations. CDSCO manufacturing license requirements align with FDA inspection protocols for export-oriented facilities. Tooling replacement cycles compress as contract manufacturers scale output for regulated markets without rotary press capital expansion.
Switzerland
Swissmedic oversight of pharmaceutical manufacturing sustains demand for narrow-tolerance tooling from precision machining centers near Biel and Geneva. The country's specialized substrate coating expertise supports tungsten carbide applications in extended-release tablet production. Basel-area pharmaceutical headquarters procure premium tooling through long-term preventive maintenance agreements.
China
Domestic tablet press manufacturers in Shanghai and Guangdong provinces are developing captive tooling production to reduce import dependence for standard geometries. NMPA GMP certification upgrades for pharmaceutical exporters elevate quality documentation requirements. Yangtze River Delta chemical processing hubs create secondary demand for abrasion-resistant punch materials in catalyst tablet production.
Tablet Press Tooling Market Competitive Landscape
Listed leaders compete with private specialists across material technology and service bundling dimensions. The vendor base organizes into three tiers: integrated press manufacturers with captive tooling divisions, standalone precision fabricators with coating specializations, and regional machinists serving price-sensitive generic producers. Strategic differentiation centers on preventive maintenance service unbundling and rapid custom geometry delivery. Consolidation pressure concentrates among European coating specialists facing tungsten carbide input cost volatility.
Among domestic-focused fabricators, Natoli Engineering occupies a position exemplifying rapid custom tool delivery archetypes for North American generic producers. Wilson Tool and I Holland represent precision grinding specialists serving EMA-validated European pharmaceutical lines with extended coating capabilities. These three anchors illustrate how geographic proximity to contract manufacturing clusters shapes competitive positioning more than vertical integration depth.
| Leading Market Players |
|---|
| Natoli Engineering |
| Wilson Tool |
| I Holland |
| Elizabeth Companies |
| PACIFIC TOOLS |
| Pharmachine |
| NANNO Co., Ltd. |
| Adamus SA |
| PTK-GB Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term preventive maintenance agreements lock in tooling replacement schedules and price visibility for North American contract manufacturers facing FDA validation timelines. These contracts tether procurement volumes to specific service tiers while insulating buyers from tungsten carbide spot price volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in tablet press tooling procurement. Price differentiation rests on ISO 9001 certification grade and customization level for narrow tolerance band compliance. Cost compression in standard-grade tool steel is intensifying because Indian generic producers scale multi-tip adoption without rotary press capital expansion. Contract manufacturers exhibit the highest price sensitivity due to operational expenditure flexibility requirements, while brand owners manufacturing coated tablets show the least sensitivity as extended production runs justify premium tungsten carbide investments.
Supply Chain Analysis
Inventory carrying costs for precision-ground punch geometries extend lead times for European pharmaceutical manufacturers sourcing from German and Swiss coating specialists. Geographic supply concentrates in Germany, Switzerland, and India, with Stuttgart and Solingen anchoring specialized grinding capabilities. Raw material dependencies draw from tungsten carbide powder, cemented carbide substrates, and hardened tool steel billets. Single-source vulnerability clusters around REACH-compliant coating chemistries restricted to qualified European suppliers. Distribution runs through direct mill relationships for validated pharmaceutical lines and regional distributors for price-sensitive generic producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as tungsten carbide tooling displaces legacy steel-grade capacity across abrasive formulation applications. Incumbents must navigate ceramic substrate emergence threatening next-generation premium positioning.
For Market Incumbents: Compound defensive moats by securing backward integration into tungsten carbide powder supply and expanding captive coating capacity in Germany. Ceramic substrate R&D investment counters emerging material substitution threats. Preventive maintenance service unbundling captures recurring revenue streams separate from capital equipment sales.
For New Entrants and Emerging Players: Aftermarket grinding service gaps in North American contract manufacturing clusters present white-space entry points. Preventive replacement scheduling for FDA-validated lines remains under-penetrated relative to European benchmarks. Rapid custom geometry delivery for generic producers in India offers the most penetrable geographic wedge, with domestic machining partnerships as the preferred go-to-market angle.
For Investors and Strategic Acquirers: Precision coating specialists with EMA-validated qualification trails represent the highest-value acquisition archetype for long-term viability across the analysis window. Swiss and German mid-cap fabricators with narrow-tolerance expertise face consolidation pressure from tungsten carbide input cost volatility. Watch ceramic substrate pilot adoption rates in Basel-area pharmaceutical headquarters as the inflection indicator for next-generation material displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Service Unbundling | Creates recurring revenue streams separate from capital equipment transactions for North American contract manufacturers. |
| Tungsten Carbide Backward Integration | Secures powder supply access against raw material price volatility compressing margin structures. |
| Ceramic Substrate R&D Investment | Positions for next-generation tablet geometries with complex embossing requirements in extended-release production. |
| Domestic Machining Partnership in India | Captures rapid custom tool delivery demand from Hyderabad and Ahmedabad generic drug clusters. |
| EMA Qualification Trail Expansion | Extends supplier audit protocol compliance for European pharmaceutical manufacturers under EU MDR convergence. |
Research Methodology
Initial hypotheses were tested against primary input from tablet press operations managers, tooling procurement leads at contract manufacturers, precision grinding specialists, and regulatory affairs directors, then refined through secondary validation. FDA warning letters, EMA GMP inspection reports, ISO 9001 certification databases, and customs trade records provided triangulation anchors. Bottom-up demand modeling across rotary press installed bases converged with top-down pharmaceutical production volume estimates.
Variance decomposition across material grade, product geometry, end-user operational model, and regional regulatory cluster shaped analytical framework development over the projection horizon. CAGRs were derived from segment-level replacement cycle analysis and validated against pharmaceutical capital expenditure patterns. Tungsten carbide adoption curves and multi-tip tooling penetration rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA and EMA regimes; material policy shifts around data integrity expectations or REACH substance restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Industrial Wax Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Steel Cord Market
Industrial Materials
Injection Molding Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Global High Pressure Seals Market