
 Industrial Absorbents Market | 2026-2036
Industrial Absorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Absorbents Market Intelligence
A shift from single-source procurement to multi-source vendor management for specialized absorbents is consolidating, allowing end-users to optimize cost. New Pig Corporation leverages its direct-to-customer model and strong brand recognition in industrial maintenance. Oil-Dri Corporation of America specializes in clay-based mineral absorbents, controlling its raw material supply. 3M Company competes through its broad portfolio of synthetic sorbent materials and extensive global distribution.
Industrial absorbents are materials engineered to capture and contain liquid spills in commercial and manufacturing environments. They often feature a porous physical structure, such as melt-blown polypropylene fibers or natural cellulose, to maximize surface area and absorption capacity. Synthetic absorbents, particularly polymeric types, command the largest market share due to their high efficacy with chemicals and oils. Demand from petrochemical plants for oil spill control applications continues to represent the primary consumption driver across the market.
Regulatory frameworks from bodies like the US EPA and the European Chemicals Agency (ECHA) under REACH directly influence product specifications and usage mandates. In China, Ministry of Ecology and Environment (MEE) directives on industrial pollution control compel facilities to maintain adequate spill response inventories. Future competitive advantage will depend on developing bio-based or recycled-content absorbents that meet stringent performance standards without compromising cost.
Market Dynamics
The industrial absorbents market is defined by the structural tension between tightening environmental regulations mandating immediate spill containment and persistent end-user pressure for cost-optimized operational supplies. This dynamic shapes material selection, procurement strategies, and regional demand patterns.
Growth Catalysts
- Regulatory Enforcement:Stringent regulations, including the US EPA's SPCC rule and the EU's Industrial Emissions Directive, create non-discretionary demand by mandating facilities maintain spill response capabilities, directly driving absorbent sales in North America and Europe.
- Petrochemical Sector Expansion:Continued investment in petrochemical and oil refining infrastructure, particularly along the US Gulf Coast and in China's coastal industrial zones, expands the primary end-use market for high-capacity oil absorbents.
- Material Efficacy Demands:A preference for synthetic absorbents, such as melt-blown polypropylene, is growing due to their superior oleophilic (oil-attracting) and hydrophobic (water-repelling) properties, which are critical for effective cleanup in marine and wet environments.
Market Restraints
- Raw Material Volatility:The price of synthetic absorbents is directly linked to polypropylene and other polymer resin costs, which are subject to fluctuations in global crude oil prices, creating margin pressure for manufacturers.
- Substitution from Low-Cost Alternatives:In less-regulated applications or cost-sensitive segments, traditional materials like clay granules, sawdust, or rags present a persistent substitution threat, limiting penetration of higher-performance, higher-cost synthetic products.
- Logistical Inefficiencies:The high-volume, low-weight character of many absorbent products like booms and pads results in significant transportation costs relative to their value, constraining the economic viability of long-distance distribution and favoring regional production.
Strategic Opportunities
- Bio-Based Materials:Developing absorbents from sustainable sources like cellulose, coir, or recycled paper fibers offers a path to meet corporate sustainability goals and appeal to environmentally conscious buyers, provided performance standards are met.
- Emerging Geographic Markets:Industrializing nations in Southeast Asia and Latin America, where safety and environmental regulations are strengthening, represent significant growth opportunities for absorbent suppliers as compliance becomes a priority.
- New Energy Applications:The rapid growth of battery manufacturing and energy storage facilities creates a new application for specialized absorbents designed to contain and neutralize spills of hazardous electrolytes and cooling fluids.
Industry Challenges
- Fragmented Regulatory Landscape:Manufacturers and distributors face complexity in ensuring products comply with a patchwork of national and regional standards, such as US EPA regulations versus the EU's REACH framework, which increases compliance costs.
- Used Product Disposal:The disposal of saturated absorbents, which often qualify as hazardous waste, presents a significant logistical and financial burden for end-users, influencing their purchasing decisions toward products that minimize waste volume.
- Performance Standardization Gaps:A lack of universally accepted test methods for absorption capacity and retention makes it difficult for customers to make direct, like-for-like comparisons between competing products, leading to purchasing decisions based on price over performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Absorbents Market |
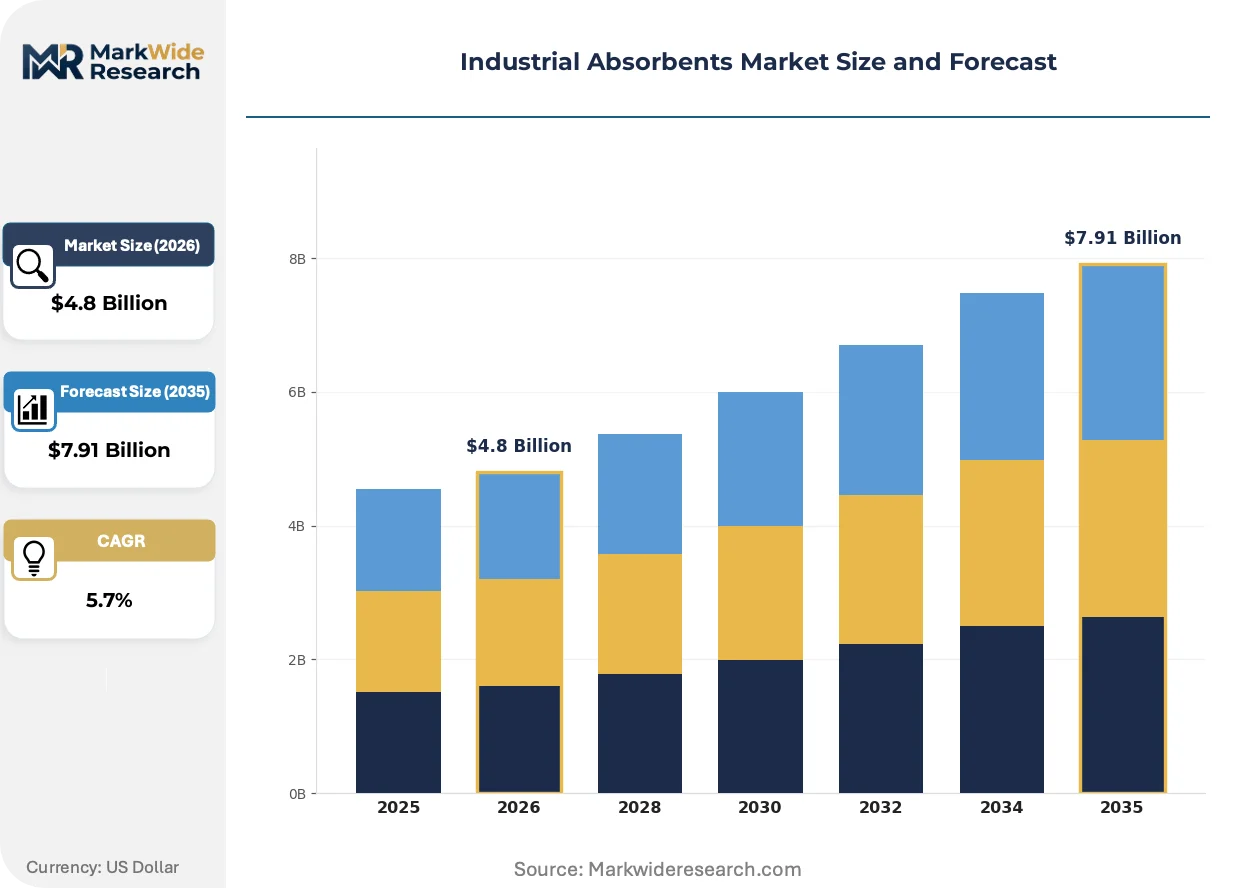
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Absorbents, Natural Absorbents, Cellulose-Based Absorbents, Polymeric Absorbents Technology: Activated Carbon, Superabsorbent Polymers, Silica Gel, Clay Minerals, Zeolites Application: Oil Spill Control, Chemical Processing, Wastewater Treatment, Air Purification, Packaging Protection End User Industry: Manufacturing Units, Mining Companies, Petrochemical Plants, Environmental Agencies |
| Companies Covered | 3M Company, New Pig Corporation, Oil-Dri Corporation of America, Brady Worldwide, Inc., Kimberly-Clark Worldwide, Inc., Meltblown Technologies Inc., Johnson Matthey Plc, Monarch Green, Inc., TOLSA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Absorbents Market Strategic Shifts & Innovations
The market's evolution is driven by a dual focus on enhancing material performance and addressing the full product lifecycle. Innovations are centered on creating smarter, more sustainable, and service-oriented solutions that go beyond simple spill containment to offer greater operational value.
Smart absorbents featuring embedded indicators are a key product evolution. These advanced materials are engineered to change color upon contact with specific liquids, providing immediate visual feedback on the nature of a spill, such as distinguishing an acid from a base. High-risk facilities like laboratories and chemical processing plants are adopting these products for rapid hazard identification, and the technology is integrating safety diagnostics directly into the containment material itself.
The European Union's circular economy initiatives, a core component of the EU Green Deal, are directly influencing material sourcing. This policy framework compels manufacturers to increase the use of recycled content in their products to gain market access and meet sustainability targets. The synthetic absorbents segment is responding by investing in processes to utilize post-industrial and post-consumer polypropylene and polyester waste streams as feedstock for new pads, socks, and booms.
End-users are progressively moving toward comprehensive spill management solutions instead of making simple transactional product purchases. This behavioral shift disrupts the traditional distributor-led model, creating an opening for suppliers who can bundle site assessments, employee training, and certified waste disposal services with their absorbent products. This service-oriented approach is most visible in the highly regulated aerospace and pharmaceutical manufacturing sectors in North America and Western Europe.
Industrial Absorbents Market Segmentation
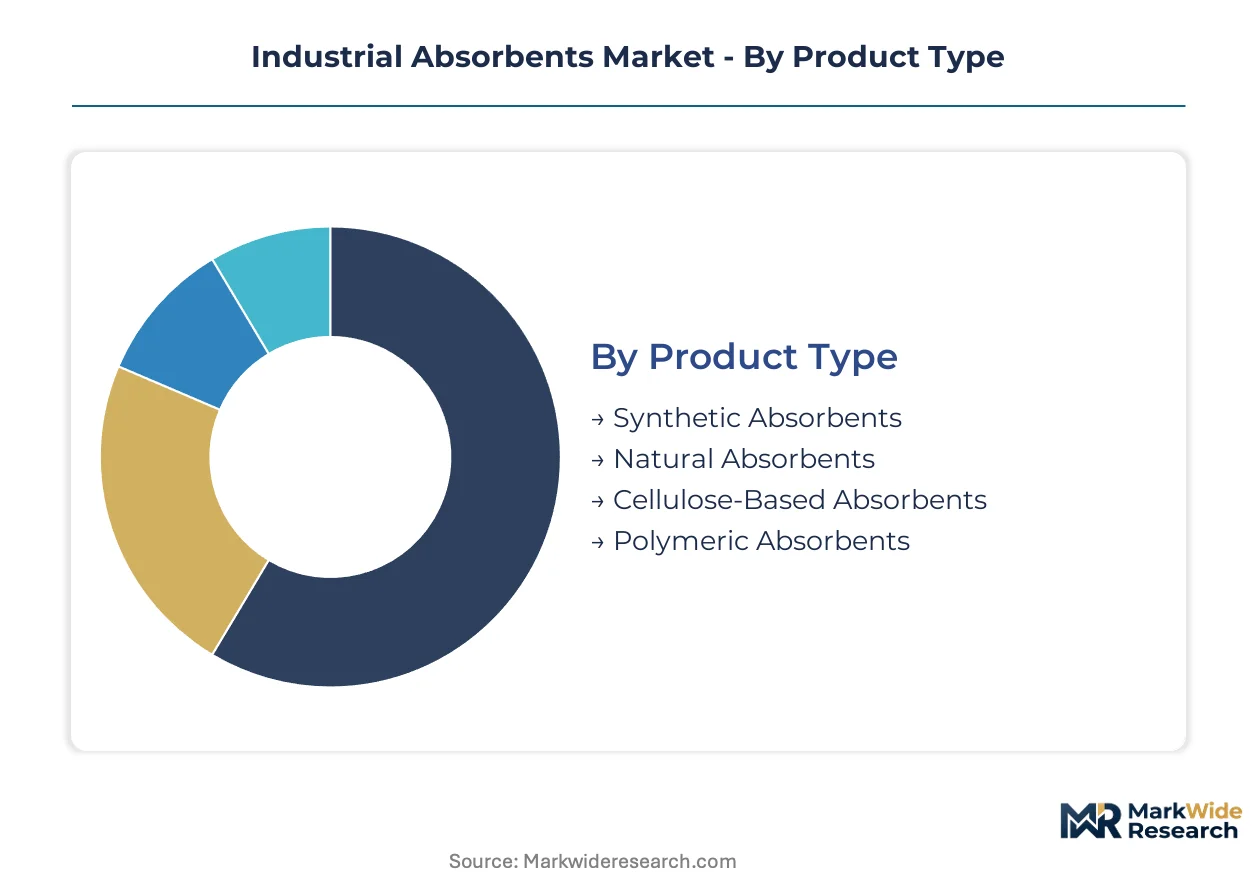
The industrial absorbents market is segmented to reflect the diverse material requirements, technological advancements, and end-use applications driving demand. This segmentation helps in understanding specific product performance needs and regulatory compliance nuances across different industries.
Product Type:
The customization-vs-standardization spectrum significantly influences product type selection in the industrial absorbents market.
- Synthetic Absorbents:These materials, often melt-blown polypropylene fibers, offer superior oleophilic and hydrophobic properties, making them highly effective for oil and chemical spills. Demand concentrates in petrochemical plants and marine environments due to their high efficacy in challenging conditions.
- Polymeric Absorbents:Engineered polymers provide high absorption capacity for specific chemicals and hazardous liquids, often used in specialized industrial processes. These advanced materials find significant demand in chemical processing plants and laboratories requiring precise containment.
- Natural Absorbents:Comprising materials like peat, wood fiber, or corn cob, these products offer an environmentally friendly option for general-purpose liquid absorption.
- Cellulose-Based Absorbents:Derived from recycled paper or wood pulp, these renewable absorbents are employed for water-based spills and non-corrosive liquid containment in various manufacturing settings.
Most installed capacity flows through Synthetic Absorbents. Expansion is steepest in Polymeric Absorbents.
Technology:
The cost tier of absorbent technologies dictates their suitability for various applications, balancing performance with economic viability.
- Superabsorbent Polymers:These highly efficient cross-linked polymers can absorb hundreds of times their weight in liquid, primarily used for aqueous solutions and specialized chemical containment. Demand is strong in healthcare and specific industrial manufacturing for electrolyte spills.
- Clay Minerals:Including attapulgite and bentonite, these natural granular materials offer cost-effective, broad-spectrum absorption for oils, greases, and water-based liquids. These traditional absorbents serve general industrial maintenance and automotive sectors, leveraging their widespread availability.
- Activated Carbon:This porous material is effective for adsorbing vapors and certain dissolved organic compounds, finding use in air and water purification systems.
- Silica Gel:A desiccant used for moisture control, silica gel prevents corrosion and degradation of sensitive products during storage and transport.
- Zeolites:These porous aluminosilicate minerals selectively adsorb specific ions and molecules, employed in specialized filtration and chemical separation processes.
Demand for Clay Minerals remains strong for general spill management. Superabsorbent Polymers are gaining traction for specialized, high-volume liquid containment.
Application:
Application diversity drives specific material and technological requirements across the industrial absorbents landscape.
- Oil Spill Control:This application involves containing and cleaning up petroleum-based spills on land and water surfaces, utilizing oleophilic materials like polypropylene pads and booms. Petrochemical plants and marine operations represent the primary consumption driver for these high-capacity absorbents.
- Chemical Processing:Facilities handling hazardous chemicals require specialized absorbents capable of neutralizing or containing aggressive liquids, preventing environmental contamination and worker exposure. High-risk laboratories and pharmaceutical manufacturing sectors demand these precise solutions.
- Wastewater Treatment:Absorbents are used to remove contaminants, oils, and suspended solids from industrial wastewater streams before discharge.
- Air Purification:Certain absorbent technologies capture airborne pollutants and volatile organic compounds, improving indoor air quality in manufacturing environments.
- Packaging Protection:Absorbents prevent damage to goods during transit by controlling moisture or containing accidental leaks within packaging.
The largest volume of absorbents is consumed in Oil Spill Control. New opportunities are emerging in Wastewater Treatment for contaminant removal.
End User Industry:
Customer type influences procurement strategies and the required scale of absorbent solutions within the industrial market.
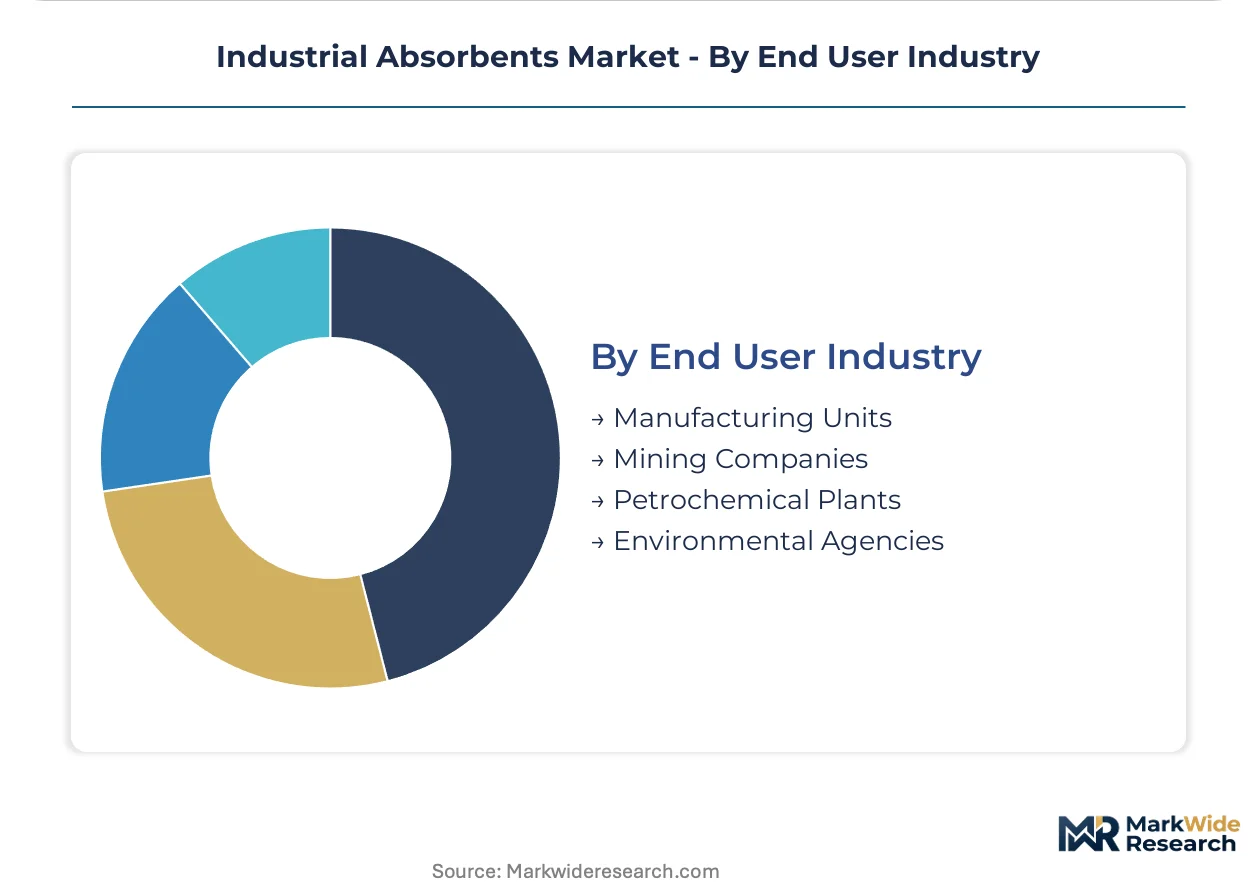
- Petrochemical Plants:These facilities require extensive inventories of high-capacity oil and chemical absorbents for rapid spill containment due to large volumes of hazardous materials. Regulatory frameworks like the US EPA's SPCC rule compel their usage.
- Manufacturing Units:A broad category encompassing various industries, manufacturing units use absorbents for general maintenance, minor spills, and workshop safety. Cost-optimized operational supplies are a persistent end-user pressure in this segment.
- Mining Companies:Absorbents manage spills of oils, fuels, and process chemicals in mining operations, particularly in remote and environmentally sensitive areas.
- Environmental Agencies:These bodies utilize absorbents for large-scale environmental remediation projects and mandated spill response efforts following industrial accidents.
Petrochemical Plants represent the dominant end-user. Demand from Environmental Agencies is expanding most quickly due to increased regulatory oversight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial absorbents market experiences shifting production dynamics, with certain manufacturing migrating to regions offering a relative advantage in regulatory compliance costs or raw material access. This regulatory-arbitrage angle influences where absorbent products are manufactured and distributed globally. Demand patterns are shaped by localized industrial activity and environmental protection mandates.
United States
Demand for industrial absorbents in the United States is driven by extensive petrochemical operations and manufacturing sectors. The US EPA's Spill Prevention, Control, and Countermeasure (SPCC) rule mandates spill response capabilities. The Gulf Coast region, with its dense concentration of refineries, represents a primary consumption hub for oil and chemical absorbents.
China
China's industrial absorbents market is propelled by rapid industrialization and stringent environmental protection policies. Ministry of Ecology and Environment (MEE) directives compel facilities to maintain adequate spill response inventories. Coastal industrial zones, particularly in the Yangtze River Delta, are significant consumers due to concentrated manufacturing.
Germany
Europe's largest economy, Germany, sees substantial demand for industrial absorbents from its advanced manufacturing and chemical industries. The EU's Industrial Emissions Directive and REACH regulations enforce strict spill containment standards. Industrial clusters in Bavaria and North Rhine-Westphalia drive consumption for specialized polymeric and synthetic absorbents.
India
India's expanding manufacturing base and increasing focus on environmental compliance are boosting demand for industrial absorbents. Growing regulatory oversight from bodies like the Central Pollution Control Board mandates better spill management practices. Industrial corridors in Gujarat and Maharashtra are emerging as key consumption centers.
Brazil
Petrochemical and mining operations in Brazil create a steady need for industrial absorbents, particularly for oil spill control. National environmental agencies, such as IBAMA, are increasing enforcement of spill prevention protocols. The Southeast region, with its significant industrial and oil & gas infrastructure, anchors the country's absorbent consumption.
Industrial Absorbents Market Key Industry Players
Established producers occupy the standard tier, offering broad portfolios of synthetic and natural absorbents; emerging entrants pursue niche applications like bio-based materials or smart absorbents. The market exhibits a tiered structure, with large diversified players competing alongside specialized manufacturers. Strategic archetypes include integrated raw material suppliers, direct-to-customer specialists, and broad-portfolio industrial suppliers. Dominant competitive moves involve portfolio diversification into higher-value specialized absorbents and strategic partnerships to expand geographic reach.
On the premium-tier vector, 3M Company exemplifies a broad-portfolio industrial supplier, leveraging its extensive global distribution network for synthetic sorbent materials. New Pig Corporation represents a direct-to-customer specialist, utilizing its strong brand recognition in industrial maintenance to reach end-users efficiently. Oil-Dri Corporation of America anchors the segment for clay-based mineral absorbents, demonstrating upstream control over its raw material supply. These established players, alongside other specialized manufacturers, continually adapt their offerings to meet evolving regulatory and performance demands across diverse industrial applications.
| Leading Market Players |
|---|
| 3M Company |
| New Pig Corporation |
| Oil-Dri Corporation of America |
| Brady Worldwide, Inc. |
| Kimberly-Clark Worldwide, Inc. |
| Meltblown Technologies Inc. |
| Johnson Matthey Plc |
| Monarch Green, Inc. |
| TOLSA Group |
| Others |
Cost & Logistics Intelligence
Polypropylene resin costs directly impact synthetic absorbent pricing, influencing the tiered structure from manufacturing through end-user procurement. Logistics expenses also significantly shape regional pricing due to the bulk nature of many absorbent products.
Pricing Analysis
Raw material cost volatility directly influences the pricing of synthetic absorbents, which manufacturers often pass through to maintain margins. Pricing stratifies across premium, standard, and economy tiers, differentiated by absorption capacity and chemical compatibility. Certification levels, such as those required by the US EPA, also command a premium. Cost compression runs through general manufacturing units, which are highly price-sensitive, while petrochemical plants prioritize performance over cost.
Supply Chain Analysis
Ministry of Ecology and Environment (MEE) directives in China encourage localized sourcing for spill response inventories, reshaping regional supply. Supply concentrates in industrial zones across China, the US Gulf Coast, and Germany. The market relies on polypropylene resins and various clay minerals as primary inputs. Logistics chokepoints present a structural risk for high-volume, low-weight products. Distribution runs through both direct-to-customer models and broad industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial absorbents market operates as a stable compounder, driven by persistent regulatory enforcement from bodies like the US EPA and the EU's ECHA. Facilities must maintain spill response capabilities, ensuring consistent demand.
For Market Incumbents:Acquire specialized bio-based materials companies to counter sustainability mandates and strengthen product portfolios. Diversify offerings to include advanced polymeric absorbents for niche chemical applications, mitigating margin pressure from commodity clay granules. Investment in R&D for recycled-content feedstocks can address circular economy initiatives. Strengthening distribution networks in emerging markets like Southeast Asia expands reach against regional competitors.
For New Entrants and Emerging Players:Capture market share in new energy applications, particularly for specialized absorbents designed for battery manufacturing and cooling fluids. Target industrializing nations in Southeast Asia where environmental regulations are strengthening, creating compliance-driven demand. A service-oriented go-to-market angle, bundling site assessments and certified waste disposal, can differentiate offerings. Focus on performance standardization to build trust in fragmented regulatory landscapes.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory compliance costs are high and specialized material R&D is capital intensive. The market offers consistent demand over the next decade due to non-discretionary regulatory compliance. Target vertically integrated mid-cap specialists possessing proprietary bio-based or smart absorbent technologies. Increased M&A activity for companies with strong IP in sustainable absorbents or advanced monitoring capabilities is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports growing demand from the petrochemical sector along the US Gulf Coast. |
| Green Manufacturing Transition | Meets EU circular economy targets and appeals to environmentally conscious buyers. |
| Long-term Supply Agreement | Secures raw material stability for synthetic absorbents amidst price volatility. |
| Acquisition of Specialist Firm | Gains proprietary bio-based or smart absorbent technology for future growth. |
| Distribution Channel Expansion | Penetrates emerging geographic markets in Southeast Asia and Latin America. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and internal market intelligence databases — were reconciled to construct the market analysis. Field interviews engaged plant managers, procurement leads, environmental compliance officers, and R&D directors across key industries. Secondary research leveraged US EPA reports, ECHA guidelines, MEE directives, and industry trade association publications. A bottom-up and top-down triangulation approach ensured data accuracy and consistency.
An integrated analytical framework reconciled historical data, current market dynamics, and future projections across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from observed historical growth patterns and projected demand drivers. Key forecast inputs included petrochemical sector investment plans and anticipated environmental regulation updates.
Raw material price volatility, shifts in environmental enforcement, and the emergence of disruptive spill containment technologies are the dominant revision risks. Forecasts reflect assumptions regarding these external factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Plastic Gears Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Global Melamine Market