
 Global Medical Plastics Extrusion Market | 2026-2036
Global Medical Plastics Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Plastics Extrusion Market Foresight
Drug delivery systems is pivoting toward microbore and multi-lumen extruded tubing as wearable infusion platforms expand. Vention Medical sustains leadership through advanced catheter manufacturing capabilities across North American and European facilities. Putnam Plastics specializes in complex geometric extrusions for neurovascular and cardiovascular applications. Raumedic anchors European supply through its German manufacturing base with strong regulatory compliance infrastructure.
Medical plastics extrusion is a continuous thermoplastic shaping process where polymer resins are melted, homogenized, and forced through precision dies to create tubing, profiles, and film with tight dimensional tolerances, often achieving wall thicknesses below 0.001 inch for vascular access devices. The process serves critical functions in fluid management, structural support, and barrier protection across sterile healthcare environments. Polyethylene dominates catheter and fluid delivery applications due to its lubricity and chemical resistance, while polycarbonate commands premium positioning in surgical instruments requiring optical clarity and sterilization durability. Co-extrusion technology is expanding fastest as manufacturers layer dissimilar polymers to combine properties like radiopacity, drug elution, and electrical conductivity in single profiles.
FDA enforces stringent biocompatibility and sterilization validation requirements through ISO 10993-aligned 510(k) pathways, while EU MDR mandates enhanced clinical evidence and unique device identification for extruded components incorporated into finished devices. REACH and RoHS restrictions on phthalates and heavy metal additives are forcing reformulation of legacy PVC compounds across European supply chains. Stakeholders must monitor evolving polymer recycling mandates and carbon footprint disclosure rules that threaten to reshape material selection and supplier qualification timelines.
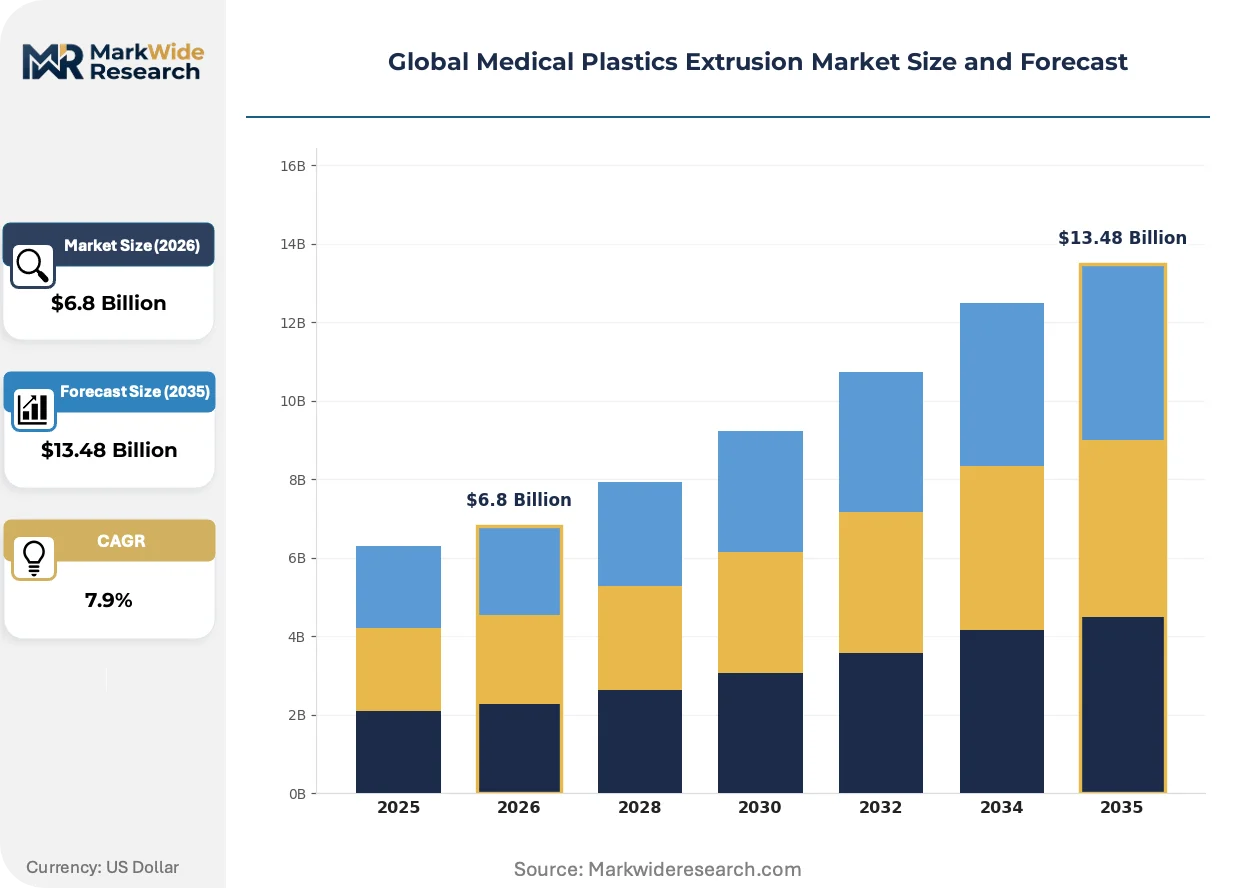
Market Dynamics
Co-extrusion technology is compressing supplier tiers as catheter manufacturers demand single-source profiles combining radiopacity, drug elution, and electrical conductivity in one tubing structure.
Growth Catalysts
- EU MDR compliance mandates:Enhanced clinical evidence and unique device identification requirements are forcing catheter OEMs to consolidate qualified extrusion suppliers with established quality management systems.
- Microbore tubing specifications:Wearable infusion platforms are accelerating procurement of sub-millimeter precision extrusions for continuous drug delivery applications.
- German medical device clusters:Concentrated demand around Stuttgart and Freiburg is driving specialized polymer processing capacity expansion across precision tubing manufacturers.
Market Restraints
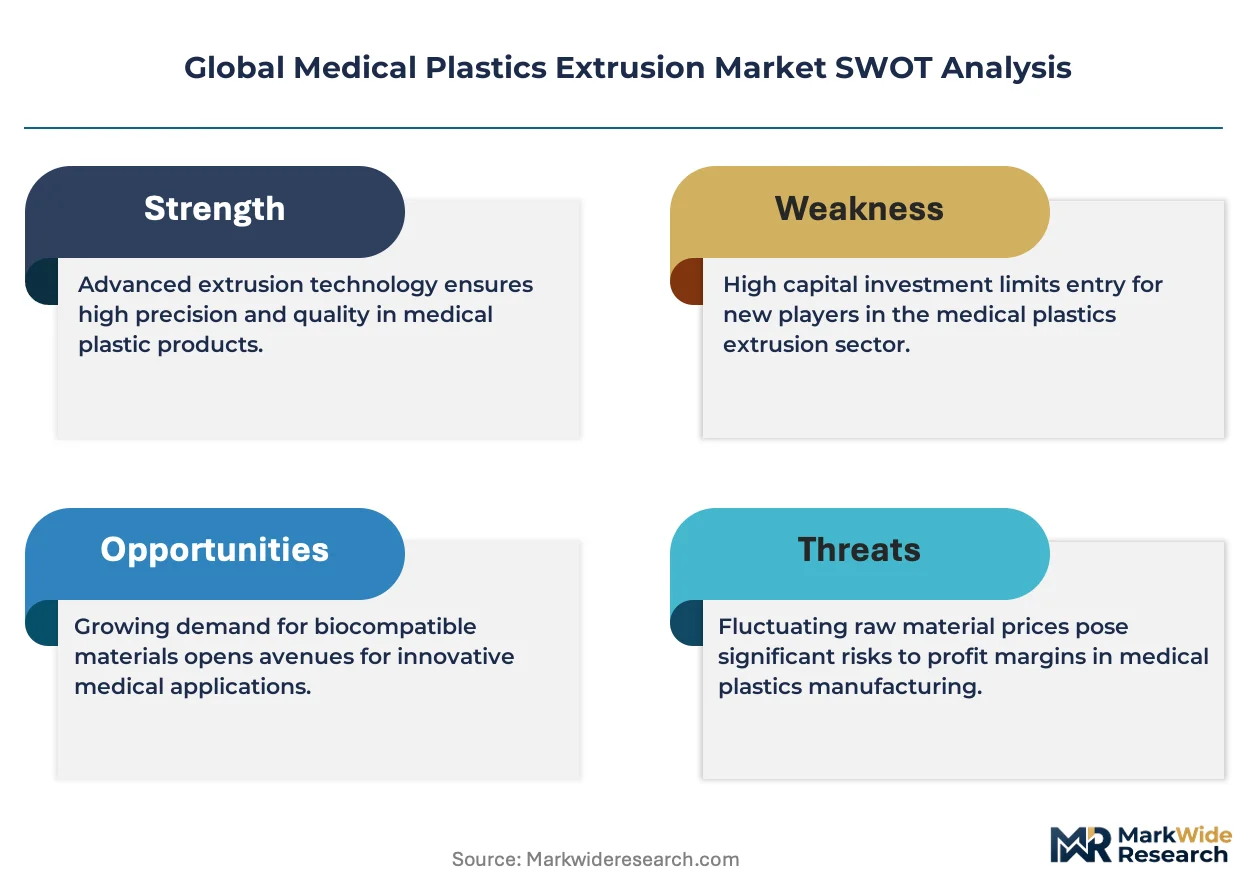
- Specialized resin supply concentration:Medical-grade polycarbonate and radiopaque compounds face tight allocation from limited polymer compounders, creating input cost volatility.
- REACH phthalate restrictions:Legacy PVC reformulation timelines are extending qualification cycles for European device manufacturers dependent on established supply chains.
- Thin-wall extrusion technical limits:Vascular access devices below 0.001 inch wall thickness exhibit yield variability that constrains high-volume automation.
Strategic Opportunities
- India's CDSCO pathway acceleration:Streamlined medical device registration is opening procurement channels for Western extrusion suppliers serving domestic catheter manufacturers.
- Bioresorbable polymer convergence:Combining polylactic acid extrusion with drug-loading capabilities creates white space in temporary implantable scaffolds.
- Carbon footprint disclosure rules:Early compliance with emerging polymer recycling mandates positions suppliers for preferred vendor status with sustainability-focused OEMs.
Industry Challenges
- ISO 13485 auditor scarcity:Extended certification timelines for new extrusion facilities are delaying market entry for capacity expansions.
- Multi-lumen tooling capex intensity:Precision mandrel and die systems for complex geometries require seven-figure capital commitments with long depreciation cycles.
- Legacy MRP integration friction:Real-time dimensional SPC data from extrusion lines struggles to interface with established device manufacturer ERP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Plastics Extrusion Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene, Polycarbonate Application: Surgical Instruments, Diagnostic Equipment, Drug Delivery Systems, Implantable Devices, Medical Packaging End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Pharmaceutical Manufacturers, Research Institutions Technology: Blown Film Extrusion, Cast Film Extrusion, Single Screw Extrusion, Twin Screw Extrusion, Co-Extrusion |
| Companies Covered | Vesta, Vention Medical, Putnam Plastics, Pexco, Raumedic, Spectrum Plastics Group, Nolato, Trelleborg AB, Bemis Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Plastics Extrusion Market Shifts & Advancements
Polymer layering architectures are displacing monolithic tubing as device engineers pursue property combinations impossible through single-material formulations.
Multi-layer co-extrusion is consolidating catheter supply chains by enabling radiopaque stripes, lubricious liners, and antimicrobial surfaces within one continuous profile. Neurovascular device manufacturers are specifying these architectures for delivery systems requiring torque response and trackability. The technology is compressing vendor lists as OEMs reduce qualification burden through single-source multi-property tubing.
REACH and RoHS additive restrictions are forcing compounders to eliminate phthalate plasticizers and heavy metal-based radiopacifiers from legacy PVC formulations. European device manufacturers face reformulation timelines extending 18-36 months for established product lines. Cardiology catheter producers are responding fastest, accelerating transitions to polyethylene and thermoplastic elastomer alternatives ahead of regulatory deadlines.
Device OEMs are unbundling extrusion procurement from finished device contracts, establishing direct supplier relationships with tier-2 tubing specialists. This disintermediation bypasses traditional contract manufacturer markups while imposing stricter quality agreements on extruders. The pattern is most visible in cardiovascular applications, where Boston Scientific and Abbott Vascular units are qualifying German and Irish precision extruders for direct supply.
Global Medical Plastics Extrusion Market Segmentation
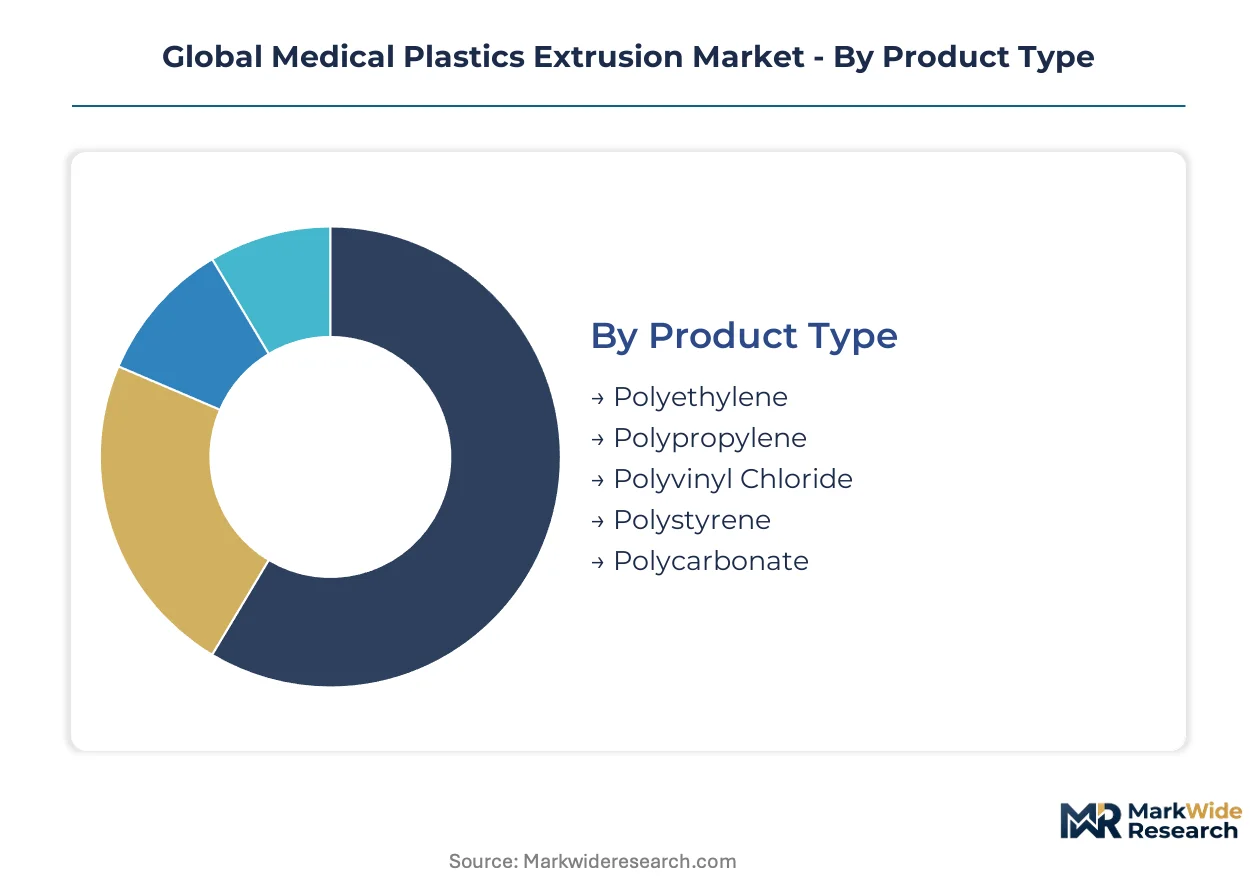
Medical plastics extrusion segmentation reveals how polymer chemistry, device application, and manufacturing technology intersect to determine supplier qualification paths. OEM procurement teams segment suppliers by extrusion capability depth rather than commodity resin availability alone.
Product Type:
Material replacement cycles dominate procurement planning as REACH phthalate restrictions force compound reformulation across European device supply chains.
- Polyethylene:Linear low-density formulations deliver lubricious surfaces for catheter fluid channels and drug delivery lumens. German cardiovascular device manufacturers specify medical-grade polyethylene for torque-responsive delivery systems requiring chemical resistance against lipids and saline.
- Polycarbonate:Amorphous thermoplastic achieves optical clarity exceeding 90% light transmission for surgical instrument housings and endoscopic components. Freiburg-area device clusters source polycarbonate extrusions for sterilization cycles exceeding 100 steam autoclave exposures.
- Polypropylene:Semicrystalline polymer offers fatigue resistance for syringe barrels and fluid management connectors.
- Polyvinyl Chloride:Legacy plasticized formulations face accelerated phase-out timelines under ECHA additive restrictions.
- Polystyrene:Crystal and impact grades serve diagnostic cuvettes and tissue culture vessels with tight dimensional tolerances.
Polyethylene sits at the top of the volume ranking, with polycarbonate climbing the fastest as optical-grade surgical instruments displace glass and metal alternatives.
Application:
End-use device economics determine extrusion specification stringency, with implantable applications imposing the most demanding biocompatibility validation burdens.
- Drug Delivery Systems:Multi-lumen microbore tubing enables wearable infusion platforms with sub-millimeter channel geometries for insulin and biologic administration. Stuttgart-area manufacturers specify co-extruded profiles combining drug-compatible liners with structural outer layers for ambulatory pump cartridges.
- Implantable Devices:Permanent and bioresorbable extrusions require ISO 10993-6 implantation testing and particulate contamination controls exceeding Class 7 cleanroom standards. Irish vascular scaffold producers source polylactic acid extrusions with molecular weight preservation through annealing protocols.
- Surgical Instruments:Handles, retractors, and suction devices demand sterilization durability across gamma, steam, and ethylene oxide modalities.
- Diagnostic Equipment:Fluidic manifolds and sample handling channels require optical clarity and protein adsorption resistance.
- Medical Packaging:Form-fill-seal films and sterile barrier systems balance permeation resistance with peelable seal integrity.
Drug delivery systems command premium pricing tiers, while medical packaging generates the highest unit volumes through disposable consumption patterns.
End User:
Procurement sophistication varies sharply across customer categories, with pharmaceutical manufacturers imposing the most extensive supplier audit protocols.
- Pharmaceutical Manufacturers:Combination product regulations require extrusion suppliers to maintain drug master files and active pharmaceutical ingredient contact compliance. Swiss injectable device producers qualify tubing for biologic stability across temperature excursion profiles.
- Hospitals:Health system procurement consolidations favor extruders with validated sterilization partnerships and consignment inventory programs.
- Ambulatory Surgical Centers:Cost-focused purchasing drives specification of standard-grade extrusions over custom profiles.
- Diagnostic Laboratories:High-throughput automation compatibility determines tubing selection for liquid handling systems.
- Research Institutions:Small-batch flexibility and rapid prototyping capabilities outweigh unit cost considerations.
Pharmaceutical manufacturers represent the margin concentration point, with ambulatory surgical centers expanding most quickly through outpatient procedure migration.
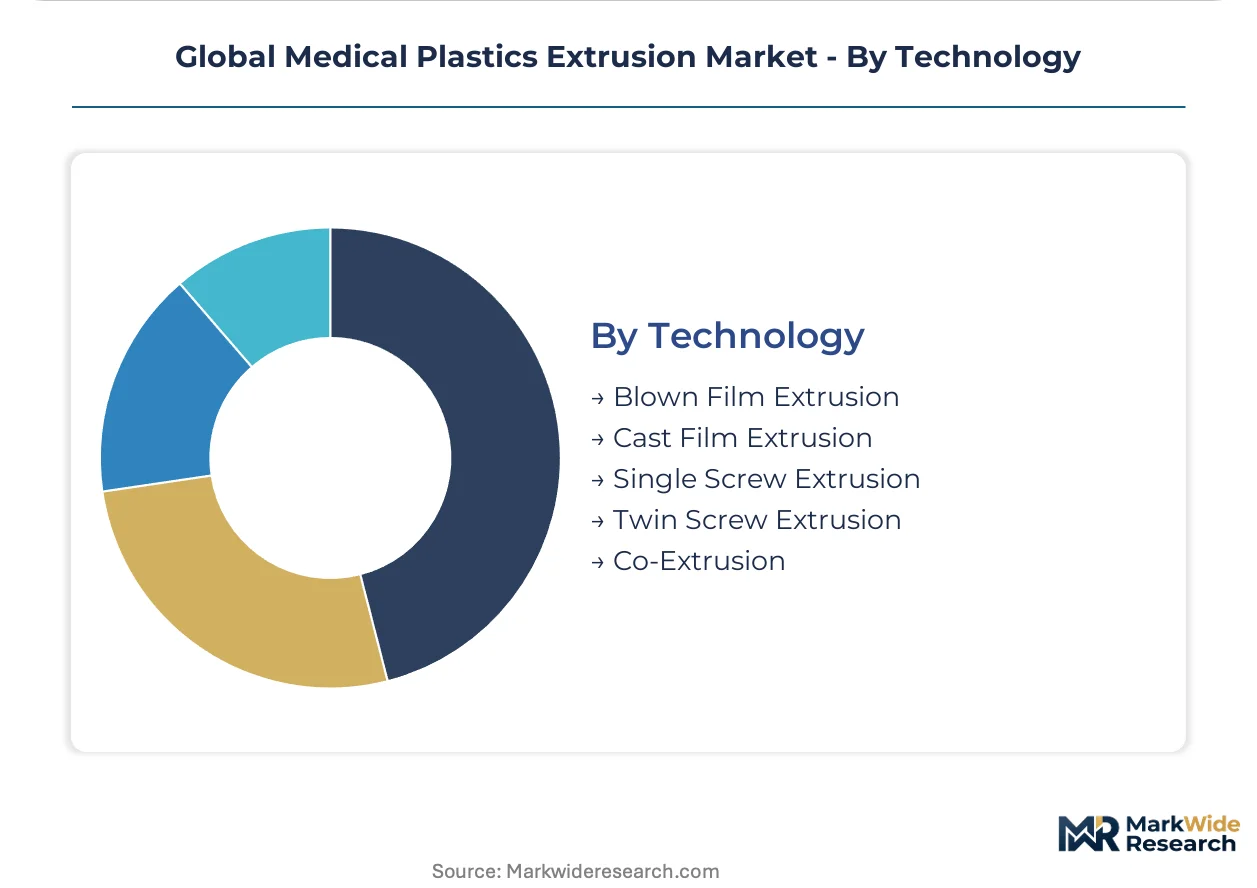
Technology:
Capital equipment intensity separates technology tiers, with multi-layer systems requiring seven-figure investments that consolidate supplier capabilities.
- Co-Extrusion:Simultaneous processing of multiple polymer streams enables property gradients impossible through monolithic formulations—radiopaque stripes, lubricious liners, and antimicrobial surfaces unified in single catheter profiles. Freiburg precision extruders supply neurovascular OEMs with five-layer architectures combining torque transmission and trackability.
- Twin Screw Extrusion:Counter-rotating intermeshing screws deliver superior mixing for filled compounds and temperature-sensitive bioresorbable polymers. German compounders employ twin-screw systems for radiopaque barium sulfate distribution in vascular access tubing.
- Blown Film Extrusion:Annular die processing creates biaxially oriented sterile barrier films with balanced mechanical properties.
- Cast Film Extrusion:Chill roll quenching produces optical-grade films for diagnostic device windows and surgical drapes.
- Single Screw Extrusion:Conventional processing dominates high-volume commodity tubing with established resin formulations.
Single screw extrusion retains the largest installed base, with co-extrusion gaining share fastest as device engineers specify multi-property tubing architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns track regulatory cost differentials as extrusion capacity relocates toward jurisdictions with streamlined medical device approval pathways and lower compliance overhead. Manufacturers balance proximity to German device clusters against emerging cost advantages in Asian supply bases.
United States
Catheter OEM procurement concentrates in Minnesota and Massachusetts medical device corridors, where FDA 510(k) pathways enable rapid product iteration. The agency's ISO 10993-aligned biocompatibility requirements elevate supplier qualification standards. Twin Cities-area extruders supply neurovascular device manufacturers with multi-lumen tubing for stroke intervention systems.
Germany
EU MDR compliance mandates force catheter manufacturers toward qualified extruders with established quality management systems. ECHA REACH restrictions on phthalate plasticizers accelerate PVC reformulation across Baden-Württemberg device clusters. Stuttgart and Freiburg precision extruders anchor European supply for cardiovascular delivery systems requiring torque-responsive profiles.
Switzerland
Swissmedic combination product regulations drive demand for extrusion suppliers maintaining drug master files and active pharmaceutical ingredient contact compliance. Injectable device producers in the Lake Geneva region qualify tubing for biologic stability across temperature excursion profiles. Basel-area pharmaceutical manufacturers impose the most extensive supplier audit protocols in European procurement.
India
CDSCO pathway acceleration opens procurement channels for Western extrusion suppliers serving domestic catheter manufacturers. Domestic device producers in Maharashtra and Gujarat expand precision tubing consumption for diabetes care and cardiac intervention platforms. Mumbai-Pune pharmaceutical corridors drive specialized polymer processing capacity for combination product applications.
China
NMPA medical device registration reforms compress approval timelines for imported extrusion components. Yangtze River Delta device manufacturers scale precision tubing consumption for endoscopic and minimally invasive surgical platforms. Shanghai-Suzhou pharmaceutical clusters source radiopaque catheter materials for domestic cardiovascular intervention markets.
Global Medical Plastics Extrusion Market Competitive Landscape
Capacity expansion dominates the current landscape as established extruders add multi-layer co-extrusion lines to capture catheter OEM consolidation. The vendor base separates into three tiers: integrated device manufacturers with captive extrusion, specialized precision tubing houses, and regional commodity processors. Two strategic archetypes define positioning: German and Swiss specialists anchor premium-tier regulatory compliance, while North American players leverage proximity to FDA submission expertise. Competitive moves center on M&A consolidation of qualified supplier bases and geographic expansion into Asian device manufacturing corridors.
Among German-based precision extruders, Raumedic occupies a position exemplifying European regulatory infrastructure depth, while Vention Medical represents North American scale advantages across multiple facilities. Putnam Plastics sits within the specialist tier, anchoring complex geometric capabilities for neurovascular and cardiovascular applications. These three names illustrate how competitive positioning fragments across geographic compliance expertise and application specialization rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| Vesta |
| Vention Medical |
| Putnam Plastics |
| Pexco |
| Raumedic |
| Spectrum Plastics Group |
| Nolato |
| Trelleborg AB |
| Bemis Manufacturing Company |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists across North American and European medical extrusion markets have compressed pricing discipline by consolidating fragmented regional processors into platform networks with unified procurement leverage and standardized cost-to-serve metrics.
Pricing Analysis
Distributor margin compression distinguishes catheter OEM procurement, where direct-to-extruder relationships bypass traditional contract manufacturer markups and impose volume-tiered pricing schedules calibrated to ISO 13485 certification depth and cleanroom classification. Price differentiation rests on FDA master file availability and EU MDR technical documentation completeness, with Swiss and German suppliers commanding premiums against commodity Asian competitors. Cost compression in standard-grade polyethylene tubing intensifies as Indian and Chinese domestic producers scale precision capabilities. Ambulatory surgical centers exhibit highest price sensitivity through consolidated GPO contracting, while pharmaceutical manufacturers prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision extruders for multi-layer co-extrusion capacity serving neurovascular and cardiovascular OEMs, where seven-figure tooling investments and 18-month qualification cycles deter rapid supplier switching. Raw material dependencies center on medical-grade polycarbonate from Belgian and US compounders, radiopaque barium sulfate formulations, and specialized thermoplastic elastomers. Tariff exposure on Chinese-sourced polymer resins threatens margin stability for cost-optimized tubing lines. Distribution runs through qualified supplier programs managed by Boston Scientific, Abbott Vascular, and Medtronic procurement divisions with direct audit protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical plastics extrusion rests on bioresorbable polymer premiumization and automation-driven yield recovery in sub-millimeter tubing categories, offsetting input volatility in specialized resin markets.
For Market Incumbents: Deepen captive supply integration into polymer compounding to secure radiopaque and lubricious additive formulations against REACH restriction-driven supply discontinuities. Expand Freiburg and Stuttgart-area cleanroom capacity to capture EU MDR consolidation demand from catheter OEMs seeking single-source multi-property tubing architectures. Prioritize ISO 13485 auditor recruitment to compress certification timelines for greenfield expansion. For New Entrants and Emerging Players: Enter via India's CDSCO-accelerated registration pathway for Western precision extruders, targeting Maharashtra-based diabetes care device manufacturers with microbore insulin delivery tubing. Penetrate bioresorbable polymer extrusion white space through polylactic acid scaffold partnerships with Irish vascular device developers. Lead with rapid prototyping capabilities and small-batch flexibility to outmaneuver incumbent minimum order quantity constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European precision extruders with underutilized co-extrusion lines and dormant FDA master files, relative to integrated device manufacturer captive operations trading at strategic control premiums. Acquisition targets should exhibit established German or Swiss regulatory infrastructure with scalable capacity for multi-lumen neurovascular applications. Monitor EU MDR notified body capacity constraints as inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Co-Extrusion Capacity Expansion | Captures catheter OEM consolidation toward single-source multi-property tubing architectures. |
| Bioresorbable Polymer Extrusion Development | Opens temporary implantable scaffold markets requiring molecular weight preservation protocols. |
| EU MDR Regulatory Infrastructure Investment | Positions suppliers for preferred vendor status under enhanced clinical evidence mandates. |
| Direct Hospital System Partnership | Bypasses contract manufacturer markups through consignment inventory and sterilization validation. |
| Carbon Footprint Disclosure Compliance | Secures sustainability-focused OEM procurement ahead of emerging polymer recycling mandates. |
Research Methodology
Direct dialogue with catheter OEM procurement directors, precision extrusion plant managers, polymer compounder technical R&D leads, and notified body ISO 13485 auditors grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, ECHA REACH restriction timelines, and German medical device cluster investment disclosures. Bottom-up capacity modeling across 15 countries triangulated against top-down catheter market demand projections.
Bottom-up segment analysis modeled polyethylene, polycarbonate, and bioresorbable polymer demand by application intensity across drug delivery, implantable, and surgical instrument categories. Top-down macro calibration incorporated FDA submission velocity, EU MDR transition timelines, and CDSCO registration reform implementation. CAGRs derived from installed extrusion line capacity, utilization rates, and OEM inventory cycle data across the analysis window. Forecast inputs included REACH phthalate restriction compliance cost curves and microbore tubing automation yield improvement trajectories.
Inputs from German trade association production surveys and Swissmedic combination product filings were available through the study window; gaps in private-equity portfolio company financial disclosure introduce uncertainty bands around mid-cap specialist market share estimates. Forecasts reflect assumptions on EU MDR notified body capacity expansion and NMPA registration reform continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Plastic Molds Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Fly Ash Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Warehouse Drums and Barrels Market