
 Cardiac Valvulotome Market | 2026-2036
Cardiac Valvulotome Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Valvulotome Market Outlook
Aftermarket service revenue for precision cutting head refurbishment is reconfiguring margin distribution across the cardiac valvulotome value chain. LeMaitre Vascular leverages specialized manufacturing capabilities in vascular instrumentation to sustain premium positioning in mechanical valvulotome segments. Edwards Lifesciences anchors its competitive stance through deep integration with cardiac surgery workflows and valve repair ecosystems. Medtronic dominates the electrosurgical valvulotome category through extensive hospital contracting networks and capital equipment placement strategies.
A cardiac valvulotome is a precision surgical instrument designed to incise fused or stenotic heart valve leaflets, typically manufactured from medical-grade stainless steel or nitinol alloys with cutting diameters ranging from 1.5 to 4.0 millimeters to enable controlled commissurotomy during open or minimally invasive procedures. The device serves the primary commercial purpose of restoring valve orifice area in patients with rheumatic or degenerative valvular disease without requiring full valve replacement. Mechanical valvulotome systems retain the largest installed base due to their reusability and established reimbursement pathways, while disposable valvulotome demand accelerates fastest as infection control protocols tighten and single-use economics improve in ambulatory settings. Robotic-assisted technology segments command the highest per-procedure margins though standard surgical techniques still generate the majority of procedure volumes across mature healthcare systems.
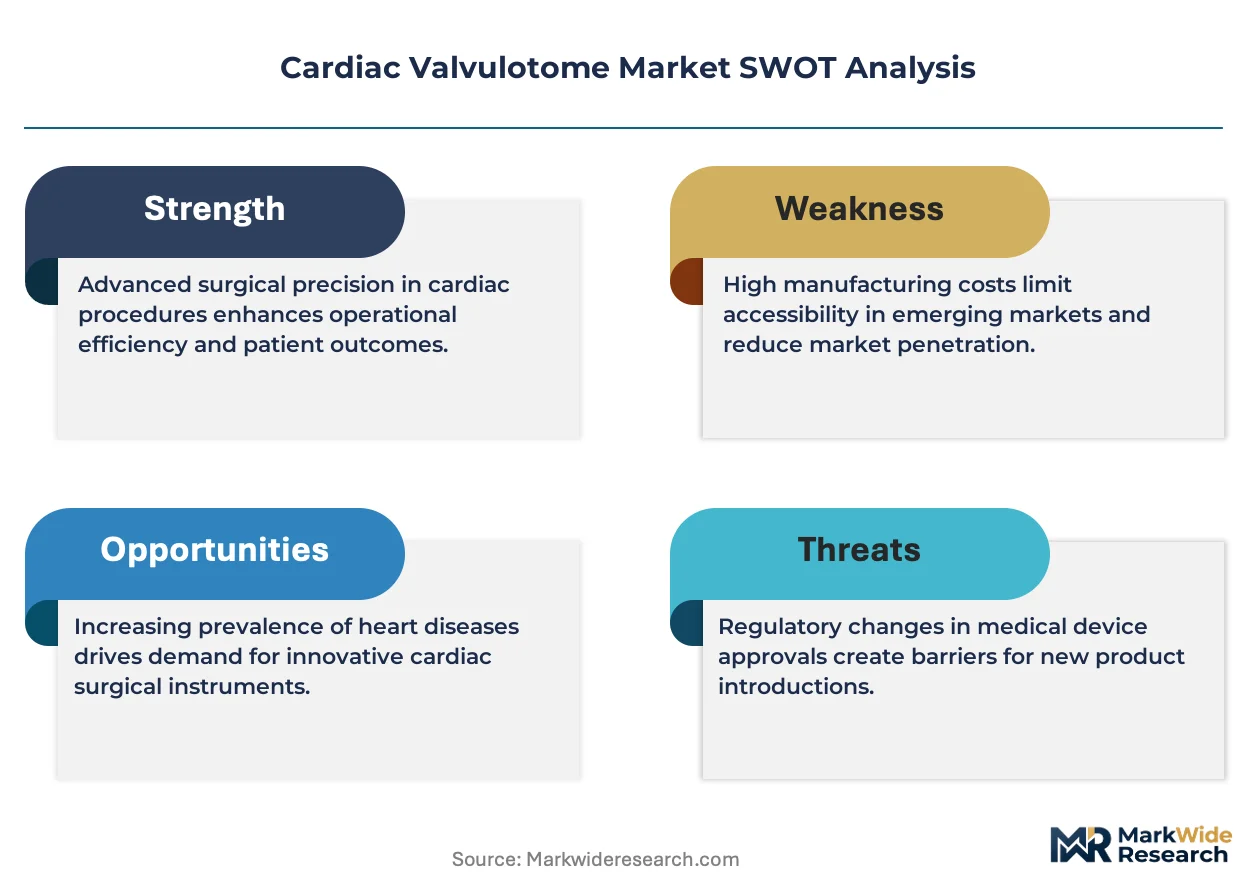
FDA 510(k) clearance requirements and EU MDR conformity assessment procedures impose substantial validation burdens on new valvulotome entrants, particularly for electrosurgical and robotic-assisted variants with active energy delivery components. Japan's PMDA and China's NMPA maintain divergent clinical evidence standards that fragment registration strategies for multinational manufacturers seeking broad commercial access. Stakeholders must monitor evolving harmonization efforts between ISO 13485 quality management frameworks and national premarket review timelines to optimize portfolio allocation across regulatory jurisdictions.
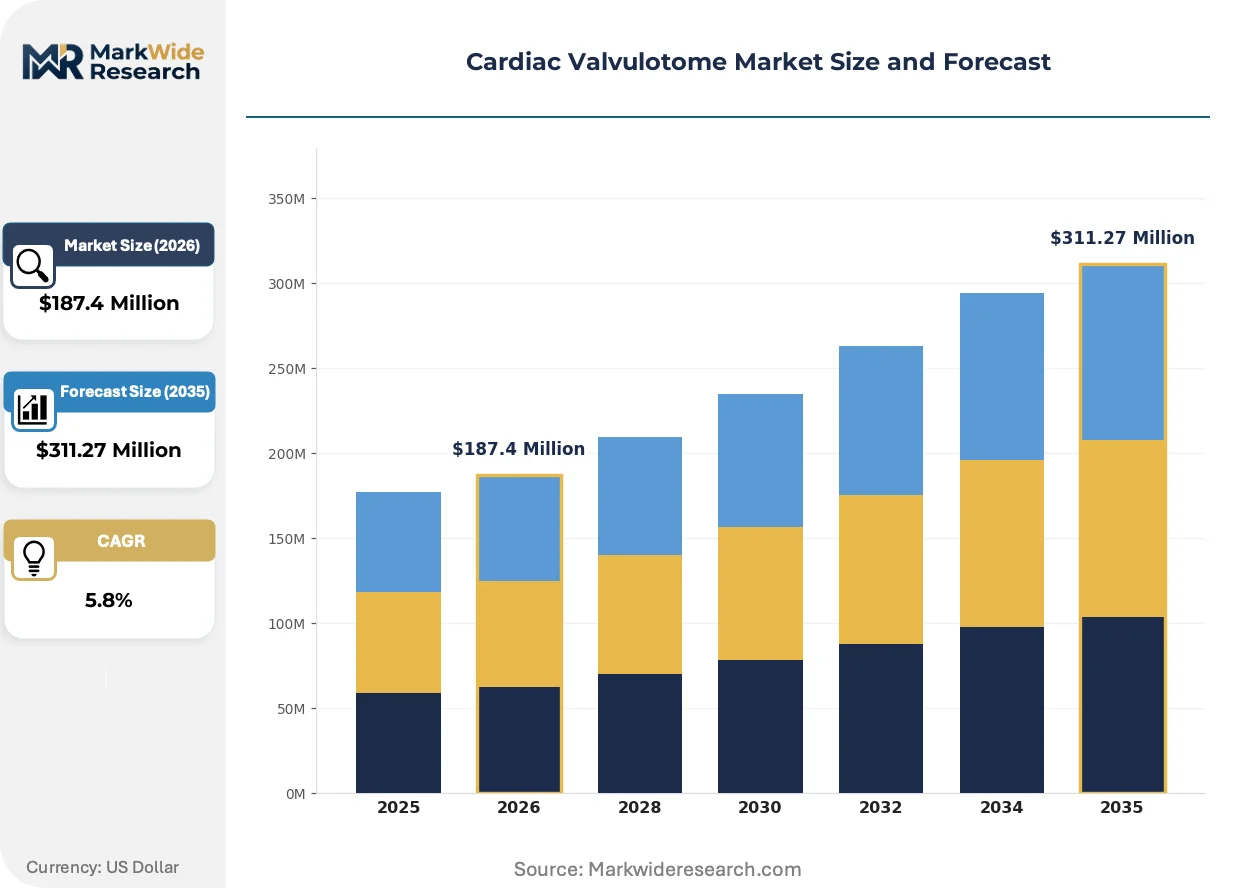
Market Dynamics
Minimally invasive surgical techniques are compressing demand for traditional open-procedure valvulotomes while expanding addressable procedure volumes through broader patient eligibility criteria and reduced recovery protocols.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited premarket notification for Class II surgical instruments accelerates electrosurgical valvulotome commercialization timelines in the United States.
- Rheumatic heart disease burden:Persistent valvular stenosis prevalence in South Asian and sub-Saharan African populations sustains mechanical valvulotome demand for commissurotomy procedures.
- Nitinol superelastic alloys:Advanced material properties enable thinner-walled, more navigable valvulotome designs compatible with transcatheter delivery systems.
Market Restraints
- EU MDR conformity assessment:Substantial clinical evidence requirements for active energy-delivery devices extend electrosurgical variant registration timelines by 18-24 months.
- Stainless steel supply concentration:Medical-grade alloy production clusters in German and Japanese specialty metallurgy facilities create input vulnerability.
- Transcatheter valve replacement substitution:Balloon-expandable and self-expanding prosthetic valves eliminate commissurotomy indication in moderate-to-severe stenosis cases.
Strategic Opportunities
- Ambulatory surgical center penetration:United States outpatient cardiac procedure site expansion creates disposable valvulotome volume opportunity outside hospital purchasing.
- Robotic-assisted surgery integration:Convergence of haptic feedback systems with precision cutting heads enables remote commissurotomy execution.
- India PLI scheme for medical devices:Production-linked incentive structures reduce landed cost for domestic valvulotome manufacturing serving South Asian markets.
Industry Challenges
- ISO 13485 quality management implementation:Small manufacturers face certification timeline compression against MDR transition deadlines.
- Electrosurgical energy calibration:Precise thermal dose control requires specialized biomedical engineering talent scarce outside established cardiac device hubs.
- Legacy instrument refurbishment:Service revenue dependence on mechanical valvulotome head reconditioning conflicts with single-use transition in infection-sensitive settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Valvulotome Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valvulotome, Electrosurgical Valvulotome, Pneumatic Valvulotome, Disposable Valvulotome End User: Cardiac Surgery Centers, Hospitals, Specialty Clinics, Research Institutions Technology: Minimally Invasive, Robotic-Assisted, Standard Surgical, Hybrid Techniques Application: Valve Repair, Valve Replacement, Congenital Heart Defects, Aortic Stenosis Treatment |
| Companies Covered | LeMaitre Vascular, Medtronic, Edwards Lifesciences, Boston Scientific, B. Braun, Teleflex Incorporated, LimFlow, Inc., INVAMED, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Valvulotome Market Strategic Shifts
Active energy delivery and robotic platform compatibility are redefining valvulotome design priorities while regulatory harmonization efforts attempt to reduce multi-jurisdiction registration fragmentation.
Radiofrequency-enabled cutting heads with integrated thermal monitoring are rendering obsolete pure mechanical commissurotomy techniques that rely on tactile feedback alone. Academic cardiac centers in Germany and the United States are piloting these systems for robotic-assisted mitral valve procedures. The technology is compressing the learning curve for precise leaflet incision while reducing perforation risk.
EU MDR technical documentation requirements for active surgical instruments now mandate clinical performance data beyond bench validation. Electrosurgical valvulotome manufacturers must demonstrate equivalence or superiority against predicate devices through prospective studies. German notified bodies are experiencing backlog concentration that delays CE marking for innovative energy-delivery variants.
Hospital procurement departments are unbundling precision instrument service contracts from capital equipment purchases. United States integrated delivery networks now negotiate cutting head refurbishment separately from initial device acquisition. This behavior is most visible in mid-Atlantic and Midwestern cardiac surgery clusters where group purchasing organization consolidation has concentrated buying power.
Cardiac Valvulotome Market Segmentation
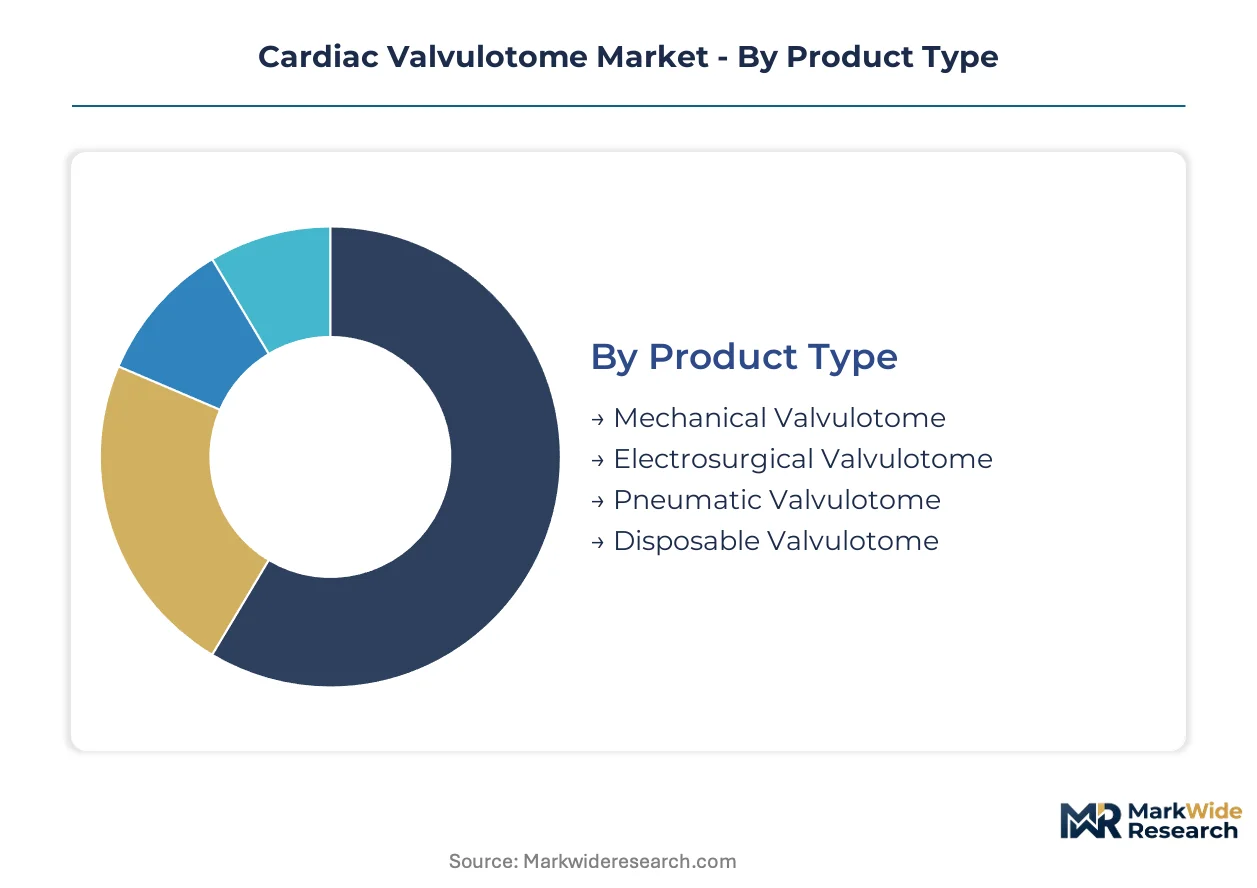
Valvulotome procurement patterns diverge sharply between capital-intensive reusable systems and high-turnover disposable units. Segment boundaries increasingly blur as electrosurgical and robotic technologies reshape traditional mechanical categories.
Product Type:
Mechanical valvulotomes turn over on 5-7 year replacement cycles, while disposable variants rotate through inventory monthly. Electrosurgical systems occupy intermediate refresh intervals tied to software updates and energy platform upgrades.
- Mechanical Valvulotome:Fabricated from medical-grade stainless steel or nitinol with reusable cutting heads requiring periodic refurbishment. German cardiac surgery centers sustain the largest installed base due to preference for precision-machined instruments with established service networks.
- Electrosurgical Valvulotome:Integrates radiofrequency energy delivery with thermal monitoring for controlled commissurotomy. United States hospital procurement departments concentrate purchases through integrated delivery networks that bundle energy platform contracts with disposable tip agreements.
- Pneumatic Valvulotome:Compressed gas-actuated cutting mechanism for high-velocity leaflet incision. Limited adoption concentrates in Japanese academic medical centers with specialized cardiac surgery training programs.
- Disposable Valvulotome:Single-use polymer construction eliminating sterilization logistics. Ambulatory surgical centers in the United States Midwest are expanding procurement fastest as infection control protocols tighten.
Mechanical valvulotomes dominate installed base. Disposable variants are where expansion concentrates.
End User:
Procurement authority concentrates differently across settings—hospitals negotiate capital equipment through group purchasing organizations while specialty clinics purchase disposables directly.
- Cardiac Surgery Centers:Dedicated facilities performing 200+ valve procedures annually with preference for robotic-compatible electrosurgical platforms. United States mid-Atlantic clusters drive premium instrument demand through concentrated surgeon expertise.
- Hospitals:General acute care settings with mixed surgical portfolios where valvulotome purchasing competes with broader capital allocation priorities. German university hospitals anchor mechanical system procurement through integrated cardiovascular service lines.
- Specialty Clinics:Focused cardiac practices in India and Brazil performing high-volume commissurotomy with cost-optimized mechanical instruments. Procurement emphasizes instrument durability over technology integration.
- Research Institutions:Academic medical centers in the United States and Germany evaluating next-generation energy delivery and robotic interfaces. Purchasing volumes remain limited but influence subsequent commercial adoption patterns.
Hospitals control capital equipment decisions. Specialty clinics are expanding fastest as procedure volumes decentralize.
Technology:
Technology tiering follows surgeon training investment and facility infrastructure—standard techniques require minimal capital while robotic platforms demand dedicated operating suite configuration.
- Minimally Invasive:Transcatheter and small-incision approaches requiring flexible, navigable valvulotome designs. Nitinol superelastic construction enables thinner-walled instruments compatible with limited-access procedures in United States outpatient settings.
- Robotic-Assisted:Haptic feedback integration with precision cutting heads for remote commissurotomy execution. German cardiac centers pilot these systems for mitral valve repair, commanding highest per-procedure margins despite limited volume.
- Standard Surgical:Traditional open-procedure techniques with direct visualization and tactile feedback. Rheumatic heart disease burden in South Asian populations sustains demand for proven mechanical instruments with minimal learning curve.
- Hybrid Techniques:Combined surgical and interventional approaches requiring instrument compatibility across catheterization and operating room environments. United States integrated delivery networks evaluate these configurations for cost optimization.
Standard surgical techniques retain procedure volume leadership. Robotic-assisted platforms are climbing the fastest.
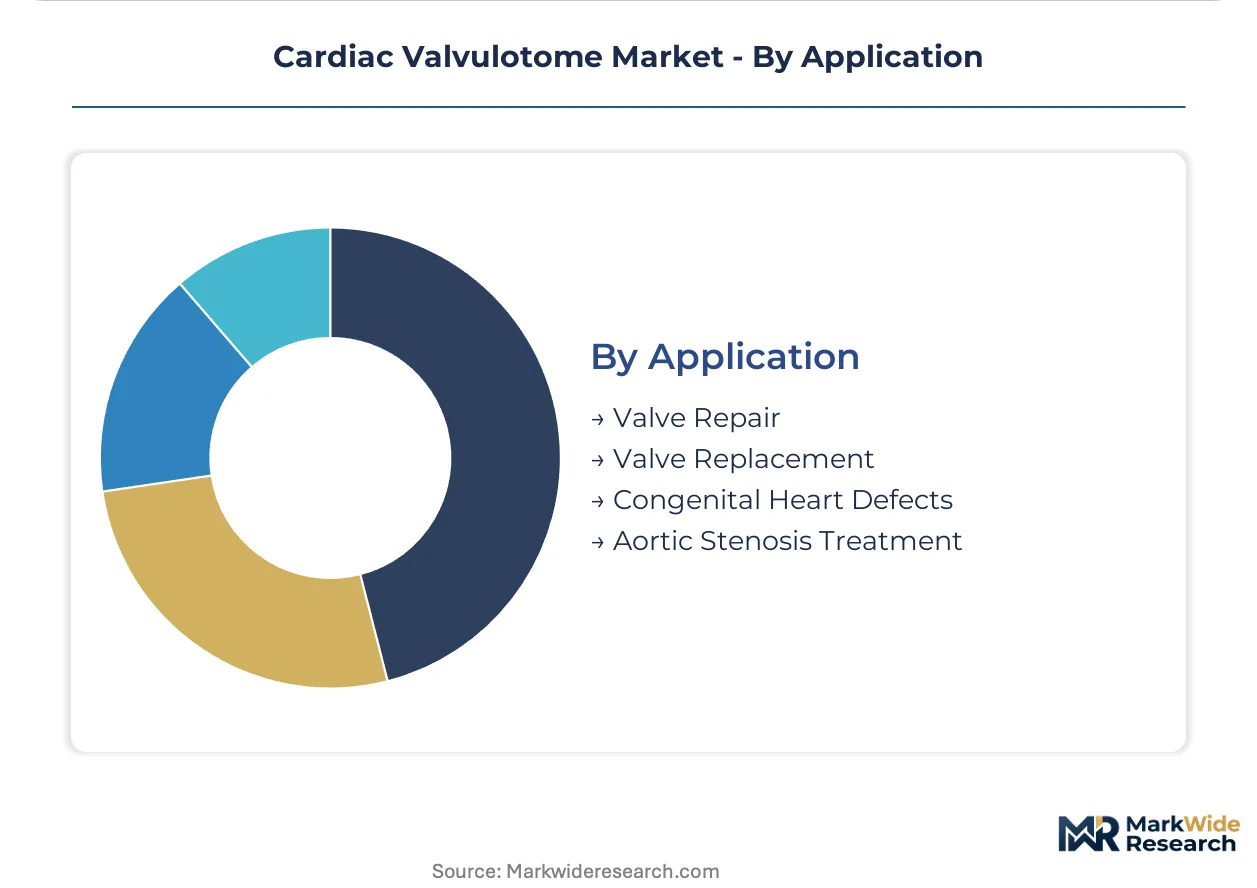
Application:
Application segmentation tracks disease etiology and intervention invasiveness—repair procedures preserve native valve anatomy while replacement eliminates recurrent stenosis risk.
- Valve Repair:Commissurotomy and leaflet reconstruction preserving native hemodynamics. German and United States academic centers concentrate electrosurgical valvulotome adoption for precise incision control.
- Valve Replacement:Prosthetic valve implantation following preparatory valvulotome use in select calcified cases. Indian subcontinent mechanical valvulotome demand concentrates here due to rheumatic disease prevalence and cost constraints.
- Congenital Heart Defects:Pediatric and adult congenital procedures requiring specialized instrument sizing. Japanese pediatric cardiac surgery programs drive demand for miniaturized mechanical designs.
- Aortic Stenosis Treatment:Degenerative calcific valve intervention where transcatheter replacement increasingly substitutes for surgical commissurotomy. Residual surgical cases concentrate in United States centers managing complex anatomy unsuitable for catheter-based approaches.
Valve repair applications anchor mechanical instrument utilization. Valve replacement procedures are gaining share fastest as patient demographics shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cardiac surgery centers favor precision-machined reusable instruments with dedicated refurbishment networks, while United States facilities accelerate disposable adoption through ambulatory surgical center expansion. Indian and Brazilian markets concentrate on cost-optimized mechanical systems for high-volume commissurotomy. Japanese academic centers pilot advanced energy-delivery configurations.
United States
FDA 510(k) pathway streamlining accelerates electrosurgical valvulotome commercialization timelines. Integrated delivery networks in the mid-Atlantic and Midwest unbundle service contracts from capital equipment purchases. Boston and Philadelphia cardiac surgery clusters drive premium instrument demand through concentrated surgeon expertise.
Germany
Specialized cardiac centers sustain the largest installed base of mechanical valvulotomes with established precision-machining service networks. EU MDR conformity assessment procedures extend registration timelines for active energy-delivery variants. Munich and Heidelberg academic medical centers pilot robotic-assisted mitral valve repair systems.
India
Rheumatic heart disease prevalence sustains mechanical valvulotome demand for cost-constrained commissurotomy procedures. Production-linked incentive schemes under the PLI program reduce landed costs for domestic manufacturing. Delhi and Mumbai specialty clinics perform high-volume valve repair with durability-focused instrument procurement.
Japan
PMDA clinical evidence standards fragment registration strategies for multinational manufacturers seeking market access. Academic medical centers in Tokyo and Osaka evaluate next-generation energy delivery and pediatric miniaturized designs. Compressed gas-actuated pneumatic systems concentrate in specialized cardiac surgery training programs.
Brazil
Cost-optimized mechanical instruments dominate procurement for degenerative and rheumatic valve disease interventions. ANVISA regulatory pathways shape product development timelines for multinational entrants. São Paulo and Rio de Janeiro specialty cardiac practices emphasize instrument durability over technology integration.
Cardiac Valvulotome Market Competitive Environment
Capability concentration sits with precision-machining specialists; scale advantage sits with diversified cardiovascular device conglomerates. The market structures around three tiers: premium electrosurgical platform developers, mid-market mechanical instrument fabricators, and emerging disposable specialists. Two dominant competitive moves are reshaping positioning: strategic partnerships between energy-platform developers and robotic surgery integrators, plus backward integration into nitinol alloy supply by established mechanical manufacturers.
Within the diversified cardiovascular conglomerate tier, Medtronic and Edwards Lifesciences exemplify scale-driven platform strategies. Boston Scientific occupies a position bridging electrosurgical innovation with interventional cardiology workflows. Among precision vascular instrumentation specialists, LeMaitre Vascular represents the dedicated mechanical instrument archetype with focused manufacturing capabilities.
| Leading Market Players |
|---|
| LeMaitre Vascular |
| Medtronic |
| Edwards Lifesciences |
| Boston Scientific |
| B. Braun |
| Teleflex Incorporated |
| LimFlow, Inc. |
| INVAMED |
| BD |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific freight corridors from German specialty metallurgy facilities to United States cardiac surgery centers impose cost dynamics that amplify supply concentration effects. Electrosurgical valvulotome manufacturers pass elevated logistics expenses downstream through tiered pricing structures that separate robotic-compatible platforms from standard mechanical instruments.
Pricing Analysis
Long-term offtake agreements between United States integrated delivery networks and electrosurgical platform developers anchor premium pricing tiers, while spot purchasing dominates disposable valvulotome procurement in ambulatory surgical centers. Price differentiation rests on FDA 510(k) clearance tier and volume scale commitments. Cost compression in mechanical instrument refurbishment services intensifies as single-use protocols displace reusable systems. Specialty clinics in India and Brazil exhibit highest price sensitivity; German cardiac centers demonstrate lowest sensitivity due to preference for precision-machined instruments with bundled service contracts.
Supply Chain Analysis
Contract manufacturing for nitinol superelastic components concentrates in German and Japanese precision metallurgy facilities, with polymer molding for disposable variants distributed across United States and Chinese medical device foundries. Raw material dependencies center on medical-grade stainless steel, nitinol alloys, and radiofrequency generator subassemblies. Single-source vulnerability in specialized cutting head fabrication creates exposure to EU MDR transition delays. Distribution runs through hospital group purchasing organizations for capital equipment and direct-to-clinic channels for high-turnover disposable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac valvulotome demand sits in early-cycle expansion as robotic-assisted surgery adoption accelerates procedural addressability beyond traditional open-procedure candidates. Minimally invasive technique penetration in United States outpatient settings extends market reach without requiring equivalent capital infrastructure investment.
For Market Incumbents: Harden service network control over precision cutting head refurbishment to defend against disposable substitution in infection-sensitive settings. Deepen backward integration into nitinol alloy supply through captive sourcing agreements with German or Japanese metallurgy specialists. Electrosurgical platform commoditization from integrated delivery network bundling poses the central threat; differentiation through haptic feedback integration and robotic compatibility offers the strongest defensive lever. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgical center disposable valvulotome procurement, where United States Midwest expansion creates volume opportunity outside established hospital contracting relationships. Target pneumatic valvulotome niches in Japanese academic training programs where incumbent presence remains limited. Direct sales to specialty clinics with emphasis on sterilization logistics elimination provides the clearest go-to-market angle against capital-intensive platform competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates seeking to divest non-core mechanical instrument portfolios amid electrosurgical transition. Precision-machining specialists with established refurbishment networks and ISO 13485 certification infrastructure represent the most defensible acquisition archetype over a five-to-ten year horizon. Monitor FDA 510(k) clearance velocity for electrosurgical variants as the critical inflection signal; accelerated approvals indicate platform consolidation timing, while extended timelines sustain mechanical instrument relevance.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Integration | Haptic feedback convergence with precision cutting heads enables remote commissurotomy execution in German academic centers. |
| CE Marking Pathway Acceleration | EU MDR technical documentation investment reduces backlog exposure for electrosurgical variants with active energy delivery. |
| Hospital System Partnership | Integrated delivery network contracting secures bundled energy platform and disposable tip placement in United States mid-Atlantic clusters. |
| Software Companion Development | Thermal monitoring algorithms for radiofrequency-enabled cutting heads compress learning curves and reduce perforation risk. |
| Reimbursement Strategy | CPT code alignment for robotic-assisted commissurotomy procedures unlocks ambulatory surgical center expansion in United States outpatient settings. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and hospital procurement contract filings preceded structured interviews with cardiac surgeons, biomedical engineers, group purchasing organization contracts managers, and valvulotome manufacturing operations directors. Secondary validation drew from SEC 10-K filings of publicly traded cardiovascular device manufacturers, ISO 13485 certification registries, and trade flow data for medical-grade nitinol alloys. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation across mechanical, electrosurgical, and disposable product categories.
Assumptions regarding FDA review timeline stability, EU MDR notified body capacity, and nitinol alloy price volatility were held fixed across baseline scenarios while robotic surgery adoption curves and transcatheter valve replacement substitution rates were varied in sensitivity testing. The analytical framework modeled volume and value outputs across product type, end user facility category, technology tier, and application indication dimensions. CAGRs were derived from logistic diffusion curves fitted to historical procedure data and adjusted for regulatory approval velocity and reimbursement policy shifts. Forecast inputs incorporated rheumatic heart disease prevalence projections and ambulatory surgical center site expansion trajectories.
Stress conditions across FDA 510(k) backlog accumulation, EU MDR transition deadline extensions, and transcatheter valve replacement penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding minimally invasive technique adoption and infection control protocol tightening in outpatient settings. Quarterly review of FDA premarket notification clearance velocity, German notified body queue lengths, and United States ambulatory surgical center cardiac procedure authorization trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Stable Angina Management Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market