
 Transcatheter Pulmonary Valve Replacement Market | 2026-2036
Transcatheter Pulmonary Valve Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Pulmonary Valve Replacement Market Insights
The capital-intensity divergence between integrated device manufacturers and focused transcatheter innovators is unwinding competitive dynamics across the valve replacement landscape. Medtronic leverages its structural heart portfolio to sustain manufacturing scale and cath lab system integration. Edwards Lifesciences Corporation anchors its position through deep specialization in tissue valve engineering and percutaneous delivery platforms. Abbott competes across multiple structural heart segments while navigating distinct regulatory pathways for pediatric and adult indications.
Transcatheter pulmonary valve replacement encompasses percutaneous implantation of prosthetic valves within failing native or surgically placed right ventricular outflow tract conduits, typically utilizing bovine or porcine pericardial tissue mounted on nickel-titanium or cobalt-chromium frames delivered via femoral or jugular venous access. The procedure eliminates sternotomy and cardiopulmonary bypass for patients with repaired tetralogy of Fallot or other congenital lesions. Bioprosthetic valves occupy the dominant revenue position given established durability data and tissue compatibility profiles, while self-expandable valves represent the fastest-growing product category as nitinol frame designs improve conformability within dilated native outflow tracts. Hospitals capture the largest end-user share due to hybrid operating room infrastructure requirements, though specialty care facilities are expanding capacity for lower-complexity redo procedures.
FDA premarket approval and humanitarian device exemption pathways govern US market entry, while CE marking under the EU Medical Device Regulation and Japan's PMDA shonin approval shape access across other major jurisdictions. The central bank of regulatory risk for manufacturers lies in pediatric indication expansions, where long-term hemodynamic performance data requirements extend trial timelines. Stakeholders must monitor evolving reimbursement thresholds for congenital heart interventions as health technology assessment bodies tighten evidence standards for transcatheter versus surgical alternatives.
Market Dynamics
Balloon-expandable valve platforms are ceding ground to self-expanding nitinol frames as dilated native right ventricular outflow tracts become the dominant anatomical target, compressing the addressable patient pool for earlier-generation delivery systems and forcing portfolio reallocation among device manufacturers.
Growth Catalysts
- FDA Humanitarian Device Exemption pathway:Streamlined pediatric indication approvals accelerate commercialization timelines for congenital heart defect interventions, reducing regulatory friction for tissue valve innovators targeting repaired tetralogy of Fallot populations.
- Tertiary hospital hybrid operating room expansion:Capital investment in catheterization-surgical suites enables same-admission transcatheter pulmonary valve replacement without inter-facility transfers, capturing procedure volume previously lost to logistical fragmentation.
- Bioprosthetic tissue engineering advances:Enhanced bovine pericardial leaflet processing improves hemodynamic durability profiles, extending valve functional lifespan and expanding the redo-procedure candidate pool beyond surgical conduit failure.
Market Restraints
- Nickel-titanium alloy supply concentration:Nitinol wire and tube production clusters in a limited set of specialized metallurgical suppliers, exposing frame manufacturers to input cost volatility and geopolitical trade friction.
- Long-term hemodynamic data requirements:Pediatric indication expansions demand extended follow-up protocols that stretch clinical trial timelines and defer revenue recognition for emerging valve platforms.
- Surgical pulmonary valve replacement durability:Established surgical conduits with documented 15-20 year lifespans present a credible substitute for adult patients with favorable anatomy, constraining transcatheter penetration in lower-risk demographics.
Strategic Opportunities
- Japan's PMDA shonin approval pathway:Streamlined regulatory access for novel structural heart devices creates first-mover advantage for manufacturers with existing CE marking under EU Medical Device Regulation.
- Remote catheterization lab networks:Hub-and-spoke distribution models connecting community cardiology centers to tertiary procedural expertise expand geographic reach without full hybrid OR capital requirements.
- Computational modeling and 3D-printed patient-specific sizing:Pre-procedural simulation convergence with additive manufacturing reduces valve size mismatch rates and enables outpatient screening workflows.
Industry Challenges
- Pediatric interventional cardiology fellowship pipeline constraints:The specialized skill set combining congenital anatomy expertise with transcatheter delivery technique faces training program bottlenecks, limiting operator availability for program expansion.
- Health technology assessment evidence thresholds:Reimbursement bodies in Germany and Japan are tightening comparative effectiveness requirements against surgical alternatives, demanding prospective registry data that extends market access timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Pulmonary Valve Replacement Market |
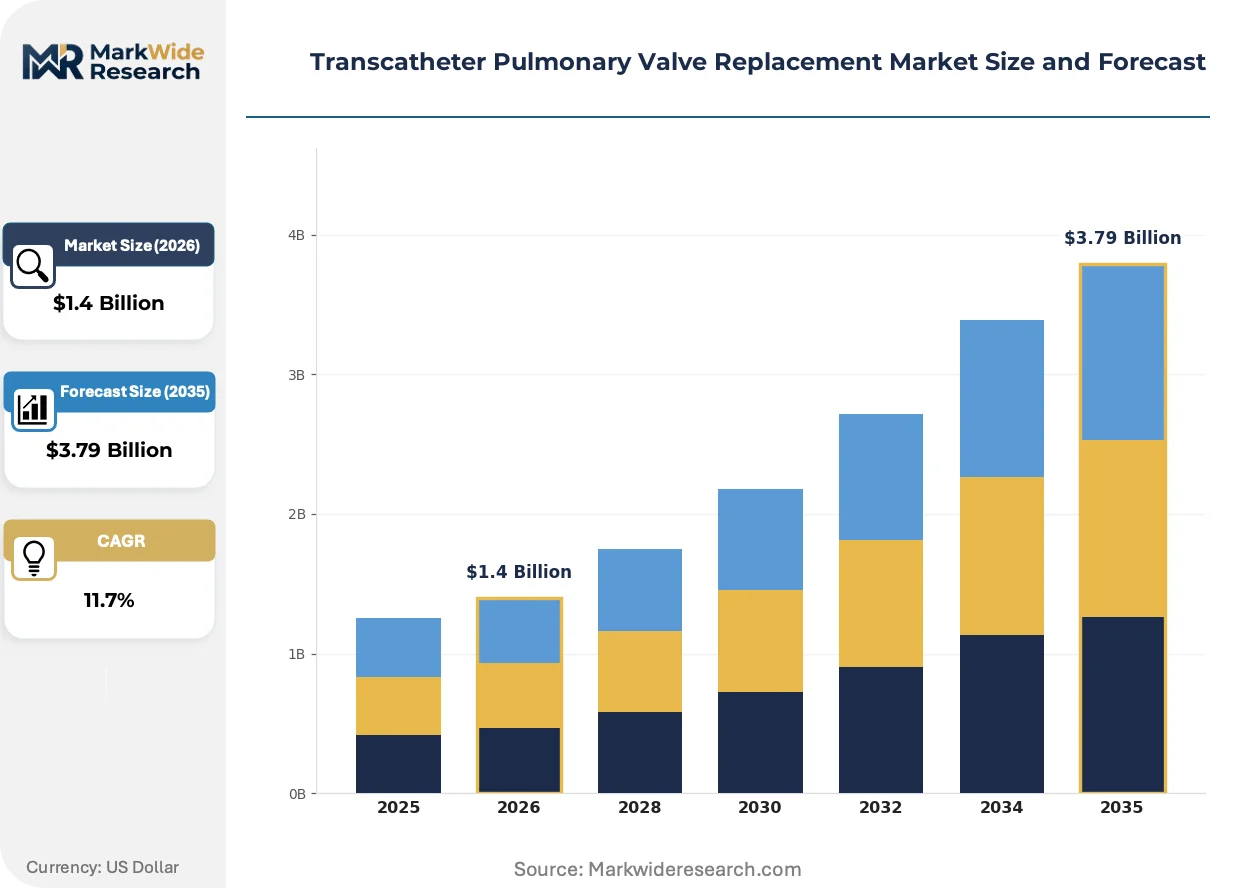
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprosthetic Valves, Self-Expandable Valves, Balloon-Expandable Valves, Mechanical Valves End User: Cardiology Clinics, Hospitals, Outpatient Centers, Specialty Care Facilities Delivery Mode: Transcatheter Access, Open-heart Approach, Minimal Access Surgery, Hybrid Procedures Patient Age Group: Pediatric Patients, Adult Patients, Geriatric Patients, Adolescent Patients |
| Companies Covered | Medtronic, Edwards Lifesciences Corporation, Abbott, Boston Scientific Corporation, JenaValve Technology, Inc., LivaNova PLC, Terumo Corporation, Artivion, Xeltis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Pulmonary Valve Replacement Market Trends and Innovations
Transcatheter pulmonary valve replacement is undergoing a platform shift from surgical conduit-dependent procedures toward native outflow tract interventions, enabled by frame design evolution and pre-procedural imaging advances that reshape patient selection criteria.
Self-expanding nitinol valve frames with conformable skirt designs are supplanting balloon-expandable platforms in dilated native right ventricular outflow tracts. Pediatric cardiology departments at congenital heart centers are adopting these systems for anatomic variants previously deemed unsuitable for transcatheter approaches. The technology is compressing the surgical referral pipeline for redo pulmonary valve replacement by expanding the treatable anatomical spectrum without sternotomy.
EU Medical Device Regulation clinical evaluation requirements are intensifying post-market surveillance obligations for bioprosthetic valve manufacturers. The regulation mandates systematic literature reviews and periodic safety update reports that extend compliance costs across the product lifecycle. Pediatric indication holders face disproportionate impact as long-term follow-up data requirements compound with smaller denominator patient populations.
Hospital procurement committees are consolidating transcatheter valve purchasing through single-source structural heart contracts rather than device-specific negotiations. The committee model displaces individual physician preference in favor of system-wide value assessments integrating procedure volume, training support, and capital equipment bundling. This behavioral shift concentrates most visibly in United States integrated delivery networks where catheterization lab standardization reduces inventory complexity.
Transcatheter Pulmonary Valve Replacement Market Segmentation
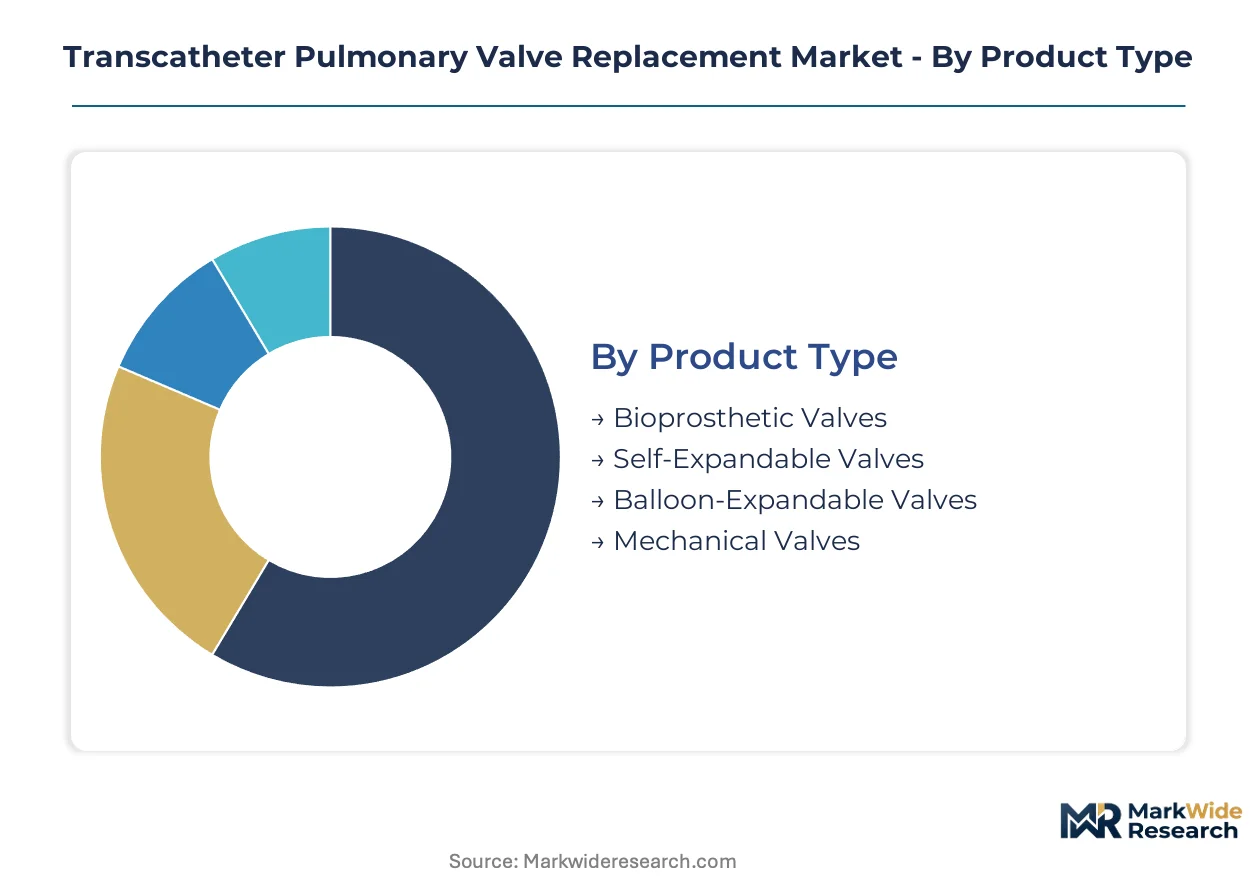
Segmentation in transcatheter pulmonary valve replacement reveals how regulatory pathways, anatomical complexity, and care setting infrastructure partition commercial opportunity. Manufacturers must align product specifications with distinct FDA, CE marking, and PMDA requirements across each category.
Product Type:
FDA premarket approval and CE marking under EU Medical Device Regulation impose divergent evidence requirements across valve platforms, shaping portfolio investment priorities.
- Bioprosthetic Valves:Bovine or porcine pericardial tissue mounted on metallic frames dominates current procedure volumes. Tertiary congenital heart centers in the United States and Germany drive demand for these valves given established durability data and tissue compatibility profiles.
- Self-Expandable Valves:Nitinol frame designs with conformable skirts enable treatment of dilated native right ventricular outflow tracts previously unsuitable for transcatheter approaches. Pediatric cardiology departments at Japanese university hospitals are expanding adoption fastest as PMDA shonin approvals streamline market access.
- Balloon-Expandable Valves:Earlier-generation platforms face compressing addressable patient pools as anatomical targets shift toward native outflow tracts.
- Mechanical Valves:Limited commercial presence due to anticoagulation requirements and congenital heart patient lifecycle considerations.
Bioprosthetic valves handle the majority of throughput; self-expandable valves are expanding most quickly on share.
End User:
Capital intensity and reimbursement thresholds stratify valve procurement across care settings, with hybrid infrastructure requirements filtering market participation.
- Hospitals:Hybrid operating room infrastructure and cath lab system integration capture the largest procedure volume. United States integrated delivery networks and German university medical centers consolidate purchasing through single-source structural heart contracts.
- Cardiology Clinics:Hub-and-spoke models connecting community centers to tertiary expertise enable lower-complexity redo procedures without full surgical backup.
- Specialty Care Facilities:Pediatric-focused congenital heart centers concentrate expertise for complex anatomical variants.
- Outpatient Centers:Limited penetration due to emergency surgical backup requirements and overnight monitoring protocols.
Hospitals absorb the dominant share of valve placements; specialty care facilities are climbing the fastest as pediatric program expansion accelerates.
Delivery Mode:
Operator training pathways and anatomical complexity determine access route selection, with fellowship pipeline constraints limiting technique diffusion.
- Transcatheter Access:Femoral or jugular venous delivery eliminates sternotomy and cardiopulmonary bypass. United States congenital heart centers and Japanese pediatric cardiology departments drive volume growth as fellowship programs expand interventional training capacity.
- Hybrid Procedures:Combined catheterization-surgical approaches enable bail-out surgical conversion for high-risk anatomies.
- Minimal Access Surgery:Thoracotomy-based delivery retains niche application for specific conduit morphologies.
- Open-heart Approach:Surgical valve replacement remains the comparator for health technology assessment bodies in Germany tightening evidence standards.
Transcatheter access commands the procedural majority; hybrid approaches are gaining share fastest as case complexity escalates.
Patient Age Group:
Long-term hemodynamic data requirements and valve durability expectations create distinct commercial timelines across developmental stages.
- Pediatric Patients:Repaired tetralogy of Fallot populations require valve systems compatible with somatic growth. FDA Humanitarian Device Exemption pathway accelerates approval timelines, though extended follow-up protocols defer full market authorization.
- Adult Patients:Largest absolute volume segment with established surgical conduit failure as primary indication.
- Adolescent Patients:Transition age group with specific sizing challenges as outflow tract dimensions stabilize.
- Geriatric Patients:Smallest segment given congenital heart disease epidemiology and life expectancy patterns.
Adult patients account for the dominant procedure load; pediatric applications show the steepest expansion trajectory as indication expansions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procedure volumes and patient selection criteria diverge sharply across major markets, with congenital heart center density and reimbursement frameworks determining transcatheter pulmonary valve replacement utilization patterns.
United States
Pediatric cardiology departments at tertiary congenital heart centers in Boston, Philadelphia, and Houston drive the largest absolute procedure volumes. FDA Humanitarian Device Exemption pathways accelerate pediatric indication approvals, though extended follow-up requirements defer full market authorization for novel platforms. Integrated delivery networks in the Midwest and Southeast are consolidating valve purchasing through single-source structural heart contracts.
Germany
University medical centers in Munich, Heidelberg, and Berlin anchor European procedure volume through established hybrid operating room infrastructure. CE marking under EU Medical Device Regulation imposes intensified post-market surveillance obligations, mandating systematic literature reviews and periodic safety update reports. Health technology assessment bodies are tightening comparative effectiveness evidence thresholds against surgical alternatives.
Japan
Pediatric cardiology departments at Tokyo and Osaka university hospitals are expanding adoption fastest as PMDA shonin approvals streamline market access for self-expanding nitinol valve systems. The national reimbursement system for congenital heart interventions creates predictable procurement timelines for bioprosthetic valve manufacturers. Kansai and Kanto regions concentrate specialized interventional training capacity.
United Kingdom
NHS specialized commissioning frameworks concentrate transcatheter pulmonary valve replacement within designated congenital heart centers in London, Birmingham, and Liverpool. MHRA post-Brexit regulatory pathways maintain alignment with EU Medical Device Regulation clinical evaluation requirements. Pediatric transition services for repaired tetralogy of Fallot patients are expanding interventional cardiology fellowship pipelines.
Canada
Health Canada approval pathways for novel structural heart devices create sequential market entry following US FDA premarket authorization. Tertiary pediatric cardiology programs in Toronto, Montreal, and Vancouver capture national referral patterns for complex redo procedures. Provincial health technology assessment processes are converging on evidence standards for transcatheter versus surgical pulmonary valve replacement.
Transcatheter Pulmonary Valve Replacement Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in transcatheter pulmonary valve replacement, with capital intensity and regulatory navigation capabilities determining competitive position. Device manufacturers cluster around two strategic archetypes: diversified structural heart portfolios leveraging manufacturing scale and cath lab system integration, versus focused innovators concentrating on tissue valve engineering and percutaneous delivery platforms. Portfolio reallocation toward self-expanding nitinol frames and pediatric indication expansions represent the dominant competitive moves as anatomical targets shift.
Within the integrated tier, Medtronic and Edwards Lifesciences Corporation occupy positions spanning multiple structural heart segments with established regulatory pathways across FDA, CE marking, and PMDA jurisdictions. Abbott exemplifies the diversified medical technology archetype competing across cardiac rhythm management, vascular, and structural heart segments simultaneously. Boston Scientific Corporation represents the interventional cardiology specialist model with concentrated expertise in catheter-based delivery systems.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences Corporation |
| Abbott |
| Boston Scientific Corporation |
| JenaValve Technology, Inc. |
| LivaNova PLC |
| Terumo Corporation |
| Artivion |
| Xeltis |
| Others |
Pricing and Supply Chain Analysis
FDA premarket approval and CE marking under EU Medical Device Regulation gate both supplier qualification and price differentiation simultaneously, as manufacturers must absorb extended clinical trial costs and post-market surveillance obligations that stratify valve systems across premium and standard tiers based on indication breadth and durability data depth.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and diversified structural heart manufacturers dominate procurement, with three-tier pricing structure across premium, standard, and economy levels reflecting FDA indication scope, tissue processing methodology, and cath lab system bundling. Price differentiation stems from pediatric indication exclusivity and hybrid OR capital equipment integration. Cost compression in standard-tier bioprosthetic valves is intensifying because hospital procurement committees are consolidating purchasing through single-source structural heart contracts. Pediatric cardiology departments at tertiary congenital heart centers exhibit lowest price sensitivity due to limited alternative suppliers and emergency surgical backup requirements.
Supply Chain Analysis
United States and Germany anchor nitinol wire and tube production for self-expanding valve frames, while Japan and Switzerland concentrate precision laser-cutting and surface finishing capabilities for cobalt-chromium components. Raw material dependencies include nickel-titanium alloy feedstock, bovine pericardial tissue from regulated abattoirs, and biocompatible polymer skirt materials. Single-source vulnerability in specialized metallurgical suppliers exposes frame manufacturers to input cost volatility and geopolitical trade friction. Distribution runs through direct sales forces to hospital procurement committees and GPO contracts, with limited third-party distributor participation due to technical training requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcatheter pulmonary valve replacement functions as a regulatory entrenchment market where FDA Humanitarian Device Exemption pathways and extended pediatric follow-up protocols create formidable switching costs for hospital systems and congenital heart centers.
For Market Incumbents: Fortify positions through backward integration into nitinol wire production and captive tissue processing facilities to offset nickel-titanium alloy supply concentration. Expand CE marking portfolios under EU Medical Device Regulation ahead of competitors to capture German university medical center procurement cycles. Emerging focused innovators with self-expanding nitinol platforms threaten market share in dilated native outflow tract segments. For New Entrants and Emerging Players: Anchor in Japan's PMDA shonin approval pathway for streamlined market access following CE marking completion, targeting pediatric cardiology departments at Tokyo and Osaka university hospitals where adoption of conformable skirt designs is accelerating. Hub-and-spoke remote catheterization lab networks in United States Midwest and Southeast regions offer the most penetrable infrastructure for lower-complexity redo procedures without full hybrid OR capital requirements. Pursue computational modeling partnerships for 3D-printed patient-specific sizing as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across self-expandable valve manufacturing as nitinol frame complexity and conformable skirt engineering demand specialized equipment investments. Long-term viability over the next decade favors manufacturers with diversified structural heart portfolios capable of absorbing pediatric indication trial timelines and cross-subsidizing regulatory compliance costs. Acquisition target archetype: focused innovators with CE-marked self-expanding platforms and established Japanese PMDA relationships. Monitor health technology assessment body evidence threshold tightening in Germany as the signal to watch for reimbursement risk inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | FDA Humanitarian Device Exemption pathway accelerates approval timelines for repaired tetralogy of Fallot populations. |
| Self-Expanding Nitinol Platform Development | Conformable skirt designs enable treatment of dilated native right ventricular outflow tracts previously unsuitable for transcatheter approaches. |
| Hybrid Operating Room Partnership | Capital investment in catheterization-surgical suites captures procedure volume previously lost to inter-facility transfers. |
| Computational Modeling Integration | Pre-procedural simulation convergence with additive manufacturing reduces valve size mismatch rates and enables outpatient screening. |
| EU Medical Device Regulation Compliance Investment | Systematic literature reviews and periodic safety update reports extend compliance costs but create regulatory moats against under-resourced competitors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pediatric interventional cardiologists, congenital heart center procurement managers, biomedical engineers, and GPO contracts directors; and secondary validation against FDA 510(k) and PMA filings, EUDAMED device registrations, hospital procurement databases, and CMS Medicare claims data. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue segmentation across the analysis window.
Across the projection horizon, the analytical framework modeled valve replacement demand through product type, end user infrastructure tier, delivery mode complexity, and patient age group developmental stage. CAGRs were derived from regression-based trend extrapolation incorporating procedural volume trajectories, reimbursement pathway maturation, and technology substitution elasticities. Industry-specific forecast inputs included pediatric fellowship program expansion rates and hybrid OR capital expenditure cycles at tertiary congenital heart centers.
Decision-makers should treat outputs as directional under assumptions of stable FDA and PMDA regulatory timelines and continued nickel-titanium alloy supply availability; material deviation in pediatric indication approval velocity or geopolitical trade restrictions would warrant model refresh. Recalibration cycles align with material shifts in health technology assessment evidence standards and congenital heart center density expansion patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
C-Arms Devices Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Creatinine Meter Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
Japan Drug Delivery Devices Market