
 Asia-Pacific Acute Coronary Syndrome Market | 2026-2036
Asia-Pacific Acute Coronary Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Acute Coronary Syndrome Market Outlook
Fixed-dose combination packaging for dual antiplatelet therapy is hardening as the default discharge configuration across Asia-Pacific cardiac wards. AstraZeneca leverages its regional manufacturing footprint to sustain supply continuity for ticagrelor-based regimens. Daiichi Sankyo Company anchors its position through deep specialization in oral anticoagulant formulations tailored to East Asian metabolic profiles.
Acute Coronary Syndrome encompasses a spectrum of clinical conditions including myocardial infarction and unstable angina arising from sudden coronary artery occlusion, typically managed through immediate antiplatelet inhibition, beta-blockade, and statin therapy to stabilize plaque and restore perfusion. Antiplatelet agents occupy the largest margin pool due to mandatory post-PCI continuation protocols, while injectable delivery modes lead emergency department settings where rapid therapeutic onset determines outcomes. Oral statin segments dominate maintenance phases across cardiology clinics and rehabilitation centers throughout the region.
Japan's PMDA, India's CDSCO, and Australia's TGA enforce divergent bioequivalence standards that fragment registration timelines for generic antiplatelet entrants across the region. The EU MDR's extraterritorial influence on multinational device-drug combination submissions further complicates market access for stent-coating therapies. Stakeholders must monitor regulatory harmonization negotiations between ASEAN member states to anticipate whether centralized drug approval mechanisms will reshape competitive entry dynamics.
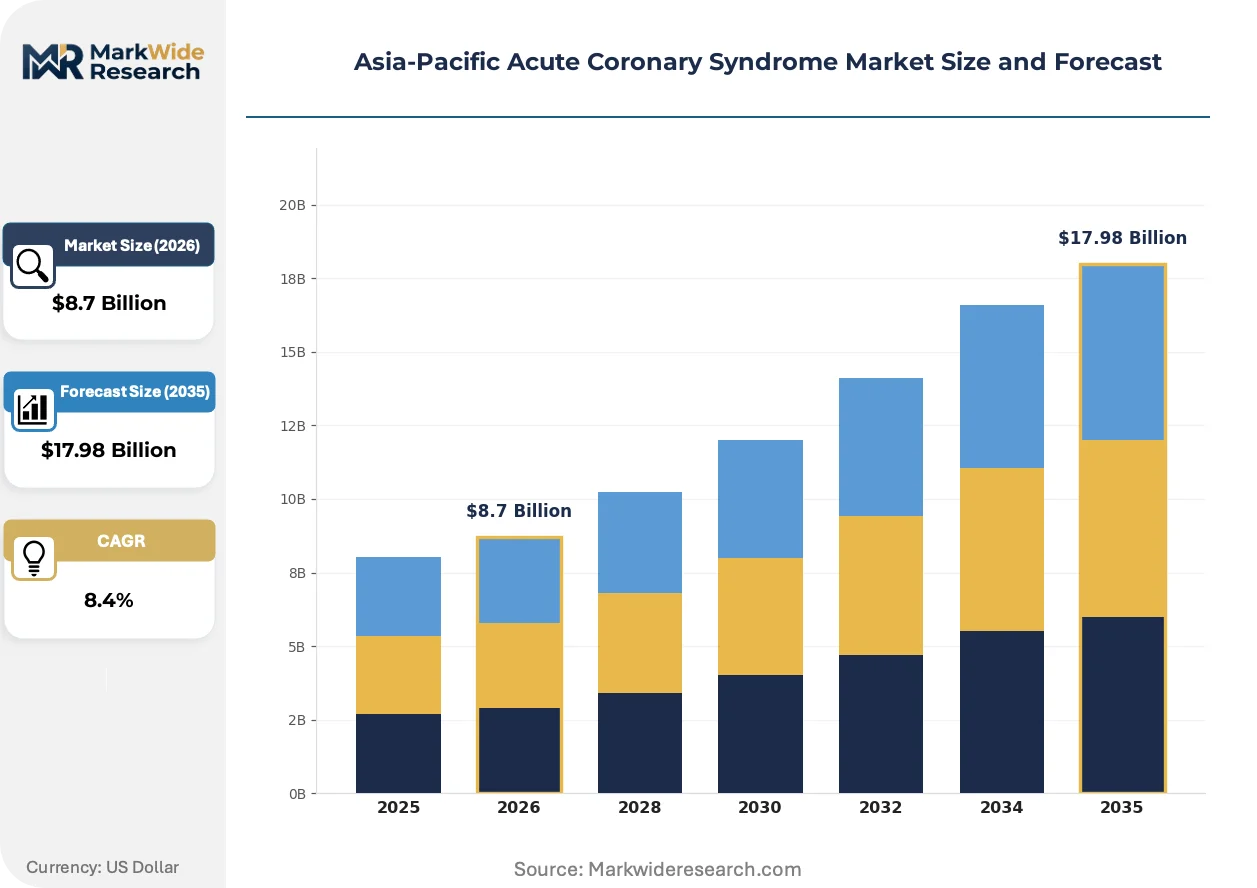
Market Dynamics
Dual antiplatelet therapy standardization is compressing formulation diversity across Asia-Pacific cardiac units, forcing manufacturers to consolidate around fixed-dose packaging formats that simplify discharge protocols but erode margin differentiation.
Growth Catalysts
- Government health insurance expansion:India's Ayushman Bharat scheme is widening percutaneous coronary intervention access to previously uncovered patient populations.
- PMDA accelerated approval pathways:Japan's streamlined antiplatelet review timelines are compressing novel agent time-to-market by eliminating redundant bridging studies.
- Cardiac catheterization infrastructure:Southeast Asian hospital networks are installing emergency PCI capabilities in secondary cities previously dependent on tertiary referral.
Market Restraints
- Bioequivalence fragmentation:Divergent CDSCO, PMDA, and TGA standards force generic antiplatelet sponsors to execute separate regional trials.
- Active pharmaceutical ingredient concentration:East Asian API supply clusters create single-source vulnerability for clopidogrel precursors.
- EU MDR extraterritoriality:Stent-coating combination products face redundant technical documentation for device-drug submissions.
Strategic Opportunities
- Rural India penetration:Telecardiology-linked hub-and-spoke models enable diagnosis in districts lacking on-site interventional capacity.
- Metabolic-tailored dosing:East Asian CYP2C19 polymorphism prevalence creates demand for genotype-guided antiplatelet selection protocols.
- ASEAN regulatory harmonization:Centralized drug approval negotiations may collapse multi-country registration into single-market entry.
Industry Challenges
- Interventional cardiologist density:Training pipeline gaps in Indonesia and Vietnam limit PCI volume expansion despite installed hardware.
- Cold-chain last-mile integrity:Temperature-sensitive monoclonal antiplatelet biologics degrade in tropical distribution networks lacking validated storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Acute Coronary Syndrome Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiplatelet Agents, Beta-blockers, ACE Inhibitors, Statins Therapy Area: Myocardial Infarction, Unstable Angina, Chest Pain, Revascularization Delivery Mode: Injectable, Oral, Intravenous, Sublingual End User: Hospitals, Cardiology Clinics, Emergency Departments, Rehabilitation Centers |
| Companies Covered | AstraZeneca, Sanofi, Daiichi Sankyo Company, Novartis, Merck & Co., Inc., Pfizer Inc., Amgen Inc., Dr. Reddy's Laboratories, Serum Institute of India, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Acute Coronary Syndrome Market Strategic Shifts
Fixed-dose combination packaging is consolidating antiplatelet administration protocols across Asia-Pacific discharge workflows, while regulatory divergence and procurement centralization simultaneously reshape competitive entry dynamics.
Polymer-free drug-eluting stent technology is unifying antiproliferative delivery with reduced inflammatory response profiles. Japanese tertiary centers are transitioning from durable-polymer platforms within 18-month replacement cycles. This convergence is unifying previously separate stent and drug supply contracts into single-source purchasing agreements.
PMDA's Sakigake designation system is compressing novel antiplatelet review timelines for agents demonstrating substantial efficacy advantages over standard-of-care. Domestic sponsors gain priority consultation access that foreign entrants must replicate through Japanese partnership structures. Cardiovascular biologics with companion diagnostic components face accelerated assessment under this framework.
Hospital procurement consortia across Australia and South Korea are consolidating antiplatelet purchasing into multi-year sole-source agreements. Group purchasing organizations displace fragmented pharmacy-level contracting that previously sustained mid-tier generic suppliers. This concentration is most visible in Victoria's public hospital network, where statewide tendering collapsed twelve separate contracts into two preferred supplier arrangements.
Asia-Pacific Acute Coronary Syndrome Market Segmentation
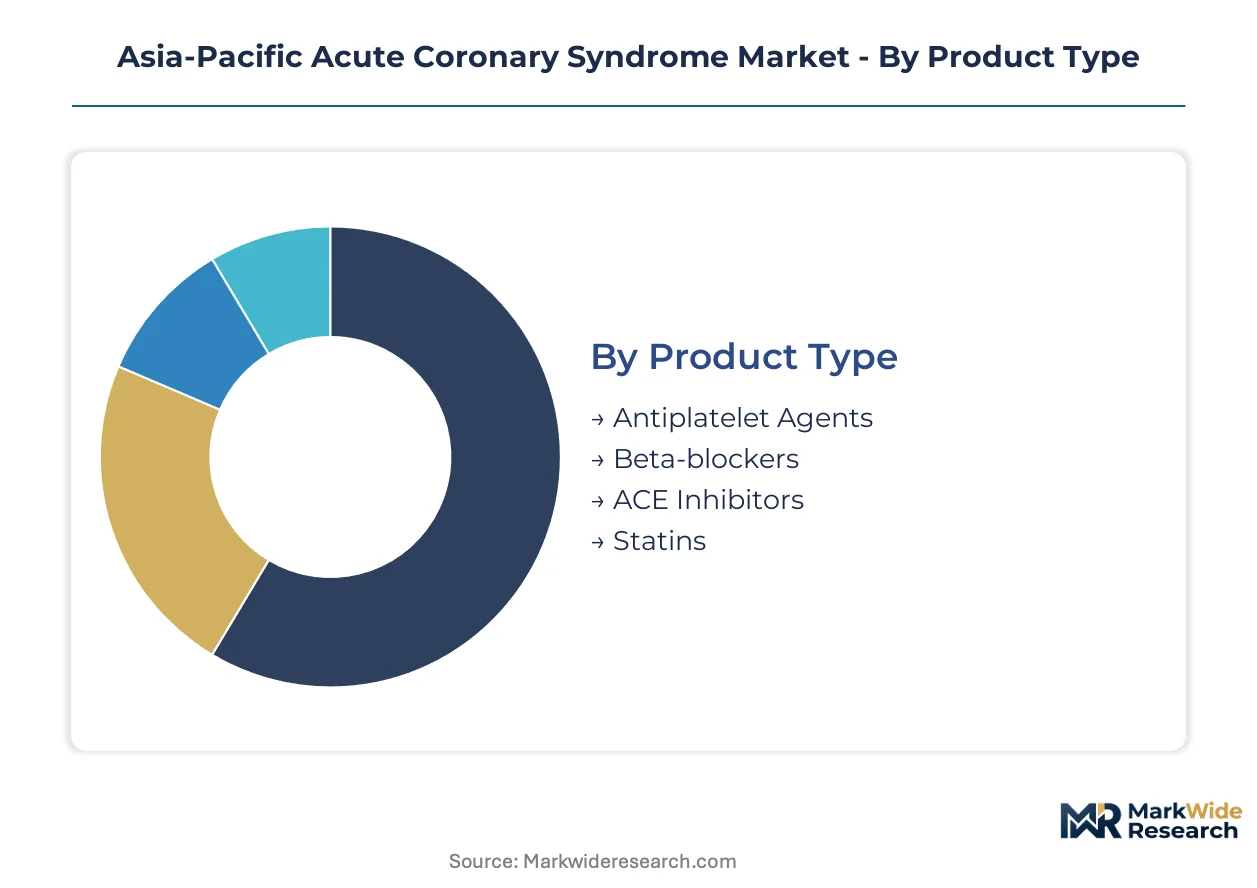
Segmentation in the Asia-Pacific Acute Coronary Syndrome Market reveals distinct capital requirements and reimbursement pathways across therapeutic modalities. Pharmaceutical manufacturers align R&D portfolios with delivery infrastructure gaps and regulatory approval velocity in target geographies.
Product Type:
Antiplatelet agents demand the heaviest upfront investment due to mandatory post-PCI continuation protocols and bioequivalence study requirements across PMDA, CDSCO, and TGA jurisdictions.
- Antiplatelet Agents:Ticagrelor and clopidogrel formulations dominate maintenance protocols following percutaneous coronary intervention. Japanese tertiary centers and Indian government hospitals concentrate procurement volume under fixed-dose combination tenders. Mandatory dual therapy continuation creates predictable revenue streams but requires sustained manufacturing scale to meet tender compliance.
- Statins:Oral atorvastatin and rosuvastatin formulations anchor long-term plaque stabilization regimens in cardiology clinics across Australia and South Korea. High-volume generic penetration in India's Ayushman Bharat network compresses margins while expanding addressable patient populations.
- Beta-blockers:Post-infarction sympathetic blockade protocols sustain demand in emergency departments and rehabilitation centers throughout Southeast Asia.
- ACE Inhibitors:Ventricular remodeling prevention drives prescription in Japanese and Australian guideline-directed medical therapy pathways.
Most installed capacity flows through antiplatelet agents. Expansion is steepest in statins as India's insurance expansion widens maintenance-phase access.
Therapy Area:
Acuity level determines reimbursement tier and treatment setting, with ST-elevation myocardial infarction commanding premium intervention rates.
- Myocardial Infarction:ST-elevation and non-ST-elevation variants drive emergency PCI volume in Japanese and South Korean catheterization laboratories. PMDA accelerated pathways compress novel antiplatelet time-to-market for infarction indications. Australian public hospital networks concentrate revascularization capacity in metropolitan referral hubs.
- Unstable Angina:Intermediate-risk stratification protocols generate diagnostic catheterization demand in India's emerging tier-2 cities. Telecardiology-linked hub-and-spoke models extend triage capacity to districts lacking on-site interventional cardiologists.
- Chest Pain:Rule-out protocols in emergency departments across Thailand and Vietnam drive rapid troponin testing and observation unit admissions.
- Revascularization:Elective PCI and coronary artery bypass grafting recovery phases sustain rehabilitation center pharmacy volumes in Australia and Japan.
Procedure volume concentrates in myocardial infarction. Unstable angina is climbing the fastest as diagnostic access expands beyond tertiary centers.
Delivery Mode:
Route selection balances therapeutic onset urgency against outpatient compliance economics across the care continuum.
- Injectable:Subcutaneous and intramuscular antiplatelet loading doses dominate emergency department protocols where minutes-to-therapy determines myocardial salvage. Cold-chain requirements constrain monoclonal biologic distribution in tropical Southeast Asian networks lacking validated storage infrastructure.
- Oral:Maintenance-phase statin and beta-blocker administration in cardiology clinics and rehabilitation centers throughout Japan and Australia favors tablet formulations with established adherence packaging.
- Intravenous:Glycoprotein IIb/IIIa inhibitor infusion in catheterization laboratories supports high-risk PCI procedures in South Korean and Indian tertiary centers.
- Sublingual:Nitroglycerin rescue dosing persists in pre-hospital and emergency department settings across the region despite limited new product development.
Patient-days concentrate in oral delivery. Injectable formats are gaining share fastest as emergency PCI capabilities deploy in secondary Southeast Asian cities.
End User:
Facility type determines procurement channel and formulary control, with hospital consortia displacing fragmented pharmacy contracting.
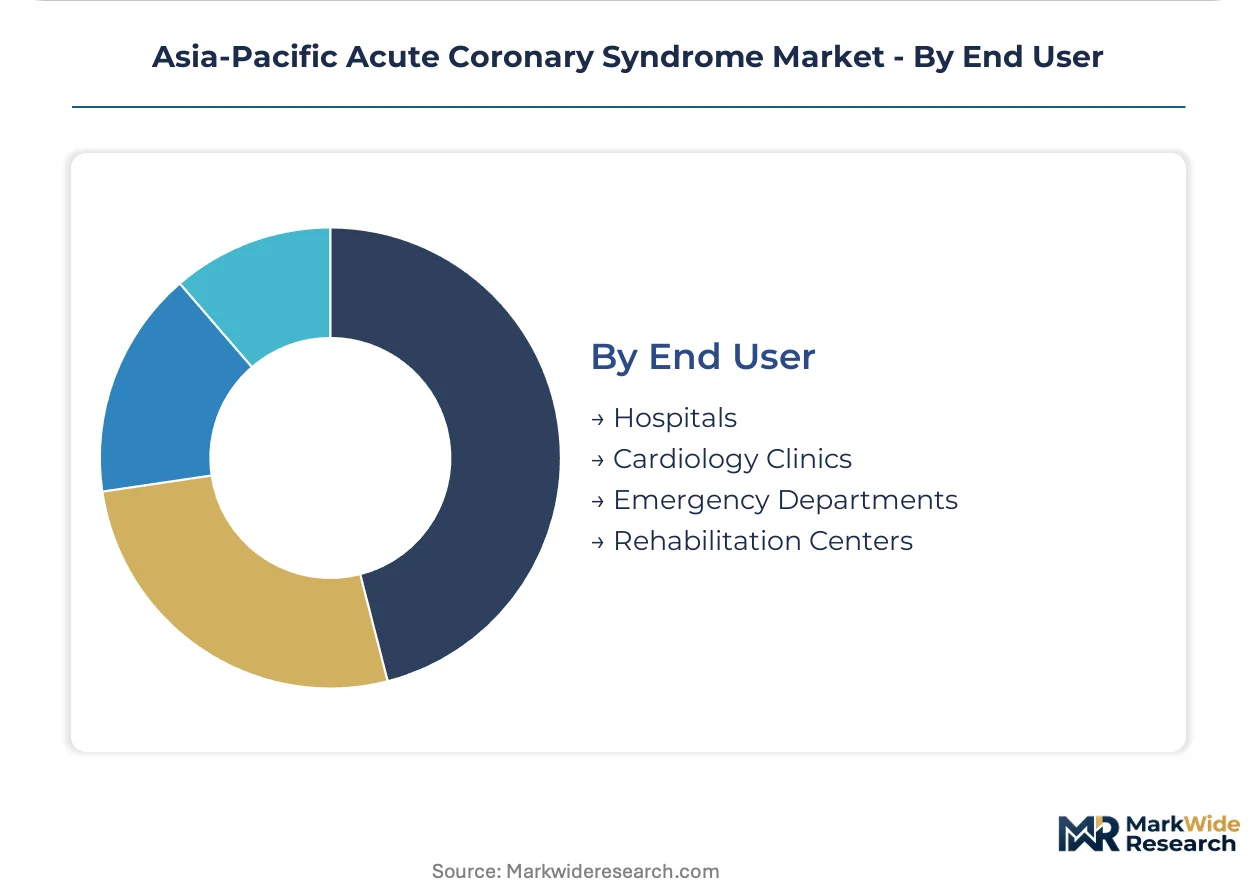
- Hospitals:Inpatient PCI and antiplatelet loading dose administration concentrate in Japanese designated cancer care hospitals and Indian government empanelled facilities. Victoria's statewide tendering collapsed twelve separate contracts into two preferred supplier arrangements, compressing mid-tier generic access.
- Cardiology Clinics:Outpatient maintenance therapy and risk factor management in Australian and South Korean private practice settings sustain oral statin and beta-blocker volumes.
- Emergency Departments:Door-to-balloon time pressures drive rapid antiplatelet initiation in Thai and Vietnamese urban referral centers expanding catheterization capabilities.
- Rehabilitation Centers:Secondary prevention program enrollment in Japanese and Australian cardiac recovery facilities extends guideline-directed medical therapy adherence monitoring.
Revenue concentration sits with hospitals. Cardiology clinics are expanding most quickly as post-PCI surveillance protocols lengthen maintenance-phase engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's pharmaceutical sector pioneered accelerated cardiovascular drug approval frameworks during the 1990s, establishing regulatory templates later adopted across Asia-Pacific. Regional demand now fragments across insurance expansion programs, catheterization infrastructure buildouts, and metabolic-tailored dosing protocols.
Japan
Kanto's tertiary cardiac centers drive antiplatelet volume through PMDA's Sakigake accelerated review system. METI coordinates domestic manufacturing incentives for active pharmaceutical ingredient reshoring. Tokyo-Osaka corridor hospitals deploy polymer-free drug-eluting stent platforms within compressed replacement cycles.
India
Ayushman Bharat insurance expansion widens percutaneous coronary intervention access to tier-2 and tier-3 cities previously dependent on out-of-pocket payment. CDSCO bioequivalence requirements for generic antiplatelet entrants sustain separate regional trial obligations. Maharashtra and Gujarat pharmaceutical clusters manufacture clopidogrel precursors for domestic formulation and regional export.
Australia
Victoria's statewide hospital procurement collapsed twelve separate antiplatelet contracts into two preferred supplier arrangements. TGA bioequivalence standards diverge from ASEAN harmonization negotiations, fragmenting registration timelines. Sydney and Melbourne metropolitan hubs concentrate emergency PCI capacity while rural telecardiology networks extend diagnostic triage.
South Korea
MFDS streamlined review pathways compress novel agent approval timelines for cardiovascular biologics. Seoul Capital Area hospital consortia consolidate purchasing into multi-year sole-source agreements. Busan-Ulsan manufacturing zones supply regional export markets with statin active pharmaceutical ingredients.
Thailand
Bangkok emergency departments expand door-to-balloon capabilities through Japanese and Korean equipment partnerships. Tropical distribution networks struggle with cold-chain integrity for temperature-sensitive monoclonal antiplatelet biologics. Secondary cities deploy hub-and-spoke telecardiology models linking district hospitals to metropolitan interventional centers.
Asia-Pacific Acute Coronary Syndrome Market Competitive Environment
Premium-margin players sit above commodity-margin players across antiplatelet formulation and fixed-dose combination packaging dimensions. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with regional manufacturing footprints, mid-scale generic specialists executing bioequivalence studies across PMDA and CDSCO jurisdictions, and domestic API suppliers captive to East Asian precursor clusters. Consolidation pressures intensify through hospital procurement centralization and tender compliance requirements. Two dominant competitive moves reshape positioning: backward integration into active pharmaceutical ingredient production and partnership structures securing PMDA priority consultation access.
Within the multinational tier, AstraZeneca and Daiichi Sankyo Company exemplify divergent strategic archetypes. AstraZeneca leverages regional manufacturing continuity for ticagrelor-based regimen supply across Asia-Pacific cardiac wards. Daiichi Sankyo Company occupies a specialization position in oral anticoagulant formulations calibrated to East Asian metabolic profiles. Novartis represents the diversified portfolio approach, spanning antiplatelet, statin, and cardiovascular biologic segments through integrated hospital contracting. These three anchors illustrate how regulatory navigation capabilities and manufacturing scale separate sustainable positioning from tender-excluded marginal suppliers.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi |
| Daiichi Sankyo Company |
| Novartis |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Dr. Reddy's Laboratories |
| Serum Institute of India |
| Others |
Value Chain & Pricing Dynamics
Interventional cardiologist concentration in Japan's Kanto corridor and India's Maharashtra-Gujarat pharmaceutical belt compresses labor-cost differentials into a three-tier pricing structure across premium, standard, and economy levels. This workforce geography separates premium fixed-dose combination tenders in Tokyo-Osaka tertiary centers from economy generic volumes in Ayushman Bharat-empanelled facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PMDA Sakigake-designated novel antiplatelets from CDSCO-approved generics and unbranded hospital procurement tenders. Price differentiation hinges on bioequivalence certification tier and manufacturing scale compliance with tender documentation requirements. Cost compression in the economy tier intensifies because India's insurance expansion funnels volume toward lowest-compliant bidders. Government hospital networks exhibit highest price sensitivity; Japanese designated cancer care hospitals demonstrate lowest sensitivity due to formulary control independence.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive monoclonal antiplatelet biologics remain underdeveloped across Southeast Asian tropical distribution networks lacking validated cold-chain infrastructure. Active pharmaceutical ingredient production concentrates in China's Zhejiang province, India's Hyderabad-Bangalore corridor, and South Korea's Busan-Ulsan manufacturing zones. Clopidogrel precursors and statin intermediates draw from these East Asian clusters. Single-source vulnerability for CYP2C19 genotype-guided antiplatelet raw materials creates supply chain risk. Distribution runs through hospital procurement consortia and government tender authorities displacing fragmented pharmacy-level contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Acute Coronary Syndrome Market represents a late-cycle quality story as procurement centralization and bioequivalence fragmentation favor sponsors with sustained manufacturing scale and regulatory navigation depth. Demand shifts toward polymer-free drug-eluting stent platforms and metabolic-tailored dosing protocols reward premium specification investment.
For Market Incumbents: Anchor manufacturing continuity through backward integration into active pharmaceutical ingredient production in Maharashtra and Gujarat pharmaceutical clusters. Secure PMDA priority consultation access through Japanese partnership structures to compress novel agent review timelines against emerging generic sponsors executing separate CDSCO regional trials. Defend tender compliance position by sustaining cold-chain validation infrastructure across tropical Southeast Asian distribution networks where temperature-sensitive biologics degrade. For New Entrants and Emerging Players: PMDA's Sakigake designation system in Japan opens a window for cardiovascular biologics with companion diagnostic components to bypass redundant bridging studies. Target rural India penetration through telecardiology-linked hub-and-spoke models enabling diagnosis in districts lacking on-site interventional cardiologists. Pursue genotype-guided antiplatelet selection protocols calibrated to East Asian CYP2C19 polymorphism prevalence as the most penetrable application segment. For Investors and Strategic Acquirers: Hospital procurement consortia are the most active acquirer in this space, consolidating antiplatelet purchasing into multi-year sole-source agreements that displace mid-tier generic suppliers. Long-term viability over the next decade favors vertically integrated manufacturers with captive API supply and regulatory dossier depth across PMDA, CDSCO, and TGA jurisdictions. Monitor ASEAN regulatory harmonization negotiations for early signals of centralized drug approval mechanisms collapsing multi-country registration into single-market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive supply of clopidogrel precursors insulates against East Asian single-source vulnerability and tender compliance requirements. |
| PMDA Sakigake Designation Pursuit | Accelerated review timelines compress novel antiplatelet time-to-market for agents demonstrating substantial efficacy advantages. |
| Telecardiology Hub-and-Spoke Deployment | Rural India penetration extends diagnostic triage to districts lacking on-site interventional cardiologists through metropolitan linkage. |
| Polymer-Free Drug-Eluting Stent Transition | Japanese tertiary centers transition platforms within compressed replacement cycles unifying stent and drug supply contracts. |
| Genotype-Guided Dosing Protocol Development | East Asian CYP2C19 polymorphism prevalence creates demand for metabolic-tailored antiplatelet selection algorithms. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital procurement managers, regulatory affairs leads at pharmaceutical sponsors, and formulary directors at Japanese designated cancer care hospitals with secondary validation against PMDA submission databases, CDSCO approval records, ClinicalTrials.gov cardiovascular trial entries, and hospital tender documentation. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing across the analysis window.
Comparable-period anchoring tied projection assumptions to historical PCI volume trajectories, antiplatelet tender award patterns, and insurance expansion enrollment curves without specifying base years. The analytical framework modeled segmentation across product type, therapy acuity, delivery mode, and end-user facility class throughout the forecast period. CAGRs derived from procedure volume elasticity to catheterization infrastructure deployment, reimbursement tier expansion, and regulatory approval velocity. Forecast inputs incorporated PMDA Sakigake pipeline progression and ASEAN harmonization negotiation status.
Revisions become necessary when regulatory approval timelines extend beyond modeled assumptions, bioequivalence standards diverge further across PMDA-CDSCO-TGA jurisdictions, or cold-chain infrastructure investments lag biologic distribution requirements. Practitioners should monitor ASEAN centralized approval mechanism negotiations, India's Ayushman Bharat empanelment expansion rates, and Japanese polymer-free stent platform adoption curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Global Statin Market
Cardiovascular
Stroke Management Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Vasculitis Market
Cardiovascular
Venous Thromboembolism Treatment Market