
 Fractional Flow Reserve Market | 2026-2036
Fractional Flow Reserve Market Size, Share, and Industry Trends Forecast 2026-2036
Fractional Flow Reserve Market Intelligence
The integration of artificial intelligence into non-invasive FFR-CT (Computed Tomography) analysis is reshaping how coronary artery disease is diagnosed and treated. This shift toward software-based assessment complements traditional invasive methods. Koninklijke Philips N.V. leverages its strong imaging portfolio to offer integrated cath lab solutions. Abbott Laboratories sustains its market position through an extensive range of pressure wires, while HeartFlow, Inc. specializes entirely in non-invasive FFR analysis from CT scans.
Fractional flow reserve provides a physiological index to assess the hemodynamic significance of coronary artery blockages. The technique involves measuring the pressure gradient across a stenosis, calculated as the ratio of distal coronary pressure (Pd) to aortic pressure (Pa) during maximum blood flow. Pressure wires remain the foundational product segment, representing a significant portion of procedural volume and recurring revenue. Within applications, the assessment of coronary artery disease dominates use cases, although post-intervention evaluation is an expanding area.
Market access and product design are governed by stringent regulatory frameworks from bodies like the US FDA, Europe's EMA, and Japan's PMDA. These agencies mandate rigorous clinical validation for both invasive wires and non-invasive software, influencing research and development timelines. Stakeholders must navigate evolving reimbursement policies and the strategic choice between investing in traditional invasive technologies versus next-generation non-invasive diagnostic platforms.
Market Dynamics
The central dynamic shaping the market is the ongoing clinical and economic re-evaluation of invasive versus non-invasive diagnostic pathways. This tension between traditional pressure wires and emergent FFR-CT software is compelling a strategic realignment across the entire value chain.
Growth Catalysts
- AI-Enhanced Diagnostics:The application of artificial intelligence to FFR-CT analysis improves the speed and accuracy of non-invasive assessments, encouraging its use as a primary screening tool for coronary artery disease before committing to invasive procedures.
- Aging Demographics:A rising prevalence of cardiovascular conditions in countries with advanced healthcare systems and aging populations, particularly Germany and Japan, sustains procedural volumes and drives demand for precise physiological assessment tools.
- Favorable Reimbursement:Evolving reimbursement frameworks in developed economies are increasingly supporting the use of physiological assessments like FFR over purely anatomical angiography, recognizing its value in guiding revascularization decisions and improving patient outcomes.
Market Restraints
- High Procedural Costs:The expense associated with single-use, high-fidelity pressure wires remains a significant barrier to wider adoption, particularly in cost-sensitive healthcare systems, limiting procedural frequency despite clinical benefits.
- Technical Limitations of FFR-CT:The accuracy of non-invasive FFR-CT is dependent on high-quality CT scans and can be compromised in patients with severe arterial calcification, prior stents, or arrhythmias, necessitating a follow-up invasive procedure.
- Stringent Regulatory Hurdles:Rigorous clinical validation mandates from regulatory bodies such as the US FDA and Japan's PMDA for both new pressure wires and software algorithms extend development timelines and increase R&D costs.
Strategic Opportunities
- Expansion in Emerging Economies:Underpenetrated markets in Southeast Asia and Latin America represent a significant growth opportunity as their healthcare infrastructure modernizes and investment in advanced cardiology centers increases.
- Post-Intervention Assessment:The application of FFR for evaluating the success of percutaneous coronary intervention (PCI) is an expanding use case, allowing clinicians to optimize stent placement and confirm hemodynamic improvement post-procedure.
- Fusion with Intravascular Imaging:Integrating FFR data with intravascular imaging technologies like IVUS or OCT offers a comprehensive anatomical and physiological assessment, creating an opportunity for hybrid guidance systems that improve procedural decision-making.
Industry Challenges
- Specialized Training Requirements:Effective use of both invasive pressure wires and non-invasive FFR-CT software requires specialized training for interventional cardiologists and radiologists, creating a skills gap that can slow technology adoption.
- Data Integration Complexity:Integrating FFR-CT analysis platforms with existing hospital IT infrastructure, including Picture Archiving and Communication Systems (PACS) and Electronic Health Records (EHR), presents a significant operational challenge for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractional Flow Reserve Market |
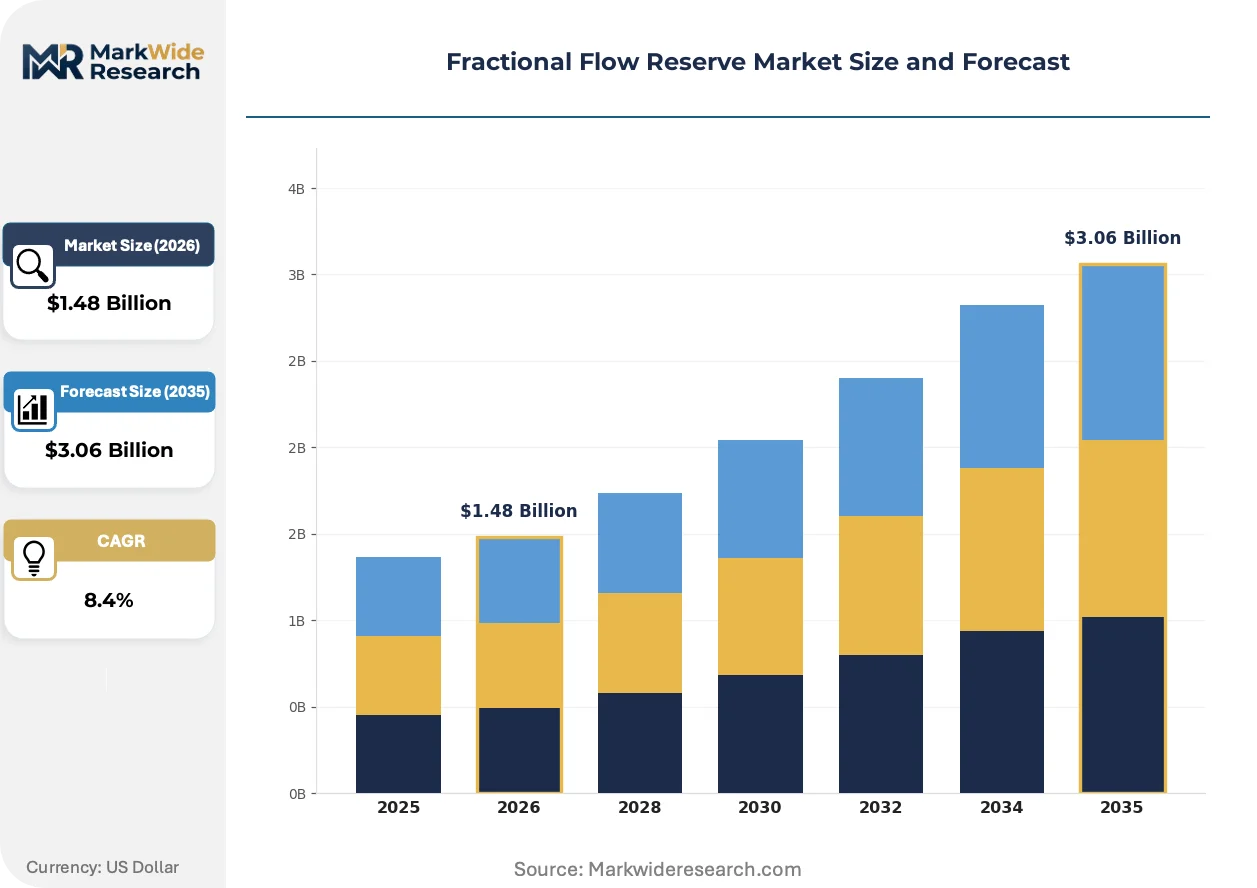
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.06 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Wires, Guiding Catheters, Imaging Systems, Software Solutions Application: Coronary Artery Disease, Cardiac Ischemia Assessment, Post-Intervention Evaluation, Peripheral Artery Disease End User: Cardiology Clinics, Diagnostic Laboratories, Cardiac Surgery Centers, Research Institutions Deployment: Hospital-Based, Ambulatory Surgical Centers, Mobile Clinics, Remote Diagnostic Services |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Koninklijke Philips N.V., Siemens Healthineers, GE HealthCare, HeartFlow, Inc., Opsens Inc., ACIST Medical Systems, CathWorks Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractional Flow Reserve Market Strategic Shifts & Innovations
The digitization of physiological assessment is the defining trend, shifting value from single-use hardware toward recurring software revenue and data-driven clinical insights. This evolution influences product design, competitive strategy, and the fundamental workflow within interventional cardiology, favoring integrated diagnostic platforms.
AI-powered analysis of computed tomography scans is the leading technological innovation. These algorithms create a 3D model of the coronary arteries and simulate blood flow to calculate FFR values non-invasively, providing a functional assessment without a catheter-based procedure. Interventional cardiology teams are adopting this technology as a gatekeeper for the cath lab, and it is virtualizing the initial diagnostic workflow for stable chest pain.
Europe's Medical Device Regulation (MDR) represents a significant regulatory shift impacting the market. The framework imposes stricter requirements for clinical evidence, risk management, and post-market surveillance on all devices, including pressure wires and diagnostic software. This increases the compliance burden for manufacturers, forcing greater investment in lifecycle data collection. Software as a Medical Device (SaMD) is especially affected, now requiring rigorous validation akin to hardware.
A prominent demand-side shift involves the bundling of FFR technologies within larger, system-level procurement contracts for catheterization labs. This model favors vendors offering integrated ecosystems that combine imaging systems, disposables like pressure wires, and analytical software into a single purchase. It displaces the practice of buying standalone components and is most visible in large hospital networks in the United States seeking to standardize care and simplify purchasing.
Fractional Flow Reserve Market Segmentation
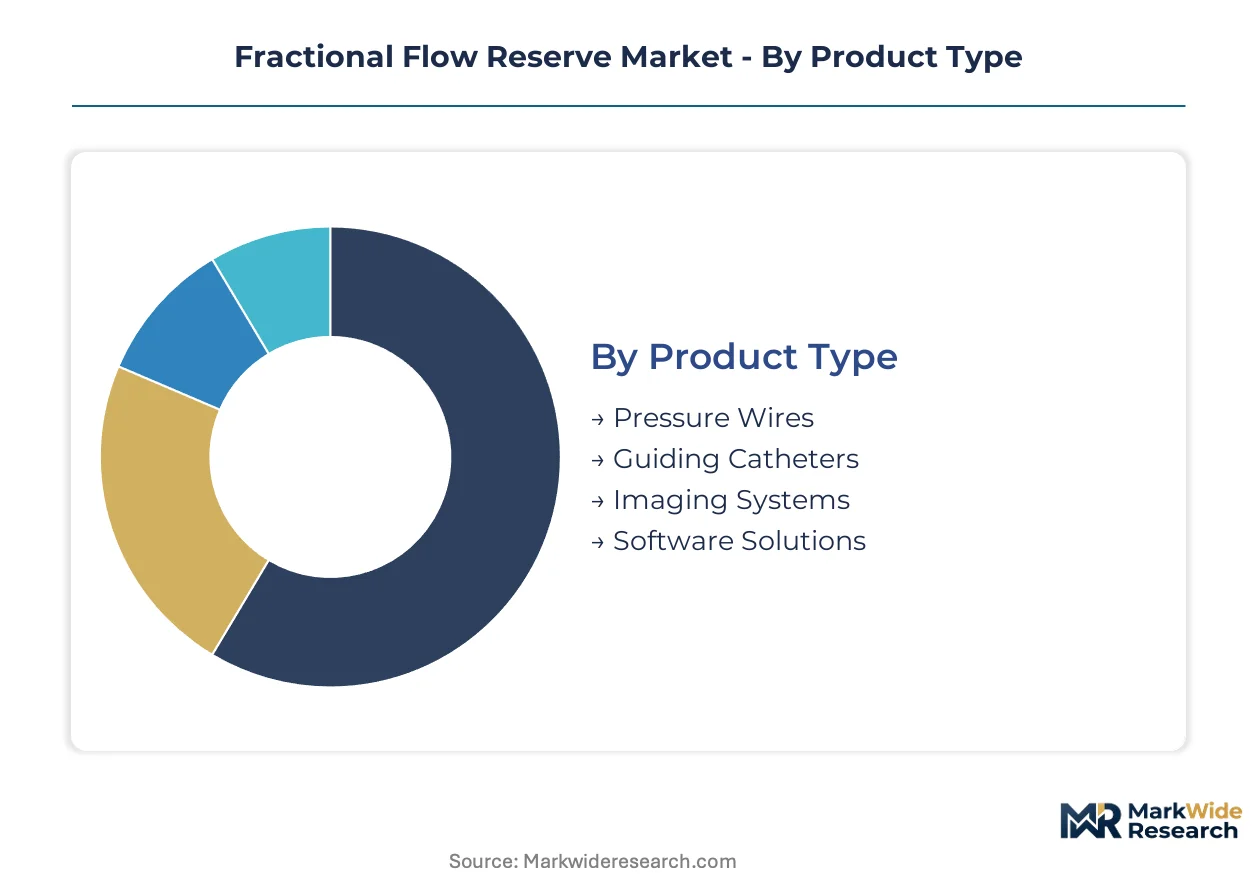
Understanding the Fractional Flow Reserve (FFR) market through segmentation provides clarity on where demand is concentrating and how technological advancements are reshaping clinical practice. This detailed breakdown highlights the diverse solutions available and the varied settings where these critical diagnostic tools are employed.
Product Type:
Product type segmentation highlights the diverse tools and platforms that enable FFR measurement and analysis, ranging from physical instruments to advanced software. This category delineates the core components required for both invasive and non-invasive assessment of coronary artery blockages.
- Pressure Wires:These single-use, high-fidelity sensors measure pressure gradients across coronary stenoses, providing a physiological index for blockage severity. Their use is foundational in cardiac catheterization labs for precise assessment before revascularization, with demand concentrated in developed economies like Germany and Japan due to established invasive cardiology practices.
- Software Solutions:These platforms leverage artificial intelligence to analyze CT scans, creating 3D coronary artery models and simulating blood flow for non-invasive FFR values. Their adoption accelerates in cardiac surgery centers seeking to optimize diagnostic workflows and reduce invasive procedures, adhering to rigorous validation from bodies like the US FDA and Europe's EMA.
- Guiding Catheters:These specialized catheters provide access and support for pressure wire delivery during invasive FFR procedures. They are essential tools within interventional cardiology for navigating complex coronary anatomies.
- Imaging Systems:These systems, including CT scanners and angiography equipment, provide anatomical context for FFR measurements. They are critical for both invasive and non-invasive FFR assessment in diagnostic laboratories.
Pressure Wires command the established base. The steepest expansion runs through Software Solutions.
Application:
The application landscape reveals where FFR technologies are clinically deployed, addressing specific diagnostic and evaluative needs within cardiovascular medicine. This segmentation illustrates the primary use cases that drive demand for both invasive and non-invasive FFR methods.
- Coronary Artery Disease:This application involves assessing the hemodynamic significance of blockages in coronary arteries to guide revascularization decisions. It represents the dominant use case for FFR technologies in cardiology clinics globally, supported by robust clinical evidence for improved patient outcomes.
- Post-Intervention Evaluation:This expanding use case involves evaluating the success of percutaneous coronary intervention (PCI) and optimizing stent placement. Demand grows as clinicians seek to confirm hemodynamic improvement and ensure optimal patient outcomes, particularly in advanced cardiology centers.
- Cardiac Ischemia Assessment:FFR is employed to determine if a coronary lesion is causing insufficient blood flow to the heart muscle. This assessment helps identify patients who will benefit most from revascularization.
- Peripheral Artery Disease:While primarily focused on coronary arteries, FFR techniques are also explored for assessing blockages in peripheral arteries. This represents a niche but potentially expanding area of application.
Assessment of coronary artery disease forms the core demand. Post-intervention evaluation is gaining significant traction.
End User:
End-user segmentation delineates the primary facilities and institutions that adopt FFR technologies, reflecting their specific infrastructure, patient populations, and clinical needs. This category highlights the diverse healthcare settings driving the market's evolution.
- Cardiology Clinics:These outpatient facilities are primary points for diagnosing and managing cardiovascular conditions, including initial assessment for FFR. They drive significant demand for both invasive and non-invasive FFR solutions to guide patient care effectively.
- Cardiac Surgery Centers:These specialized centers perform complex cardiac procedures and increasingly utilize FFR for precise ischemia assessment before surgery. Their demand concentrates on integrated cath lab solutions that combine imaging and FFR capabilities for comprehensive patient management.
- Diagnostic Laboratories:These facilities perform various tests, including FFR-CT analysis, supporting cardiology clinics and hospitals. They require sophisticated imaging and software solutions for accurate diagnostic work.
- Research Institutions:Academic and research centers utilize FFR technologies for clinical trials, developing new diagnostic algorithms, and understanding disease progression. They often drive innovation in FFR methodologies.
Cardiology clinics represent the largest patient touchpoint. Cardiac surgery centers are increasingly central to complex cases.
Deployment:
Deployment models illustrate the varied settings and operational structures through which FFR technologies are delivered to patients. This segmentation captures the evolving landscape of healthcare delivery, from traditional hospital settings to emergent remote services.
- Hospital-Based:This traditional deployment model involves FFR procedures performed within hospital catheterization labs and diagnostic departments. It remains the predominant setting for invasive FFR and complex FFR-CT analysis due to infrastructure requirements.
- Remote Diagnostic Services:This emerging model leverages FFR-CT software for off-site analysis, enabling specialists to interpret scans from various locations. Its adoption accelerates due to advancements in telemedicine and AI-powered diagnostic platforms, particularly for initial screening.
- Ambulatory Surgical Centers:These centers perform outpatient surgical procedures, including some less complex cardiac interventions. Their demand for FFR tools grows as more procedures shift from inpatient hospital settings.
- Mobile Clinics:These clinics provide healthcare services in underserved or remote areas, potentially integrating portable diagnostic tools for initial cardiovascular screenings. This deployment model is still nascent for FFR technologies.
Hospital-Based services remain the foundational delivery method. Remote Diagnostic Services are emerging as a flexible alternative.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Fractional Flow Reserve market exhibits a complex global trade dynamic, driven by both advanced technology exports and localized demand for cardiovascular diagnostics. Countries with mature healthcare systems often lead in developing and adopting sophisticated FFR solutions. This global interplay balances innovation hubs with expanding clinical needs.
United States
High prevalence of cardiovascular disease and a focus on precision medicine drive demand for FFR technologies. The US FDA mandates rigorous clinical trials for new FFR devices and software, influencing market entry. Major medical device clusters in California and Massachusetts foster continuous innovation in diagnostic platforms and integrated solutions.
Germany
An aging population and advanced healthcare infrastructure create substantial demand for precise cardiac assessment tools. Europe's MDR imposes strict compliance requirements for FFR products sold in the region, affecting development timelines. Munich and Berlin are important hubs for medical technology research and development, specializing in non-invasive diagnostics.
Japan
Rapid demographic shifts towards an older population sustain a strong need for cardiovascular health management and early diagnosis. The PMDA ensures stringent regulatory oversight for both invasive and non-invasive FFR solutions, prioritizing patient safety. Tokyo's leading medical centers are early adopters of advanced FFR-CT analysis, optimizing diagnostic workflows.
China
Expanding healthcare access and a rising middle class increase the diagnosis of coronary artery disease, boosting FFR adoption. China's NMPA is streamlining approval processes for innovative medical devices, encouraging domestic production. Shanghai and Beijing host significant investment in cardiac care infrastructure and advanced medical imaging.
India
Modernization of cardiology centers and a large patient pool contribute significantly to the market for FFR technologies. The CDSCO regulates medical devices, including FFR pressure wires and software, ensuring quality standards. Bangalore and Hyderabad are emerging as centers for healthcare technology adoption, particularly in digital health solutions.
Fractional Flow Reserve Market Key Industry Players
On the supply side, the industry is moderately consolidated with distinct specialist niches emerging within the Fractional Flow Reserve market. Established medical device manufacturers offer comprehensive cardiology portfolios, while focused innovators specialize in advanced non-invasive diagnostic software. This creates archetypes of traditional invasive hardware providers, pure-play FFR-CT software developers, and integrated cath lab solution providers. Competitive moves include portfolio diversification into non-invasive technologies and strategic partnerships to integrate AI-enhanced diagnostics.
On the premium-tier vector, Koninklijke Philips N.V. exemplifies integrated cath lab solutions, leveraging its extensive imaging portfolio to provide comprehensive diagnostic capabilities. Abbott Laboratories, a diversified medical technology corporation, anchors the traditional invasive segment with its broad range of pressure wires and supporting equipment. HeartFlow, Inc. represents a pure-play software innovator, specializing entirely in non-invasive FFR analysis derived from CT scans, driving the shift towards digital diagnostics. These companies collectively illustrate the market's strategic shift towards comprehensive and technologically advanced diagnostic offerings across different modalities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| GE HealthCare |
| HeartFlow, Inc. |
| Opsens Inc. |
| ACIST Medical Systems |
| CathWorks Ltd. |
| Others |
Cost & Logistics Intelligence
Regulatory validation bottlenecks, particularly from the US FDA and Europe's MDR, determine both FFR product pricing tier spreads and the global supply chain shape for certified medical devices. These frameworks impose significant development costs on both invasive pressure wires and non-invasive software.
Pricing Analysis
The pricing gap between established invasive FFR hardware and advanced non-invasive software defines market value. The market operates on a hybrid pricing model, combining per-unit transactional costs for pressure wires with SaaS-tiered subscriptions for AI-powered FFR-CT analysis. Price differentiation stems from rigorous clinical validation levels and seamless integration with existing cath lab infrastructure. Pricing softness affects traditional pressure wires due to emerging non-invasive alternatives, with cost-sensitive healthcare systems exhibiting higher price sensitivity than advanced cardiology centers.
Supply Chain Analysis
Export control regimes for advanced medical device components limit the free flow of specialized FFR technology. Supply concentration for high-fidelity sensors and advanced imaging processors centers in Germany, Japan, and the United States. The industry relies on a few key manufacturers for critical raw materials and specialized software algorithms, creating single-source vulnerability. Distribution runs through direct sales channels to large hospital networks and cardiology clinics, complemented by regional medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fractional Flow Reserve market's rapid evolution is a capability-scarcity story, particularly concerning advanced AI development and integration expertise for non-invasive diagnostics. This talent gap limits the speed of innovation and broader clinical adoption.
For Market Incumbents: Harden core invasive FFR franchises by integrating advanced AI capabilities into existing cath lab solutions. Invest heavily in software R&D or acquire pure-play FFR-CT developers to counter disruption from digital-native competitors. Deepen vertical integration of software with imaging systems to maintain control over the diagnostic workflow. Prioritize certification investment in next-generation non-invasive platforms to meet US FDA and Europe's EMA requirements.
For New Entrants and Emerging Players: Establish a beachhead in the remote diagnostic services segment, leveraging AI-powered FFR-CT analysis platforms. Target underpenetrated markets in Southeast Asia and Latin America where healthcare infrastructure is modernizing. Focus on niche applications like post-intervention evaluation to demonstrate unique value proposition. Partner with large hospital networks to facilitate seamless data integration with existing PACS and EHR systems.
For Investors and Strategic Acquirers: The market sits at a growth acceleration phase that favors agile software innovators with proven clinical validation. Long-term viability remains strong, driven by global aging demographics and technological advancements in non-invasive diagnostics. Identify mid-cap software companies possessing strong AI intellectual property and established regulatory clearances as prime acquisition targets. The signal to watch is the expansion of favorable reimbursement policies for non-invasive FFR-CT across developed economies.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development | Enhances FFR-CT accuracy and workflow efficiency for clinicians. |
| Regulatory Pathway Acceleration | Reduces time-to-market for novel FFR technologies, increasing patient access. |
| Integrated Cath Lab Solutions | Simplifies procurement and standardizes care across hospital networks. |
| Tele-Diagnostic Platform Rollout | Expands FFR-CT accessibility to remote areas and underserved patient populations. |
| Pressure Wire Miniaturization | Minimizes invasiveness and improves patient comfort during procedures. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary validation. Conversations included interventional cardiologists, hospital procurement leads, medical device engineers, and regulatory affairs specialists. Secondary data sources comprised US FDA filings, EMA clinical trial databases, industry association reports, and peer-reviewed academic publications. This approach ensured robust bottom-up and top-down triangulation of market insights.
Forecast inputs considered include historical market performance, technological adoption curves, and evolving reimbursement landscapes across the analysis window. The analytical framework modeled segmentation dimensions by product type, application, end-user, deployment, and regional healthcare spending. Compound Annual Growth Rates were derived from a synthesis of historical trends, expert consensus, and projected clinical integration rates. Key industry-specific inputs involved the global prevalence of coronary artery disease and FFR-CT adoption rates.
Macroeconomic conditions sit as an overlay; deviation in healthcare budget allocations or R&D investment would shift the trajectory over the forecast period. The analysis reflects current regulatory frameworks and clinical practice guidelines. Material shifts in medical device approval or reimbursement policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Chronic Heart Failure Market