
 Unstable Angina Therapeutics Market | 2026-2036
Unstable Angina Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Unstable Angina Therapeutics Market Analytics
Next-generation antiplatelet potency tiers are unwinding older generic-dominated protocols across emergency cardiology units. Pfizer leverages its manufacturing scale to sustain supply continuity for high-volume beta blocker formulations. AstraZeneca anchors its position through R&D intensity in dual antithrombotic pathways. Sanofi competes on geographic dominance in European hospital formulary access.
Unstable angina therapeutics comprise pharmaceutical agents and procedural adjuncts that prevent thrombus propagation, reduce myocardial oxygen demand, and stabilize coronary plaques in patients presenting with acute chest pain without biomarker elevation. These interventions typically target platelet aggregation thresholds below 50% inhibition, blood pressure reduction to systolic targets below 140 mmHg, and LDL cholesterol suppression below 70 mg/dL to forestall progression to myocardial infarction. Antiplatelet agents occupy the largest margin pool due to mandatory peri-procedural loading doses and maintenance requirements. Antithrombotic agents represent the fastest-growing therapeutic class as direct oral anticoagulants displace parenteral heparin protocols in transitional care settings. Hospital end users concentrate procurement leverage through cardiovascular service line integration and episode-based reimbursement contracts.
The US FDA and EMA govern approval pathways for antithrombotic combinations, with the FDA's Division of Cardiovascular and Renal Products demanding mortality outcome data for label expansion beyond acute settings. The EU MDR intensifies post-market surveillance for Class III cardiac devices used in revascularization adjunct therapy, raising compliance costs for device-drug combination approaches. Stakeholders must monitor how CMS's expanding bundled payment models for acute myocardial infarction episodes reshape drug selection incentives within hospital formularies.
Market Dynamics
Hospital cardiovascular service line consolidation is compressing procurement autonomy as integrated delivery networks centralize formulary decisions across multiple acute care sites.
Growth Catalysts
- CMS bundled payment expansion:Medicare's episode-based reimbursement models for acute myocardial infarction episodes incentivize protocol standardization around high-efficacy antithrombotic combinations in United States hospital systems.
- Dual antiplatelet therapy protocols:Emergency cardiology units are adopting intensified platelet inhibition regimens for percutaneous coronary intervention support, driving volume through catheterization laboratories.
- Direct oral anticoagulant transition:Parenteral heparin protocols in transitional care settings are giving way to oral alternatives that simplify discharge planning and reduce nursing burden.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for clopidogrel and ticagrelor concentrates in Chinese and Indian chemical clusters, exposing formulators to geopolitical disruption risk.
- FDA mortality endpoint requirements:The Division of Cardiovascular and Renal Products demands hard outcome data for label expansion beyond acute settings, extending trial timelines and development costs.
- Generic antiplatelet erosion:Patent expiration on foundational P2Y12 inhibitors has collapsed pricing power for maintenance dose regimens in outpatient settings.
Strategic Opportunities
- EU MDR device-drug combinations:Class III cardiac device regulations are creating compliance barriers that favor established pharmaceutical-device integrators with post-market surveillance infrastructure.
- Rural hospital network penetration:Underserved United States regions with expanding critical access hospital designations represent untapped volume for telecardiology-supported acute coronary syndrome protocols.
- Pharmacogenomic-guided dosing:CYP2C19 variant testing integration with antiplatelet selection protocols offers differentiation in high-risk patient stratification.
Industry Challenges
- Specialized interventional cardiology staffing:Catheterization laboratory nurse and technician shortages constrain procedure throughput and protocol adherence in community hospital settings.
- Multinational trial recruitment complexity:Divergent EMA and FDA endpoint expectations fragment clinical development programs and delay regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unstable Angina Therapeutics Market |
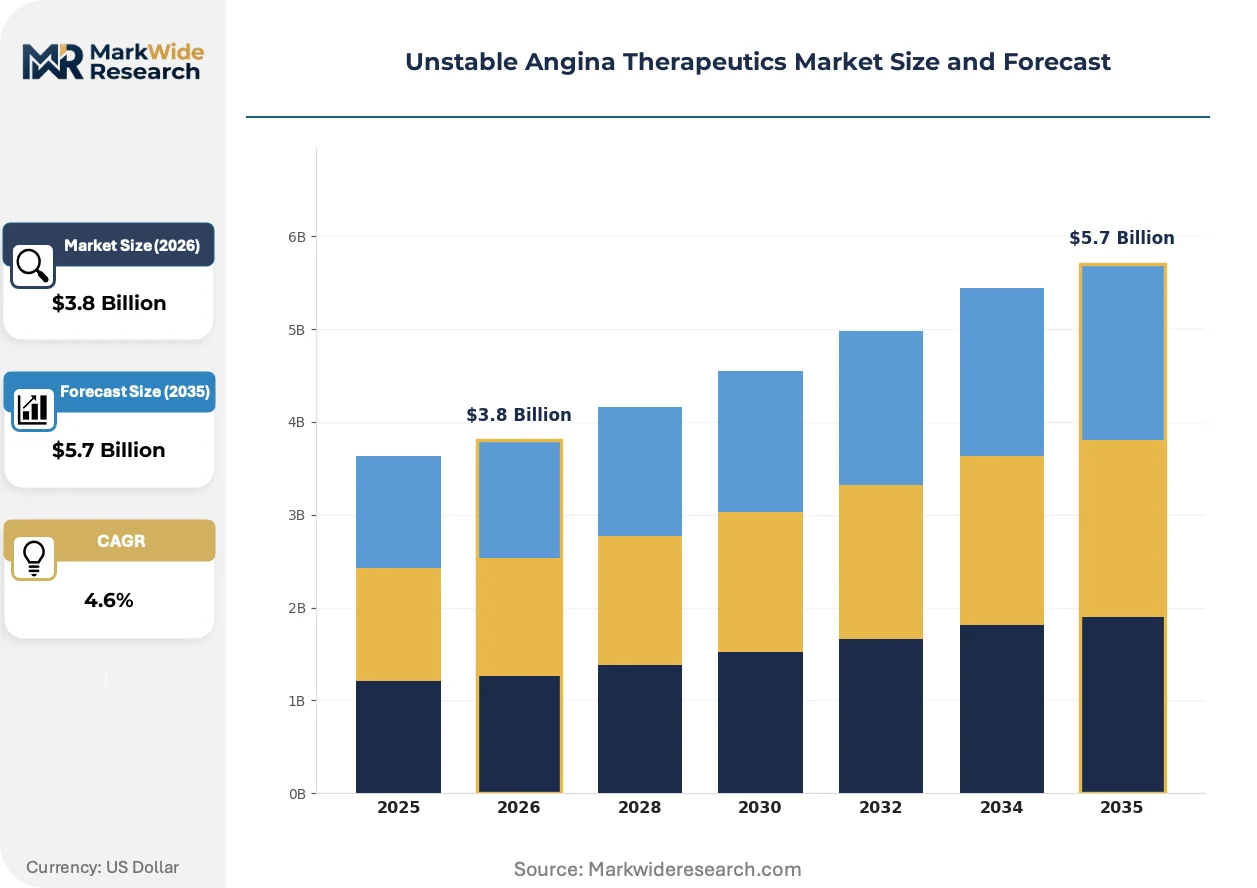
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiplatelet Agents, Beta Blockers, ACE Inhibitors, Statins Therapeutic Class: Antithrombotic Agents, Antianginal Medications, Pharmacological Interventions, Revascularization Therapies Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Home Care Settings, Long-term Care Facilities |
| Companies Covered | Pfizer, Novartis AG, AstraZeneca, F. Hoffmann-La Roche Ltd, Abbott, Sanofi, Bayer AG, Gilead Sciences, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unstable Angina Therapeutics Market Evolving Landscape
Antithrombotic therapy development is pivoting toward precision dosing algorithms and real-time monitoring integration that reduce bleeding complications while maintaining ischemic protection.
Direct oral anticoagulants with rapid onset and offset kinetics are displacing unfractionated heparin in transitional care pathways. Hospitalist services managing acute coronary syndrome patients post-catheterization are adopting these agents to streamline same-day discharge protocols. This shift is compressing pharmacy inventory requirements and reducing nursing administration burden in step-down units.
The EU MDR intensifies post-market surveillance obligations for Class III cardiac devices used in revascularization adjunct therapy. Device-drug combination manufacturers face elevated compliance costs and extended notified body review timelines. European hospital procurement committees are consolidating supplier relationships to reduce vendor qualification overhead.
Episode-based reimbursement contracts are reshaping how United States cardiovascular service lines evaluate therapeutic value. Hospital pharmacy and therapeutics committees now prioritize agents with demonstrated readmission reduction over acquisition cost minimization. This recalibration is most visible in Medicare Advantage–dominated markets where downside risk contracts concentrate financial accountability.
Unstable Angina Therapeutics Market Segmentation
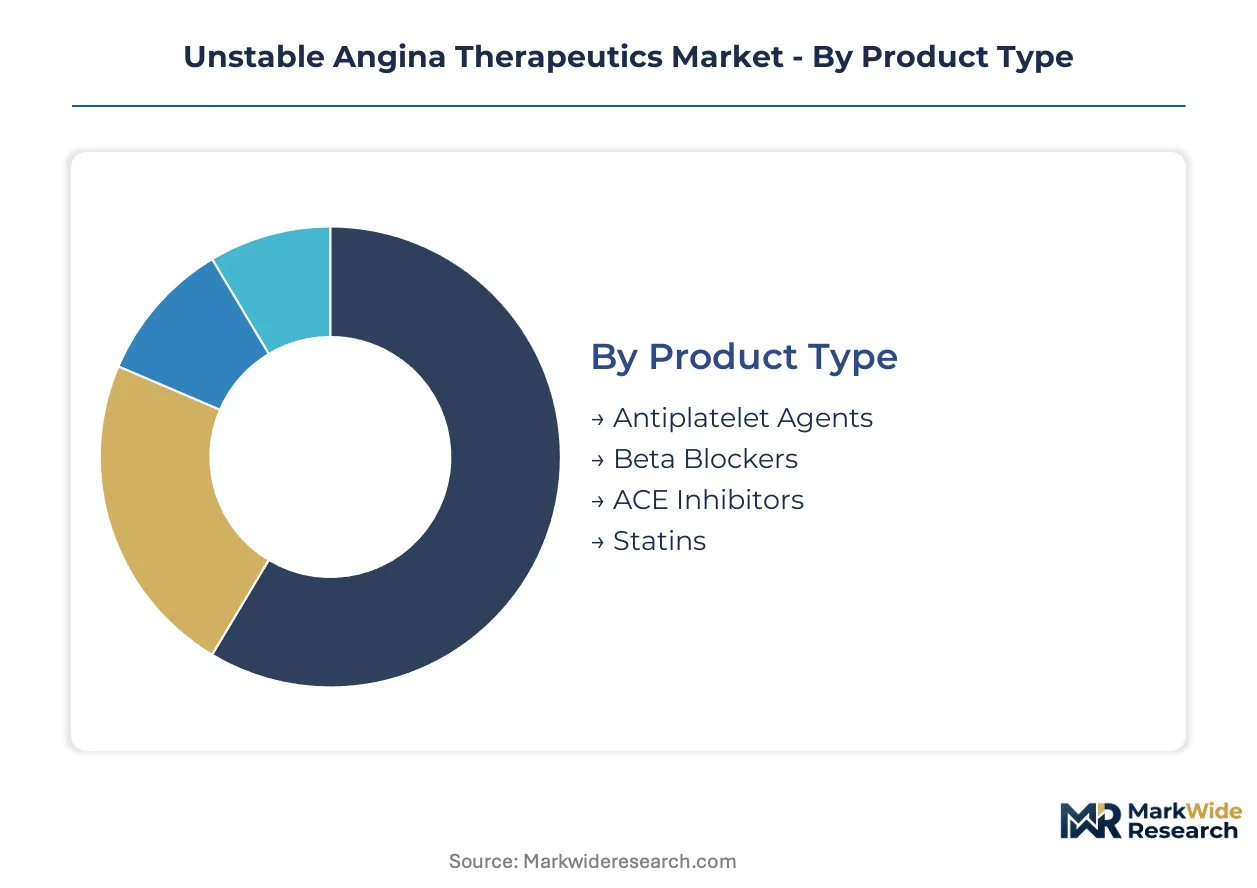
Segmentation in unstable angina therapeutics reveals how procurement leverage concentrates around acute care settings while outpatient transitions reshape administration preferences. Pharmaceutical manufacturers calibrate portfolio investments across these dimensions to align with episode-based reimbursement incentives and formulary consolidation trends.
Product Type:
Antiplatelet agents face the most intense substitution pressure from next-generation P2Y12 inhibitors and pharmacogenomic-guided alternatives that challenge legacy generic protocols.
- Antiplatelet Agents:These agents inhibit platelet aggregation through P2Y12 receptor blockade and cyclooxygenase-1 inhibition, with ticagrelor and prasugrel formulations displacing clopidogrel in high-risk catheterization laboratory protocols across United States cardiovascular networks. Demand concentrates in hospital-based acute coronary care units where peri-procedural loading doses drive volume, though generic erosion compresses maintenance dose margins in outpatient settings.
- Beta Blockers:Cardioselective and non-selective formulations reduce myocardial oxygen demand through heart rate and contractility suppression, with extended-release metoprolol and carvedilol dominating emergency department initiation protocols. United States integrated delivery networks standardize on specific formulations to reduce pharmacy inventory complexity under bundled payment contracts.
- ACE Inhibitors:These agents interrupt the renin-angiotensin-aldosterone system to reduce afterload and prevent ventricular remodeling in post-acute coronary syndrome patients.
- Statins:High-intensity lipid-lowering agents target LDL cholesterol suppression below 70 mg/dL per cardiology society guidelines.
Antiplatelet agents anchor the volume base while beta blockers gain share at the steepest rate through protocol standardization in catheterization laboratory workflows.
Therapeutic Class:
Cost tier differentiation separates acute inpatient interventions from transitional care protocols that bridge hospital discharge to outpatient management.
- Antithrombotic Agents:Direct oral anticoagulants and parenteral heparin derivatives prevent thrombus propagation through factor Xa and direct thrombin inhibition, with apixaban and rivaroxaban formulations displacing unfractionated heparin in United States hospitalist step-down units. Demand is climbing the fastest as same-day discharge protocols simplify nursing administration and reduce pharmacy inventory burden.
- Antianginal Medications:Nitrates, calcium channel blockers, and ranolazine reduce ischemic symptoms through coronary vasodilation and metabolic modulation.
- Pharmacological Interventions:Combination protocols integrate antiplatelet, anticoagulant, antihypertensive, and lipid-lowering agents into standardized order sets.
- Revascularization Therapies:These procedural adjuncts support percutaneous coronary intervention through antithrombotic loading and glycoprotein IIb/IIIa inhibition.
Antithrombotic agents command premium positioning through clinical trial differentiation while pharmacological interventions absorb volume through protocol bundling.
Administration Route:
Volume concentration favors oral formulations that enable discharge planning efficiency, while intravenous routes retain critical role in emergency stabilization.
- Oral:Tablet and capsule formulations of antiplatelet agents, beta blockers, and statins dominate maintenance therapy and discharge prescribing, with United States Medicare Advantage networks prioritizing agents with once-daily dosing to improve adherence metrics under star rating programs.
- Intravenous:Infusion-based anticoagulation and glycoprotein IIb/IIIa inhibition provide rapid onset for emergency catheterization laboratory procedures.
- Subcutaneous:Low-molecular-weight heparin and fondaparinux support bridging therapy in transitional care settings.
- Intramuscular:This route sees limited application in acute coronary syndrome protocols due to absorption variability concerns.
Oral administration anchors the volume base through outpatient conversion while intravenous routes defend position in emergency stabilization workflows.
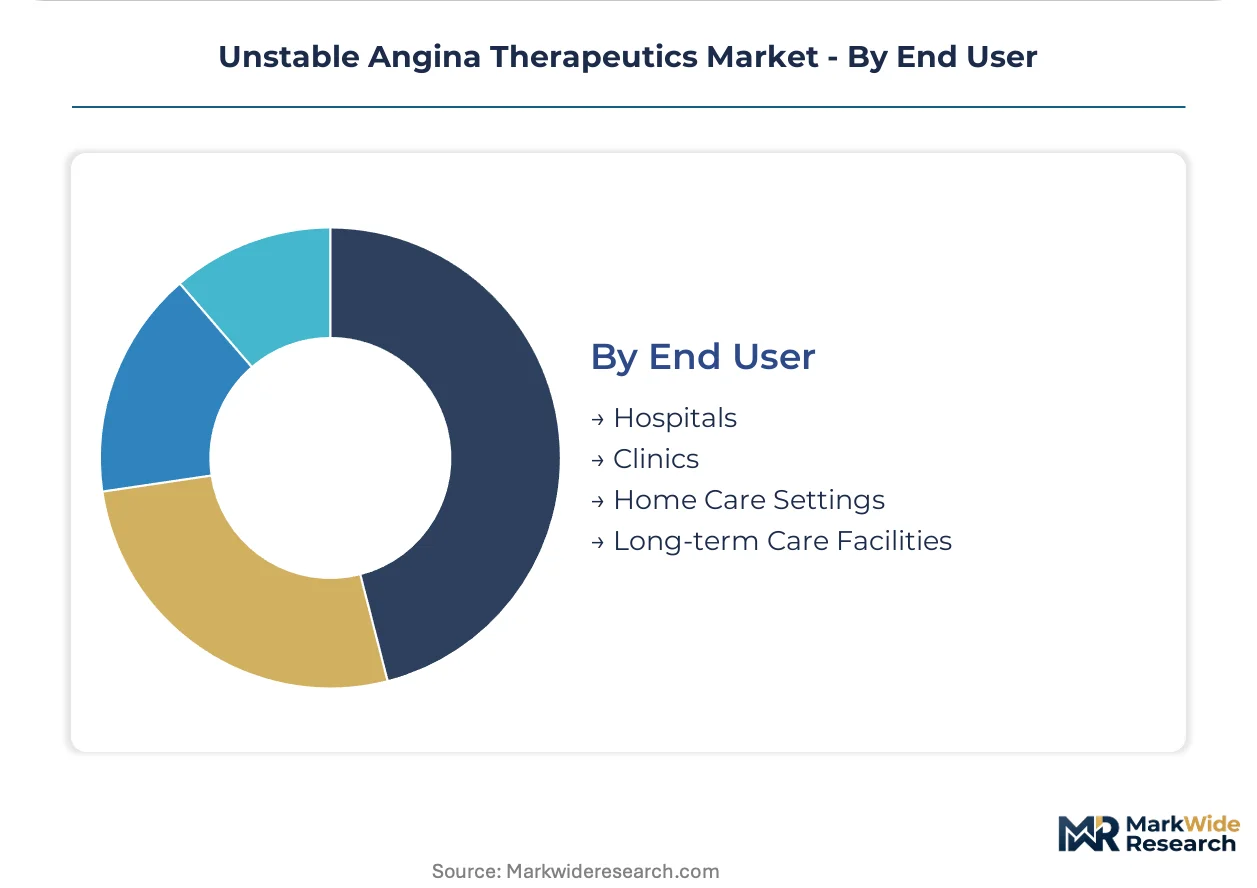
End User:
Customer type fragmentation concentrates purchasing power in hospital systems while home care expansion creates new channel complexity.
- Hospitals:Acute care facilities with catheterization laboratories and cardiovascular service lines drive procurement volume through integrated delivery network consolidation, with United States health systems centralizing formulary decisions across multiple sites to leverage scale in antithrombotic contract negotiations.
- Clinics:Outpatient cardiology practices manage post-discharge medication titration and adherence monitoring.
- Home Care Settings:These channels support early discharge protocols through nursing administration of subcutaneous anticoagulation.
- Long-term Care Facilities:Skilled nursing facilities manage antiplatelet and antihypertensive therapy in post-acute coronary syndrome rehabilitation patients.
Hospitals anchor the volume base through episode-based reimbursement concentration while home care settings expand most quickly through same-day discharge protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical trade flows in cardiovascular therapeutics tilt toward import dependence in emerging markets while established manufacturing clusters in the United States, Germany, and Switzerland anchor export capacity. Active pharmaceutical ingredient sourcing concentrates in Asian chemical hubs, creating cross-border supply vulnerabilities that shape regional procurement strategies.
United States
Medicare bundled payment models for acute myocardial infarction episodes drive hospital formulary consolidation toward high-efficacy antithrombotic combinations. FDA Division of Cardiovascular and Renal Products demands mortality outcome data for label expansions beyond acute settings. Integrated delivery networks in the Northeast and Midwest centralize purchasing decisions across multi-site cardiovascular service lines.
Germany
Hospital cardiovascular service line integration accelerates under Diagnosis-Related Group reimbursement pressure, favoring protocol standardization around dual antiplatelet therapies. EMA centralized procedures for antithrombotic combinations streamline multi-national market access from Frankfurt and Amsterdam regulatory hubs. The Rhine-Ruhr and Bavarian hospital networks concentrate procurement leverage for beta blocker and statin formulations.
Japan
PMDA accelerated approval pathways for cardiovascular drugs support rapid adoption of next-generation P2Y12 inhibitors in catheterization laboratory protocols. METI pharmaceutical industry policies incentivize domestic manufacturing resilience for critical antiplatelet APIs. The Kanto region around Tokyo anchors demand concentration through dense academic medical center networks managing acute coronary syndrome volumes.
India
CDSCO regulatory harmonization with ICH guidelines facilitates faster market entry for imported antithrombotic innovations while domestic generic manufacturers supply clopidogrel and metoprolol across price-sensitive hospital segments. Government hospital procurement through centralized tenders in Maharashtra and Karnataka drives volume concentration for essential cardiovascular medicines. The Hyderabad-Visakhapatnam pharmaceutical cluster expands API synthesis capacity for beta blocker intermediates.
China
NMPA priority review pathways for cardiovascular innovations accelerate market access for novel anticoagulants in tier-one hospital catheterization laboratories. National centralized procurement volume-based purchasing collapses pricing for generic antiplatelet agents while creating volume guarantees for selected manufacturers. The Yangtze River Delta pharmaceutical corridor concentrates formulation capacity for high-volume beta blocker and statin exports.
Unstable Angina Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across R&D intensity and manufacturing scale dimensions. The market structure tilts toward consolidation among large-cap pharmaceutical firms with cardiovascular franchises, while mid-tier specialists carve positions in pharmacogenomic-guided dosing and device-drug combinations. Three archetypes dominate: integrated multinationals with hospital formulary relationships, biotech innovators with precision medicine platforms, and generic manufacturers with API backward integration. Competitive moves center on cardiovascular service line partnership contracts and dual antithrombotic pathway patent extensions.
Within the integrated multinational tier, Pfizer, AstraZeneca, and Sanofi exemplify divergent strategic positioning. Pfizer anchors scale-driven supply continuity for high-volume cardiovascular formulations across United States hospital networks. AstraZeneca occupies the R&D-intensive vector through dual antithrombotic pathway development. Sanofi represents geographic dominance archetypes with European hospital formulary access concentration. Each firm navigates CMS bundled payment incentives and EMA MDR compliance costs through differentiated capability investments.
| Leading Market Players |
|---|
| Pfizer |
| Novartis AG |
| AstraZeneca |
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Sanofi |
| Bayer AG |
| Gilead Sciences |
| Bristol Myers Squibb |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory buffers for antiplatelet APIs now govern procurement negotiations between United States hospital networks and generic formulators, compressing margin structures as integrated delivery networks centralize purchasing leverage across multi-site cardiovascular service lines. This lead-time compression concentrates pricing power with manufacturers possessing captive synthesis capacity for clopidogrel and ticagrelor intermediates.
Pricing Analysis
Hospital procurement committees anchor antithrombotic pricing through episode-based reimbursement contracts that prioritize readmission reduction metrics over acquisition cost minimization. Three-tier pricing structure across premium, standard, and economy levels separates next-generation P2Y12 inhibitors from generic clopidogrel and economy-tier beta blocker formulations. Cost compression in maintenance dose regimens is intensifying because patent expiration on foundational antiplatelet agents has collapsed outpatient pricing power. Medicare Advantage networks exhibit highest price sensitivity due to star rating program adherence penalties, while academic medical centers demonstrate lowest sensitivity through research funding offsets.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes have extended API delivery windows for United States formulators sourcing from Indian and Chinese chemical clusters. Active pharmaceutical ingredient manufacturing for cardiovascular therapeutics concentrates in Hyderabad-Visakhapatnam, the Yangtze River Delta, and Ahmedabad chemical corridors. Raw material dependencies span acetone derivatives for beta blocker synthesis, pyridine intermediates for antiplatelet agents, and heparin crude sourced from porcine intestinal mucosa. Single-source vulnerability in heparin starting material creates structural exposure to livestock disease outbreaks. Distribution runs through pharmaceutical wholesale distributors with cold-chain capabilities serving hospital formularies and outpatient pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cardiovascular service line consolidation as integrated delivery networks in the United States centralize formulary decisions across multi-site acute care systems.
For Market Incumbents: Secure backward integration into API synthesis for clopidogrel and ticagrelor to defend margin position against generic erosion in outpatient maintenance dose markets. Lock in multi-year supply agreements with Hyderabad and Yangtze River Delta chemical manufacturers to mitigate geopolitical disruption risk. Deepen hospital formulary relationships through pharmacogenomic-guided dosing platform investments that differentiate beyond commodity antiplatelet offerings. For New Entrants and Emerging Players: Lead with pharmacogenomic testing integration targeting critical access hospitals in rural United States regions lacking interventional cardiology staffing. Penetrate the transitional care antithrombotic segment where direct oral anticoagulant adoption is displacing parenteral heparin protocols. Deploy telecardiology-supported acute coronary syndrome protocols as the primary go-to-market angle to overcome catheterization laboratory infrastructure gaps. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cardiovascular service line integration will compress vendor counts to three-to-five preferred suppliers per integrated delivery network. Target acquisition profiles center on device-drug combination specialists with EU MDR post-market surveillance infrastructure and pharmacogenomic platform capabilities. Watch CMS bundled payment model expansion into additional acute coronary syndrome episode types as the signal for formulary consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Mortality endpoint data satisfies FDA Division of Cardiovascular and Renal Products requirements for label expansion beyond acute settings. |
| Regulatory Approval Pathway | EU MDR Class III device-drug combination compliance creates barriers favoring established integrators with surveillance infrastructure. |
| Manufacturing Scale-Up | Captive API synthesis capacity insulates formulators from geopolitical disruption in Indian and Chinese chemical clusters. |
| Hospital System Partnership | Episode-based reimbursement contracts with integrated delivery networks lock in volume through cardiovascular service line integration. |
| Pipeline Diversification | Pharmacogenomic-guided dosing platforms differentiate beyond commodity antiplatelet agents in high-risk patient stratification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases through bottom-up and top-down triangulation. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists inform therapeutic protocol adoption patterns. Secondary validation draws from CMS Medicare data, GPO contracts, and cardiovascular society guideline publications to cross-check demand assumptions.
Segmentation dimensions modeled span product type, therapeutic class, administration route, and end user across the projection horizon. Treatment line positioning, dosage form preferences, and regional regulatory clusters further stratify volume and value outputs. CAGRs derive from patient volume epidemiology, procedure growth in catheterization laboratories, and protocol substitution rates for next-generation antithrombotic agents. Forecast inputs incorporate FDA approval pathway timelines, EU MDR compliance cost trajectories, and CMS bundled payment expansion assumptions.
Forecasts assume regulatory continuity in FDA and EMA antithrombotic approval frameworks; material policy shifts would require re-modeling. Supply disruption scenarios in Asian API manufacturing clusters, interventional cardiology staffing shortages, and divergent mortality endpoint expectations between regulators constitute specific revision triggers. Practitioners should keep alternative scenarios live as integrated delivery network consolidation and pharmacogenomic testing adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Angina Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Vasculitis Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Antihypertensive Market