
 North America Acute Coronary Syndrome Market | 2026-2036
North America Acute Coronary Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acute Coronary Syndrome Market Analytics
Aftermarket service revenue for angiography systems is fragmenting as hospitals extend equipment lifecycles and negotiate performance-based maintenance contracts. AstraZeneca leverages its antiplatelet portfolio to anchor hospital formularies across major US health systems. Pfizer Inc. competes through integrated cardiovascular care pathways that bundle diagnostics with therapeutic protocols.
Acute coronary syndrome encompasses a spectrum of clinical conditions including unstable angina and myocardial infarction arising from sudden coronary artery occlusion, typically diagnosed through elevated cardiac troponin levels and electrocardiographic changes requiring immediate revascularization. The condition demands rapid therapeutic intervention to restore coronary perfusion and limit myocardial necrosis. Stent-based interventions dominate procedural volumes while pharmacological therapy sustains recurring revenue through chronic anticoagulant and antiplatelet regimens. Hospitals capture the largest share of end-user spending, though ambulatory surgical centers are gaining structural importance as same-day percutaneous coronary intervention protocols expand.
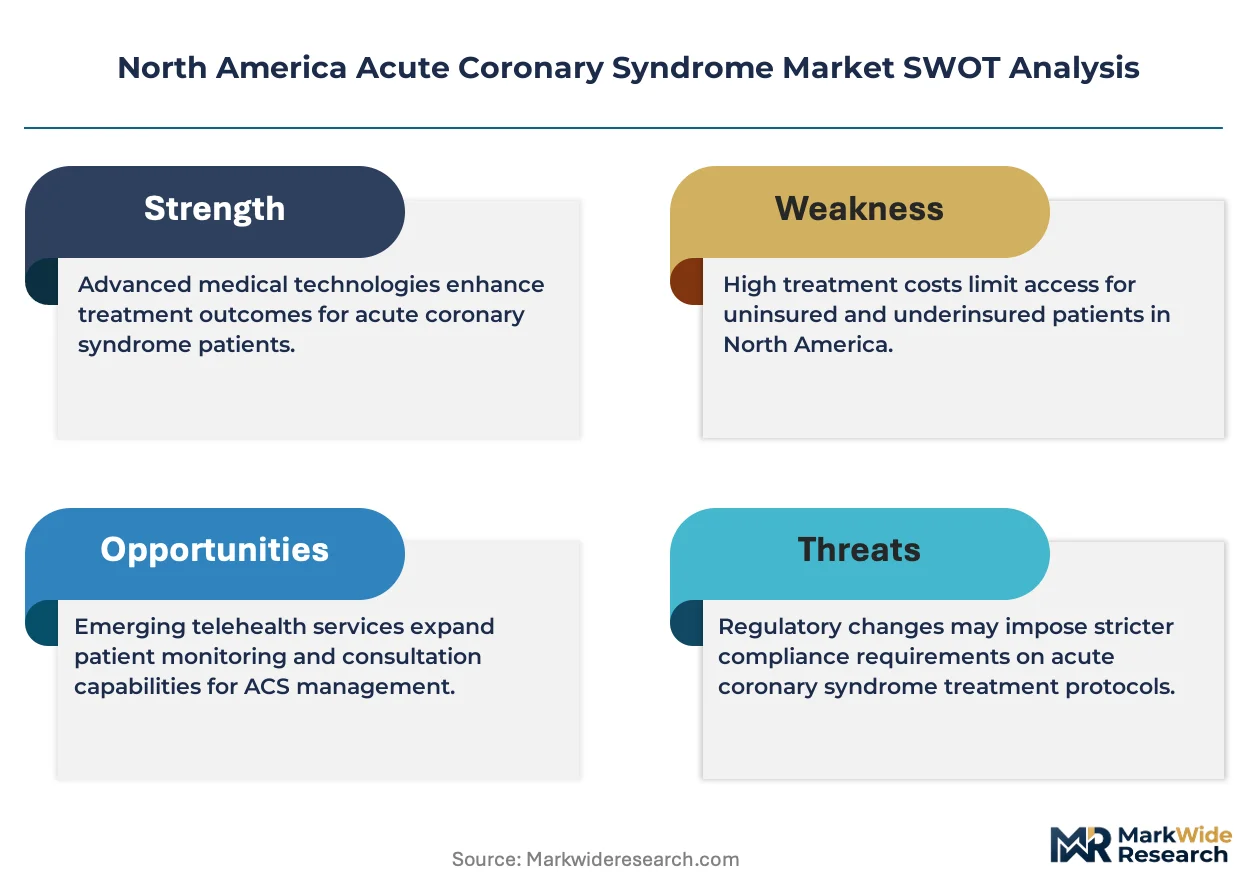
FDA premarket review pathways and CMS national coverage determinations shape device commercialization timelines and reimbursement thresholds for new interventional technologies. The EPA regulates sterilization emissions from cardiac catheterization labs, influencing capital equipment specifications. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled coronary imaging and state-level certificate-of-need regulations that constrain cath lab expansion.
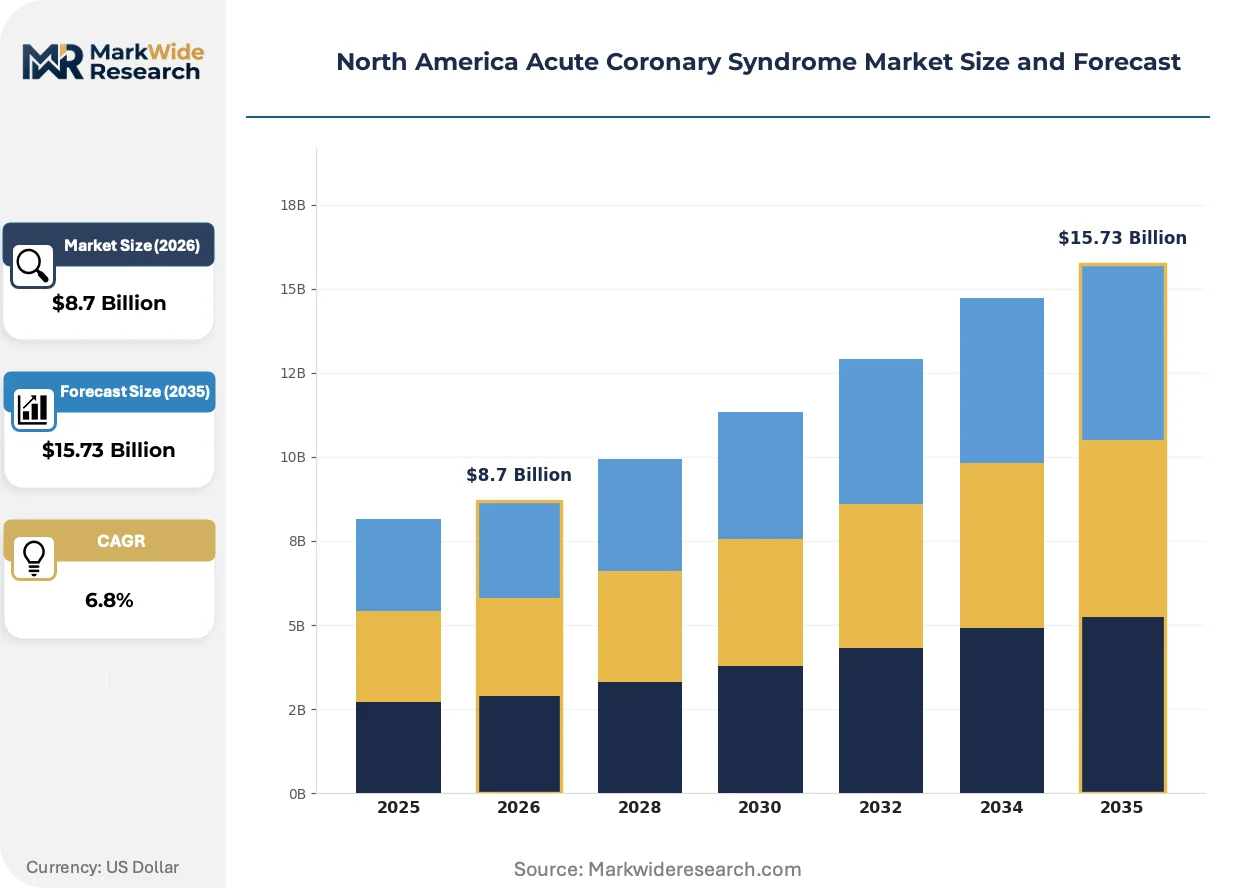
Market Dynamics
Minimally invasive revascularization is consolidating procedural economics around transcatheter platforms, compressing open-surgical volumes and redirecting capital allocation toward cath lab infrastructure across US and Canadian hospital systems.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated premarket review for coronary imaging AI and robotic-assisted PCI systems compresses commercialization timelines for device developers targeting US tertiary centers.
- CMS Transcatheter Reimbursement Updates:National coverage determinations for same-day discharge PCI protocols expand site-of-service migration toward ambulatory surgical centers in high-volume US markets.
- US Northeast Corridor Clustering:Patient volume concentration and research infrastructure density in Boston, New York, and Philadelphia metropolitan areas concentrate clinical trial access and early adoption curves.
Market Restraints
- Certificate-of-Need Regulations:State-level CON laws in 35 US jurisdictions constrain cath lab expansion and shield incumbent providers from competitive entry.
- Sterilization Emissions Compliance:EPA regulations on ethylene oxide and vaporized hydrogen peroxide emissions from cardiac catheterization labs force capital equipment retrofits and operational workflow changes.
- Antiplatelet Generic Erosion:Patent expirations on P2Y12 inhibitors compress pharmaceutical revenue per patient episode and shift formulary leverage toward integrated device-drug bundles.
Strategic Opportunities
- Canadian Provincial Expansion:Underpenetrated interventional cardiology programs in Alberta and British Columbia offer first-mover positioning for US-trained physician networks and equipment vendors.
- AI-Enabled Coronary Imaging:FDA draft guidance on machine learning-based FFR-CT and intravascular ultrasound analysis creates regulatory clarity for algorithm developers seeking 510(k) clearance.
- Performance-Based Maintenance Contracts:Extended equipment lifecycles and outcome-linked service agreements are displacing traditional time-and-materials aftermarket revenue models for angiography system vendors.
Industry Challenges
- Interventional Cardiologist Pipeline:Fellowship training slot constraints and geographic maldistribution between academic medical centers and community hospitals limit procedural capacity expansion.
- Legacy EHR Integration:AI-enabled imaging platforms face interoperability friction with entrenched electronic health record systems from Epic and Cerner, delaying clinical workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acute Coronary Syndrome Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Bypass Equipment, Angiography Systems, Catheters End User: Hospitals, Cardiac Centers, Clinics, Ambulatory Surgical Centers Delivery Mode: Intravenous, Oral, Transdermal, Invasive Treatment Type: Pharmacological Therapy, Surgical Intervention, Lifestyle Modification, Rehabilitation |
| Companies Covered | AstraZeneca, Pfizer Inc., Sanofi, Johnson & Johnson Service Inc., Amgen Inc., Novartis AG, Merck & Co., Inc., Daiichi Sankyo Company, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acute Coronary Syndrome Market Evolving Landscape
Transcatheter coronary intervention is absorbing adjacent diagnostic and therapeutic modalities, collapsing the traditional separation between imaging, revascularization, and chronic disease management into unified care pathways.
Intravascular lithotripsy is hybridizing calcium modification with standard PCI workflow, enabling treatment of heavily calcified lesions previously relegated to coronary artery bypass grafting. US tertiary centers with high-volume complex PCI programs are adopting the technology at accelerating cadence. The convergence is compressing referral patterns for surgical revascularization and redistributing procedural economics toward hybrid cath lab suites.
FDA guidance on artificial intelligence-enabled coronary imaging is reshaping premarket submission requirements for machine learning-based FFR-CT algorithms and automated plaque characterization tools. The regulatory clarity is accelerating 510(k) clearance timelines for developers with robust training datasets. Device manufacturers are responding by embedding algorithmic modules directly into angiography system software stacks rather than pursuing standalone diagnostic approvals.
Hospital procurement committees are consolidating vendor relationships around integrated cardiovascular care platforms that bundle diagnostic equipment, interventional devices, and chronic therapy protocols into single-source contracts. The purchasing pattern is displacing point-solution vendors and favoring diversified manufacturers with cross-portfolio negotiation leverage. This concentration is most visible in US integrated delivery networks with centralized supply chain authority over multiple hospital campuses.
North America Acute Coronary Syndrome Market Segmentation
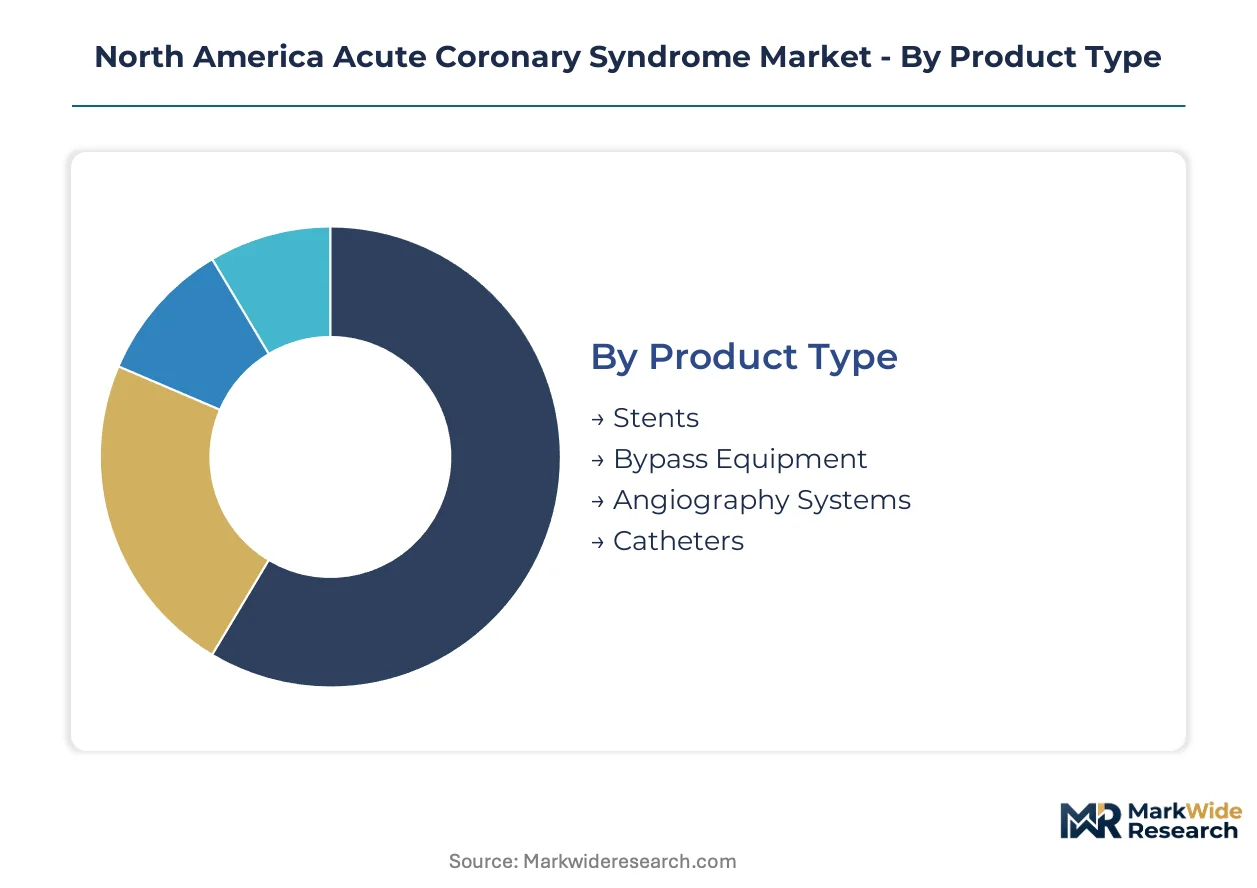
Segmentation in the North America Acute Coronary Syndrome market reveals distinct procurement patterns across device categories and care settings. Hospital administrators and cath lab directors allocate capital budgets differently depending on whether investments target immediate revascularization capacity or chronic disease management infrastructure.
Product Type:
Mature stent platforms dominate installed base volumes while emerging robotic-assisted delivery systems reshape capital allocation priorities across US health systems.
- Stents:Drug-eluting and bare-metal platforms constitute the procedural core of interventional cardiology programs across tertiary centers. Demand concentrates in US Northeast corridor hospitals where complex PCI volumes justify dedicated inventory management systems and physician preference item negotiations.
- Bypass Equipment:Cardiopulmonary bypass machines and ancillary perfusion systems support hybrid OR-cath lab configurations. Adoption is accelerating in Texas and Florida health systems expanding structural heart programs alongside traditional coronary interventions.
- Angiography Systems:Flat-panel detector systems with rotational angiography capability anchor diagnostic workflow in high-volume centers.
- Catheters:Guiding catheters, balloon catheters, and microcatheters enable lesion access across the PCI procedural spectrum.
Stents retain volume leadership; angiography systems hold the steepest expansion curve as AI-enabled imaging modules drive replacement cycles.
End User:
Cost tier stratification separates capital-intensive tertiary infrastructure from lean ambulatory models migrating same-day PCI protocols.
- Hospitals:Academic medical centers and community hospital systems capture the majority of ACS episode spending through bundled payment arrangements. Patient volume concentrates in metropolitan statistical areas with certificate-of-need constraints protecting incumbent cath lab operators from competitive entry.
- Cardiac Centers:Dedicated cardiovascular specialty facilities unbundle interventional services from general hospital overhead. Expansion is climbing the fastest in Arizona and North Carolina markets where physician-owned entities exploit regulatory arbitrage between hospital outpatient department and ambulatory surgical center reimbursement.
- Clinics:Diagnostic and pre-procedural evaluation sites feed referral networks toward intervention-capable facilities.
- Ambulatory Surgical Centers:Same-day discharge PCI protocols are gaining structural importance in Medicare Advantage-dominant markets.
Hospitals retain volume leadership; ambulatory surgical centers hold the steepest expansion curve as site-of-service migration accelerates.
Delivery Mode:
Application urgency distinguishes acute invasive interventions from chronic oral maintenance regimens in the ACS care continuum.
- Intravenous:Anticoagulant and antiplatelet loading doses administered in emergency department and cath lab settings achieve rapid therapeutic levels. Demand concentrates in US trauma centers and STEMI-receiving hospitals where door-to-balloon time metrics drive formulary standardization.
- Oral:Chronic P2Y12 inhibitor and statin maintenance therapy sustains recurring pharmaceutical revenue per patient episode. Prescription volume is expanding most quickly through integrated delivery network specialty pharmacies capturing 90-day refill compliance.
- Transdermal:Nitroglycerin patches and alternative delivery mechanisms support outpatient angina management.
- Invasive:Intracoronary and intravenous procedural delivery encompasses contrast media, thrombolytics, and device-based therapies.
Oral delivery retains volume leadership; invasive delivery holds the steepest expansion curve as transcatheter platforms absorb adjacent therapeutic modalities.
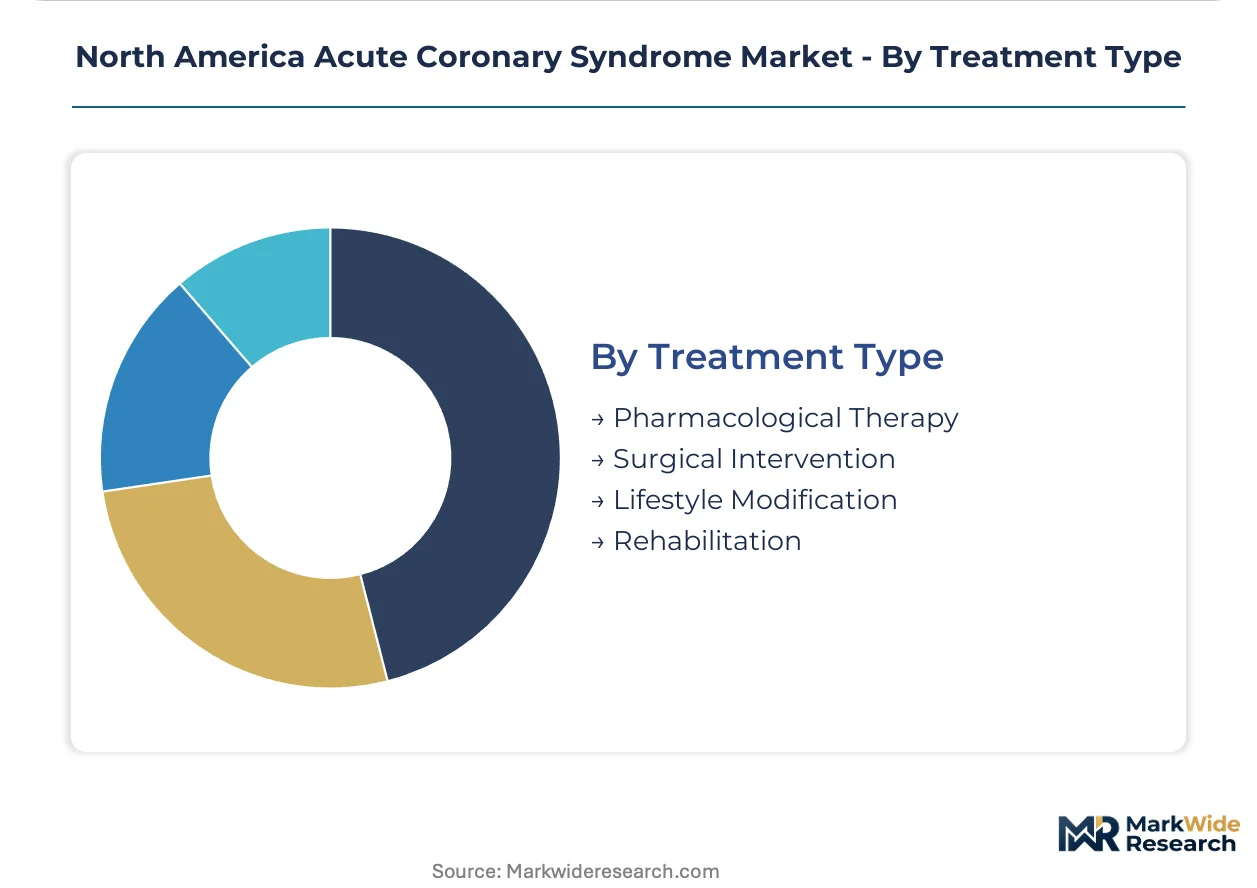
Treatment Type:
Customer type segmentation separates acute procedural revenue from longitudinal chronic disease management contracts.
- Pharmacological Therapy:Antiplatelet, anticoagulant, beta-blocker, and statin protocols constitute the foundational layer of ACS management across all care settings. Formulary control concentrates in US integrated delivery networks where AstraZeneca and generic manufacturers compete for hospital contract anchoring.
- Surgical Intervention:Percutaneous coronary intervention and coronary artery bypass grafting represent the procedural revenue core. Procedure volume is gaining share fastest in hybrid OR-cath lab suites enabling single-episode revascularization decisions without inter-facility transfer.
- Lifestyle Modification:Cardiac rehabilitation and risk factor management programs support readmission reduction metrics.
- Rehabilitation:Phase II and III cardiac rehab services extend episode value through Medicare-covered structured exercise.
Pharmacological therapy retains volume leadership; surgical intervention holds the steepest expansion curve as transcatheter platforms displace open surgical volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes acute coronary syndrome interventions through tertiary hospital networks and expanding ambulatory surgical centers, while Canada deploys similar technologies through provincial health authorities with tighter capital constraints and longer equipment replacement cycles.
United States
FDA breakthrough device designations for robotic-assisted PCI systems and AI-enabled coronary imaging accelerate commercialization timelines for developers targeting high-volume cath labs. CMS national coverage determinations for same-day discharge protocols reshape site-of-service economics toward ambulatory settings. The US Northeast corridor—anchored by Boston, New York, and Philadelphia metropolitan areas—concentrates patient volumes, research infrastructure, and early adoption curves for transcatheter innovations.
Canada
Provincial health authorities in Alberta and British Columbia underinvest in interventional cardiology capacity relative to population need, creating first-mover positioning for US-trained physician networks. Health Canada regulatory pathways align with FDA precedents but introduce timing lags for device approvals. Toronto's University Health Network and Vancouver Coastal Health anchor complex PCI referral patterns, while Prairie provinces rely on inter-facility transfers for surgical revascularization.
Mexico
Private hospital chains in Mexico City and Monterrey drive demand for drug-eluting stents and diagnostic angiography systems through out-of-pocket payment and medical tourism channels. COFEPRIS regulatory timelines for cardiovascular devices lag US FDA approvals by 18-24 months, segmenting market access between premium private tiers and constrained public sector procurement. Guadalajara's Hospital Civil and Mexico City's Instituto Nacional de Cardiología concentrate academic research capacity.
North America Acute Coronary Syndrome Market Competitive Landscape
Capability concentration sits with diversified pharmaceutical-device conglomerates; scale advantage sits with integrated delivery network contractors. The North America ACS market structures around three tiers: antiplatelet formulary anchors, interventional device platforms, and hybrid care pathway integrators. Consolidation pressures favor players with cross-portfolio negotiation leverage over point-solution vendors. Dominant competitive moves include hospital system sole-source contracting and performance-based maintenance agreements for capital equipment.
Within the pharmaceutical anchor tier, AstraZeneca and Pfizer Inc. exemplify formulary control strategies across major US health systems. Among diversified cardiovascular platforms, Johnson & Johnson Service Inc. occupies a position spanning interventional devices and surgical equipment. These three companies represent distinct archetypes: patent-protected drug portfolio dominance, integrated diagnostic-therapeutic bundling, and diversified medtech scale.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer Inc. |
| Sanofi |
| Johnson & Johnson Service Inc. |
| Amgen Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| Daiichi Sankyo Company |
| Boehringer Ingelheim |
| Others |
Value Network & Pricing Analysis
Undercapacity in Canadian cath lab infrastructure relative to population-adjusted procedural demand concentrates pricing power with incumbent US equipment vendors while forcing provincial buyers toward extended equipment lifecycles and performance-based service negotiations. This utilization asymmetry between supply-constrained Canadian markets and capacity-saturated US Northeast corridors creates divergent procurement postures across the North American landscape.
Pricing Analysis
Long-term offtake contracts dominate capital equipment procurement for angiography systems and robotic PCI platforms, with US integrated delivery networks leveraging multi-hospital volume commitments against vendor list pricing. Price differentiation stems from FDA breakthrough designation tiering and bundled service-inclusion levels, with premium configurations capturing formulary anchoring at academic medical centers. Cost compression in mid-tier community hospital segments is intensifying because generic antiplatelet erosion compresses pharmaceutical margins and redirects procurement leverage toward device-drug bundles. Medicare Advantage plans exhibit highest price sensitivity through site-of-service arbitrage, while cash-pay medical tourism channels in Mexican private hospitals show lowest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration for coronary stent platforms sits with specialized EMS providers in Costa Rica and Ireland serving FDA-regulated markets, while angiography system assembly anchors in Germany and Japan. Raw material dependencies span nitinol tubing from US specialty mills, drug-eluting polymer coatings from Swiss chemical suppliers, and flat-panel detector sensors from South Korean semiconductor foundries. Single-source vulnerability in robotic PCI catheter production creates supply chain risk given limited qualified manufacturing sites. Distribution runs through hospital procurement committees and group purchasing organizations, with direct-to-cath-lab logistics displacing traditional distributor networks for high-value devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device designations for AI-enabled coronary imaging and robotic-assisted PCI systems constitute a regulatory inflection accelerating commercialization timelines and reshaping competitive positioning across the North American acute coronary syndrome landscape.
For Market Incumbents: Build regulatory data moats through expanded clinical trial footprints in US Northeast corridor academic medical centers, securing physician preference item status before generic device competition intensifies. Deepen backward integration into AI algorithm development to capture recurring software revenue streams and displace standalone diagnostic vendors from angiography system stacks. For New Entrants and Emerging Players: Alberta and British Columbia provincial health authorities represent the most penetrable geography, where underinvestment in interventional cardiology capacity creates first-mover positioning for US-trained physician networks and equipment vendors targeting hybrid OR-cath lab configurations. Pursue direct hospital system partnerships bypassing established GPO contracts through outcome-guaranteed service models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-integrated diagnostic platform developers with embedded software modules in angiography systems, offering SaaS-like margin profiles within capital equipment markets. Acquisition targets should demonstrate Health Canada regulatory progress or established CMS reimbursement codes. Watch FDA draft guidance finalization on machine learning-based FFR-CT as the signal indicating algorithm commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated premarket review compresses commercialization timelines for coronary imaging AI developers. |
| Hospital System Partnership | Sole-source contracting with integrated delivery networks displaces point-solution vendors from formulary access. |
| Software Companion Development | Embedded algorithmic modules in angiography stacks capture recurring revenue from hardware installations. |
| Reimbursement Strategy | CMS national coverage determinations for same-day discharge protocols reshape site-of-service economics. |
| Geographic Expansion | Canadian provincial market entry exploits capacity constraints and longer equipment replacement cycles. |
Research Methodology
The analysis maps stent platforms, angiography systems, and robotic-assisted PCI devices, each validated through cath lab directors, hospital procurement managers, and interventional cardiologists across tertiary centers and community hospital systems. Primary fieldwork combined structured interviews with biomedical engineers and GPO contracts managers, cross-referenced against FDA 510(k) filings, CMS national coverage determinations, and hospital procurement databases. Bottom-up equipment installation tracking and top-down pharmaceutical formulary spend analysis were triangulated to validate market sizing.
Assumptions held fixed include FDA regulatory pathway timelines and CMS reimbursement parity between hospital outpatient departments and ambulatory surgical centers, while variables included provincial health authority capital budget cycles and generic antiplatelet erosion rates. Segmentation modeling spanned product type, end-user setting, delivery mode, and treatment type across the projection horizon. CAGRs were derived from procedural volume trajectories and equipment replacement cycle analysis, incorporating Health Canada approval lag assumptions and certificate-of-need constraint intensity by state jurisdiction.
Practitioners should monitor FDA guidance finalization on AI-enabled coronary imaging and state-level certificate-of-need repeal initiatives for early signals requiring forecast revision. Cross-checking against CMS Medicare cost report data on cath lab procedure volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Tachycardia Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Pericarditis Treatment Market