
 Disk Space Analyzer Software Market | 2026-2036
Disk Space Analyzer Software Market Size, Share, and Industry Trends Forecast 2026-2036
Disk Space Analyzer Software Market Insights
Modular bundling of disk space analyzers with broader systems management suites is expanding buyer choice beyond standalone procurement. TreeSize leverages deep Windows ecosystem integration to sustain enterprise loyalty. WizTree competes on raw scanning speed, differentiating through its NTFS Master File Table reading architecture. DaisyDisk anchors creative-sector demand with visual-first design that occupies a distinct premium position against utilitarian alternatives.
Disk space analyzer software comprises utilities that map storage consumption through file system traversal, visualization rendering, and policy-based cleanup automation, typically supporting NTFS, APFS, ext4, and cloud object storage protocols. These tools serve commercial and industrial users by identifying redundant data, optimizing tiered storage costs, and enforcing retention compliance. Integrated Solutions lead revenue contribution as vendors embed visualization engines within endpoint management and backup platforms, while Cloud Services represent the fastest-expanding deployment vector as organizations distribute storage across multi-provider environments. Subscription-Based pricing captures the dominant margin pool by converting episodic license renewals into predictable recurring revenue.
FDA 21 CFR Part 11 requirements for electronic records in life sciences, GDPR data minimization mandates in Europe, and Japan's METI cybersecurity guidelines for critical infrastructure collectively shape product roadmaps toward audit logging, access controls, and encrypted reporting. ISO 27001 certification has become a de facto market access threshold for vendors serving regulated industries. Stakeholders must evaluate whether their current tooling provides sufficient API connectivity to feed storage analytics into centralized SIEM and governance platforms.
Market Dynamics
Multi-cloud storage sprawl is forcing enterprise IT departments to deploy visualization tools that federate analytics across AWS, Azure, and Google Cloud object stores from a single console.
Growth Catalysts
- GDPR data minimization mandates:European organizations must systematically audit storage to demonstrate compliance with Article 5 retention limitations, driving systematic deployment of mapping tools.
- Healthcare data retention:FDA 21 CFR Part 11 requirements for electronic records in life sciences necessitate immutable audit trails of storage access and deletion events.
- NTFS Master File Table acceleration:Direct MFT reading architectures reduce scan times from hours to seconds, eliminating the productivity penalty that previously suppressed enterprise adoption.
Market Restraints
- Cloud API fragmentation:Proprietary metadata schemas across AWS S3, Azure Blob, and Google Cloud Storage force vendors to maintain costly adapter layers that inflate development overhead.
- Substitution by native tooling:Cloud providers bundle basic storage analytics at no marginal cost, compressing pricing power for third-party visualization suites.
- Skills concentration:Expertise in file system internals and kernel-level optimization clusters in Germany, the United States, and Japan, limiting vendor hiring pools elsewhere.
Strategic Opportunities
- India's data localization push:RBI and MEITY mandates for domestic data storage create demand for analyzers that map compliance boundaries across hybrid architectures.
- SIEM convergence:Integration of storage telemetry with Splunk, Datadog, and Elastic Security platforms opens new procurement budgets outside traditional IT operations.
- Container-native deployment:Kubernetes operators for ephemeral storage analysis address DevOps teams managing stateful workloads at scale.
Industry Challenges
- Legacy mainframe integration:IBM z/OS and Fujitsu BS2000 environments resist standard file system APIs, requiring costly custom engineering for unified visibility.
- ISO 27001 certification timelines:Six-to-twelve-month audit cycles delay vendor entry into regulated financial services and defense procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disk Space Analyzer Software Market |
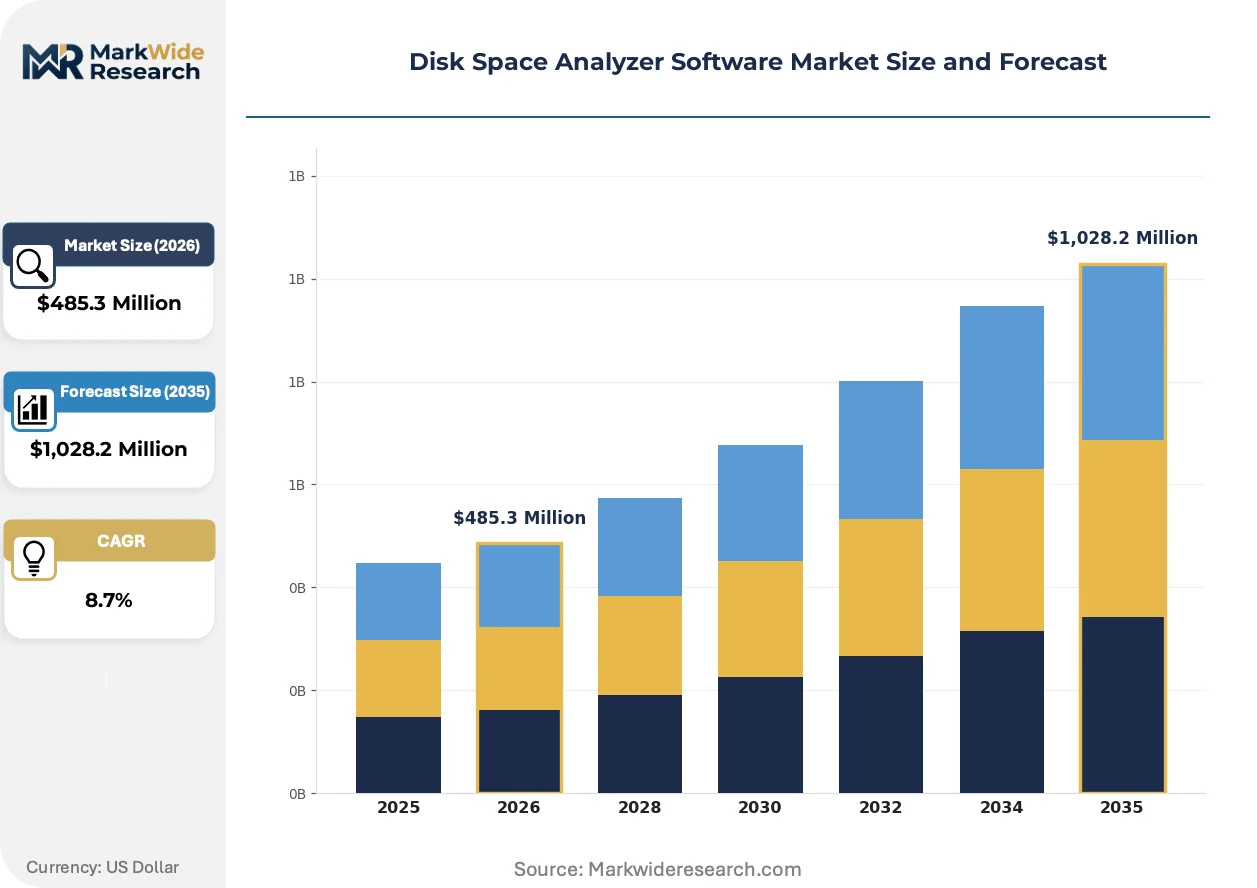
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Tools, Integrated Solutions, Cloud Services, Mobile Applications Deployment Model: On-Premises, Private Cloud, Public Cloud, Hybrid Cloud End User: Small Businesses, Enterprises, Government Agencies, Educational Institutions Pricing Model: Subscription-Based, One-Time Purchase, Freemium, Tiered Pricing |
| Companies Covered | TreeSize, WinDirStat, WizTree, DiskSavvy, SpaceSniffer, DaisyDisk, Disk Drill, CCleaner, Glary Utilities, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disk Space Analyzer Software Market Trends and Innovations
Agentless architecture is displacing endpoint-installed collectors, reducing deployment friction and expanding addressable markets beyond managed-device environments.
Direct NTFS Master File Table reading is overtaking traditional file-by-file traversal methods. Enterprise security teams now mandate this approach for forensic integrity, as MFT access leaves no filesystem modification timestamps. The technique compresses competitive differentiation around raw scan speed rather than visualization polish.
Japan's METI cybersecurity guidelines for critical infrastructure now require encrypted reporting channels and immutable access logs for storage audit tools. Vendors serving energy and telecommunications sectors must embed hardware security module integration. Japanese buyers now treat these capabilities as baseline procurement criteria rather than premium options.
Subscription pricing with usage-based tiers is displacing perpetual licensing in mid-market accounts. Value-added resellers and managed service providers now bundle disk space analysis into broader endpoint management contracts. This pattern concentrates in Germany, where Mittelstand firms prefer operational expenditure treatment for compliance tooling.
Disk Space Analyzer Software Market Segmentation
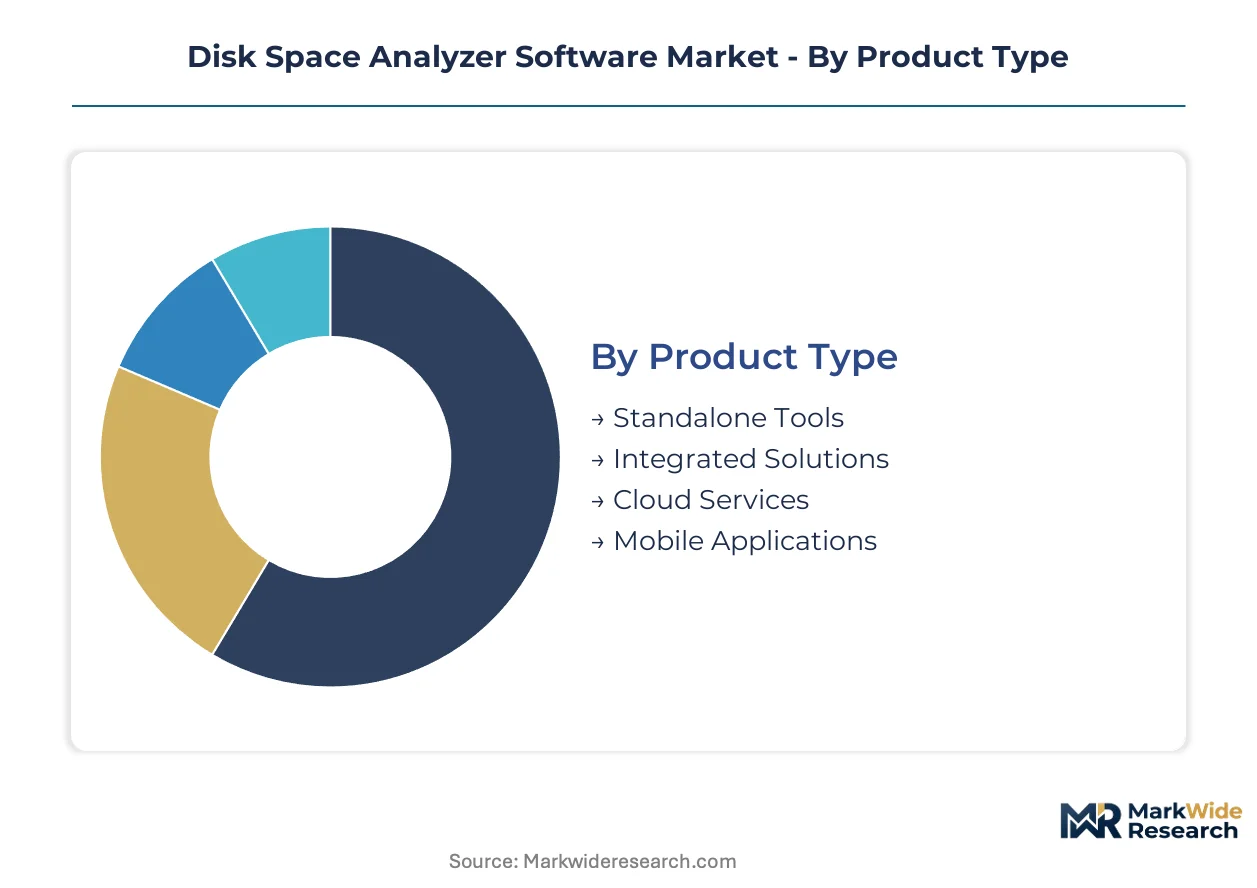
Disk space analyzer vendors architect product lines around deployment constraints and procurement psychology. Segmentation reveals where engineering investment concentrates and which buyer segments command premium pricing power.
Product Type:
Supply concentration favors vendors bundling visualization engines into broader systems management suites rather than standalone specialists.
- Integrated Solutions:Visualization engines embedded within endpoint management, backup, and IT service management platforms dominate enterprise procurement. Large IT departments in Germany and the United States prefer consolidated vendor relationships over point-tool fragmentation.
- Cloud Services:Federated analytics across AWS, Azure, and Google Cloud object stores from unified consoles address multi-cloud sprawl. DevOps teams managing stateful Kubernetes workloads drive demand for container-native deployment options.
- Standalone Tools:Specialized utilities with deep file system integration serve forensic and compliance use cases requiring granular control.
- Mobile Applications:Lightweight scanning for personal device storage management occupies a niche consumer position with limited enterprise relevance.
Today's leader: Integrated Solutions. Tomorrow's challenger: Cloud Services.
Deployment Model:
Cost tier stratification separates regulated industries requiring air-gapped control from cloud-native development teams prioritizing elasticity.
- Hybrid Cloud:Organizations distribute storage across on-premises infrastructure and multiple public providers. India's RBI and MEITY data localization mandates create demand for analyzers mapping compliance boundaries across hybrid architectures.
- Public Cloud:Native integration with AWS S3, Azure Blob, and Google Cloud Storage APIs enables agentless deployment. Proprietary metadata schemas across providers force vendors to maintain costly adapter layers.
- On-Premises:Air-gapped environments in defense and critical infrastructure sectors require offline operation with hardware security module integration.
- Private Cloud:Single-tenant deployments satisfy financial services firms with strict data residency requirements.
Hybrid Cloud commands the premium tier. Public Cloud is climbing the fastest.
End User:
Customer type determines feature depth, with compliance automation separating enterprise procurement from price-sensitive smaller accounts.
- Enterprises:IT departments require immutable audit trails, SIEM integration with Splunk and Datadog, and policy-based cleanup automation. GDPR Article 5 retention mandates and FDA 21 CFR Part 11 requirements shape product roadmaps.
- Government Agencies:Defense and intelligence sectors mandate ISO 27001 certification and encrypted reporting channels. Japan's METI cybersecurity guidelines for critical infrastructure specify hardware security module integration.
- Small Businesses:Cost-conscious buyers favor subscription pricing with usage-based tiers over perpetual licensing.
- Educational Institutions:Volume licensing agreements and research data management needs drive procurement decisions.
Enterprises anchor current revenue. Government Agencies present the steepest expansion trajectory.
Pricing Model:
Margin structure shifts from episodic license renewals toward predictable recurring revenue as vendors pursue SaaS transformation.
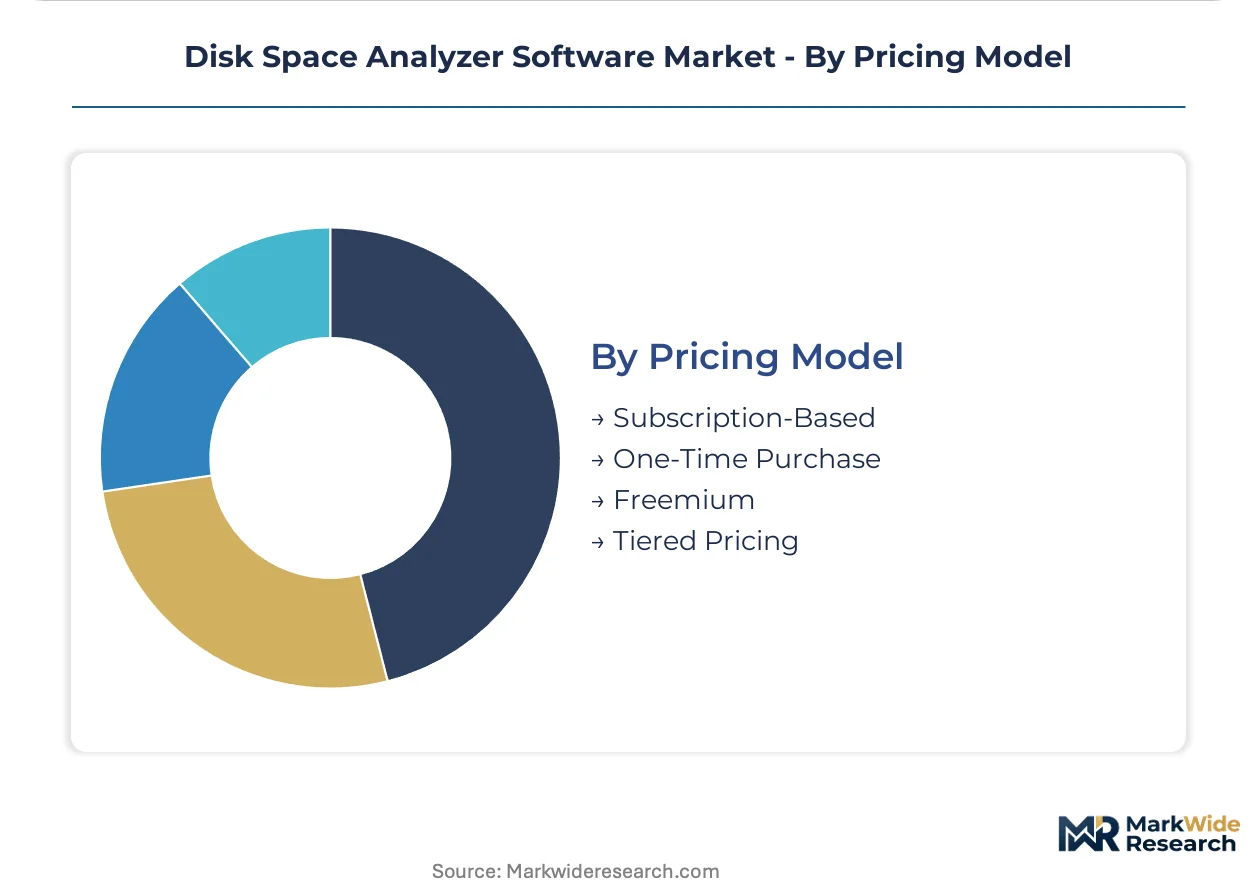
- Subscription-Based:Monthly or annual recurring revenue models dominate mid-market accounts. German Mittelstand firms prefer operational expenditure treatment for compliance tooling.
- Freemium:Basic scanning capabilities with premium features unlocked through paid tiers acquire individual users and small teams.
- One-Time Purchase:Perpetual licensing persists in air-gapped government and defense environments with restricted internet connectivity.
- Tiered Pricing:Three-level structures across premium, standard, and economy levels align feature access with organizational scale.
Subscription-Based holds the dominant margin pool. Freemium serves as the primary customer acquisition engine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disk space analyzer software originated in German engineering labs and US enterprise IT departments during the late 1990s storage management wave. Early tools emerged from systems administration communities in Munich and Seattle before commercialization spread to compliance-heavy markets. Geographic expansion now tracks data governance enforcement intensity and cloud migration velocity.
United States
FDA 21 CFR Part 11 mandates in life sciences and SEC record-keeping rules drive enterprise procurement of audit-capable tools. HIPAA requirements for healthcare data retention create specialized demand in hospital systems and insurance networks. Boston's biotech corridor and Seattle's cloud engineering clusters host dense concentrations of compliance-focused buyers.
Germany
GDP data minimization under Article 5 compels systematic storage auditing across Mittelstand manufacturing and financial services. BSI technical guidelines for critical infrastructure operators mandate immutable logging capabilities. Bavaria's automotive engineering hubs and Frankfurt's banking centers represent the densest adoption pockets for integrated systems management suites.
Japan
METI cybersecurity guidelines for critical infrastructure require encrypted reporting channels and hardware security module integration in energy and telecommunications sectors. JIS standards for enterprise software procurement favor vendors with ISO 27001 certification. Tokyo's financial district and Osaka's industrial automation clusters lead deployment of container-native storage analysis tools.
India
RBI data localization mandates for banking and MEITY requirements for government data residency create demand for hybrid architecture mapping. SEBI audit trail regulations for capital markets drive financial services adoption. Bangalore's SaaS development ecosystem and Mumbai's financial services corridor concentrate procurement of cloud-native deployment options.
United Kingdom
UK GDPR enforcement through the Information Commissioner's Office sustains demand for systematic storage auditing and deletion verification. FCA requirements for financial services record retention shape product specifications. London's fintech corridor and Cambridge's research computing clusters represent high-value customer concentrations for subscription-based tooling.
Disk Space Analyzer Software Market Competitive Landscape
The competitive structure tilts toward specialized utility developers with deep file system expertise rather than diversified systems management conglomerates. Market concentration remains moderate, with distinct performance-versus-design positioning creating definable customer segments. Two strategic archetypes dominate: speed-optimized scanning engines and visual-first creative-sector tools. Competitive moves center on API ecosystem expansion and SIEM platform partnerships rather than direct consolidation.
Among Windows-integrated specialists, TreeSize and WinDirStat occupy positions representing enterprise loyalty through ecosystem depth. WizTree exemplifies the performance-driven archetype with its NTFS Master File Table architecture. DaisyDisk anchors the premium visual-design segment serving creative professionals. These three companies collectively illustrate how technical specialization—deep Windows integration, raw scanning velocity, or interface differentiation—creates defensible positioning against bundled alternatives from broader systems management vendors.
| Leading Market Players |
|---|
| TreeSize |
| WinDirStat |
| WizTree |
| DiskSavvy |
| SpaceSniffer |
| DaisyDisk |
| Disk Drill |
| CCleaner |
| Glary Utilities |
| Others |
Pricing and Supply Chain Analysis
ISO 27001 certification timelines gate qualified supply for regulated financial services and defense procurement, compressing vendor entry and sustaining premium-tier pricing power for established players with existing audit credentials. Buyers in Germany and Japan treat encrypted reporting channels and hardware security module integration as baseline requirements, not optional upgrades.
Pricing Analysis
Subscription-based recurring revenue models dominate mid-market procurement, with annual contracts converting episodic license renewals into predictable cash flows. Price differentiation hinges on SIEM integration depth and GDPR audit trail granularity, separating enterprise-grade suites from stripped-down alternatives. Cost compression in the standalone utility tier intensifies as cloud providers bundle basic storage analytics at zero marginal cost. Small businesses exhibit highest price sensitivity, while government agencies in Japan and defense sectors in the United States accept substantial premiums for air-gapped deployment and immutable logging.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale IT department demand, while value-added resellers and managed service providers bundle disk space analysis into broader endpoint management contracts. Engineering talent concentrates in Germany, the United States, and Japan, where expertise in NTFS Master File Table architectures and kernel-level optimization clusters. Component dependencies include cryptographic libraries for encrypted reporting, visualization engines for federated analytics, and API adapters for multi-cloud metadata schemas. Single-source vulnerability runs through specialized file system developers in Munich and Seattle engineering clusters. Distribution runs through systems management suite vendors and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance automation represents a late-cycle quality story, with FDA 21 CFR Part 11 and GDPR Article 5 mandates shifting procurement toward premium audit-capable specifications over basic visualization tools.
For Market Incumbents: Acquire container-native deployment capabilities to address DevOps teams managing stateful Kubernetes workloads at scale. Integrate storage telemetry with Splunk, Datadog, and Elastic Security platforms before cloud-native entrants capture SIEM convergence budgets. Threat substitution by bundled cloud provider analytics demands faster API ecosystem expansion than standalone speed optimization. Certification investment in ISO 27001 and hardware security module integration locks out mid-market challengers in Japanese energy and telecommunications sectors. For New Entrants and Emerging Players: The mid-market gap between premium integrated suites and freemium standalone tools offers white-space entry for subscription-based compliance automation. India's RBI and MEITY data localization mandates create penetrable demand for hybrid architecture mapping tools. Container-native operators for ephemeral storage analysis address underserved DevOps segments. Go-to-market through Bangalore SaaS development ecosystems and Mumbai financial services corridors leverages localized procurement relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized file system utilities because enterprise IT departments prefer consolidated vendor relationships over point-tool fragmentation. Platform integration of standalone speed-optimized engines or visual-first creative tools into broader systems management suites captures recurring revenue pools. Acquisition targets include NTFS MFT architecture specialists and SIEM-integrated compliance platforms. Watch for inflection when Japanese METI guidelines expand beyond critical infrastructure to general enterprise mandates.| Strategic Initiative | Industry Significance |
|---|---|
| SIEM Platform Integration | Splunk and Datadog partnerships open procurement budgets outside traditional IT operations. |
| Container-Native Deployment | Kubernetes operators address DevOps teams managing stateful workloads at scale. |
| Hardware Security Module Integration | METI guidelines in Japan mandate HSM-encrypted reporting for energy sector procurement. |
| API Ecosystem Expansion | Multi-cloud adapter layers for AWS, Azure, and Google Cloud reduce development overhead. |
| ISO 27001 Certification Investment | Six-to-twelve-month audit cycles delay competitors in regulated financial services channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged CTOs at enterprise IT departments, IT procurement officers in German Mittelstand manufacturing, platform engineers managing multi-cloud storage, and compliance leads at life sciences firms navigating FDA 21 CFR Part 11. Secondary validation drew from SEC filings of systems management vendors, hyperscaler capex disclosures, GDPR enforcement actions by European data protection authorities, and METI cybersecurity guideline updates. Bottom-up segment sizing and top-down market triangulation cross-checked projections.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled deployment model, organization size, vertical compliance requirements, integration complexity with SIEM platforms, and regional adoption patterns shaped by data governance enforcement intensity. CAGRs derived from weighted average of segment growth rates adjusted for technology substitution effects. Forecast inputs included cloud migration velocity indices and regulatory audit frequency trends.
Caveats apply where cloud API fragmentation accelerates or GDPR enforcement intensity shifts materially. Forecasts reflect assumptions about sustained multi-cloud sprawl and continued tightening of data retention mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Systems Administration Management Tools Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Global Ipad POS Software Market
Software & Services
User Research Repositories Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Audio Editing Software Market
Software & Services
Global Data Discovery Software Market
Software & Services
File Analysis Software Market
Software & Services
Period-Tracking Software Market
Software & Services
High Education Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Cricket Analysis Software Market