
 Network Equipment Market | 2026-2036
Network Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Network Equipment Market Intelligence
Silicon photonics is broadening the performance envelope for data center interconnects by displacing traditional copper backplanes in high-density switching applications. Cisco Systems leverages vertical integration across silicon, optics, and software stacks to sustain margin capture in enterprise routing. Huawei Technologies anchors substantial manufacturing scale in optical transport, though geopolitical restrictions compel the company to navigate channel limitations across multiple Western markets. Nokia Corporation specializes in carrier-grade fiber access platforms, competing aggressively for broadband network buildouts in European and Asian telecommunications markets.
Network equipment encompasses the physical hardware infrastructure enabling data transmission, routing, switching, and wireless connectivity across telecommunications and enterprise environments, typically operating at speeds from 1 Gbps to 800 Gbps with latency specifications measured in microseconds. These systems form the backbone of modern digital commerce, cloud services, and real-time communications by processing packet flows through specialized ASICs, programmable forwarding planes, and redundant power architectures. Wireless access points represent the fastest-expanding product category as Wi-Fi 7 and private 5G deployments accelerate enterprise edge connectivity. Fiber optic technology commands premium positioning in margin pools due to the technical complexity of coherent optical engines and the concentration of component suppliers. Routers maintain mature, high-volume status in telecommunications backbones, while network security applications within the application dimension are attracting disproportionate R&D investment from vendors responding to zero-trust architecture mandates.
The Federal Communications Commission shapes US market access through spectrum allocation and equipment authorization rules, while the European Telecommunications Standards Institute coordinates interoperability benchmarks that influence procurement specifications across EU member states. China's Ministry of Industry and Information Technology governs domestic network infrastructure deployment through GB standards and dual carbon goals that increasingly favor energy-efficient switching architectures. Stakeholders must monitor how divergent national security frameworks for supply chain provenance reshape vendor qualification criteria and long-term procurement commitments across major network buildout programs.
Market Dynamics
Silicon photonics is modularizing optical engine architectures and compressing the traditional supply chain boundaries between semiconductor foundries and optical component assemblers, forcing incumbents to reconfigure their manufacturing footprints.
Growth Catalysts
- Hyperscale Cloud Expansion:Data center operators in Northern Virginia, Frankfurt, and Singapore are deploying 800 Gbps switching fabrics to support AI training clusters, pulling demand for coherent optical transceivers and high-density patch panels.
- EU Cybersecurity Certification:The NIS2 Directive mandates Common Criteria certification for critical network infrastructure, compelling telecommunications operators to refresh router and firewall hardware across member states.
- Industrial Automation:Automotive manufacturing clusters in Stuttgart and Wolfsburg are installing private 5G networks and time-sensitive Ethernet switches to synchronize robotic assembly lines with sub-millisecond precision.
Market Restraints
- Indium Phosphide Supply Concentration:Coherent optical engine production depends on III-V semiconductor wafers from a limited set of Japanese and US compound semiconductor foundries, exposing the supply chain to single-source fragility.
- Geopolitical Channel Restrictions:Equipment vendors face qualification barriers in multiple Western markets due to national security frameworks governing supply chain provenance and firmware audit requirements.
- Copper Interconnect Persistence:Short-reach data center interconnects below 100 meters continue using passive copper DAC assemblies, delaying silicon photonics penetration in the highest-volume rack-to-rack applications.
Strategic Opportunities
- Private 5G Enterprise Networks:Manufacturing campuses in Bavaria and the US Midwest represent underpenetrated demand for integrated radio access network equipment with industrial IoT gateway functionality.
- Energy-Efficient Switching Mandates:China's dual carbon goals favor disaggregated white-box switching architectures with open network operating systems, creating procurement openings for non-incumbent vendors.
- Co-Packaged Optics Convergence:The integration of silicon photonics with switch ASICs enables 51.2 Tbps fabric capacity in single-chip designs, collapsing the traditional optical-to-electrical boundary.
Industry Challenges
- Photonics Packaging Talent Scarcity:The specialized skill set for aligning laser diodes with silicon waveguides is concentrated among a small cohort of engineers in Eindhoven and Tokyo, constraining manufacturing scale-up.
- Multi-Vendor Interoperability Certification:Open RAN deployments require extensive testing across disaggregated radio units, distributed units, and centralized units, extending deployment timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Equipment Market |
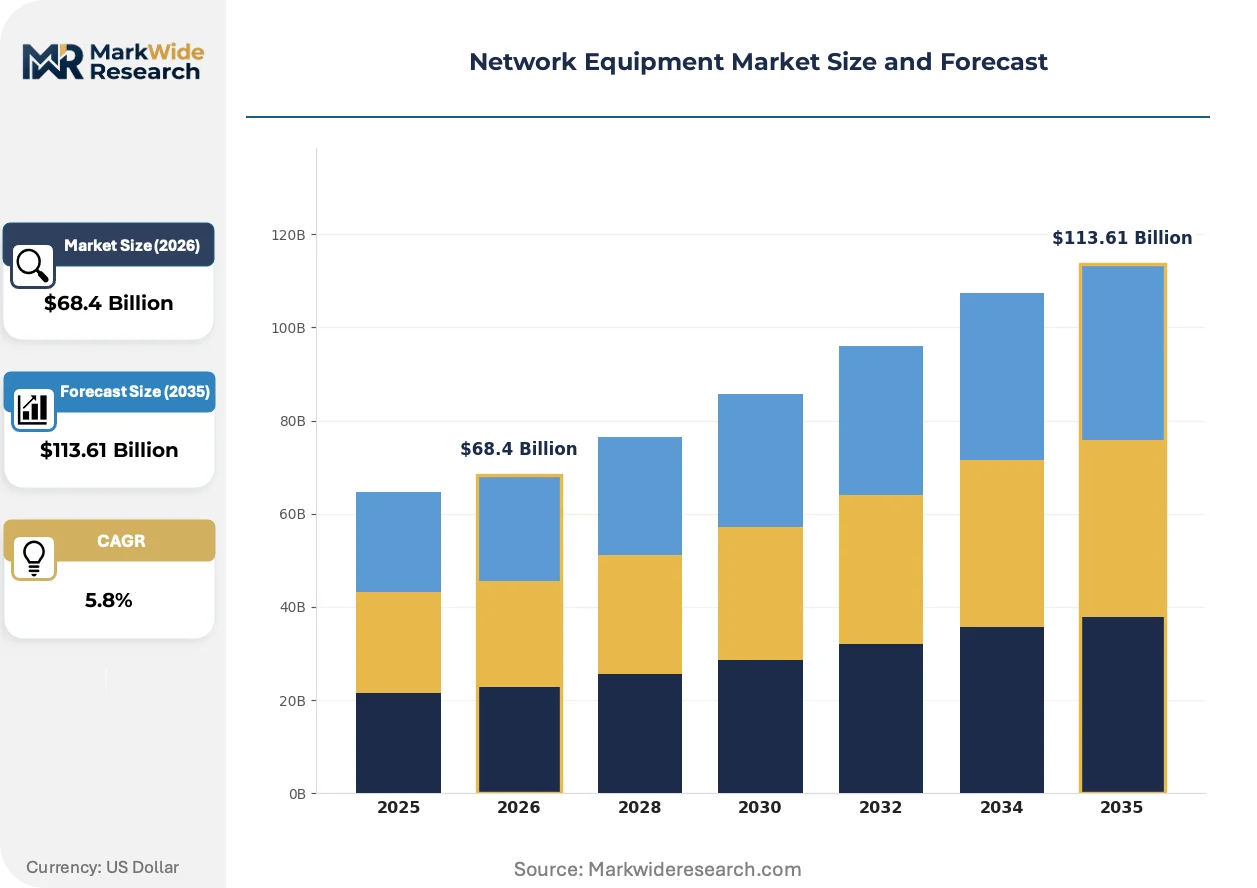
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Modems, Access Points Technology: Wired, Wireless, Ethernet, Fiber Optic End User: Telecommunications, Enterprises, Data Centers, Government Application: VoIP, Video Conferencing, Network Security, Cloud Computing |
| Companies Covered | Cisco Systems, Huawei Technologies, Nokia Corporation, Ericsson, Juniper Networks, Hewlett Packard Enterprise, ZTE Corporation, Arista Networks, Ciena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Equipment Market Strategic Shifts & Innovations
Optical transport architectures are fragmenting into disaggregated subsystems, programmable forwarding planes are displacing fixed-function ASICs, and procurement patterns are compressing vendor qualification cycles from years to quarters.
Silicon photonics is modularizing coherent optical engine designs by integrating indium phosphide lasers directly onto silicon substrates. Cloud operators in hyperscale facilities are adopting these co-packaged optics at accelerated refresh cycles. This technology is modularizing the traditional boundary between switch silicon and pluggable transceivers, collapsing the supply chain into fewer manufacturing steps.
The EU Cybersecurity Act establishes a harmonized certification framework for ICT products, services, and processes across member states. Equipment manufacturers must now undergo third-party evaluation against Common Criteria or EUCC schemes before public procurement eligibility. Carrier-grade router vendors targeting European telecommunications markets are restructuring firmware development pipelines to satisfy audit requirements.
Enterprise buyers are consolidating network equipment procurement through cloud-managed service contracts rather than capital purchase agreements. Value-added distributors and systems integrators in Germany and the Netherlands are capturing margin through managed network-as-a-service offerings. This behavioral shift is most pronounced among mid-market manufacturing enterprises seeking to outsource operational complexity.
Network Equipment Market Segmentation
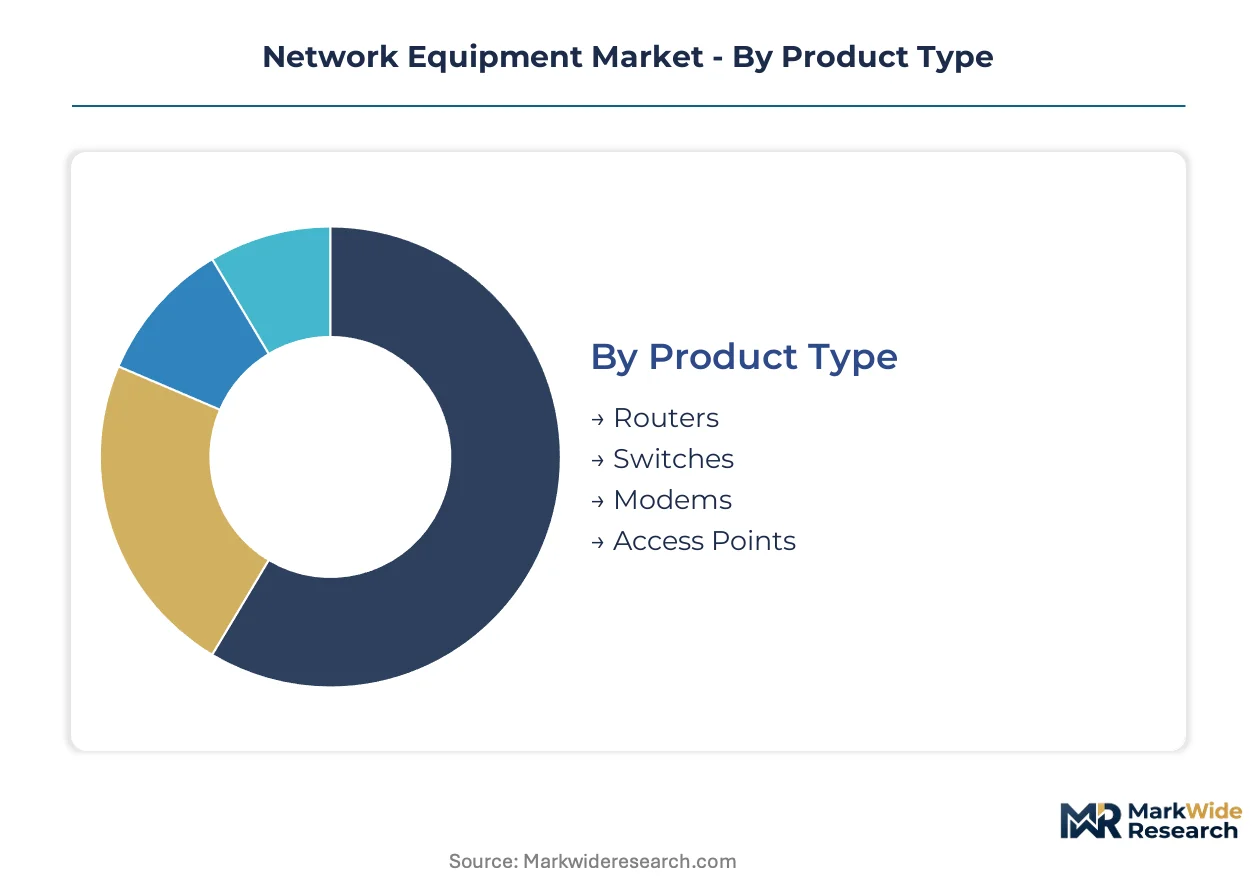
Network equipment segmentation reveals how vendor portfolios align with divergent performance requirements across telecommunications backbones, hyperscale data centers, and industrial edge deployments. Procurement patterns vary sharply by segment, with carrier-grade hardware demanding multi-year certification cycles while enterprise switching refreshes on compressed timelines.
Product Type:
Standardization dominates high-volume switching and routing categories, while access infrastructure permits greater customization for spectrum environments and physical deployment constraints.
- Routers:Carrier-grade systems process packet flows through specialized forwarding ASICs with redundant power architectures and terabit-scale fabric capacity. Telecommunications operators in Germany and Japan deploy these systems in backbone refresh cycles driven by NIS2 Directive compliance mandates and 5G transport densification requirements.
- Switches:Data center switching fabrics operate at 400-800 Gbps per port with latency specifications below one microsecond, displacing copper backplanes through silicon photonics integration. Hyperscale operators in Northern Virginia and Singapore are pulling demand for high-density spine-leaf architectures supporting AI training clusters.
- Modems:CPE devices bridge last-mile connectivity across DSL, cable, and fiber access technologies with integrated Wi-Fi 7 radio functionality.
- Access Points:Enterprise wireless infrastructure supports Wi-Fi 7 and private 5G radio configurations with centralized management planes.
Most installed capacity flows through Switches. Expansion is steepest in Access Points.
Technology:
Cost tiers separate legacy copper interconnects from premium optical transport, with deployment distance and bandwidth density determining technology selection.
- Wired:Copper Ethernet and passive DAC assemblies persist in rack-scale deployments below 100 meters due to cost advantages over optical alternatives. Enterprise data centers in the US Midwest continue specifying copper for top-of-rack connections despite silicon photonics advancement.
- Wireless:Radio access network equipment spans macro cell base stations, small cells, and private 5G indoor deployments with integrated IoT gateway functionality. Manufacturing campuses in Bavaria are installing time-synchronized wireless infrastructure for robotic assembly line coordination.
- Ethernet:Switched Ethernet dominates enterprise LAN and data center interconnects with standardized IEEE 802.3 specifications from 1 Gbps to 800 Gbps.
- Fiber Optic:Coherent optical engines enable terabit-scale transport across metro and long-haul distances through indium phosphide laser integration.
Volume concentrates in Wired installations. Margin capture is strongest in Fiber Optic.
End User:
Customer type determines procurement complexity, with government and telecommunications segments imposing certification barriers that filter vendor participation.
- Telecommunications:Carrier networks require Common Criteria certification under EU Cybersecurity Act frameworks, with equipment authorization governed by national regulators including Germany's BSI and Japan's MIC. These operators are refreshing router hardware across member states to satisfy NIS2 Directive mandates.
- Enterprises:Mid-market manufacturing firms in Stuttgart and Wolfsburg are outsourcing network operations through managed service contracts rather than capital purchases. Value-added distributors in the Netherlands are capturing margin through network-as-a-service offerings.
- Data Centers:Hyperscale operators specify disaggregated white-box switching with open network operating systems, favoring energy-efficient architectures aligned with China's dual carbon goals.
- Government:Public sector procurement imposes supply chain provenance requirements and firmware audit specifications that constrain vendor qualification.
Procurement volume flows through Telecommunications. Contracting velocity is climbing fastest in Enterprises.
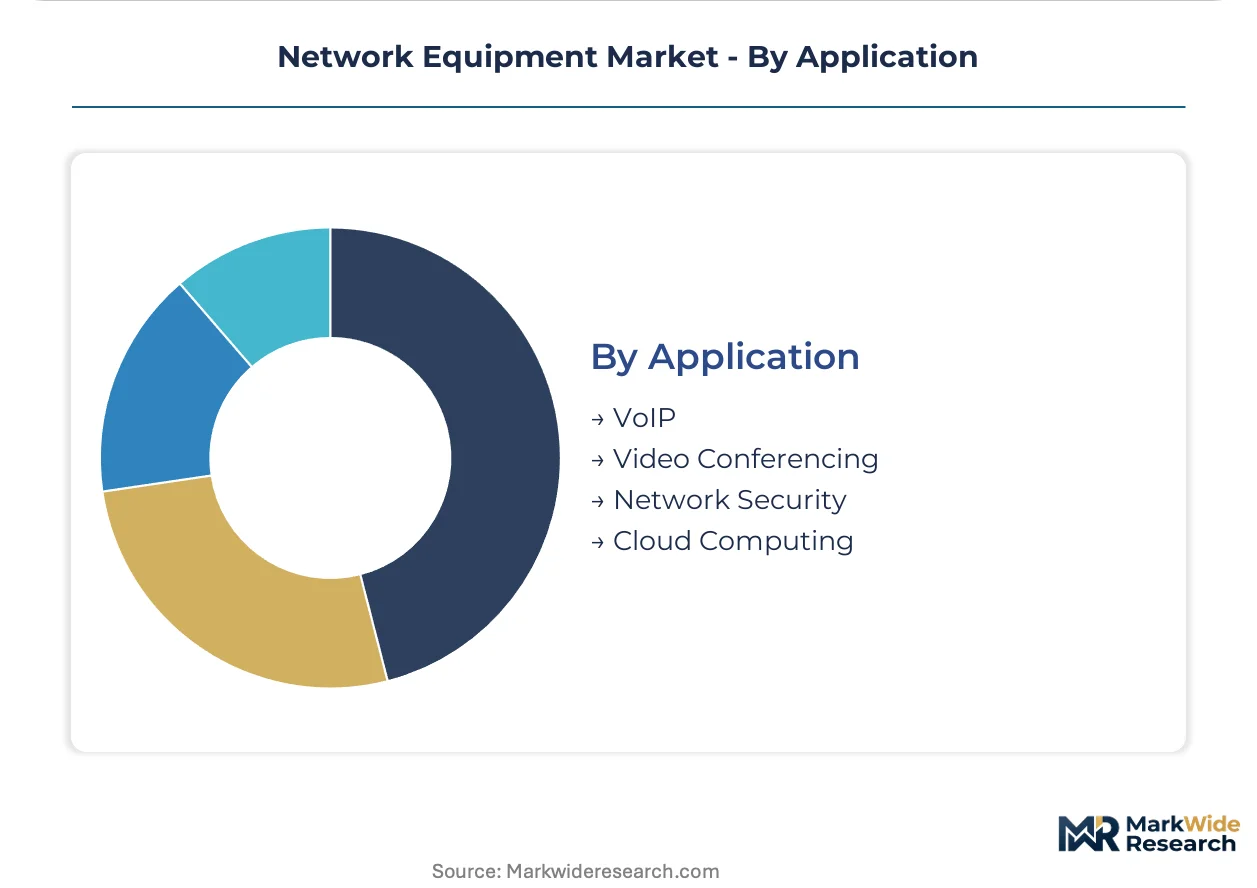
Application:
Maturity gradients separate established connectivity applications from security and cloud infrastructure segments attracting disproportionate R&D investment.
- Network Security:Firewalls, intrusion detection systems, and zero-trust enforcement points operate as embedded functions within routing and switching platforms or as discrete appliances. Vendors are restructuring firmware development pipelines to satisfy EUCC audit requirements for European public procurement eligibility.
- Cloud Computing:Software-defined networking controllers and programmable forwarding planes enable elastic capacity provisioning across distributed compute infrastructure. Hyperscale facilities in Frankfurt and Singapore are deploying 800 Gbps fabrics to support AI training workloads.
- VoIP:Session border controllers and media gateways bridge traditional PSTN interconnects with packet-switched voice infrastructure.
- Video Conferencing:Edge caching and quality-of-service prioritization equipment supports real-time media delivery across enterprise WANs.
Deployment scale is largest in Cloud Computing. Security applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive manufacturing clusters are pulling fiber optic and time-sensitive Ethernet demand for robotic assembly synchronization. Regulatory pressure from the EU Cybersecurity Act and NIS2 Directive is reshaping procurement eligibility across member states.
Germany
Industrial automation in Stuttgart and Wolfsburg drives private 5G network deployments and time-sensitive Ethernet switch installations. The Federal Office for Information Security enforces Common Criteria certification under EU Cybersecurity Act frameworks. Bavarian manufacturing campuses are installing integrated radio access network equipment with industrial IoT gateway functionality.
United States
Hyperscale data center operators in Northern Virginia deploy 800 Gbps switching fabrics to support AI training clusters. The Federal Communications Commission governs spectrum allocation and equipment authorization rules for network infrastructure. Dallas-Fort Worth metroplex facilities are specifying disaggregated white-box switching with open network operating systems.
China
Dual carbon goals from the Ministry of Industry and Information Technology favor energy-efficient switching architectures in hyperscale facilities. GB standards govern domestic network infrastructure deployment with increasing stringency around firmware audit requirements. Yangtze River Delta data centers are adopting co-packaged optics at accelerated refresh cycles.
Japan
Compound semiconductor foundries in Tokyo supply indium phosphide wafers for coherent optical engine production. The Ministry of Internal Affairs and Communications regulates telecommunications equipment authorization with emphasis on supply chain provenance. Osaka-Kobe manufacturing corridors are refreshing router hardware to satisfy cybersecurity certification mandates.
Singapore
Hyperscale cloud operators specify 400-800 Gbps spine-leaf architectures for distributed compute infrastructure. The Infocomm Media Development Authority coordinates interoperability benchmarks influencing procurement specifications. Tuas data center precincts are deploying high-density patch panels for coherent optical transceiver interconnects.
Network Equipment Market Key Industry Players
Global majors compete with regional champions across certification complexity and manufacturing scale dimensions. The vendor base separates into tiered positions based on vertical integration depth and geographic market access. Three archetypes dominate: integrated silicon-to-systems operators, optical transport specialists, and disaggregated white-box fabricators. Capacity expansion in compound semiconductor foundries and strategic partnerships for photonics packaging capability represent the primary competitive vectors.
Within the integrated systems tier, Cisco Systems and Huawei Technologies occupy positions reflecting contrasting geographic market access profiles. Nokia Corporation exemplifies the carrier-grade infrastructure specialist archetype. These three anchors demonstrate how vendor positioning varies sharply between enterprise routing, optical transport, and telecommunications backbone segments.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Nokia Corporation |
| Ericsson |
| Juniper Networks |
| Hewlett Packard Enterprise |
| ZTE Corporation |
| Arista Networks |
| Ciena Corporation |
| Others |
Cost & Logistics Intelligence
Captive silicon-to-systems integration anchors both supply security and pricing power for dominant router and switch vendors, compressing margin leakage while hyperscale buyers force cost transparency through disaggregated procurement. This structural choice separates premium-positioned incumbents from white-box competitors competing on energy efficiency metrics under China's MIIT dual carbon mandates.
Pricing Analysis
Input-cost pass-through from indium phosphide wafer supply constrains coherent optical engine pricing, with Japanese compound semiconductor foundries commanding premium positioning due to III-V fabrication scarcity. Three-tier pricing structure across carrier-grade certified, enterprise-standard, and white-box economy levels differentiates procurement eligibility under EU Cybersecurity Act frameworks. Cost compression in spine-leaf switching intensifies because hyperscale operators consolidate volume through direct ASIC sourcing. Telecommunications operators demonstrate lowest price sensitivity due to NIS2 Directive compliance mandates, while mid-market manufacturing enterprises in Germany outsource through network-as-a-service contracts to cap capital exposure.
Supply Chain Analysis
Certification gating through Common Criteria and EUCC schemes filters vendor participation in European public procurement, extending qualification timelines and concentrating eligible supply among vertically integrated incumbents. Manufacturing concentrates in China, Taiwan, and the United States for switch ASIC fabrication, with Japan anchoring indium phosphide laser production for coherent optical engines. Raw material dependencies center on silicon wafers, rare earth elements for optical amplification, and copper for short-reach interconnects. Single-source vulnerability in photonics packaging talent pools constrains manufacturing scale-up. Distribution runs through value-added distributors in Germany and the Netherlands capturing margin through managed service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hyperscale cloud operators pulling demand toward 800 Gbps switching fabrics with sub-microsecond latency specifications. Procurement consolidation around energy-efficient architectures under China's dual carbon goals reinforces premium positioning for certified vendors.
For Market Incumbents: Anchor market position through captive silicon photonics packaging capability in Eindhoven or Tokyo talent clusters, defending against white-box disaggregation by accelerating co-packaged optics roadmaps. Deepen backward integration into indium phosphide laser sourcing to mitigate single-supplier fragility from Japanese compound semiconductor foundries. Prioritize EUCC certification investment to maintain public procurement eligibility across NIS2 Directive member states. For New Entrants and Emerging Players: Begin with private 5G enterprise network deployments in Bavarian manufacturing campuses, where time-sensitive Ethernet demand for robotic assembly synchronization outpaces incumbent service coverage. Target disaggregated white-box switching opportunities in China's Yangtze River Delta hyperscale facilities, where open network operating systems procurement favors non-traditional vendors. Pursue channel partnerships with Dutch value-added distributors to embed network-as-a-service offerings for mid-market manufacturing outsourcing demand. For Investors and Strategic Acquirers: Roll-up economics work for optical transport specialists because coherent engine production requires concentrated photonics packaging talent that resists rapid replication. Long-term viability centers on vendors controlling silicon-to-optics integration depth across the 5-10 year technology transition. Monitor hyperscaler capex disclosure patterns as the primary inflection indicator for switching fabric refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Collapse of optical-to-electrical boundaries enables 51.2 Tbps single-chip fabric capacity for hyperscale AI clusters. |
| EUCC Certification Investment | Third-party firmware audit compliance secures public procurement eligibility under EU Cybersecurity Act frameworks. |
| Private 5G Enterprise Deployment | Integrated radio access network equipment with industrial IoT gateway functionality penetrates under-served manufacturing campuses. |
| Indium Phosphide Supply Security | Captive wafer sourcing from Japanese compound semiconductor foundries mitigates III-V supply chain fragility. |
| Network-as-a-Service Channel Partnership | Dutch value-added distributors capture recurring revenue through outsourced network operations for mid-market enterprises. |
Research Approach
Bottom-up hyperscale facility and telecommunications operator modeling reconciled against top-down semiconductor foundry and optical component tracking forms the analytical core of this study. Primary interviews with data center procurement officers, carrier network planners, photonics packaging engineers, and value-added distribution executives combined with secondary validation against SEC filings from equipment vendors, hyperscaler capex disclosures, and EU regulatory certification databases. Triangulation across these sources ensures demand-side projections align with supply-side capacity constraints.
Historical trendline analysis of switching fabric refresh cycles, coherent optical transceiver deployment rates, and cybersecurity certification timelines informs the projection framework. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and geographic regulatory cluster, with particular attention to NIS2 Directive compliance mandates across EU member states. CAGRs derive from elasticity-adjusted demand curves incorporating AI training cluster expansion, industrial automation connectivity requirements, and energy-efficiency procurement preferences. Forecast inputs center on indium phosphide wafer supply constraints and photonics packaging talent availability.
Several conditions sit outside the modeled scope, including abrupt geopolitical channel restrictions, compound semiconductor foundry disruption, and unanticipated Wi-Fi 7 substitution for private 5G deployments. Forecasts reflect assumptions about sustained hyperscale capital expenditure commitment and stable EU regulatory certification timelines. A model refresh is warranted upon material change in hyperscaler AI infrastructure investment patterns or substantial revision to EU Cybersecurity Act implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Gigabit Ethernet Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Industrial Ethernet Market
Network Technology
Wi-Fi Extender Market
Network Technology
Digital Repeater Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
2.4GHz Router Market
Network Technology
Cloud Gateway Module Market
Network Technology
Lit Fiber Market
Network Technology
Open RAN Market
Network Technology
Protocol Analyzer Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
North America Network Management Solutions Market
Network Technology
Carrier Routing Equipment Market
Network Technology
US Private 5G Network Market
Network Technology
Session Border Controller (SBC) Market