
 Cloud Managed Access Points Market | 2026-2036
Cloud Managed Access Points Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Managed Access Points Market Outlook
Healthcare facilities is unwinding from retail and hospitality as the dominant buyer archetype for cloud-managed wireless infrastructure. Cisco leverages its Meraki cloud platform to anchor enterprise and healthcare verticals with unified policy management. HPE Aruba competes through its Edge Services Platform, which sustains R&D intensity in AI-powered network automation. Juniper Networks differentiates via Mist AI, which specializes in predictive operations and reduces mean time to resolution for distributed campus environments.
Cloud managed access points are wireless networking devices whose configuration, monitoring, and firmware management occur through remote cloud controllers rather than on-premises controllers, typically supporting dual-band or tri-band operation with Power over Ethernet Plus (PoE+) input and throughput exceeding 3 Gbps in Wi-Fi 6E implementations. These devices serve commercial and industrial environments requiring centralized visibility across hundreds or thousands of distributed radio units without dedicated IT staff at each location. Indoor access points dominate volume shipments and margin pools due to enterprise office densification and classroom modernization, while Wi-Fi 6E connectivity standards represent the fastest-growing segment as organizations refresh legacy Wi-Fi 5 infrastructure to support 6 GHz spectrum utilization and lower-latency device density. Hybrid cloud deployment models are gaining structural share among regulated industries requiring local data residency for authentication logs paired with cloud analytics for performance optimization.
The FCC governs unlicensed spectrum allocation and equipment authorization under Part 15 rules in the United States, directly shaping which frequency bands and power levels manufacturers must support. ETSI enforces harmonized radio spectrum use across European member states, while the EU Cybersecurity Act establishes certification frameworks for network equipment that vendors must navigate for CE marking compliance. Stakeholders should monitor spectrum auction outcomes and cybersecurity labeling requirements as decisive variables for product roadmaps and geographic market entry sequencing.
Market Dynamics
Wi-Fi 6E spectrum availability is fragmenting procurement priorities across enterprise buyers, forcing infrastructure refresh cycles that favor cloud-native management over controller-based architectures.
Growth Catalysts
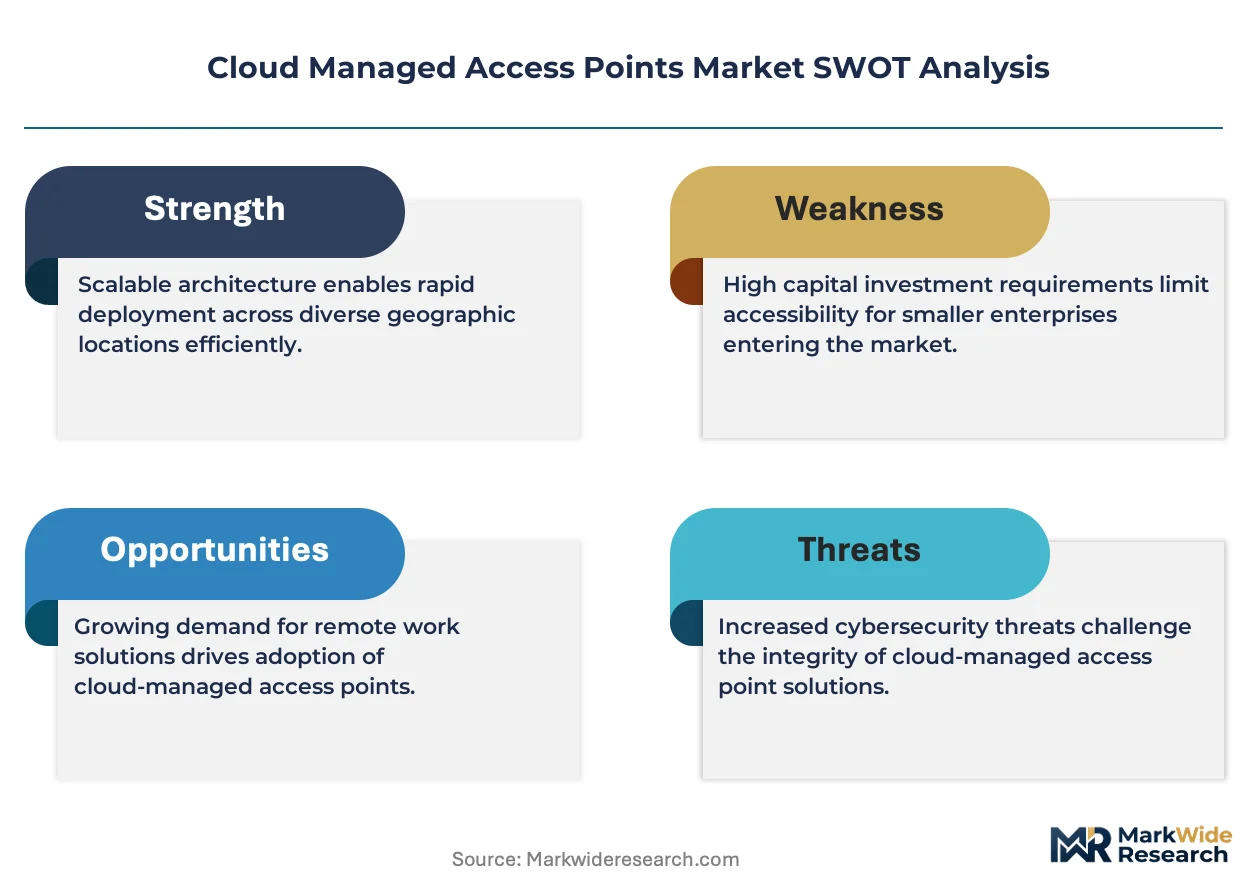
- Healthcare facility densification:Hospital systems deploy cloud-managed access points to unify clinical device tracking and guest Wi-Fi under single-pane visibility. Medical IoT compliance requirements accelerate this transition.
- ETSI harmonized spectrum frameworks:European standardization of 6 GHz unlicensed bands reduces cross-border deployment friction for multinational campus networks. Equipment certification reciprocity cuts time-to-market for vendors.
- Power over Ethernet Plus (PoE+) standardization:IEEE 802.3bt implementation enables single-cable deployment for tri-band access points, reducing electrical contractor costs in retrofit environments.
Market Restraints
- Silicon supply concentration:Wi-Fi 6E radio chip fabrication concentrates among three foundry operators in Taiwan and South Korea. Geopolitical friction threatens lead times for access point manufacturers.
- Legacy controller sunk costs:Enterprises with recent on-premises wireless LAN controller investments face write-down pressure that delays cloud migration timelines.
- Copper and gallium arsenide price volatility:RF component input costs swing with commodity markets, compressing hardware margins for volume shipment tiers.
Strategic Opportunities
- Industrial IoT convergence:Manufacturing facilities combine cloud-managed Wi-Fi with private 5G networks for deterministic latency control. Dual-radio access points capture this hybrid architecture demand.
- India smart city mandates:Urban infrastructure projects specify centralized network management for public Wi-Fi deployments. Cloud-native platforms align with procurement specifications.
- Subscription revenue models:Per-access-point SaaS licensing replaces perpetual hardware sales, improving vendor cash flow predictability and customer lifetime value metrics.
Industry Challenges
- Radio frequency engineering talent scarcity:6 GHz propagation modeling and interference mitigation require specialized expertise that outpaces university program output.
- Multi-vendor interoperability certification:Passpoint and OpenRoaming implementation inconsistencies create integration friction for heterogeneous campus environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Managed Access Points Market |
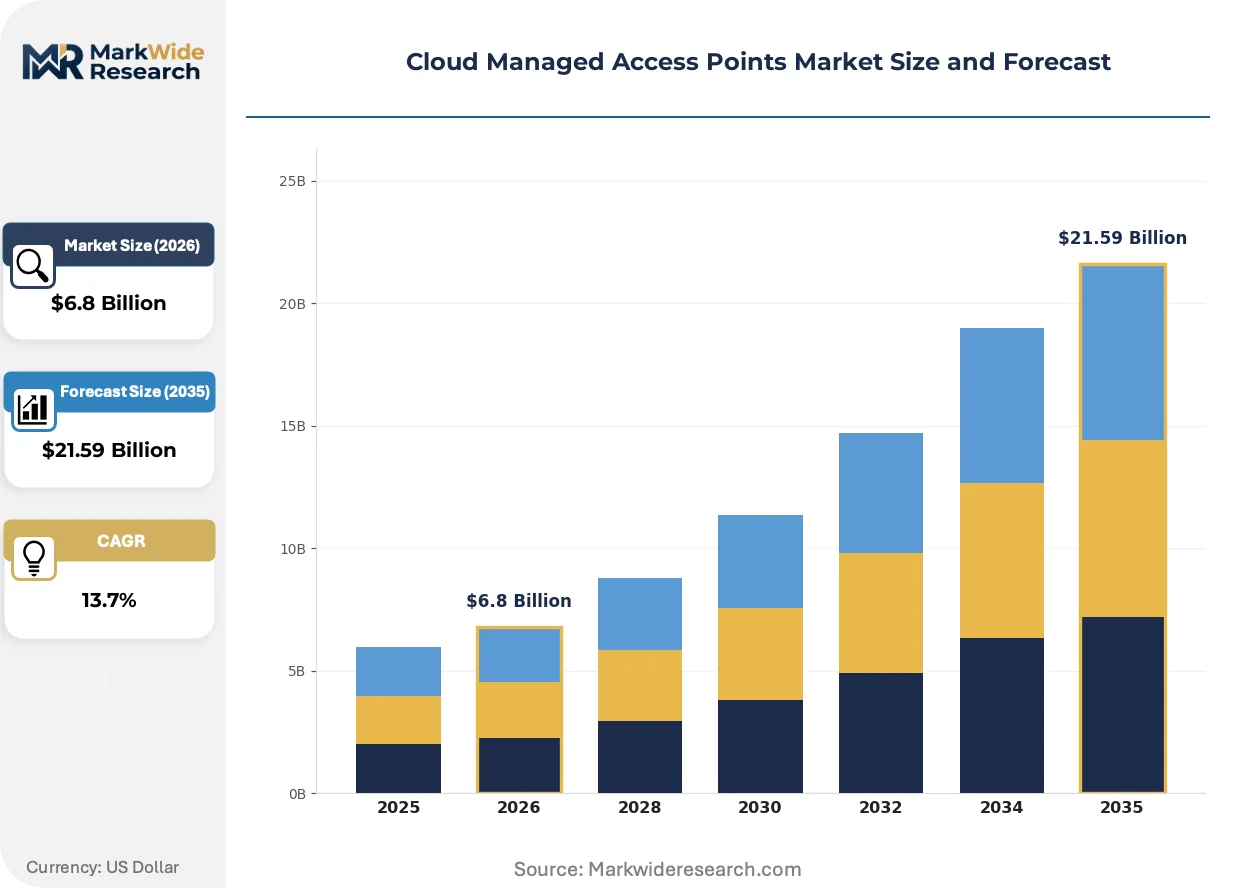
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Access Points, Outdoor Access Points, Mesh Access Points, Dual-Band Access Points Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: SMBs, Enterprises, Educational Institutions, Healthcare Facilities Connectivity Standard: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Others |
| Companies Covered | Cisco, HPE Aruba, Juniper Networks, CommScope, Extreme Networks, Fortinet, Ubiquiti, Ruckus Networks, Meraki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Managed Access Points Market Strategic Shifts
Artificial intelligence inference at the network edge is redefining operational workflows, shifting troubleshooting from reactive ticket resolution toward predictive radio resource optimization.
Wi-Fi 7 (802.11be) is decomposing the traditional controller-access point hierarchy by embedding scheduling intelligence directly into radio firmware. Multi-link operation enables simultaneous 2.4 GHz, 5 GHz, and 6 GHz transmission for deterministic latency in video collaboration suites. Enterprise IT departments in Germany and Japan pilot these implementations for conference room density targets that exceed Wi-Fi 6E capacity.
The FCC's Part 15 equipment authorization process is tightening emission mask requirements for 6 GHz standard power indoor access points. Manufacturers must submit updated test reports for existing Wi-Fi 6E certifications, extending product launch timelines by four to six months. Healthcare and education verticals in the United States delay refresh decisions pending regulatory clarity on automated frequency coordination database requirements.
Enterprise procurement teams now bundle network management software with security service edge contracts, collapsing separate RFP processes that previously ran on independent cycles. Value-added distributors and systems integrators capture this consolidation by offering combined SASE and wireless LAN packages. This pattern concentrates most visibly among financial services headquarters in New York, London, and Singapore where zero-trust architecture mandates drive purchasing alignment.
Cloud Managed Access Points Market Segmentation
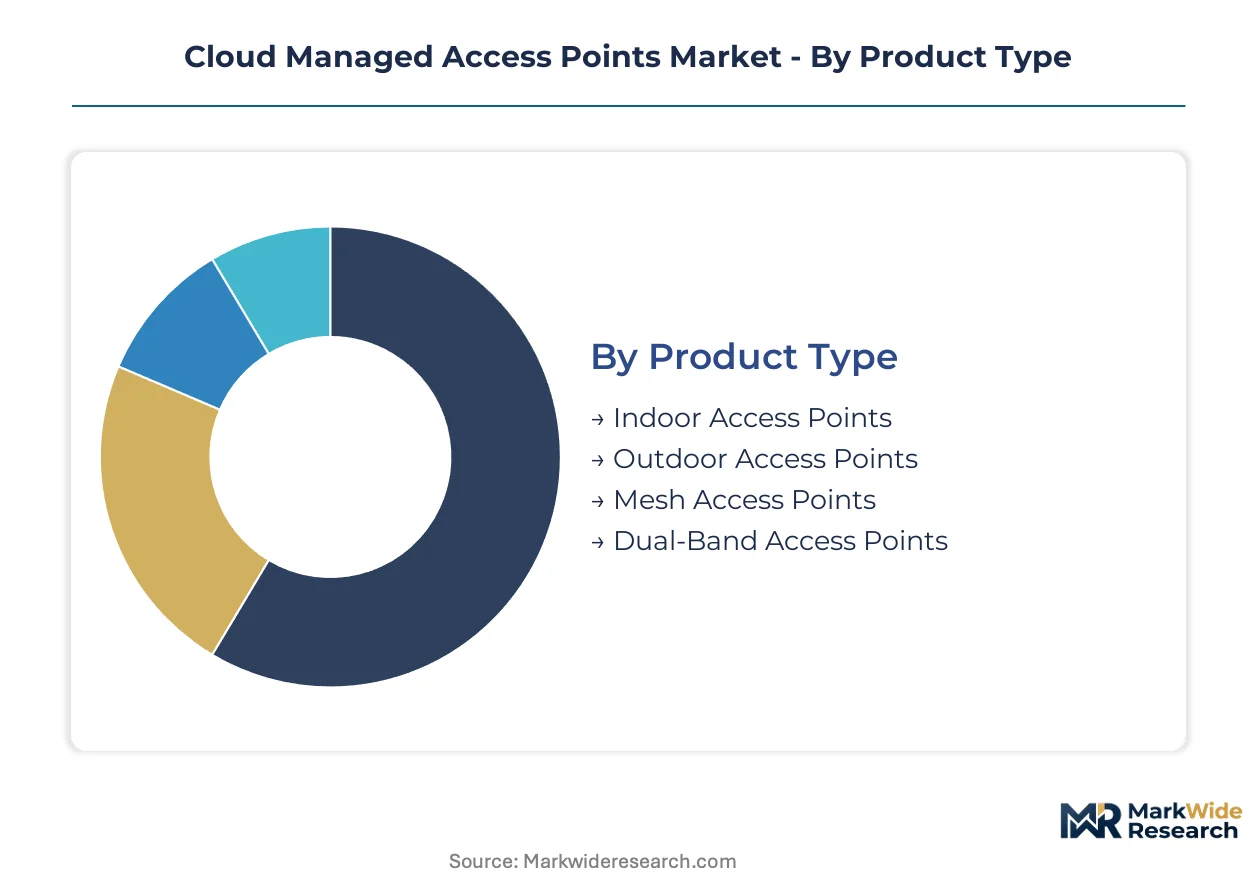
Cloud managed access points fragment across four structural dimensions that determine procurement patterns, margin profiles, and vendor competitive intensity. Product type and connectivity standard concentrate volume and technology leadership, while deployment model and end user shape pricing architecture and sales cycle length.
Product Type:
Substitution pressure from private 5G small cells and fixed wireless access equipment weighs heaviest on outdoor and mesh configurations, forcing differentiation through management software depth.
- Indoor Access Points:These units mount on ceilings and walls within climate-controlled environments, typically supporting 2.4 GHz, 5 GHz, and 6 GHz bands with integrated antennas optimized for office density. Enterprise campuses in Germany and Japan concentrate procurement for conference room modernization and open-floor densification, driven by return-to-office mandates requiring seamless roaming across dense radio environments.
- Outdoor Access Points:Hardened enclosures rated for IP67 or higher withstand temperature extremes and moisture ingress, with directional antennas engineered for stadium concourses and parking structure coverage. Municipal smart city projects in India specify these units for public Wi-Fi backbones, constrained by fiber trenching costs that make wireless mesh extensions economically preferable.
- Mesh Access Points:Self-organizing backhaul protocols eliminate ethernet cabling requirements between nodes, suiting historic building retrofits and temporary event deployments.
- Dual-Band Access Points:2.4 GHz and 5 GHz operation without 6 GHz support serves cost-sensitive refresh cycles where legacy device compatibility outweighs spectrum expansion needs.
Indoor access points anchors the volume base while outdoor access points gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates public cloud efficiency from private cloud capital intensity, with hybrid architectures commanding premium pricing for architectural complexity.
- Public Cloud:Vendor-hosted controllers manage configuration and analytics with zero customer infrastructure burden, scaling elastically across thousands of sites. Retail chains and hospitality groups in the United States standardize on this model, driven by IT staff scarcity at distributed locations and preference for operational expenditure treatment.
- Private Cloud:Customer-managed controller instances deploy within on-premises data centers or single-tenant virtual private clouds, preserving full data sovereignty. Financial services headquarters in New York and London mandate this architecture, constrained by regulatory prohibitions against third-party access to authentication logs and traffic metadata.
- Hybrid Cloud:Local controllers handle real-time functions while cloud layers provide analytics and firmware distribution, balancing latency requirements with centralized visibility. Healthcare systems adopt this pattern to satisfy HIPAA technical safeguards while leveraging predictive maintenance algorithms.
- Multi-Cloud:Controller redundancy spans two or more public cloud providers, mitigating vendor lock-in and availability zone risks for mission-critical infrastructure.
Public cloud captures the highest shipment volumes while hybrid cloud expands most quickly among regulated verticals.
End User:
Application maturity diverges sharply, with healthcare and education accelerating replacement cycles while SMBs extend legacy equipment lifespans.
- SMBs:Small and medium businesses prioritize plug-and-play deployment with minimal configuration overhead, typically purchasing through value-added distributors rather than direct vendor engagement.
- Enterprises:Multi-site corporations require centralized policy orchestration across hundreds of locations, with API integration into IT service management platforms. Manufacturing facilities in Japan combine these deployments with private 5G for deterministic latency control, driven by Industry 4.0 automation requirements.
- Educational Institutions:K-12 districts and universities face cyclical funding patterns tied to bond referendums, with E-Rate subsidies in the United States shaping technology refresh timing.
- Healthcare Facilities:Hospital systems deploy medical-grade wireless infrastructure with continuous availability guarantees and clinical IoT segmentation. The FCC's spectrum allocation decisions directly impact equipment certification timelines for these deployments, delaying procurement until regulatory clarity emerges.
Enterprises dominate absolute spending while healthcare facilities climbs the fastest as medical IoT density accelerates.
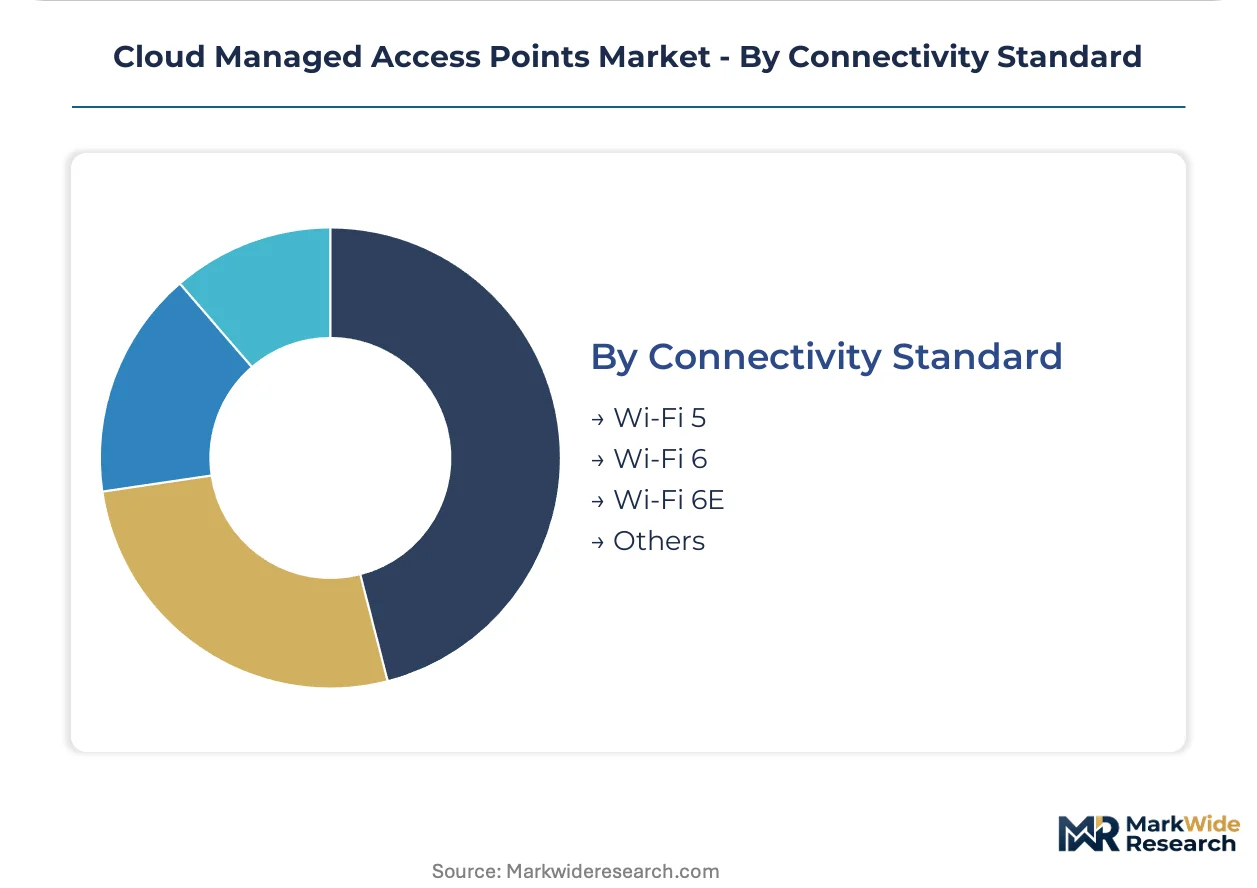
Connectivity Standard:
Supply concentration in radio silicon foundries constrains availability trajectories, with Wi-Fi 6E and Wi-Fi 7 production limited by Taiwan and South Korea fabrication capacity.
- Wi-Fi 5:802.11ac wave 2 equipment continues shipping for budget-constrained refresh cycles and legacy device compatibility requirements.
- Wi-Fi 6:OFDMA and target wake time improvements support high-density environments with improved battery life for mobile endpoints. Enterprise offices in the United States concentrate deployment for video collaboration suites, driven by hybrid work patterns requiring simultaneous high-bandwidth sessions.
- Wi-Fi 6E:6 GHz spectrum access delivers contiguous 160 MHz channels and reduced interference in greenfield deployments. Germany and Japan lead pilot implementations for conference room density targets exceeding Wi-Fi 6 capacity, constrained by ETSI and FCC certification reciprocity timelines.
- Others:Wi-Fi 7 (802.11be) and emerging standards occupy this residual category for early-adopter evaluations and testbed environments.
Wi-Fi 6 maintains the installed base while Wi-Fi 6E shows the steepest expansion trajectory as 6 GHz spectrum harmonization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare facilities concentrate procurement in Germany, Japan, and the United States, where enterprise campus densification and medical IoT compliance requirements reshape deployment priorities.
United States
Enterprise campuses in New York and financial services headquarters in London and Singapore drive SASE-aligned wireless procurement, with the FCC's Part 15 equipment authorization tightening emission mask requirements for 6 GHz standard power indoor access points. Healthcare systems delay refresh decisions pending regulatory clarity on automated frequency coordination database requirements.
Germany
Manufacturing facilities combine cloud-managed Wi-Fi with private 5G networks for deterministic latency control under Industry 4.0 automation requirements, with ETSI harmonized spectrum frameworks reducing cross-border deployment friction for multinational campus networks. Industrial clusters in Bavaria and North Rhine-Westphalia pilot Wi-Fi 7 implementations for conference room density targets exceeding Wi-Fi 6E capacity.
Japan
Enterprise IT departments in Tokyo and Osaka pilot Wi-Fi 7 multi-link operation implementations for video collaboration suites requiring simultaneous 2.4 GHz, 5 GHz, and 6 GHz transmission, with METI standards coordination accelerating local certification timelines. Manufacturing automation in the Chubu region around Nagoya anchors hybrid cloud deployment demand.
India
Urban infrastructure projects specify centralized network management for public Wi-Fi deployments under smart city mandates, with municipal procurement favoring cloud-native platforms for fiber-challenged extensions. Municipal corporations in Maharashtra and Karnataka concentrate outdoor access point deployment for stadium concourses and parking structure coverage.
United Kingdom
Financial services headquarters in London consolidate network management software with security service edge contracts under zero-trust architecture mandates, with the EU Cybersecurity Act's CE marking requirements shaping vendor certification roadmaps. Enterprise procurement teams bundle wireless LAN packages through value-added distributors.
Cloud Managed Access Points Market Competitive Environment
Player mix skews toward integrated networking incumbents with cloud-native management platforms, creating a tiered structure where full-stack infrastructure vendors hold pricing power over point-product specialists. Strategic archetypes include cloud-first platform operators, controller-legacy transition players, and AI-native challengers. Dominant competitive moves center on SaaS licensing migration and predictive analytics integration.
Within the cloud-first platform tier, Cisco and HPE Aruba exemplify integrated infrastructure vendors anchoring enterprise and healthcare verticals through unified policy management, while Juniper Networks occupies a position among AI-native challengers specializing in predictive operations for distributed campus environments.
| Leading Market Players |
|---|
| Cisco |
| HPE Aruba |
| Juniper Networks |
| CommScope |
| Extreme Networks |
| Fortinet |
| Ubiquiti |
| Ruckus Networks |
| Meraki |
| Others |
Value Chain & Pricing Dynamics
FCC Part 15 equipment authorization gates both supplier qualification timelines and price differentiation between certified and pre-certified hardware tiers, compressing margins for vendors awaiting 6 GHz emission mask clarity while rewarding early certification investments with premium positioning.
Pricing Analysis
Wi-Fi 6E-to-Wi-Fi 7 generational pricing gaps stratify procurement budgets across enterprise refresh cycles. Three-tier pricing structure across premium, standard, and economy levels segments by cloud-management feature depth and AI analytics bundling. Cost compression in economy tiers intensifies because legacy Wi-Fi 5 inventory liquidation accelerates. SMB buyers exhibit highest price sensitivity, while healthcare systems prioritize clinical-grade reliability over unit economics.
Supply Chain Analysis
Taiwan Strait maritime lanes and Kaohsiung port throughput chokepoints tether access point production schedules to geopolitical friction exposure. Radio silicon fabrication concentrates in Taiwan and South Korea, with final assembly drawing from China and Vietnam. Gallium arsenide substrate and PoE+ controller chip dependencies amplify single-source vulnerability for tri-band implementations. Distribution runs through value-added distributors serving systems integrators and direct enterprise procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare facility densification for medical IoT compliance marks this market as an early-cycle expansion story, with Wi-Fi 6E spectrum harmonization extending the runway before Wi-Fi 7 displacement.
For Market Incumbents: Compound cloud-native platform stickiness through predictive AI integration that raises switching costs for hospital systems. Deepen backward integration into radio firmware development to defend against silicon supply concentration. Prioritize ETSI-FCC certification reciprocity investment to accelerate multi-national campus deployment timelines.
For New Entrants and Emerging Players: Industrial IoT convergence gaps in manufacturing hybrid 5G-Wi-Fi architectures offer white-space entry where incumbents under-serve deterministic latency requirements. Target municipal smart city projects in India with cloud-native outdoor access point bundles. Pursue channel partnerships with security service edge vendors collapsing separate RFP processes.
For Investors and Strategic Acquirers: FCC automated frequency coordination database finalization reshapes the acquisition landscape by clearing regulatory overhang for healthcare vertical specialists. Five-to-ten year viability favors AI-native challengers with predictive operations capabilities over controller-legacy transition players. Monitor Wi-Fi 7 multi-link operation pilot outcomes in Germany and Japan as inflection indicators for generational replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| SaaS Licensing Migration | Per-access-point subscription models improve vendor cash flow predictability across healthcare and retail verticals. |
| AI-Powered Network Automation | Predictive radio resource optimization reduces mean time to resolution for distributed campus environments. |
| Hybrid Cloud Architecture Development | Local controller instances paired with cloud analytics satisfy HIPAA technical safeguards for hospital systems. |
| Private 5G Convergence Partnership | Dual-radio access points capture manufacturing demand for deterministic latency control under Industry 4.0. |
| ETSI Certification Reciprocity Investment | Harmonized European spectrum frameworks reduce cross-border deployment friction for multinational campus networks. |
Study Parameters
A standing panel of network infrastructure procurement officers, clinical biomedical engineers, manufacturing IT directors, and value-added distributor account managers provided ongoing calibration across the analysis window. Primary interview insights combined with FCC equipment authorization databases, ETSI harmonized standards filings, hyperscaler capex disclosures, and hospital GPO contract records. Bottom-up shipment tallies triangulated against top-down enterprise IT spending surveys.
Consistency checks validated volume and value outputs against external benchmarks including cloud-management platform activation data and Wi-Fi silicon foundry utilization reports. Segmentation modeling spanned product type, connectivity standard, deployment model, and end-user vertical across the projection horizon. CAGRs derived from replacement cycle timing, spectrum allocation trajectories, and medical IoT device density curves.
Underlying assumptions cover Wi-Fi 6E certification timeline stability and copper commodity price normalization, with deviation risk concentrated in Taiwan semiconductor supply continuity and FCC automated frequency coordination rule finalization. Practitioners should keep alternative scenarios live as geopolitical friction in East Asian fabrication hubs and regulatory clarity in United States spectrum management evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Fiber to the Premises Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Global Internet Transit Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Optical Networking Market
Network Technology
Global Network Management Market
Network Technology
5G CPE Device Market
Network Technology
Small Cell Networks Market
Network Technology
Europe Structured Cabling Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Germany Residential Gateway Market
Network Technology
DNS DHCP and IPAM Market