
 Application Delivery Controller (ADC) Market | 2026-2036
Application Delivery Controller (ADC) Market Size, Share, and Industry Trends Forecast 2026-2036
Application Delivery Controller (ADC) Market Analysis
Subscription-based financing and managed service leases are reconfiguring how mid-market enterprises access ADC capabilities without capital expenditure commitments. F5 Networks leverages extensive hardware-software integration to sustain premium positioning in high-throughput environments. Kemp Technologies anchors its competitive stance through specialized load-balancing solutions tailored to Microsoft-centric deployments. A10 Networks differentiates via security-hardened platforms that converge DDoS protection with traffic management functions.
An Application Delivery Controller is a network appliance or software platform that optimizes application performance through Layer 4-7 load balancing, SSL/TLS offloading, and TCP connection management, typically processing traffic at 10 Gbps to 100 Gbps throughput tiers. Its primary commercial purpose is ensuring high availability, security, and responsive user experience for web-facing and internal business applications. Cloud-based deployment models are capturing accelerated enterprise interest as hybrid work patterns persist and data gravity shifts toward distributed architectures. Security service types command premium positioning as organizations consolidate networking and cybersecurity budgets under unified procurement frameworks. Load balancing remains the foundational service segment, though web acceleration functions are gaining traction among e-commerce and media delivery operators.
FCC guidelines on communications infrastructure resilience, EU NIS2 Directive mandates for critical service providers, and ISO 27001 certification requirements collectively shape ADC product roadmaps and vendor qualification criteria. These frameworks compel encryption standards, audit logging capabilities, and geographic data residency controls that directly influence procurement specifications. Stakeholders must evaluate whether their ADC architecture can satisfy converging network performance mandates and cybersecurity compliance obligations without fragmenting operational oversight.
Market Dynamics
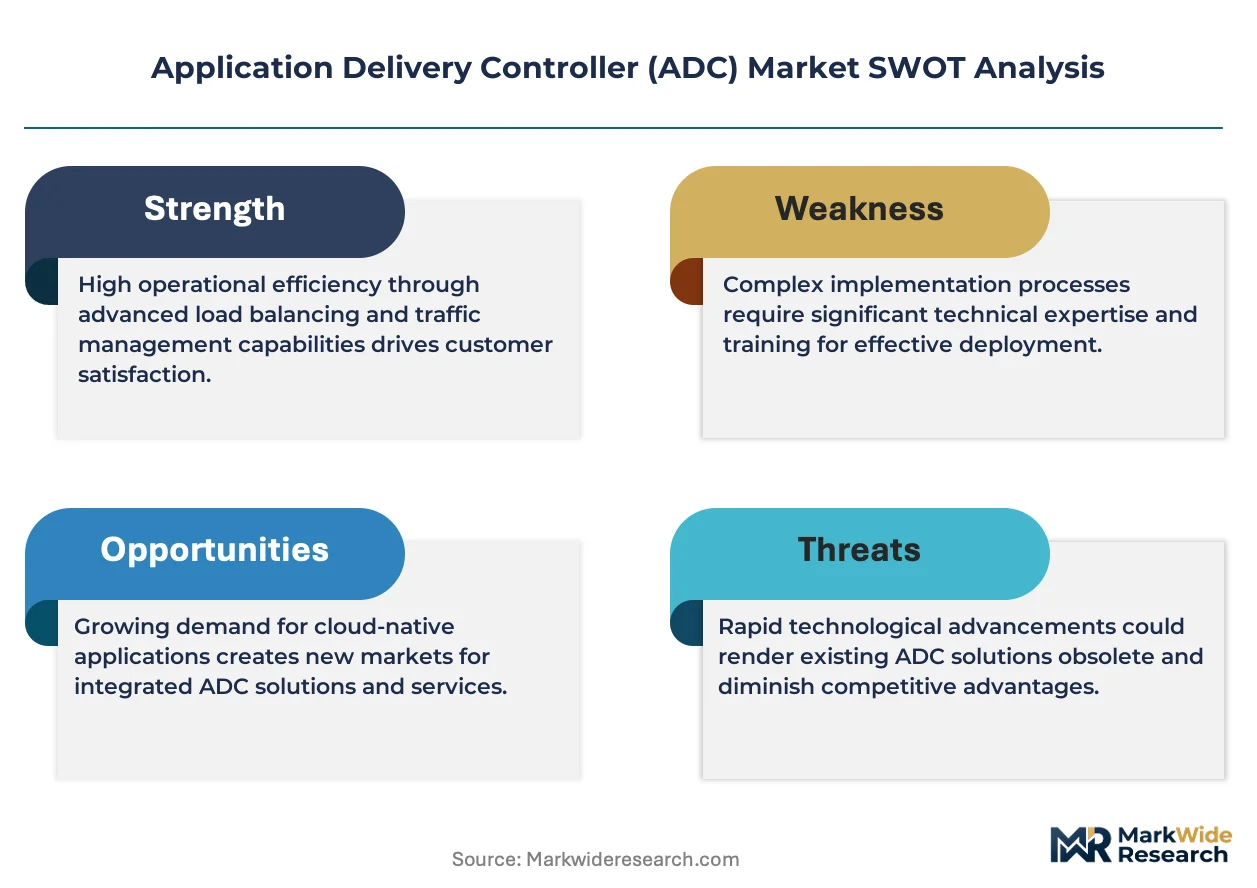
Cloud migration by financial services firms is expanding ADC procurement as hybrid architectures demand unified traffic management across on-premise and distributed cloud footprints. The EU Cybersecurity Act and NIS2 Directive are tightening resilience requirements for critical infrastructure operators, forcing vendors to embed compliance-ready encryption and audit capabilities into core platforms.
Growth Catalysts
- EU NIS2 Directive:Mandatory resilience standards for critical service providers are accelerating replacement cycles among energy and transport operators who must deploy ADC platforms with embedded security telemetry by regulatory deadlines.
- Financial services cloud migration:Banks and insurers modernizing core systems are procuring ADC solutions to manage traffic across multi-cloud environments while maintaining sub-millisecond latency for trading applications.
- SSL/TLS offloading specialization:Encryption processing at 100 Gbps throughput tiers is reducing server CPU overhead for e-commerce operators handling peak transaction volumes during seasonal demand spikes.
Market Restraints
- Specialized engineering talent scarcity:Shortages of professionals skilled in Layer 4-7 protocol optimization and certificate lifecycle management are extending deployment timelines and inflating implementation costs.
- Silicon supply concentration:Dependence on advanced semiconductor fabrication in Taiwan and South Korea creates vulnerability for hardware-dependent ADC appliances during geopolitical disruptions.
- Open-source load balancing substitution:NGINX and HAProxy deployments in cloud-native environments are displacing commercial ADC seats among DevOps-centric organizations prioritizing cost reduction over integrated security.
Strategic Opportunities
- Edge computing convergence:ADC platforms that hybridize traffic management with container orchestration are capturing emerging demand from retail and manufacturing operators deploying micro-datacenters at network peripheries.
- Managed service leases:Mid-market enterprises in Germany and France are adopting subscription-based ADC access to eliminate capital expenditure while maintaining enterprise-grade availability.
- ISO 27001 certification alignment:Vendors pre-integrating audit logging and geographic data residency controls are qualifying for accelerated procurement by defense and healthcare contractors under unified cybersecurity frameworks.
Industry Challenges
- Multi-vendor certificate management complexity:Enterprises operating heterogeneous ADC estates face operational friction synchronizing TLS certificate renewals across F5, A10, and Kemp platforms with differing automation APIs.
- Hybrid architecture integration timelines:Six-to-nine month deployment cycles for unified on-premise and cloud ADC fabrics are delaying ROI realization and straining IT project governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Delivery Controller (ADC) Market |
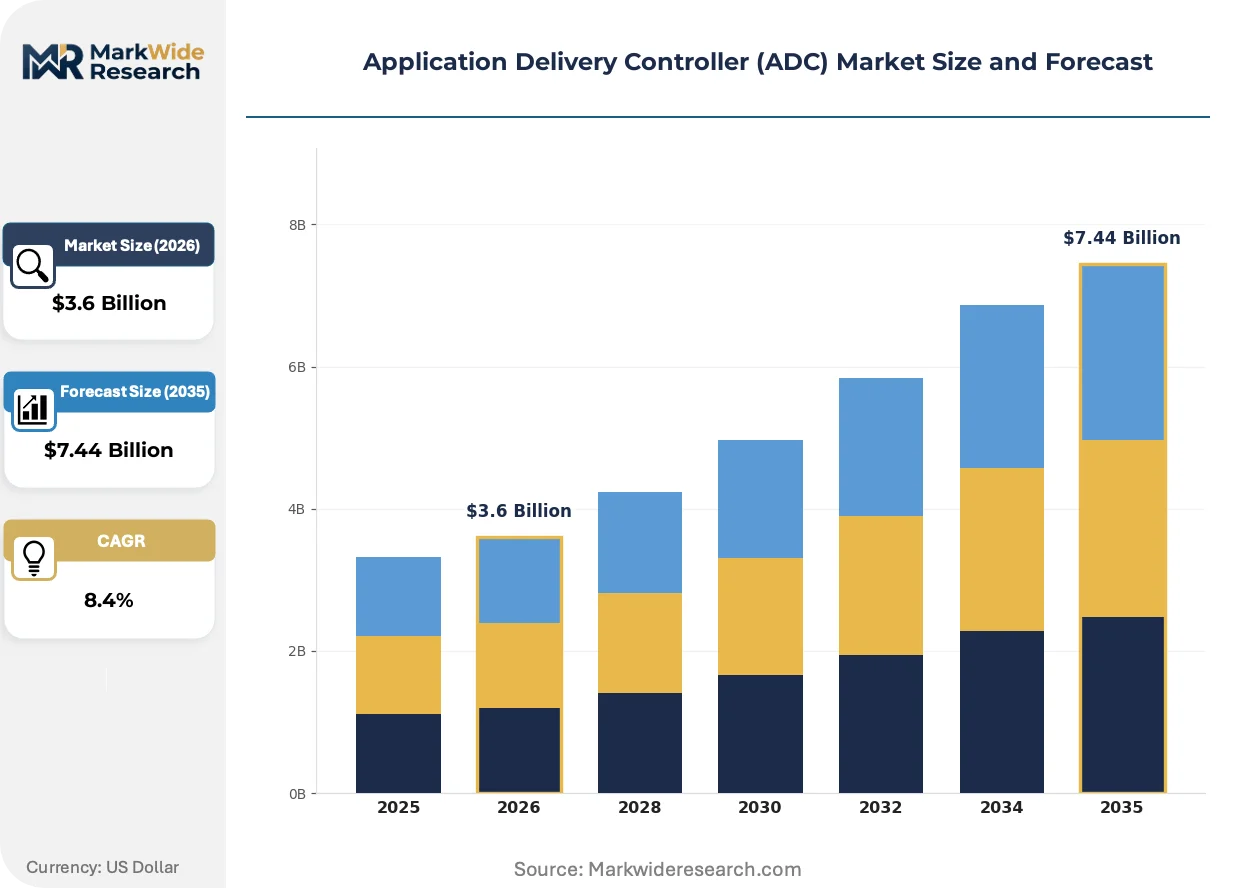
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $7.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Service Type: Load Balancing, SSL Offloading, Web Acceleration, Security End User: Telecommunications, E-Commerce, Healthcare, Education Solution: Traffic Management, Security Solutions, Performance Acceleration, Monitoring Tools |
| Companies Covered | Radware, Kemp Technologies, F5 Networks, Fortinet, Barracuda Networks, A10 Networks, Array Networks, Cisco Systems, Citrix Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Delivery Controller (ADC) Market Emerging Trajectories
ADC platforms are hybridizing with adjacent security and observability stacks as buyers consolidate networking and cybersecurity budgets under unified procurement frameworks. Three developments are compressing vendor differentiation and reshaping competitive positioning.
Container-native ADC architectures are hybridizing traditional hardware-software boundaries. Kubernetes ingress controllers now embed Layer 7 routing, SSL termination, and service mesh integration within cloud-native orchestration layers. Platform engineering teams at SaaS operators are deploying these controllers at scale, collapsing the distinction between infrastructure and application delivery tiers.
The EU Cybersecurity Act mandates Common Criteria certification for products handling critical infrastructure traffic. ADC vendors must now submit platforms for standardized security evaluation before qualifying for operator procurement in energy, transport, and finance sectors. German and French critical service providers are prioritizing pre-certified appliances to compress compliance timelines.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based service level agreements spanning availability, latency, and security incident response. Systems integrators and managed service providers are capturing intermediary value by wrapping multi-vendor ADC estates into unified operational contracts. This pattern concentrates procurement influence among UK and Netherlands-based IT services firms with established financial services practices.
Application Delivery Controller (ADC) Market Segmentation
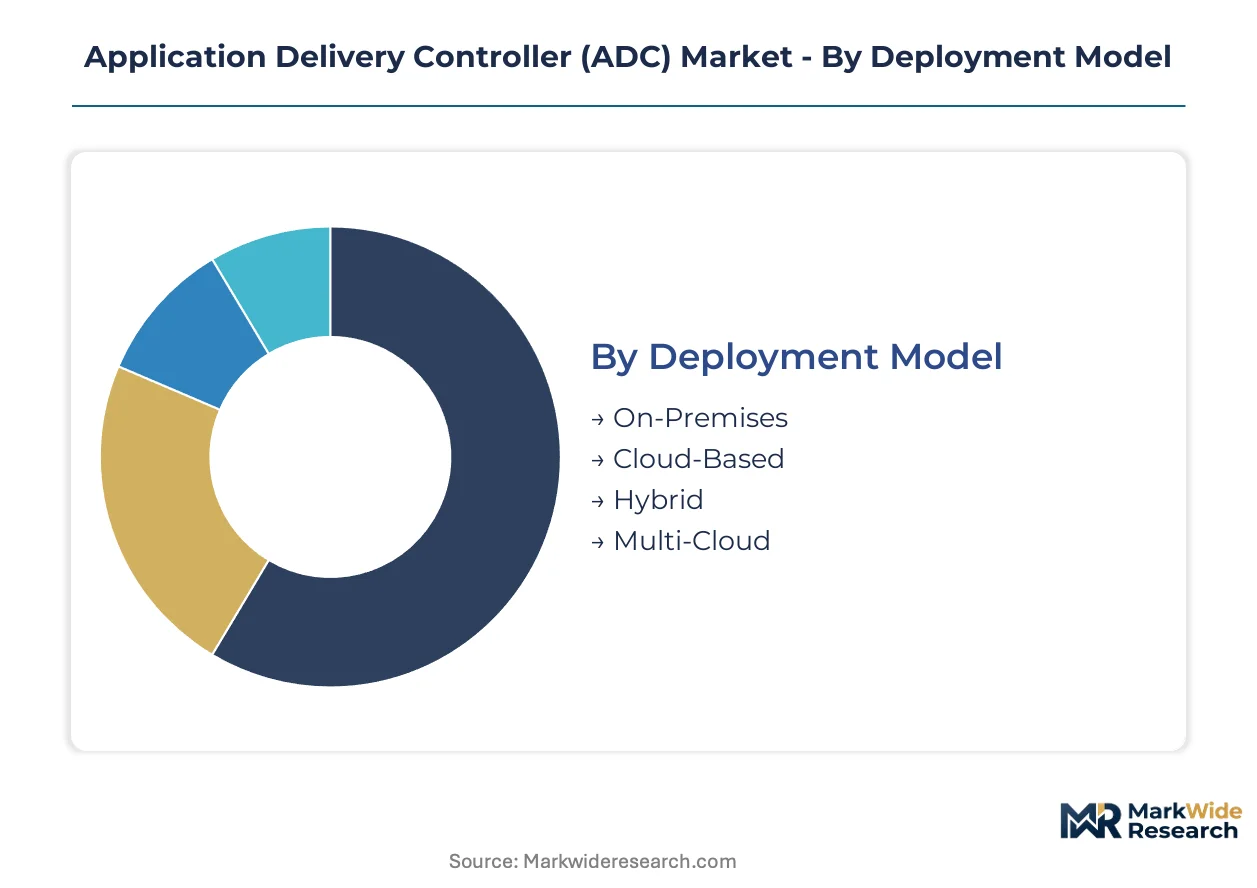
ADC procurement patterns diverge sharply across deployment architectures and service tiers. Buyers prioritize different capability bundles based on regulatory exposure, traffic volume, and internal engineering maturity.
Deployment Model:
Cost tier determines procurement authority and operational responsibility distribution across enterprise IT functions.
- On-Premises:Hardware appliances deployed within enterprise data centers deliver deterministic latency and full certificate lifecycle control. Financial services firms in Frankfurt and London maintain on-premise ADC estates for trading floor applications where sub-millisecond response is non-negotiable. Regulatory mandates from the EU NIS2 Directive reinforce preference for physically controlled encryption endpoints among critical infrastructure operators.
- Cloud-Based:SaaS-delivered ADC functions scale elastically with traffic spikes without capital deployment. E-commerce operators handling seasonal demand volatility in the United Kingdom and France are migrating core traffic management to cloud-native platforms to align operational expenditure with revenue cycles. Vendor-managed infrastructure reduces certificate management burden for mid-market enterprises lacking dedicated Layer 4-7 engineering teams.
- Hybrid:Split architectures unify on-premise appliances with cloud-delivered capacity during peak loads. Manufacturing enterprises with distributed production facilities deploy hybrid models to maintain local control while bursting to cloud for global application delivery.
- Multi-Cloud:Abstraction layers normalize traffic management across AWS, Azure, and GCP footprints simultaneously. SaaS providers avoiding vendor lock-in standardize on multi-cloud ADC controllers to preserve portability across hyperscaler environments.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Service Type:
Application workload characteristics dictate which ADC functions command budget priority within unified procurement frameworks.
- Load Balancing:Layer 4-7 traffic distribution remains the foundational ADC capability, distributing requests across server pools to eliminate single points of failure. Healthcare systems in Germany and the Netherlands deploy health-check-enabled load balancing to maintain electronic medical record availability during infrastructure maintenance windows. TCP and HTTP connection management functions optimize server utilization for transactional applications.
- Security:Converged platforms embed DDoS mitigation, web application firewalling, and bot detection within traffic management pipelines. Energy sector operators under EU Cybersecurity Act obligations prioritize security-integrated ADC platforms to compress compliance certification timelines. Unified threat telemetry reduces operational friction between network and security operations centers.
- SSL Offloading:Dedicated hardware or software modules terminate TLS connections to free application server CPU cycles. High-volume transaction processors in financial services deploy 100 Gbps encryption offloading to maintain throughput during peak trading periods.
- Web Acceleration:Caching, compression, and TCP optimization reduce page load times for content-heavy applications. Media streaming services and online retailers leverage acceleration functions to improve conversion rates and viewer retention metrics.
Load Balancing anchors revenue contribution. Security is climbing the fastest as cybersecurity budgets consolidate with networking spend.
End User:
Customer type shapes performance requirements, compliance exposure, and procurement cycle timing.
- Telecommunications:Carrier-grade ADC deployments manage subscriber-facing services and internal operational support systems at massive scale. Mobile network operators in the United Kingdom and Germany process millions of concurrent sessions through geographically distributed ADC fabrics. 5G core network virtualization is expanding software-defined ADC procurement for network function virtualization environments.
- E-Commerce:Peak-driven traffic patterns demand elastic capacity and sub-second response guarantees during promotional events. Online retailers in France and the Netherlands prioritize SSL offloading and web acceleration to minimize cart abandonment during high-velocity transaction periods.
- Healthcare:Patient data protection mandates and 24/7 availability requirements dominate ADC specification. Hospital networks deploy high-availability clustering with automated failover to sustain electronic health record access during infrastructure incidents.
- Education:Budget-constrained institutions favor subscription-based access and simplified management interfaces. Universities with distributed campuses leverage cloud-based ADC to unify application delivery without dedicated network engineering staff.
Telecommunications commands the largest deal sizes. E-Commerce is expanding most quickly as digital transaction volumes accelerate.
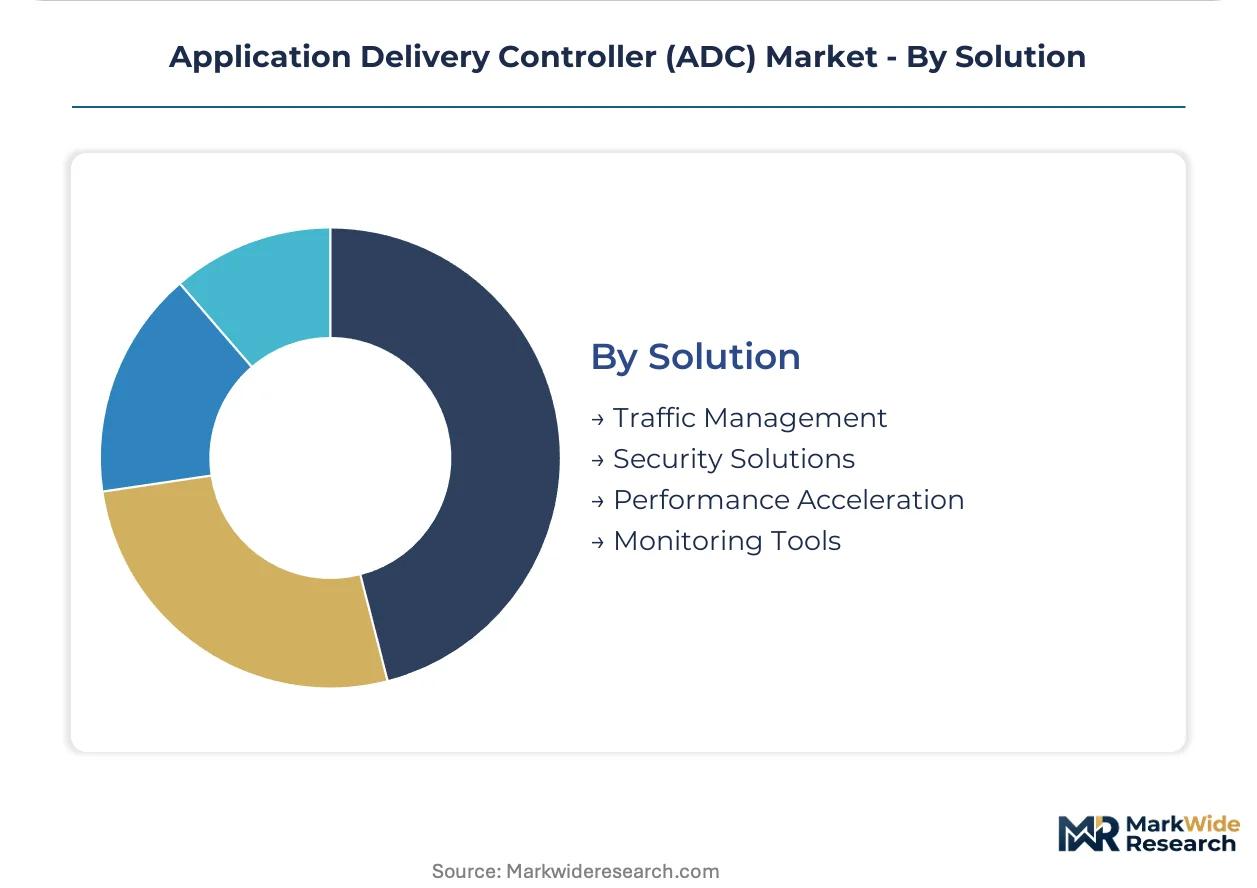
Solution:
Functional bundle depth determines vendor qualification and pricing tier placement.
- Traffic Management:Core Layer 4-7 routing, session persistence, and health monitoring capabilities form the baseline ADC value proposition. Enterprise data centers in Germany standardize on advanced traffic management for microservices architectures with dynamic service discovery requirements.
- Security Solutions:Integrated threat protection, access control, and encryption management address converged network-security procurement. Critical infrastructure operators prioritize pre-certified security-integrated platforms under EU Common Criteria evaluation schemes.
- Performance Acceleration:Protocol optimization, content caching, and compression functions target latency-sensitive applications. Video streaming platforms and financial trading systems deploy acceleration modules to maintain competitive user experience benchmarks.
- Monitoring Tools:Real-time telemetry, synthetic transaction testing, and predictive analytics enable proactive capacity management. DevOps teams integrate ADC monitoring with broader observability stacks for unified application performance management.
Traffic Management retains the broadest installed base. Security Solutions is rotating up the share rankings as compliance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a modest trade surplus in ADC hardware components, while the United Kingdom and France rely on imports for high-throughput appliances. Domestic assembly capacity concentrates in southern German industrial zones and Greater London technology corridors.
Germany
Frankfurt-based financial institutions drive procurement of sub-millisecond latency appliances for trading floor infrastructure. The EU NIS2 Directive compels energy operators in North Rhine-Westphalia to replace legacy load balancers with certified platforms by mandated deadlines. Munich and Stuttgart host manufacturing clusters assembling carrier-grade hardware for telecommunications export across Central Europe.
United Kingdom
London fintech operators and Edinburgh banking centers procure hybrid cloud ADC solutions for multi-tenant payment processing. FCC-equivalent Ofcom guidelines on communications resilience shape procurement specifications for national telecom infrastructure. The M4 corridor technology cluster sustains demand from SaaS providers scaling container-native traffic management for European customer bases.
France
Parisian e-commerce platforms and Lyon healthcare networks prioritize SSL offloading capabilities for patient data protection and high-velocity transaction processing. The EU Cybersecurity Act mandates Common Criteria certification for critical infrastructure deployments, compressing vendor qualification timelines. Toulouse aerospace and defense contractors in Occitanie specify ISO 27001-aligned platforms for secure supply chain communications.
Netherlands
Amsterdam data center operators and Rotterdam logistics platforms drive demand for multi-cloud traffic abstraction layers spanning AWS, Azure, and GCP footprints. GDPR data residency requirements influence encryption endpoint placement for financial services firms processing EU customer transactions. The Eindhoven high-tech systems cluster incubates specialized firmware development for embedded ADC silicon.
United States
New York financial exchanges and Silicon Valley SaaS operators anchor procurement of 100 Gbps throughput tiers for peak trading and streaming workloads. FCC guidelines on communications infrastructure resilience mandate audit logging capabilities for carrier-grade deployments. Northern Virginia data center concentration and Seattle cloud engineering hubs shape vendor product roadmaps for hybrid architecture integration.
Application Delivery Controller (ADC) Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Full-stack platform vendors with hardware-software integration dominate high-throughput financial services deployments. Specialized load-balancing vendors capture Microsoft-centric enterprise estates through deployment simplicity. Security-converged vendors embed DDoS mitigation and web application firewalling to qualify for critical infrastructure procurement. Competitive dynamics center on strategic partnerships with hyperscaler cloud platforms and vertical integration into custom silicon for encryption acceleration.
Within the security-integrated tier, Fortinet and Barracuda Networks exemplify vendors converging networking and cybersecurity budgets under unified procurement frameworks. F5 Networks occupies a position representing full-stack hardware-software integration for deterministic latency environments. A10 Networks anchors the high-throughput encryption specialization segment with platforms targeting 100 Gbps SSL offloading requirements. These archetypes reflect broader industry patterns of vendor consolidation and outcome-based service level agreement demands from enterprise buyers.
| Leading Market Players |
|---|
| Radware |
| Kemp Technologies |
| F5 Networks |
| Fortinet |
| Barracuda Networks |
| A10 Networks |
| Array Networks |
| Cisco Systems |
| Citrix Systems |
| Others |
Supply Flow & Price Mechanics
Silicon supply concentration in Taiwan and South Korea creates dual vulnerability for hardware-dependent ADC appliance vendors, compressing margins across premium throughput tiers while forcing buyers toward software-defined alternatives that bypass foundry bottlenecks entirely.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command positioning through FIPS 140-2 certification and 100 Gbps encryption throughput, while economy segments compete against open-source NGINX deployments. Cost compression in the mid-market tier is intensifying because hyperscaler-managed service offerings bundle ADC functions at scale. DevOps-centric organizations exhibit highest price sensitivity, whereas Frankfurt and London trading floors demonstrate lowest sensitivity due to latency requirements.
Supply Chain Analysis
Extended payment terms from Taiwanese foundry partners now stretch to 120 days for advanced ASIC procurement, straining working capital for hardware-integrated vendors. Manufacturing draws from Taiwan, South Korea, and southern Germany for high-throughput appliances, with FPGA and encryption accelerator silicon comprising critical input dependencies. Single-source vulnerability concentrates in 7nm and 5nm fabrication nodes for custom packet-processing silicon. Distribution runs through systems integrators and managed service providers who wrap multi-vendor estates into unified operational contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source load balancers threaten incumbent pricing power as Kubernetes-native controllers displace commercial seats among cloud-native enterprises, forcing vendors to defend through integrated security convergence and outcome-based service guarantees.
For Market Incumbents: Build certification moats through pre-integrated EU Cybersecurity Act compliance and ISO 27001-aligned audit telemetry. Pursue backward integration into custom encryption silicon to reduce foundry dependency for 100 Gbps throughput tiers. Consolidate channel control by acquiring managed service providers with established financial services practices in London and Frankfurt. For New Entrants and Emerging Players: Establish a beachhead in edge-computing micro-datacenter deployments for retail and manufacturing operators seeking container-native traffic management. Target mid-market German and French enterprises adopting subscription-based ADC access without capital expenditure commitments. Lead with simplified certificate lifecycle automation as the primary go-to-market angle against multi-vendor complexity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors security-converged platforms with critical infrastructure certification. Long-term viability hinges on hybrid architecture integration capabilities spanning on-premise and multi-cloud footprints. Watch hyperscaler partnership announcements as the inflection indicator for vendor survival.| Strategic Initiative | Industry Significance |
|---|---|
| Security Convergence | Embedded DDoS mitigation and WAF functions qualify vendors for EU NIS2 Directive procurement. |
| Managed Service Transition | Subscription-based leases capture mid-market demand in Germany and France without capital expenditure. |
| Custom Silicon Development | In-house encryption acceleration reduces dependency on Taiwanese foundry capacity for 100 Gbps tiers. |
| Multi-Cloud Abstraction | Normalization layers across AWS, Azure, and GCP footprints prevent vendor lock-in for SaaS providers. |
| Edge Computing Integration | Container-native controllers capture demand from retail operators deploying micro-datacenters at network peripheries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network architects, Layer 4-7 engineering leads, IT procurement officers at financial services firms, and managed service provider technical directors. Secondary validation drew from FCC infrastructure resilience guidelines, EU NIS2 Directive implementation timelines, Common Criteria certification databases, and hyperscaler capex disclosures. Bottom-up sizing of deployment models and service types was triangulated against top-down industry expenditure estimates.
Calibration against historical adoption curves informed projections across the analysis window. Segmentation dimensions modeled include deployment architecture, service tier, end-user vertical, and solution bundle depth. CAGRs were derived from regression analysis of procurement cycle timing and replacement rate assumptions. Forecast inputs incorporated regulatory deadline impacts from EU Cybersecurity Act mandates and cloud migration velocity among banking and insurance operators.
Stress conditions across semiconductor supply disruption, open-source substitution acceleration, and critical infrastructure compliance timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise hybrid architecture adoption and certificate management automation penetration. Macroeconomic contraction, geopolitical trade restriction expansion, or breakthrough container-native performance parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Unified Network Management Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Industrial Wireline Networking Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
GCC Set-Top Box Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
CPE Router Market
Network Technology
Private LTE Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
2.4GHz Router Market
Network Technology
Passive Optical Network Market
Network Technology
Lit Fiber Market