
 Fiber to the Home (FTTH) Market | 2026-2036
Fiber to the Home (FTTH) Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber to the Home (FTTH) Market Analysis
Chinese fiber optic cable production is shifting toward higher-count ribbon fiber configurations to meet dense urban deployment schedules. Corning Inc. leverages its captive glass preform supply to anchor North American pricing power. Huawei Technologies Co., Ltd. competes through integrated optical line terminal and optical network terminal portfolios. ZTE Corporation specializes in cost-optimized GPON equipment for emerging market operators.
Fiber to the Home denotes a telecommunications architecture where optical fiber extends directly to individual premises, typically employing single-mode fiber with wavelengths of 1310 nm upstream and 1490 nm downstream to deliver gigabit symmetrical services. The primary purpose is eliminating copper-based bottlenecks in last-mile connectivity to support bandwidth-intensive applications. Passive fiber deployments dominate capital expenditure allocation due to reduced active electronics in field conditions. Multi-Dwelling Units represent the fastest-growing offering segment as urbanization concentrates subscriber acquisition costs. GPON technology maintains installed-base leadership while XGS-PON and WDM platforms capture upgrade cycles.
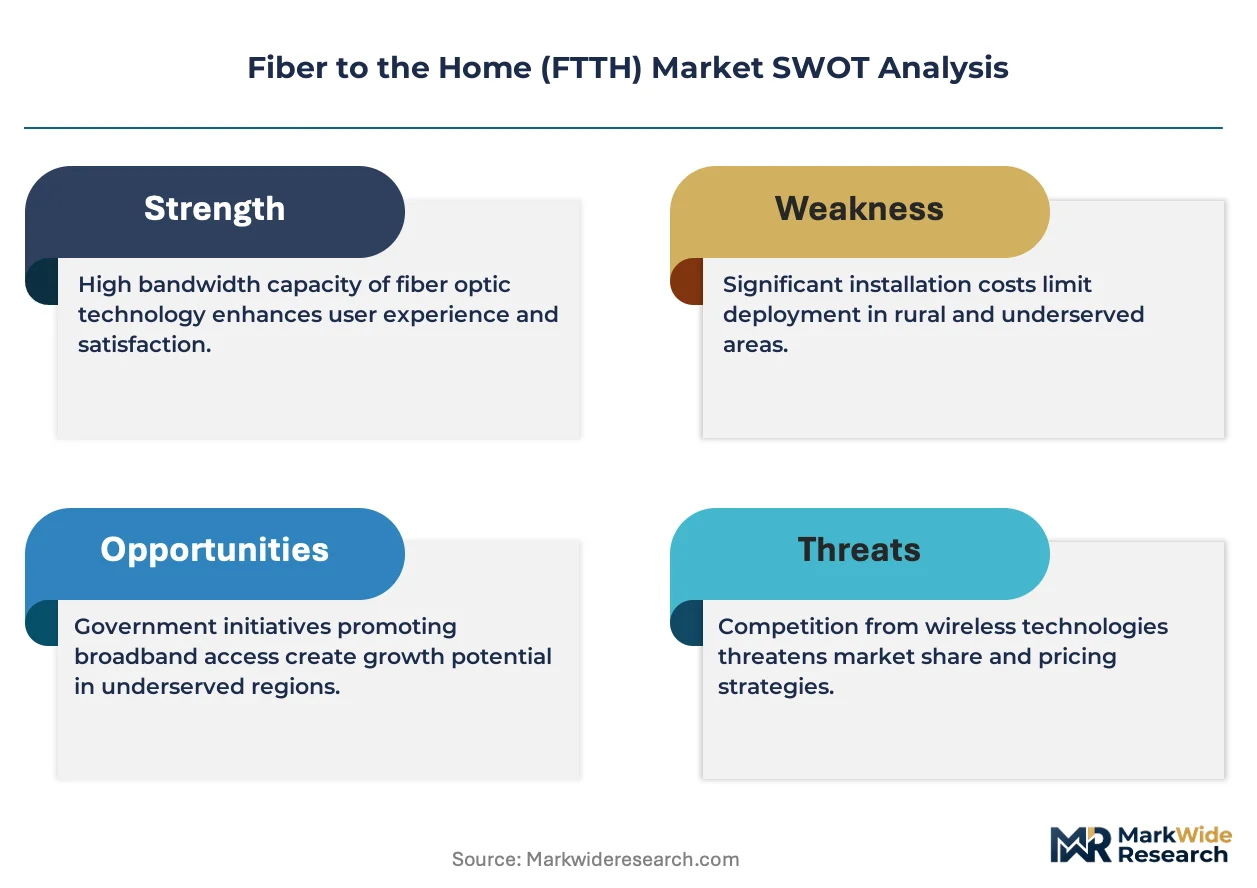
The FCC's broadband labeling rules and the EU's Gigabit Infrastructure Act shape transparency requirements and deployment timelines across their respective jurisdictions. China's MIIT enforces domestic fiber standards through GB-compliant certification that restricts non-approved equipment access. India's TRAI mandates open-access duct infrastructure to reduce last-mile deployment friction. Stakeholders must monitor spectrum allocation decisions for wireless integration alternatives and track municipal franchise agreement renegotiations that alter deployment economics.
Market Dynamics
The transition from GPON to XGS-PON architectures is compressing upgrade cycles and reallocating operator capital expenditure toward higher-capacity passive optical networks.
Growth Catalysts
- South Korea's gigabit mandate:Government infrastructure requirements accelerate residential fiber deployment timelines and standardize equipment specifications nationwide.
- China's three-tier network consolidation:State-backed carrier procurement concentration creates volume efficiencies that lower per-port equipment costs.
- Multi-Dwelling Unit urbanization:Dense subscriber clustering in apartment complexes reduces per-premises deployment labor and materials.
Market Restraints
- Glass preform supply concentration:Captive vertical integration among preform manufacturers limits pricing leverage for independent cable producers.
- GB certification barriers:China's MIIT equipment approval process restricts market access for non-domestic optical line terminal suppliers.
- Right-of-way access friction:Municipal franchise negotiations delay aerial and underground deployment schedules in contested jurisdictions.
Strategic Opportunities
- India's open-access duct mandate:TRAI infrastructure-sharing requirements reduce last-mile civil works duplication for new market entrants.
- WDM-PON convergence:Wavelength-division multiplexing integration with existing fiber plant enables wholesale capacity leasing to mobile operators.
- Rural broadband subsidy programs:Universal service fund mechanisms in underserved geographies offset low-density deployment economics.
Industry Challenges
- Fusion splicing technician scarcity:Specialized fiber termination skills constrain field crew scaling during accelerated build-out phases.
- Legacy copper decommissioning complexity:Stranded asset retirement obligations and customer migration coordination extend dual-network maintenance periods.
- Interoperability certification delays:Multi-vendor optical network terminal integration testing prolongs procurement-to-activation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber to the Home (FTTH) Market |
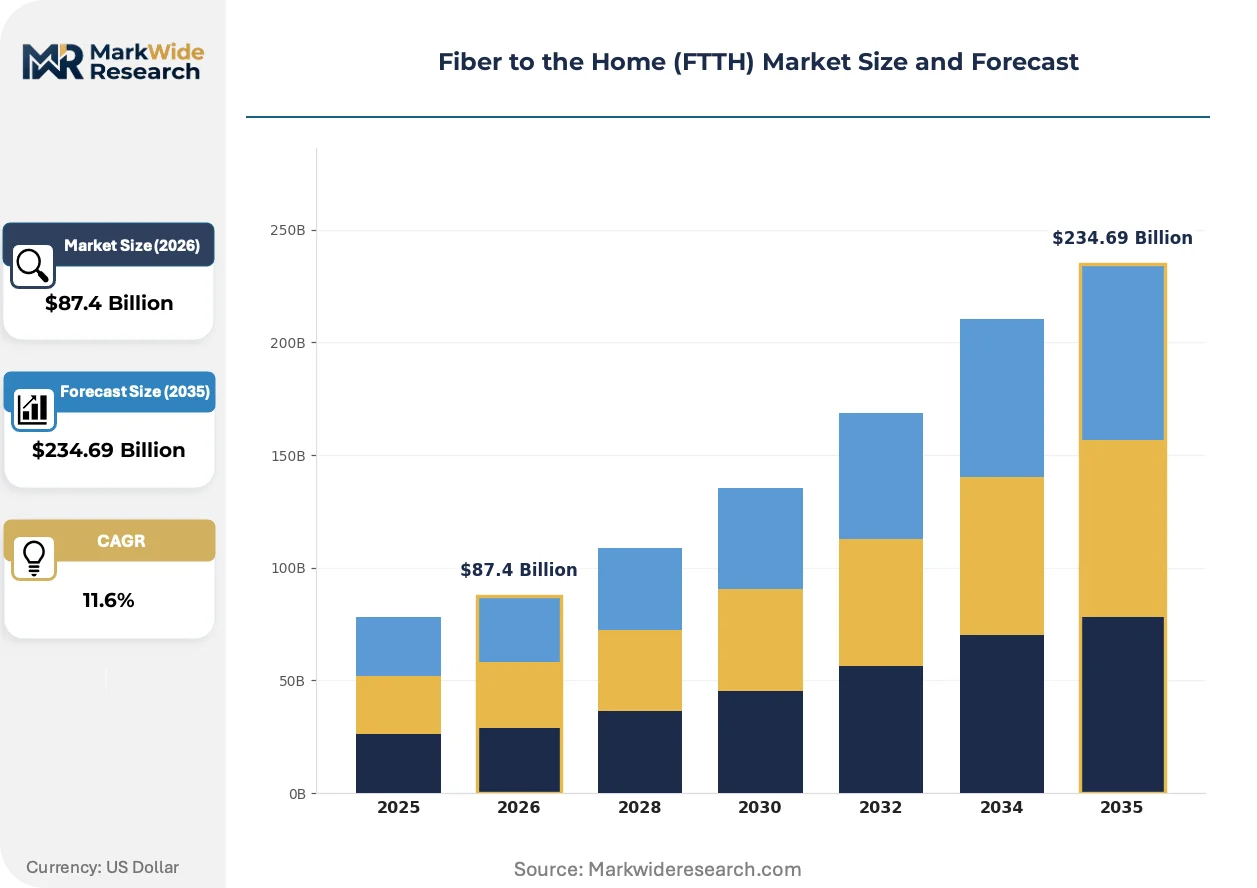
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $234.69 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Active Fiber, Passive Fiber, Hybrid Fiber, Wireless Integration Offering: Single Family Units, Multi-Dwelling Units, Business/Enterprise Solutions, Rural Connectivity Technology: GPON, EPON, WDM, FTTH Mesh End User: Residential Customers, Commercial Establishments, Educational Institutions, Government Facilities |
| Companies Covered | AT&T Inc., Corning Inc., China Telecom Corp. Ltd., Huawei Technologies Co., Ltd., Nokia Corporation, China Mobile Ltd., Orange S.A., ZTE Corporation, Verizon Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber to the Home (FTTH) Market Emerging Trajectories
Equipment vendors and network operators are converging on higher-density fiber configurations and automated deployment methods to compress capital intensity per subscriber.
XGS-PON technology is expanding into metropolitan access networks by delivering 10 Gbps symmetrical capacity over existing single-mode fiber plant. Tier-1 operators in South Korea and Japan are standardizing on XGS-PON for new residential builds while scheduling GPON overlays for legacy node upgrades. The technology is expanding into mobile front-haul applications as 5G densification demands fiber-based latency guarantees.
The EU's Gigabit Infrastructure Act imposes binding coverage targets and streamlines permit-granting procedures for broadband deployment across member states. Member countries must designate single points of contact for civil works authorization and eliminate fees for network duplication in existing infrastructure. The regulation is accelerating municipal duct access negotiations in Germany and France where legacy copper retirement timelines face statutory compression.
Operators are consolidating procurement around pre-integrated optical line terminal and optical network terminal bundles to reduce interoperability testing burdens. Chinese state carriers now specify unified management platforms that lock in vendor ecosystems across provincial subsidiaries. This specification consolidation is most visible in procurement patterns from China Telecom and China Unicom where multi-year framework agreements favor integrated solution providers over component specialists.
Fiber to the Home (FTTH) Market Segmentation
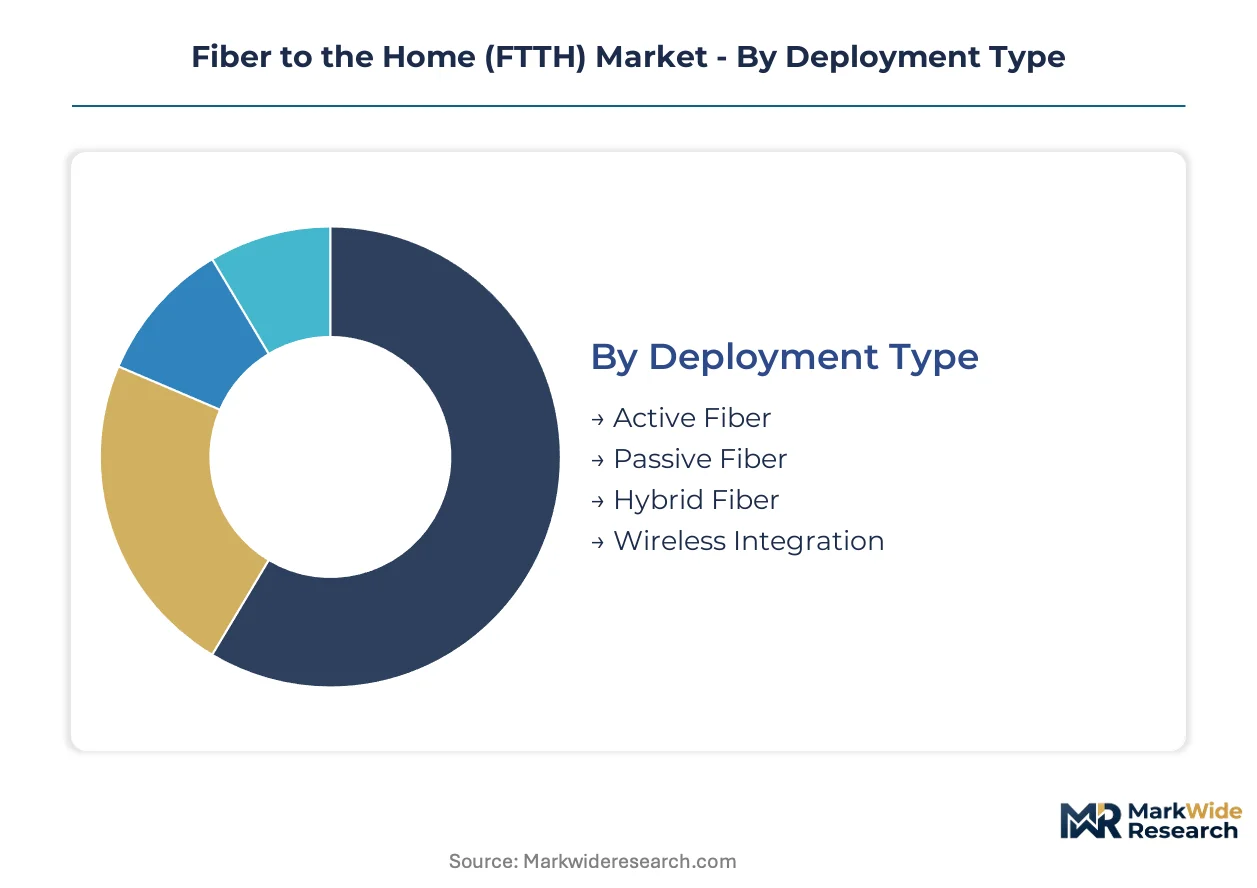
FTTH deployment economics hinge on matching infrastructure topology to subscriber density, building type, and regulatory environment. Segmentation reveals where capital concentrates and which technology transitions command procurement priority.
Deployment Type:
Capital allocation decisions favor passive architectures where electronics elimination reduces field maintenance liability.
- Active Fiber:Powered optical amplifiers and repeaters extend reach beyond standard PON limits. Demand clusters in rural South Korea where mountainous terrain stretches feeder distances beyond passive optical budget constraints.
- Passive Fiber:Unpowered splitters distribute optical signals without field electronics. This architecture dominates greenfield residential builds across China's tier-1 cities where density justifies pure fiber plant.
- Hybrid Fiber:Combines passive distribution with limited active elements at aggregation nodes. Operators in India's Maharashtra state deploy hybrid topologies to bridge urban-rural transition zones.
- Wireless Integration:Fixed wireless access complements fiber where trenching costs exceed radio deployment economics. This approach serves remote German municipalities under EU Gigabit Infrastructure Act coverage mandates.
Passive Fiber leads on scale; Wireless Integration leads on momentum.
Offering:
Subscriber acquisition cost per premise varies dramatically by building typology and tenancy structure.
- Multi-Dwelling Units:Apartment complexes enable single-drop fiber entry serving dozens of subscribers. Urbanization in Seoul and Shanghai concentrates procurement volume here as developers pre-wire new construction.
- Single Family Units:Detached homes require dedicated fiber drops and individual ONT placement. Deployment economics strain in Japanese suburban corridors where lot sizes expand and underground utility standards complicate trenching.
- Business/Enterprise Solutions:Symmetrical gigabit and 10-gigabit services with SLA guarantees. Financial districts in Singapore and Frankfurt drive specialized CPE procurement.
- Rural Connectivity:Low-density deployments subsidized through universal service mechanisms. India's BharatNet program and US Rural Digital Opportunity Fund shape equipment specifications.
Multi-Dwelling Units command procurement volume; Rural Connectivity climbs fastest on subsidy expansion.
Technology:
Upgrade cycles compress as operators balance legacy GPON harvest against XGS-PON and WDM migration timelines.
- GPON:2.5 Gbps downstream, 1.25 Gbps upstream asymmetrical capacity over single fiber. Installed base leadership persists in legacy Chinese provincial networks where replacement schedules extend through decade-end.
- EPON:Ethernet-native PON popular in cable operator fiber overlays. North American MSOs favor EPON for DOCSIS backhaul integration in legacy HFC plant conversions.
- WDM:Wavelength-division multiplexing dedicates optical channels per subscriber or service. Metro backhaul and 5G fronthaul applications in Tokyo and London drive port demand.
- FTTH Mesh:Distributed optical switching enabling flexible service provisioning. Emerging in smart city pilots where building automation and residential broadband converge on unified fiber plant.
GPON retains installed base dominance; WDM gains share fastest on mobile fronthaul requirements.
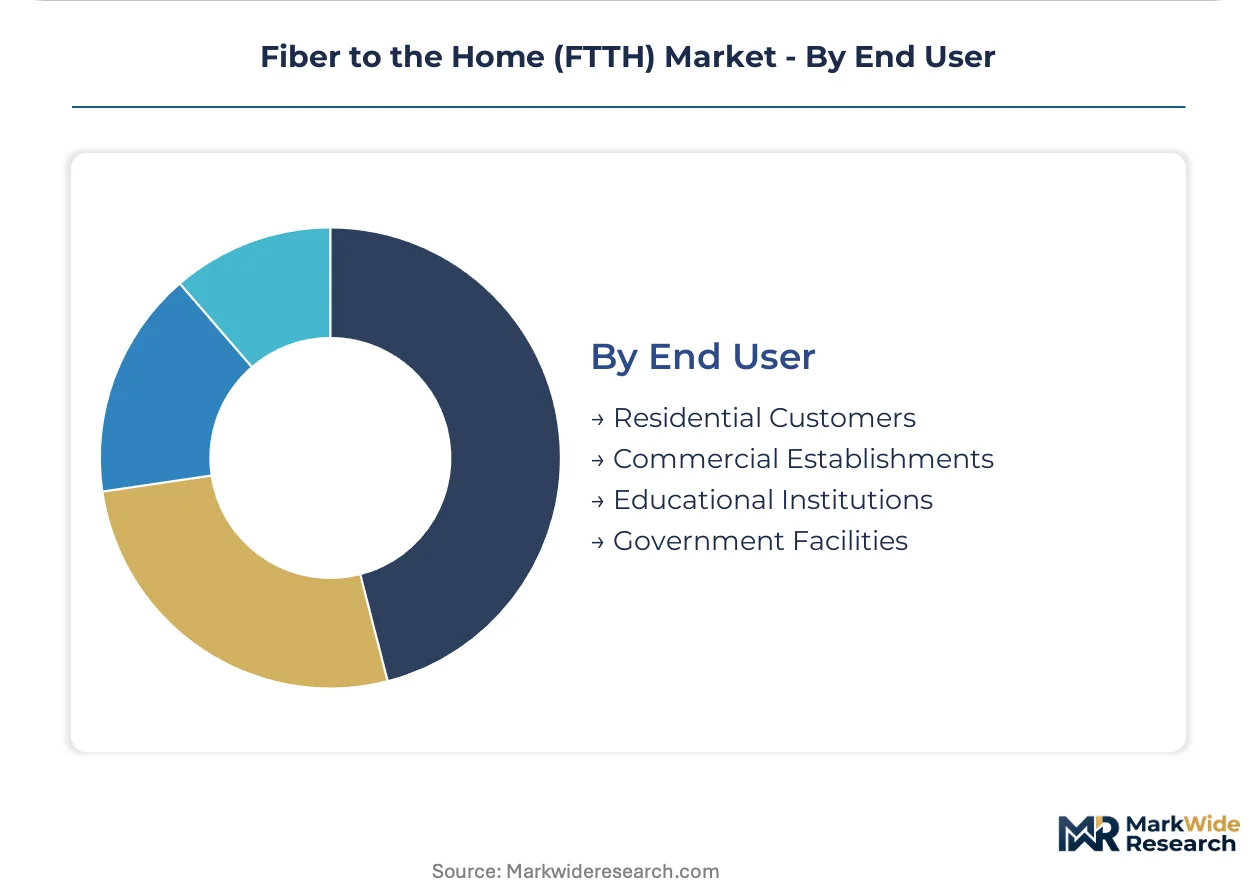
End User:
Service level differentiation and pricing power diverge sharply across customer categories with distinct bandwidth consumption profiles.
- Residential Customers:Mass-market gigabit symmetrical services with consumer-grade ONTs. South Korea's gigabit mandate standardizes equipment across this segment nationwide.
- Commercial Establishments:Retail, hospitality, and professional services requiring dedicated bandwidth with business continuity provisions. Demand concentrates in Seoul Gangnam and Shanghai Pudong commercial corridors.
- Educational Institutions:Campus-wide fiber with research network peering requirements. Japanese national universities and German technical institutes drive high-port-count OLT procurement.
- Government Facilities:Secure fiber plant with classified transmission requirements. China's MIIT GB certification restricts supplier access for sensitive installations.
Residential Customers anchor volume scale; Commercial Establishments expand most quickly on service premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in fiber deployment favors jurisdictions with streamlined permitting and subsidized infrastructure programs, drawing equipment procurement toward South Korea, China, Germany, and India where compliance costs diverge sharply from markets with fragmented municipal oversight.
South Korea
Government mandates for gigabit-ready infrastructure accelerate residential fiber timelines nationwide. The country's Ministry of Science and ICT enforces universal service obligations that standardize equipment specifications across all provinces. Seoul Capital Area concentrates procurement volume as telecom operators overlay XGS-PON systems across dense apartment complexes.
China
State-backed carrier consolidation creates volume efficiencies that compress per-port equipment costs for passive optical networks. MIIT enforces GB-compliant certification that restricts market access for non-domestic optical line terminal suppliers. Yangtze River Delta cities including Shanghai and Hangzhou drive ribbon fiber demand for dense urban deployment schedules.
Germany
The EU's Gigabit Infrastructure Act imposes binding coverage targets that accelerate municipal duct access negotiations. Single points of contact for civil works authorization eliminate fees for network duplication in existing infrastructure. Frankfurt and Munich commercial corridors drive specialized CPE procurement for symmetrical enterprise services.
India
TRAI's open-access duct mandate reduces last-mile civil works duplication for new market entrants in Maharashtra and Karnataka. Universal service fund mechanisms offset low-density deployment economics in rural geographies. BharatNet program specifications shape equipment requirements for state-led fiber expansion into underserved districts.
United States
FCC broadband labeling rules impose transparency requirements that standardize consumer-facing service disclosures. Rural Digital Opportunity Fund subsidies redirect procurement toward cost-optimized GPON and XGS-PON platforms. Texas and California metro markets concentrate multi-dwelling unit pre-wiring activity as developers integrate fiber during new construction.
Fiber to the Home (FTTH) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless integration and rural subsidy capture. The vendor base stratifies across integrated solution providers, component specialists, and state-affiliated carriers with captive procurement channels. Three archetypes dominate: glass preform-integrated cable manufacturers, optical line terminal portfolio vendors, and cost-optimized equipment specialists serving emerging markets. Competitive moves concentrate on multi-year framework agreements with state carriers and backward integration into preform supply to defend margin position.
Within the integrated solution tier, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify the state-backed vendor archetype with unified management platform specifications. Corning Inc. anchors the premium-tier vector through captive glass preform supply. These three companies represent distinct strategic positions: equipment integration, cost optimization, and upstream materials control.
| Leading Market Players |
|---|
| AT&T Inc. |
| Corning Inc. |
| China Telecom Corp. Ltd. |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| China Mobile Ltd. |
| Orange S.A. |
| ZTE Corporation |
| Verizon Communications Inc. |
| Others |
Supply Flow & Price Mechanics
Fusion splicing technician scarcity in South Korea and Japan widens pricing spreads between premium-certified deployments and economy-tier installations. Labor-cost differentials across these markets force operators to stratify procurement between high-skill XGS-PON overlays and basic GPON extensions.
Pricing Analysis
Distributor margins on optical line terminals compress as Chinese state carriers consolidate procurement through direct framework agreements with integrated solution providers. Three-tier pricing structure across premium, standard, and economy levels reflects GB certification tiers, with MIIT-compliant equipment commanding substantial premiums over uncertified alternatives. Pricing pressure stems from ribbon fiber volume scale in Yangtze River Delta deployments. Municipal operators exhibit highest price sensitivity; tier-1 state carriers demonstrate lowest sensitivity due to captive procurement channels.
Supply Chain Analysis
Regional distribution centers in Shanghai, Shenzhen, and Seoul anchor hub-and-spoke patterns for optical network terminal fulfillment. Glass preform supply concentrates in the United States, Japan, and China, with Corning's captive production anchoring North American availability. Raw material dependencies span high-purity silica, rare-earth doping elements, and specialized polymer coatings. Single-source vulnerability in preform supply creates structural risk for independent cable producers. Distribution runs through carrier-direct channels and tier-1 distributor networks serving provincial subsidiaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FTTH market represents a late-cycle quality story as operators prioritize XGS-PON specifications over legacy GPON harvest strategies. Demand-shift toward symmetrical 10-gigabit services justifies premium equipment positioning.
For Market Incumbents: Acquire captive glass preform production capacity to secure margin position against independent cable competitors. Consolidate around unified management platforms that lock in multi-year framework agreements with China Telecom and China Unicom. Threat from emerging cost-optimized vendors in India demands certification investment in MIIT GB standards. Channel control through provincial subsidiary relationships remains the critical defensive lever. For New Entrants and Emerging Players: The premium-to-economy tier price gap in rural Indian connectivity opens white-space opportunity beneath state-carrier procurement floors. Target Maharashtra and Karnataka open-access duct deployments where TRAI infrastructure-sharing reduces civil works barriers. Fixed wireless access integration in remote German municipalities offers secondary entry point under EU Gigabit Infrastructure Act coverage mandates. Go-to-market angle should emphasize cost-optimized GPON equipment with simplified ONT bundles. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists lacking backward integration into preform supply. Long-term viability over the coming decade favors integrated solution providers with state-carrier relationships and unified platform specifications. Acquisition target archetype: mid-scale optical line terminal vendors with MIIT certification pathways and existing China Mobile provincial contracts. Signal to watch is municipal franchise agreement renegotiation velocity in contested US jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Technology Migration | Enables 10 Gbps symmetrical capacity over existing single-mode fiber plant in Seoul and Tokyo corridors. |
| Backward Integration into Preform Supply | Secures captive glass supply against pricing leverage from independent cable producers in North America. |
| Unified Management Platform Consolidation | Locks vendor ecosystems across China Telecom and China Unicom provincial subsidiaries. |
| Open-Access Duct Infrastructure Capture | Reduces last-mile civil works duplication for new entrants under India's TRAI mandate. |
| Rural Broadband Subsidy Program Alignment | Offsets low-density deployment economics through BharatNet and US Rural Digital Opportunity Fund mechanisms. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged network planning executives at tier-1 operators, optical equipment procurement managers, fiber deployment contractors, regulatory affairs specialists at MIIT and TRAI, and municipal franchise negotiators. Secondary validation drew from carrier capex disclosures, equipment certification databases, customs trade data for fiber optic cable imports, and FCC broadband deployment reports. Bottom-up subscriber penetration models triangulated against top-down infrastructure spend forecasts.
Historical reference periods anchored the projection horizon to observed upgrade cycle compression from GPON to XGS-PON. Segmentation dimensions modeled span deployment topology, building typology, technology generation, and end-user category. CAGRs derived from equipment port shipment trajectories and per-premise deployment cost curves. Forecast inputs incorporated ribbon fiber density trends and municipal permitting velocity indices.
The model assumes a particular technology adoption path; alternative pathways for WDM-PON convergence would alter the outlook. Forecasts reflect assumptions regarding state-carrier procurement consolidation, technician workforce scaling, and subsidy program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Mobile Network Optimization Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Global LWAN Market
Network Technology
US Private 5G Network Market
Network Technology
Hyperconnectivity Market
Network Technology
ISP Management Systems Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Network Packet Broker Market
Network Technology
Network Devices Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Intelligent Network Management Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Malaysia Wireless Router Market