
 Stabilized Starch Market | 2026-2036
Stabilized Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Stabilized Starch Market Analytics
Pharmaceutical formulation demand is hardening as tablet binders and controlled-release matrices gain preference over conventional excipients. Cargill leverages its agricultural origination network to secure waxy corn supply chains for high-amylopectin stabilized grades. Ingredion sustains R&D intensity across modified starch hydrophobic derivatives that improve active pharmaceutical ingredient stability. Roquette Frères anchors European pharmaceutical-grade production through its pea-starch extraction platform in northern France.
Stabilized starch denotes chemically or physically treated native starch that resists retrogradation, syneresis, and thermal breakdown, typically achieving paste clarity above 80% transmittance and viscosity stability across pH 3–9 for industrial processing reliability. Its primary purpose centers on delivering predictable rheological performance in processed foods, oral dosage forms, and topical cosmetic bases where unmodified starch would gel, weep, or lose binding strength. Modified starch occupies the largest volume position across product types, though resistant starch is gaining fastest as gut-health positioning drives reformulation in functional food segments. Cold water soluble starch commands premium positioning within beverage and instant-dry-mix applications where heat-free processing reduces energy input and preserves heat-labile actives.
FDA food-additive regulations under 21 CFR 172.892 govern chemical modification limits and residual reagent thresholds, directly constraining process chemistry choices and import qualification pathways for non-US manufacturers. REACH registration requirements in Europe mandate full toxicological dossiers for chemically modified starch substances, elevating compliance costs that favor larger producers with dedicated regulatory affairs capacity. India's FSSAI additive approval process, aligned with CODEX but with country-specific purity schedules, creates a parallel compliance track for suppliers targeting its expanding processed food sector. Stakeholders must monitor evolving pharmaceutical excipient monograph harmonization between USP-NF, EP, and JP standards, as divergence in heavy-metal or microbial limits could fragment qualification requirements across supply chains.
Market Dynamics
REACH registration dossiers for chemically modified starch substances are consolidating competitive advantage toward producers with dedicated regulatory affairs infrastructure, compressing mid-tier participation across European pharmaceutical supply chains.
Growth Catalysts
- Pharmaceutical excipient harmonization:USP-NF, EP, and JP monograph alignment is reducing dual-qualification burdens for tablet binder suppliers targeting multinational drug manufacturers.
- India PLI scheme incentives:Processed food infrastructure subsidies are accelerating modified starch uptake in instant noodle and ready-to-eat segments across Maharashtra and Gujarat manufacturing corridors.
- Resistant starch gut-health positioning:Functional food reformulation is pulling chemically stabilized variants into prebiotic bakery and beverage applications previously served by fiber additives.
Market Restraints
- Waxy corn supply concentration:North American agricultural origination networks control high-amylopectin cultivar availability, exposing European and Asian processors to origination risk and freight cost volatility.
- REACH toxicological dossier costs:Full substance registration under ECHA mandates elevates compliance expenditure that favors multi-billion-euro chemical conglomerates over regional starch modifiers.
- Native starch price anchoring:Unmodified tapioca and maize alternatives cap pricing power in emerging-market food applications where cost sensitivity overrides performance premiums.
Strategic Opportunities
- Cold water soluble starch beverage penetration:Heat-free processing demand in instant coffee and protein shake dry mixes is opening premium positioning for pre-gelatinized variants with sub-ambient dissolution kinetics.
- Pea-starch pharmaceutical-grade extraction:European pulse protein infrastructure overcapacity is enabling dedicated pea-starch lines for allergen-free excipient certification targeting pediatric and geriatric dosage forms.
- FSSAI additive approval acceleration:India's streamlined CODEX-aligned purity schedules are compressing import qualification timelines for modified starch suppliers establishing local blending operations.
Industry Challenges
- Excipient GMP certification timelines:IPEC-PQG pharmaceutical-grade audits require 18-24 month facility qualification cycles that delay revenue recognition for new production lines.
- Retrogradation control technician scarcity:Specialized rheology and paste stability expertise resides concentrated among legacy modified starch R&D teams approaching retirement density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stabilized Starch Market |
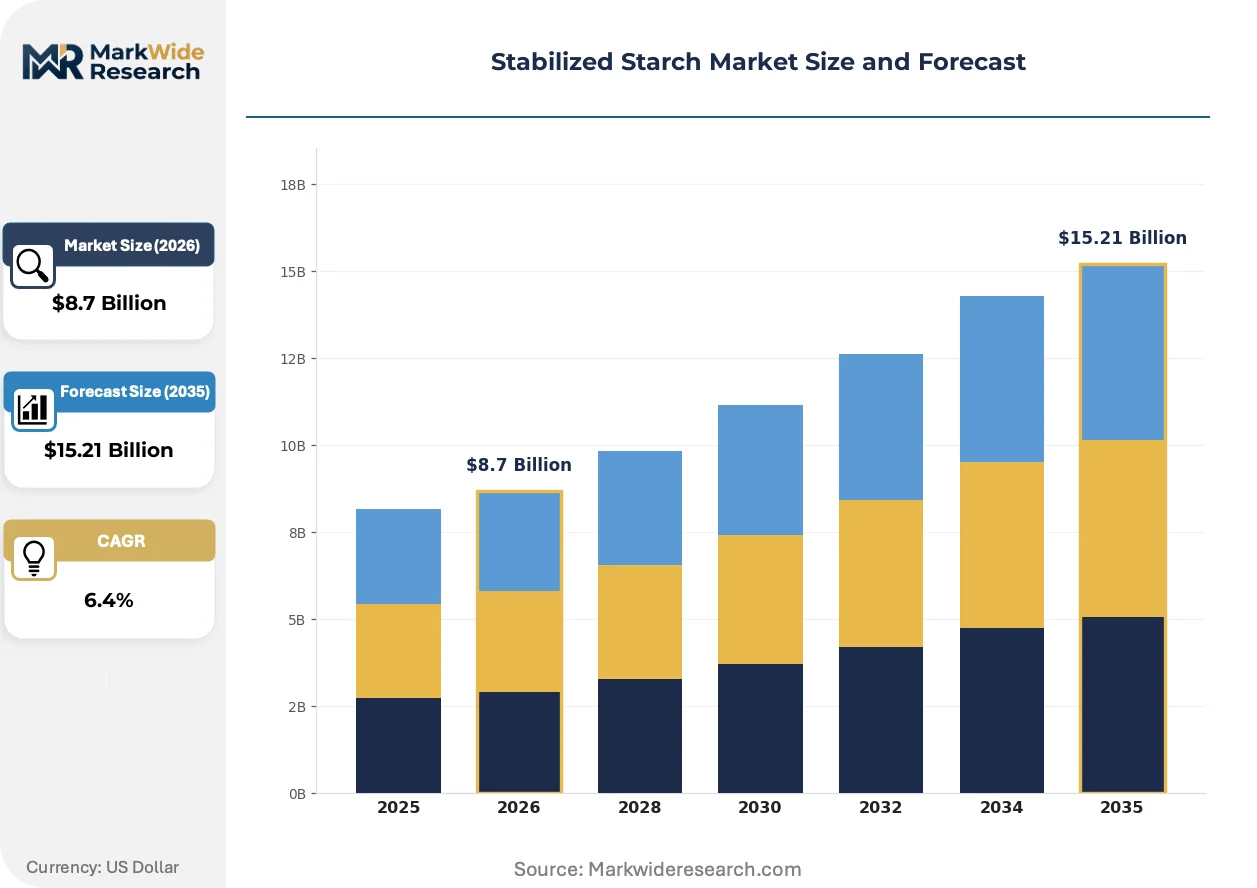
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Pre-gelatinized Starch, Cold Water Soluble Starch, Resistant Starch Form: Powder, Granule, Liquid, Gel Application: Food & Beverages, Pharmaceuticals, Personal Care, Animal Feed End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Animal Nutritionists |
| Companies Covered | Archer Daniels Midland, Cargill, Ingredion, Tate & Lyle, Roquette Frères, Avebe, Emsland Group, Grain Processing Corporation, Agrana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stabilized Starch Market Evolving Landscape
Enzymatic modification protocols are displacing conventional chemical etherification across pharmaceutical-grade production, altering capital deployment patterns and residual reagent compliance burdens throughout the value chain.
Dual-enzyme hydrolysis systems combining pullulanase with branching enzymes are decentralizing high-amylopectin concentrate production away from agricultural processing heartlands. Contract pharmaceutical manufacturers in Singapore and Switzerland are adopting these systems to reduce waxy corn import dependency. This technology is decentralizing supply chain risk while elevating batch-to-batch viscosity consistency requirements.
EU CSRD sustainability reporting mandates are forcing disclosure of scope 3 agricultural emissions across modified starch supply chains. Ingredient purchasers now require farm-level carbon intensity documentation from maize and tapioca suppliers. European pharmaceutical formulators are most affected, with several consolidating procurement toward verified low-carbon origination networks.
Specification-driven procurement is compressing supplier qualification cycles as food and pharma buyers consolidate vendor panels around dual-certified excipient sources. Direct mill relationships are displacing distributor intermediaries in volume applications. This pattern is most visible in India's processed food sector, where national brands are building captive starch modification capacity through toll manufacturing arrangements.
Stabilized Starch Market Segmentation
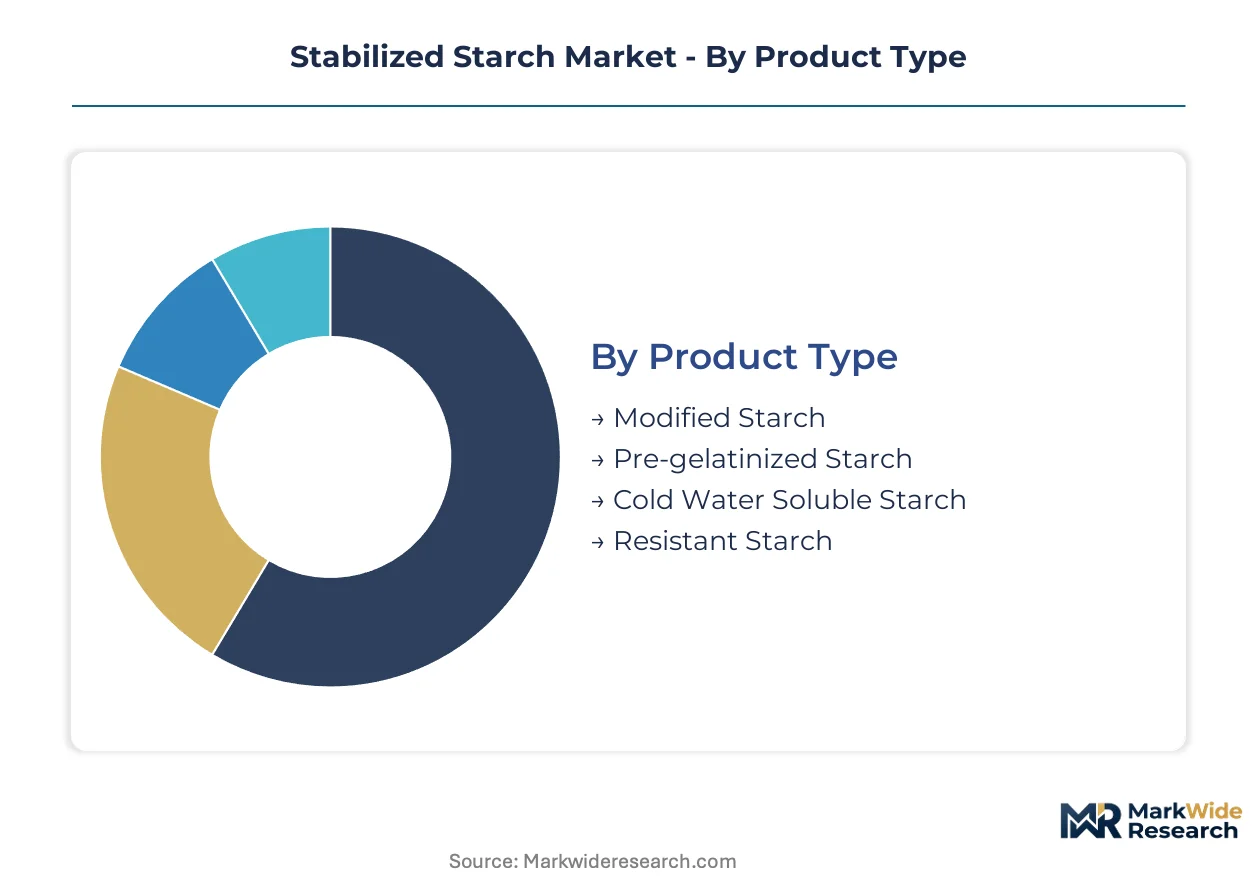
Stabilized starch procurement patterns diverge sharply across processing technologies and functional specifications. Each segment carries distinct qualification burdens, from FDA food-additive compliance to pharmaceutical excipient monograph harmonization.
Product Type:
Upgrade cycles in pharmaceutical and food processing equipment are pulling demand toward higher-performance stabilized grades that reduce retrofit costs.
- Modified Starch:Chemically or physically treated native starch achieves paste clarity above 80% transmittance and viscosity stability across pH 3–9. Food manufacturers in India's Maharashtra corridor leverage PLI scheme subsidies to convert instant noodle lines to modified starch binders. REACH registration dossiers favor producers with dedicated regulatory infrastructure.
- Resistant Starch:Chemically stabilized variants resist enzymatic digestion in the small intestine, delivering prebiotic functionality. Gut-health positioning in functional bakery and beverage applications is climbing fastest as fiber-additive replacement accelerates reformulation cycles.
- Cold Water Soluble Starch:Pre-gelatinized variants with sub-ambient dissolution kinetics enable heat-free processing in instant coffee and protein shake dry mixes.
- Pre-gelatinized Starch:Thermally treated for instant thickening without cooking energy input, serving ready-to-eat sauce applications.
Volume placements concentrate in Modified Starch; the faster expansion belongs to Resistant Starch.
Form:
Cost tiers separate commodity powder grades from premium liquid concentrates requiring specialized handling infrastructure.
- Powder:Spray-dried or drum-dried particulates dominate bulk food and pharmaceutical excipient procurement. India's Gujarat processing corridor sources powder grades for toll manufacturing arrangements with national brands.
- Liquid:Pumpable slurries eliminate dust exposure and hydration steps in high-throughput beverage plants. European pharmaceutical formulators prefer liquid delivery for topical cosmetic base production where batch consistency outweighs freight cost premiums.
- Granule:Agglomerated particles improve flowability for direct-compression tablet manufacturing.
- Gel:Hydrated colloidal suspensions serve ready-to-use cosmetic and topical pharmaceutical applications.
Procurement weight sits with Powder; Gel commands the steepest expansion trajectory in cosmetic manufacturing.
Application:
Customer maturity separates specification-driven pharmaceutical buyers from price-sensitive animal feed compounders.
- Food & Beverages:Processed food infrastructure subsidies in India accelerate modified starch uptake across instant noodle and ready-to-eat segments. FSSAI additive approval timelines compress as CODEX-aligned purity schedules streamline import qualification.
- Pharmaceuticals:Tablet binders and controlled-release matrices demand excipient GMP certification under IPEC-PQG standards. USP-NF, EP, and JP monograph alignment reduces dual-qualification burdens for multinational drug manufacturers.
- Personal Care:Topical cosmetic bases leverage stabilized starch for rheological performance without synthetic polymer alternatives.
- Animal Feed:Pellet binders and energy concentrates face native starch price anchoring in emerging markets.
Shipment volumes cluster in Food & Beverages; Pharmaceuticals is gaining share fastest on excipient harmonization momentum.
End User:
Supply concentration favors direct mill relationships over distributor intermediaries as volume buyers consolidate vendor panels.
- Food Manufacturers:National brands in India build captive modification capacity through toll manufacturing arrangements. Dual-certified excipient sources reduce qualification cycle compression.
- Pharmaceutical Firms:Multinational drug manufacturers demand farm-level carbon intensity documentation under EU CSRD mandates. Verified low-carbon origination networks consolidate procurement toward European pharmaceutical-grade producers.
- Cosmetic Companies:Personal care formulators prioritize allergen-free certification for pediatric and geriatric topical applications.
- Animal Nutritionists:Feed compounders balance performance premiums against unmodified tapioca and maize alternatives.
Contract volumes concentrate with Food Manufacturers; Pharmaceutical Firms are expanding most quickly on sustainability disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-amylopectin stabilized starch concentrates in North American agricultural corridors, while pharmaceutical formulation demand pulls consumption toward European and Asian manufacturing clusters. This geographic split shapes freight cost structures and regulatory compliance pathways across supply chains.
United States
Pharmaceutical excipient demand from contract manufacturers in New Jersey and North Carolina drives specification-grade modified starch procurement. FDA food-additive standards under 21 CFR 172.892 constrain chemical modification protocols for domestic suppliers. Iowa and Illinois processing facilities anchor waxy corn origination networks supplying high-amylopectin feedstocks.
Germany
REACH registration dossiers for chemically modified starch substances elevate compliance costs that compress mid-tier producer participation. ECHA toxicological requirements favor multi-billion-euro chemical conglomerates with dedicated regulatory affairs infrastructure. North Rhine-Westphalia pharmaceutical clusters source excipient grades through verified low-carbon origination networks under EU CSRD mandates.
India
PLI scheme subsidies for processed food infrastructure accelerate modified starch uptake across instant noodle and ready-to-eat segments. FSSAI additive approval timelines compress as CODEX-aligned purity schedules streamline import qualification for foreign suppliers. Maharashtra and Gujarat manufacturing corridors host toll manufacturing arrangements between national brands and international starch modifiers.
China
Domestic pharmaceutical-grade production expands as NMPA excipient registration pathways mature for multinational drug manufacturers. GB standards for food additives govern chemical modification limits in parallel with CODEX frameworks. Yangtze River Delta processing clusters integrate enzymatic modification protocols to reduce waxy corn import dependency.
Switzerland
Contract pharmaceutical manufacturers adopt dual-enzyme hydrolysis systems combining pullulanase with branching enzymes for batch-to-batch viscosity consistency. Swissmedic pharmaceutical-grade audits align with IPEC-PQG standards for excipient GMP certification. Basel-area formulation hubs source allergen-free pea-starch excipients for pediatric and geriatric dosage forms.
Stabilized Starch Market Competitive Landscape
Top-tier vendors anchor agricultural origination and pharmaceutical-grade certification, while regional modifiers compete on price-sensitive food applications. Market structure consolidates around multi-billion-dollar agribusiness conglomerates with integrated supply chains from cultivar development to excipient monograph compliance. Three archetypes dominate: agricultural originators controlling waxy corn genetics, European pharmaceutical-grade specialists with pea-starch extraction platforms, and Asian toll manufacturers leveraging PLI scheme infrastructure subsidies. Competitive moves center on backward integration into high-amylopectin cultivar development and strategic partnerships for enzymatic modification technology licensing.
Within the agricultural originator archetype, Cargill and Archer Daniels Midland exemplify North American players with integrated origination networks. European pharmaceutical-grade production anchors through Roquette Frères, whose northern French operations represent the pea-starch extraction specialist model. These three entities occupy positions spanning food-additive and excipient certification tiers, with geographic footprints that align production gravity against consumption pull in pharmaceutical and processed food segments.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill |
| Ingredion |
| Tate & Lyle |
| Roquette Frères |
| Avebe |
| Emsland Group |
| Grain Processing Corporation |
| Agrana |
| Others |
Value Network & Pricing Analysis
Waxy corn origination costs cascade through three-tier pricing structure across premium, standard, and economy levels, with high-amylopectin cultivar premiums separating pharmaceutical-grade excipients from commodity food binders. Freight volatility from North American agricultural corridors to European and Asian manufacturing clusters amplifies cost differentials between regional toll manufacturers and integrated agricultural originators.
Pricing Analysis
Margin tightening in standard-grade modified starch reflects native tapioca and maize price anchoring in emerging-market food applications. Cost-down pressure on economy tiers accelerates because India's PLI scheme subsidies attract toll manufacturing capacity that competes on volume scale. Pharmaceutical-grade certification under IPEC-PQG standards commands premium positioning, while animal feed compounders exhibit highest price sensitivity. Price differentiation hinges on REACH registration dossier completion and dual-certified excipient status for multinational drug manufacturers.
Supply Chain Analysis
Specialized rheology technician scarcity in European pharmaceutical-grade facilities constrains batch-to-batch viscosity consistency for modified starch production. Supply concentrates in the United States, Germany, and India, with waxy corn genetics anchored in Iowa and Illinois processing networks. Raw material flows draw from high-amylopectin cultivar development, enzymatic modification reagents, and pre-gelatinized thermal treatment infrastructure. Single-source vulnerability in North American agricultural origination exposes European and Asian processors to freight cost volatility. Distribution runs through direct mill relationships displacing distributor intermediaries in volume food and pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH toxicological dossier costs erect a barrier-to-entry moat favoring multi-billion-euro chemical conglomerates with dedicated regulatory affairs infrastructure over regional starch modifiers. ECHA compliance mandates compress mid-tier participation and consolidate competitive advantage toward producers with established registration capacity.
For Market Incumbents: Deploy backward integration into high-amylopectin cultivar development to secure waxy corn supply chains against origination risk. Cargill and Archer Daniels Midland exemplify this lever through Iowa and Illinois agricultural networks. Invest in enzymatic modification protocol licensing to reduce residual reagent compliance burdens and accelerate pharmaceutical-grade production timelines. Counter emerging Asian toll manufacturers by emphasizing dual-certified excipient status under harmonized USP-NF, EP, and JP monographs.
For New Entrants and Emerging Players: The premium-to-economy price gap in cold water soluble starch segments offers white-space entry for heat-free processing applications in instant coffee and protein shake dry mixes. Target India's Maharashtra and Gujarat manufacturing corridors where PLI scheme subsidies compress FSSAI import qualification timelines for toll manufacturing arrangements with national brands. Pursue allergen-free pea-starch extraction positioning for pediatric and geriatric pharmaceutical dosage forms, leveraging European pulse protein infrastructure overcapacity.
For Investors and Strategic Acquirers: IPEC-PQG pharmaceutical-grade audit completion announcements are the leading indicator that revenue recognition timelines will accelerate for new production lines. The stabilized starch market exhibits long-term viability anchored by pharmaceutical excipient harmonization and gut-health functional food reformulation. Acquisition targets should prioritize European pharmaceutical-grade specialists with pea-starch extraction platforms and established REACH registration dossiers. Monitor EU CSRD scope 3 agricultural emissions disclosure requirements as the signal for procurement consolidation toward verified low-carbon origination networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivar Development | Iowa and Illinois waxy corn genetics secure high-amylopectin supply chains against origination risk. |
| Enzymatic Modification Technology Licensing | Dual-enzyme hydrolysis systems reduce residual reagent burdens and improve batch viscosity consistency. |
| Pea-Starch Pharmaceutical-Grade Extraction | European pulse protein overcapacity enables allergen-free excipient certification for pediatric dosage forms. |
| Dual-Certified Excipient Status Investment | Harmonized USP-NF, EP, and JP monograph alignment reduces qualification cycles for multinational drug manufacturers. |
| Verified Low-Carbon Origination Network | EU CSRD mandates force farm-level carbon intensity documentation disclosure across maize and tapioca supply chains. |
Research Methodology
Multi-period observation of pharmaceutical excipient monograph harmonization progress, enzymatic modification patent filings, and PLI scheme subsidy disbursement rates anchored the trend analysis, supplemented by interviews with modified starch plant managers, pharmaceutical procurement leads at multinational drug manufacturers, FSSAI regulatory affairs officers, and toll manufacturing arrangement coordinators. Secondary validation drew from ECHA REACH registration databases, FDA 21 CFR 172.892 food-additive filings, USP-NF and EP excipient monograph updates, and India customs trade data for modified starch imports. Bottom-up volume modeling triangulated against top-down value projections across product type, application, and regional production hub dimensions.
Input-output matrices mapped waxy corn origination volumes through processing technology tiers to end-use consumption across food, pharmaceutical, and personal care segments. Segmentation dimensions spanned modified starch grades, resistant starch functionality tiers, cold water soluble variants, and pre-gelatinized forms crossed with powder, liquid, granule, and gel delivery formats. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory approval timeline acceleration and sustainability disclosure mandate impacts. Forecast inputs incorporated enzymatic modification adoption curves and gut-health positioning penetration rates in functional bakery applications.
Inputs from ECHA registration databases and FSSAI additive approval records were available through the study window; gaps in farm-level carbon intensity documentation introduce uncertainty bands around EU CSRD compliance cost projections. Forecasts reflect assumptions regarding pharmaceutical excipient harmonization momentum and India PLI scheme infrastructure buildout pace. Material deviation in IPEC-PQG audit completion timelines or waxy corn supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Birch Sap Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Ice Cream Bases Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Europe Fats and Oil Market
Ingredients
Lime Seed Oils Market
Ingredients
Murumuru Butter Market
Ingredients
North America Potato Protein Market
Ingredients
Chickpea Protein Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Corn Peptide Market
Ingredients
Dill Seed Oil Market
Ingredients
Bromelain Ingredient Market
Ingredients
Pea Fiber Market
Ingredients
Almond Ingredients Market