
 Smoked Yeast Market | 2026-2036
Smoked Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Yeast Market Analytics
Specialty food manufacturers is bifurcating demand away from commodity baking houses as smoked yeast commands premium positioning in craft sauces and seasoning blends. Lesaffre Group leverages vertical integration from raw yeast cultivation to finished smoke-infused powders, sustaining quality consistency across European supply chains. Angel Yeast Co., Ltd anchors Asia-Pacific production capacity with specialized fermentation infrastructure. Kerry Group differentiates through clean-label smoke flavor delivery systems that bypass traditional wood-smoke processes.
Smoked yeast denotes Saccharomyces cerevisiae biomass subjected to controlled thermal treatment or liquid smoke infusion, yielding phenolic compounds between 200-800 ppm that impart hickory, mesquite, or applewood sensory profiles to finished foods. The ingredient functions primarily as a natural flavor carrier and umami enhancer in formulations where synthetic smoke additives face consumer rejection. Powdered smoked yeast leads product type revenue pools due to extended shelf stability and ease of dry blending in industrial bakeries, while liquid smoked yeast posts the fastest growth trajectory as craft breweries adopt it for kettle-soured and smoked porter innovations. Application concentration tilts toward sauces and seasoning where margin capture exceeds commoditized baking segments.
FDA food additive regulations under 21 CFR and USDA organic certification standards govern smoked yeast labeling and processing claims in the United States, while EU EFSA evaluates smoke flavoring primary products under Regulation 2065/2003, creating divergent compliance burdens for cross-Atlantic suppliers. BIS food safety protocols in India and GB standards administered by SAMR in China add further layering for manufacturers targeting Asia-Pacific expansion. Stakeholders must monitor evolving clean-label definitions and smoke-derived contaminant thresholds as regulatory science catches up with processing innovation.
Market Dynamics
EU REACH compliance on food contact substances and novel processing techniques are tightening ingredient certification pathways, forcing suppliers to restructure quality assurance protocols and documentation systems. Specialty food manufacturers and craft breweries are expanding procurement of smoked yeast for flavor layering in artisanal products.
Growth Catalysts
- Clean-label mandates:FDA food additive regulations under 21 CFR and USDA organic certification standards are pushing synthetic smoke additives out of formulation pipelines. Natural smoked yeast biomass gains shelf space as compliant flavor carriers.
- Wood-smoke process substitution:Liquid smoke infusion technology enables consistent phenolic compound delivery between 200-800 ppm without traditional combustive smoking. Craft breweries adopt kettle-souring applications for smoked porter innovations.
- Germany:Premium positioning of hickory, mesquite, and applewood sensory profiles commands retail and foodservice margin capture. Specialty sauce and seasoning blend manufacturers concentrate procurement in this market.
Market Restraints
- Input cost volatility:Saccharomyces cerevisiae cultivation depends on molasses and grain feedstock pricing subject to agricultural commodity swings. Fermentation infrastructure energy costs compound margin pressure.
- Regulatory friction:EU EFSA evaluation of smoke flavoring primary products under Regulation 2065/2003 creates divergent compliance burdens for cross-Atlantic suppliers. Certification timelines extend 18-24 months.
- Technical limitation:Liquid smoked yeast shelf stability remains inferior to powdered variants, constraining distribution radius and cold-chain requirements for craft brewery adoption.
Strategic Opportunities
- India:BIS food safety protocols are formalizing, creating first-mover advantage for certified suppliers. Underpenetrated sauce and seasoning manufacturing base offers white-space expansion.
- Regulatory tailwind:EU Green Deal sustainability metrics favor biomass-derived flavor carriers over petroleum-based synthetic alternatives. Carbon accounting protocols reward fermentation-based production.
- Technology convergence:Precision fermentation infrastructure is merging with controlled thermal treatment systems, enabling customized phenolic compound profiles for targeted end-use applications.
Industry Challenges
- Skill gap in smoke chemistry:Formulation scientists capable of balancing phenolic compound thresholds with clean-label positioning remain scarce. Technical training programs lag market expansion.
- Certification timeline compression:Novel processing technique validation under evolving EFSA guidance requires parallel documentation streams. Regulatory science uncertainty extends go-to-market schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Yeast Market |
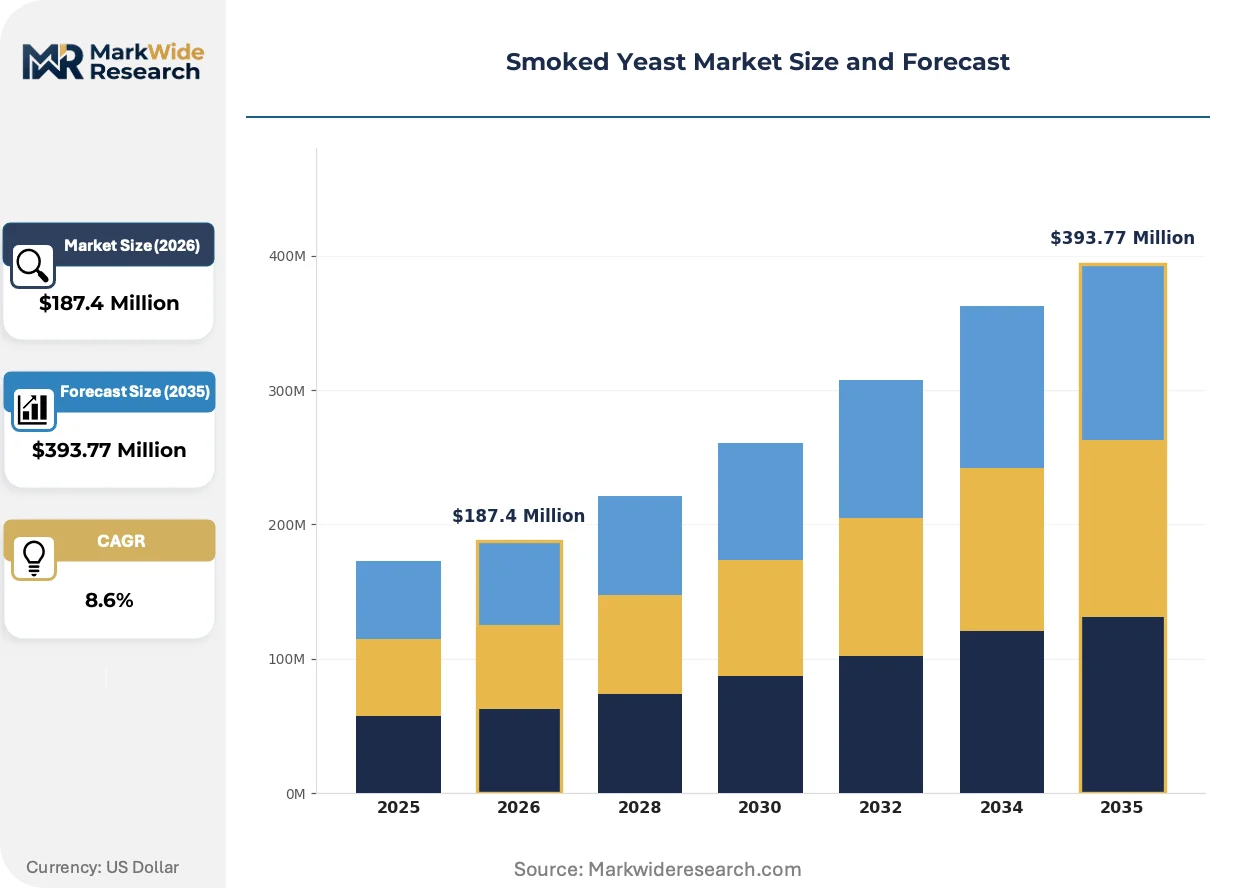
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Smoked Yeast, Powdered Smoked Yeast, Extracted Smoked Yeast, Liquid Smoked Yeast Application: Baking, Brewing, Sauces, Seasoning End User: Food Industry, Beverage Industry, Culinary Professionals, Home Cooks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Angel Yeast Co., Ltd, Kerry Group, Lesaffre Group, Biospringer, Archer Daniels Midland Company, Lallemand Inc., Chr. Hansen Holding A/S, Leiber GmbH, AB Mauri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Yeast Market Evolving Landscape
Processing innovation is fragmenting traditional wood-smoke supply chains while regulatory scrutiny compresses synthetic additive tolerance. Three distinct vectors are reconfiguring competitive positioning in flavor delivery systems.
Cold-smoke vapor deposition technology is decomposing conventional thermal treatment economics. Craft sauce manufacturers in France are piloting this method for hickory and applewood profile precision. The technology is decomposing capital barriers between industrial-scale and artisanal production volumes.
EFSA is tightening contaminant thresholds for polycyclic aromatic hydrocarbons in smoke-derived flavorings under revised Regulation 2065/2003 guidance. Liquid smoke infusion processes face heightened analytical scrutiny. Powdered smoked yeast suppliers with validated purification protocols are securing preferential supplier status with German retail chains.
Buyer concentration among specialty food manufacturers is compressing supplier negotiation cycles. Direct procurement agreements are displacing traditional ingredient distributor intermediaries. This pattern is most visible in United States craft brewery supply chains, where vertical collaboration on custom phenolic profiles is replacing off-the-shelf purchasing.
Smoked Yeast Market Segmentation
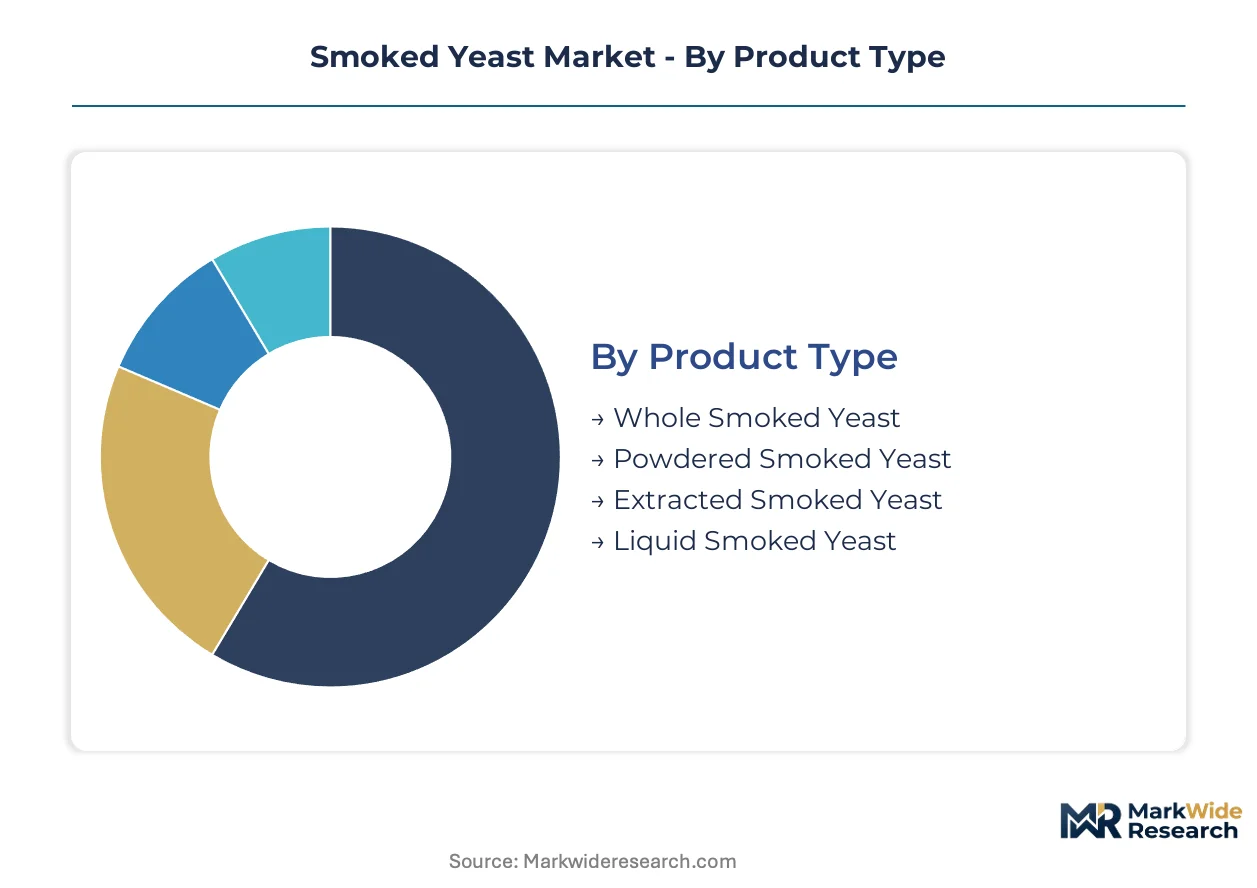
Segmentation in the smoked yeast market reveals divergent supply chain configurations across physical forms and customer tiers. Powdered variants dominate industrial procurement channels, while liquid formats penetrate craft brewery direct-buying relationships. Distribution economics and shelf stability requirements shape segment boundaries more than raw material sourcing alone.
Product Type:
German and French industrial bakeries anchor demand for powdered formats, while United States craft breweries drive liquid segment expansion through export-oriented procurement.
- Whole Smoked Yeast:Intact Saccharomyces cerevisiae cells retain full protein matrices and B-vitamin complexes. German artisanal bread producers favor this format for traditional sourdough fortification where visible yeast particulates signal authenticity.
- Powdered Smoked Yeast:Dehydrated biomass with moisture content below 5% enables ambient storage and pneumatic conveying in industrial bakeries. Extended shelf stability supports transatlantic shipping from European production hubs to United States manufacturing facilities.
- Extracted Smoked Yeast:Soluble fractions concentrate umami compounds for clean-label flavor modulation. Hydrolyzed protein content ranges 40-60% depending on extraction severity.
- Liquid Smoked Yeast:Aqueous suspensions with 15-25% solids content suit kettle-souring protocols in craft porter production. Cold-chain requirements constrain distribution radius to regional brewery clusters in the United States.
Powdered smoked yeast holds the largest share; momentum sits with liquid smoked yeast as craft brewing applications multiply.
Application:
Margin capture varies sharply across applications, with sauces and seasoning commanding premium positioning relative to commoditized baking volumes.
- Baking:Industrial-scale incorporation into European bread and cracker formulations leverages powdered formats for uniform distribution. FDA 21 CFR compliance requirements shape labeling claims in United States export markets.
- Brewing:Craft breweries in the United States deploy liquid smoked yeast for kettle-soured and smoked porter innovations. Phenolic compound precision enables reproducible flavor layering without traditional wood-smoke infrastructure.
- Sauces:Specialty manufacturers in France integrate smoked yeast for hickory and applewood profile delivery in clean-label barbecue and savory condiments.
- Seasoning:Dry blend compatibility with salt and spice matrices supports retail seasoning packet production. EU EFSA Regulation 2065/2003 compliance validates smoke-derived ingredient safety for European distribution.
Sauces and seasoning generate the steepest margin expansion; brewing applications are climbing the fastest as craft segment procurement scales.
End User:
Customer sophistication tiers separate formulation-driven industrial buyers from price-sensitive household purchasers.
- Food Industry:Large-scale manufacturers require batch-to-batch phenolic compound consistency for standardized product lines. Certificate of analysis documentation supports HACCP protocols.
- Beverage Industry:Craft breweries prioritize custom phenolic profiles over off-the-shelf specifications, driving direct supplier collaboration rather than distributor intermediation.
- Culinary Professionals:Restaurant and catering operations seek concentrated flavor impact in reduced-sodium formulations where smoked yeast replaces salt-driven umami.
- Home Cooks:Retail package sizes below 100 grams dominate this segment, with online recipe content influencing brand discovery and trial conversion.
Food industry procurement holds the largest share; beverage industry engagement is expanding most quickly as craft brewery supplier relationships deepen.
Distribution Channel:
Channel selection correlates with order scale and technical service requirements, fragmenting supplier go-to-market strategies.
- Online Retail:Direct-to-consumer and small-business procurement bypasses traditional distributor markups. Amazon and specialized ingredient platforms aggregate demand from culinary professionals and home cooks across the United States and Germany.
- Supermarkets:Mass retail placement requires packaged consumer formats with extended shelf dating. United States retail chains demand USDA organic certification for premium positioning.
- Specialty Stores:Gourmet and natural food retailers in France and Germany curate smoked yeast alongside artisanal vinegar and specialty salt assortments.
- Wholesale:Industrial volumes move through foodservice distributors and ingredient brokers serving bakery and sauce manufacturing clusters.
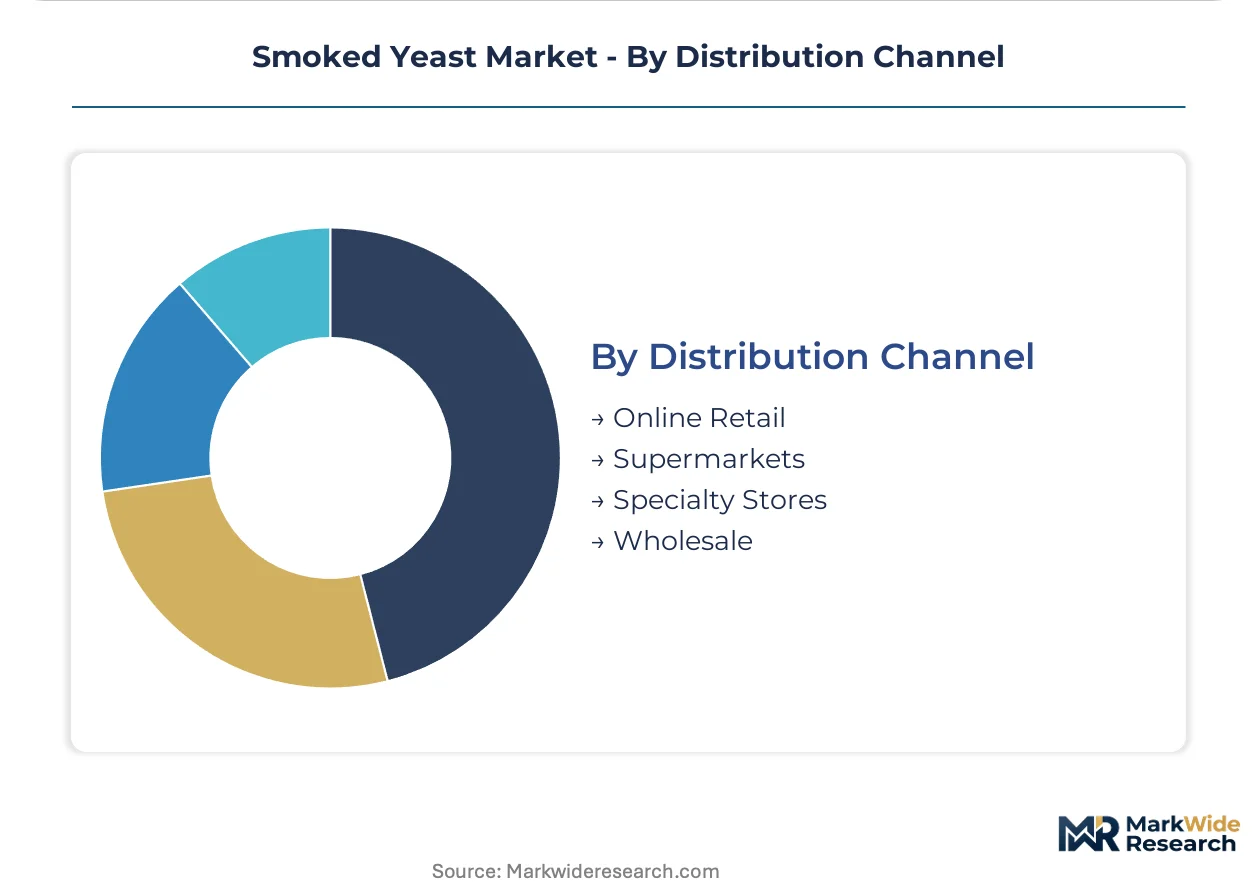
Wholesale channels capture the largest volume; online retail is gaining share fastest as procurement digitization accelerates across customer tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German production facilities supply smoked yeast biomass to United States craft brewery networks through transatlantic distribution corridors. France and Belgium serve as secondary export hubs for specialty sauce manufacturers seeking clean-label smoke flavor systems.
Germany
Artisanal bread producers in Bavaria drive whole smoked yeast procurement for visible particulate authenticity in sourdough fortification. EFSA Regulation 2065/2003 compliance documentation supports cross-border shipments to French retail chains. The Munich-Stuttgart industrial corridor hosts precision fermentation infrastructure serving domestic and export baking sectors.
United States
Craft breweries in Colorado and Oregon deploy liquid smoked yeast for kettle-soured porter production without traditional wood-smoke capital investment. FDA 21 CFR labeling requirements shape clean-label claims in barbecue sauce formulations. Pacific Northwest manufacturing clusters supply phenolic-compound-customized biomass to regional beverage producers.
France
Specialty sauce manufacturers in Île-de-France integrate cold-smoke vapor deposition technology for hickory profile precision. EU Green Deal sustainability metrics favor biomass-derived carriers over petroleum-based alternatives. Lyon-based ingredient brokers coordinate procurement between German suppliers and domestic condiment producers.
China
Angel Yeast anchors Asia-Pacific production capacity with specialized fermentation infrastructure serving domestic and export markets. SAMR-administered GB standards govern food contact substance certification for cross-border trade. Yangtze River Delta manufacturing bases supply powdered formats to Southeast Asian sauce manufacturers.
India
Underpenetrated sauce and seasoning manufacturing bases in Maharashtra and Gujarat offer white-space expansion for certified suppliers. FSSAI protocols are formalizing national food safety standards for smoke-derived ingredients. Mumbai-Pune industrial corridors attract first-mover suppliers establishing BIS-compliant distribution networks.
Smoked Yeast Market Competitive Landscape
Player mix skews toward vertically integrated yeast cultivators with captive Saccharomyces cerevisiae biomass supply. Market structure concentrates around fermentation specialists controlling upstream molasses feedstock procurement and downstream smoke-infusion processing. Two strategic archetypes dominate: European heritage groups with multi-decade brewing industry relationships, and Asia-Pacific scale producers leveraging cost-optimized infrastructure. Competitive moves center on precision fermentation technology licensing and direct procurement agreement displacement of traditional distributor intermediaries.
Within the heritage European tier, Lesaffre Group and Lallemand Inc. exemplify integrated cultivation-to-finished-product operations sustaining quality consistency across continental supply chains. Angel Yeast Co., Ltd occupies a position as the Asia-Pacific scale anchor with specialized infrastructure serving regional export demand. Kerry Group represents the clean-label innovation vector, differentiating through flavor delivery systems that bypass traditional combustive processes.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd |
| Kerry Group |
| Lesaffre Group |
| Biospringer |
| Archer Daniels Midland Company |
| Lallemand Inc. |
| Chr. Hansen Holding A/S |
| Leiber GmbH |
| AB Mauri |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for liquid smoked yeast concentrate procurement power in craft brewery networks, compressing margin capture for distributors unable to secure cold-chain reliability. This lead-time band exposes the structural tension between powdered formats with ambient stability and temperature-sensitive liquid variants that command formulation precision premiums.
Pricing Analysis
Next-generation cold-smoke vapor deposition technology carries 40-60% premiums over conventional thermal treatment systems, while legacy liquid infusion processes face downward pressure from EFSA contaminant threshold tightening. Three-tier pricing structure across premium, standard, and economy levels stratifies by phenolic compound precision and certification documentation depth. Price differentiation centers on EU EFSA Regulation 2065/2003 compliance tier and volume scale, with craft breweries showing lowest sensitivity due to custom profile requirements. Cost compression in standard-grade powdered formats is intensifying because molasses feedstock volatility feeds directly into Saccharomyces cerevisiae cultivation economics.
Supply Chain Analysis
Forty-five-day lead times from German fermentation hubs to United States craft brewery clusters anchor procurement planning for liquid smoked yeast, constraining just-in-sequence adoption. Supply concentrates in Germany, France, and China, with Angel Yeast's Yangtze River Delta infrastructure serving Asia-Pacific export demand. Raw material dependencies center on molasses feedstock, wood-derived phenolic precursors, and specialized fermentation nutrients. Single-source vulnerability runs through German precision fermentation equipment suppliers for cold-smoke vapor deposition systems. Distribution runs through direct procurement agreements displacing traditional ingredient broker intermediaries, particularly visible in United States beverage industry channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label smoke flavor substitution represents a high-growth disruption justified by EFSA's progressive tightening of synthetic additive tolerance thresholds under revised Regulation 2065/2003 guidance.
For Market Incumbents: Consolidate backward integration into captive Saccharomyces cerevisiae biomass supply to defend against Asia-Pacific scale producers leveraging cost-optimized fermentation infrastructure. Lock in direct procurement agreements with United States craft brewery networks before channel intermediaries reassert position. Certification investment in parallel EU and FDA documentation streams protects against regulatory friction extending go-to-market timelines. For New Entrants and Emerging Players: Custom phenolic profile formulation services for craft breweries represent a service-layer gap where incumbents under-serve with off-the-shelf specifications. Target India as the most penetrable geography given formalizing BIS protocols and underpenetrated sauce manufacturing bases in Maharashtra. Deploy precision fermentation technology licensing as the go-to-market angle to bypass capital-intensive smoke-infusion infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a fermentation-technology consolidation play because precision infrastructure is merging with controlled thermal treatment systems to enable customized phenolic compound profiles. Acquisition targets should center on mid-cap European heritage groups with validated EFSA purification protocols and established German retail chain supplier status. Watch for EFSA guidance finalization on novel processing technique validation as the signal indicating regulatory timeline compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Technology Licensing | Enables customized phenolic profiles without traditional combustive smoking capital investment. |
| Backward Integration into Molasses Feedstock | Secures Saccharomyces cerevisiae cultivation economics against agricultural commodity swings. |
| Direct Procurement Agreement Expansion | Displaces distributor intermediaries in United States craft brewery supply chains. |
| EFSA/FDA Parallel Certification Investment | Compresses cross-Atlantic regulatory timeline exposure for novel processing techniques. |
| Cold-Chain Distribution Partnership | Extends liquid smoked yeast radius to regional brewery clusters beyond current constraints. |
Research Methodology
Operator-level perspectives from specialty sauce formulation scientists, craft brewery procurement leads, fermentation infrastructure engineers, and EU regulatory affairs specialists anchored the qualitative base. Primary interview streams combined with secondary validation from EFSA guidance documents, FDA 21 CFR filings, BIS protocol drafts, and customs trade data for molasses and yeast biomass flows. Bottom-up volume triangulation across product type, application, and end-user segments intersected with top-down macroeconomic anchoring.
Sensitivity analysis tested forecast robustness across feedstock price volatility bands and regulatory timeline scenarios over the projection horizon. Segmentation dimensions modeled include physical form, application concentration, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from installed fermentation capacity expansion curves and craft brewery procurement scaling patterns. Industry-specific inputs incorporated phenolic compound precision thresholds and clean-label substitution elasticity estimates.
Underlying assumptions cover EFSA guidance trajectory stability and molasses supply continuity, with deviation risk concentrated in regulatory science uncertainty around novel processing technique validation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Orange Powder Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Horehound Extract Market
Ingredients
South America Phytosterols Market
Ingredients
China Corn Glucose Market
Ingredients
Cheese Cultures Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Stabilized Starch Market
Ingredients
Barley Malt Extract Market
Ingredients
Hops Derivative Market
Ingredients
Pepsin Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Europe Soy Protein Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Meat Extract Market