
 Fish Peptones Market | 2026-2036
Fish Peptones Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Peptones Market Foresight
Marine-derived protein hydrolysate production in Norway and Iceland is consolidating as North Atlantic fishing cooperatives standardize enzymatic extraction protocols. Kerry Group leverages backward integration into sustainable fishery supply chains to secure raw material consistency. Thermo Fisher Scientific anchors its position through pharmaceutical-grade certification programs that filter smaller competitors from high-specification segments. HiMedia Laboratories competes aggressively on bulk pricing for microbiology laboratories across South Asia and the Middle East.
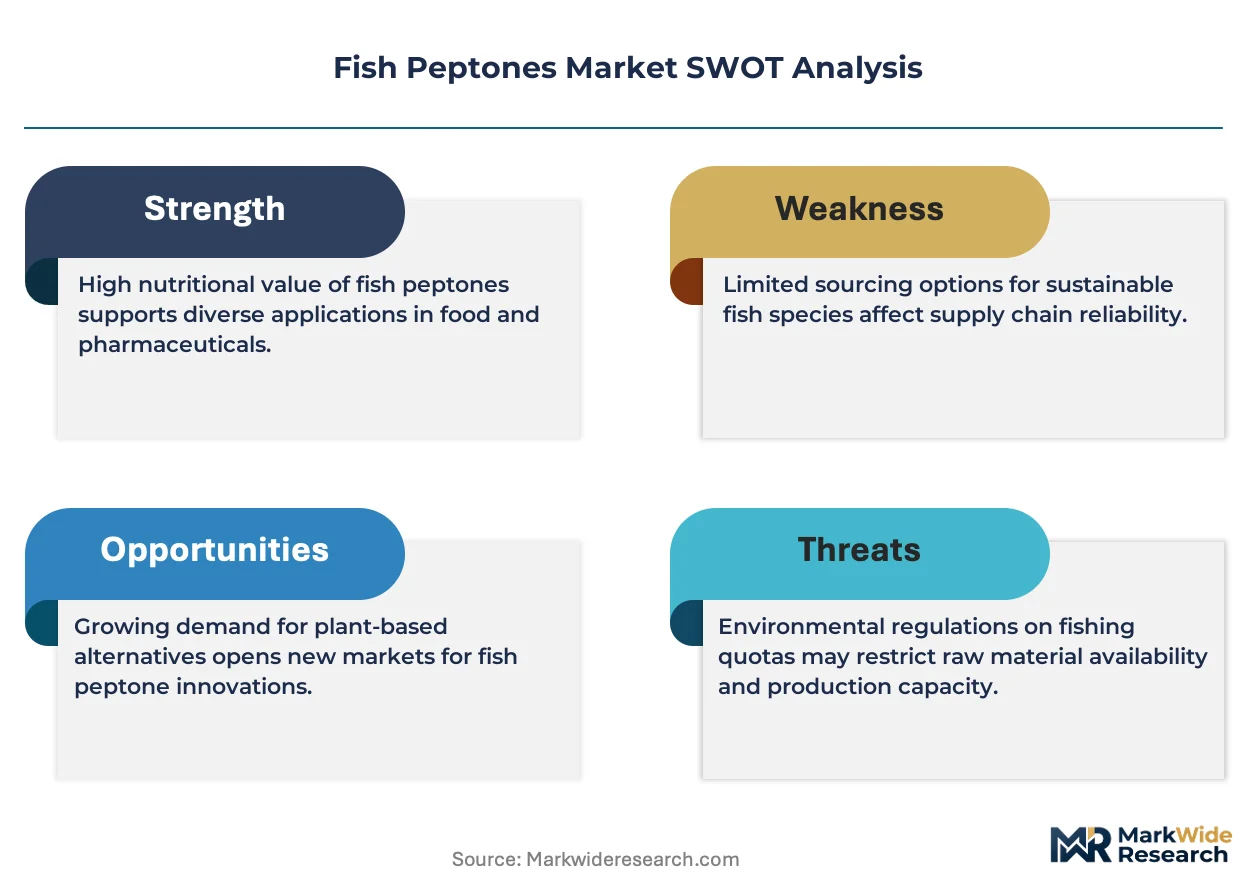
Fish peptones are water-soluble protein hydrolysates manufactured through controlled enzymatic digestion of fish tissues, yielding nitrogen-rich substrates with peptide molecular weights typically below ten kilodaltons; these compounds serve as essential nitrogen sources in microbial cultivation and industrial fermentation. Spray-dried formulations dominate volume shipments due to extended shelf stability and reduced logistics costs, though freeze-dried variants command premium positioning in cell culture applications where endotoxin thresholds are most stringent. Pharmaceutical production applications are expanding fastest as mammalian cell line developers substitute plant-derived peptones to mitigate lot-to-lot variability risks.
FDA biologics guidance and EMA GMP Annex 1 revisions are tightening raw material qualification requirements, forcing suppliers to document species traceability and allergen control across every production batch. ISO 13485 and USP <1046> standards further stratify the vendor base by separating diagnostic-grade from research-grade supply tiers. Stakeholders must evaluate whether captive fermentation capacity or external peptone sourcing delivers superior control over cell culture performance variability.
Market Dynamics
Enzymatic hydrolysis efficiency gains are compressing production costs while FDA and EMA traceability mandates are fragmenting the supplier base into certified and non-certified tiers. This dual pressure is reshaping competitive positioning between integrated fishery operators and specialized bioprocessing firms.
Growth Catalysts
- Biologics manufacturing scale-up:Mammalian cell line developers in Germany and the United States are substituting fish-derived peptones for plant-based alternatives to reduce lot-to-lot variability in monoclonal antibody production.
- REACH and FDA biologics guidelines:Tighter raw material qualification requirements are forcing end-users toward documented supply chains, advantaging certified producers with species traceability protocols.
- Enzymatic extraction standardization:North Atlantic fishing cooperatives in Norway and Iceland are consolidating around unified hydrolysis protocols, reducing batch inconsistency and securing pharmaceutical-grade output volumes.
Market Restraints
- Raw material concentration:Premium Atlantic cod and salmon byproduct supply concentrates in Norwegian and Icelandic processing facilities, creating geographic single-point vulnerability.
- Soy peptone substitution:Plant-derived alternatives at 60-70% cost parity are capturing research-grade microbiology segments where endotoxin thresholds are less stringent.
- Allergen control costs:EMA GMP Annex 1 revisions mandate species-level documentation and dedicated production lines, elevating compliance overhead for multi-species processors.
Strategic Opportunities
- Cell culture media premiumization:Freeze-dried formulations with sub-0.25 EU/mg endotoxin specifications command 40-50% price premiums over spray-dried variants in stem cell therapy applications.
- South Asian laboratory expansion:Bulk pricing strategies targeting microbiology laboratories in India and Bangladesh exploit underpenetrated diagnostic infrastructure buildouts.
- ISO 13485 certification arbitrage:Diagnostic-grade supply tier separation creates margin expansion for firms bridging research-grade production with medical device quality systems.
Industry Challenges
- Proteolytic enzyme sourcing:Qualified food-grade enzyme suppliers for controlled hydrolysis are concentrated among three European specialty chemical firms, creating input bottleneck risk.
- Endotoxin testing throughput:LAL assay capacity constraints at third-party laboratories are extending batch release timelines from 72 hours to 10-14 days for pharmaceutical customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Peptones Market |
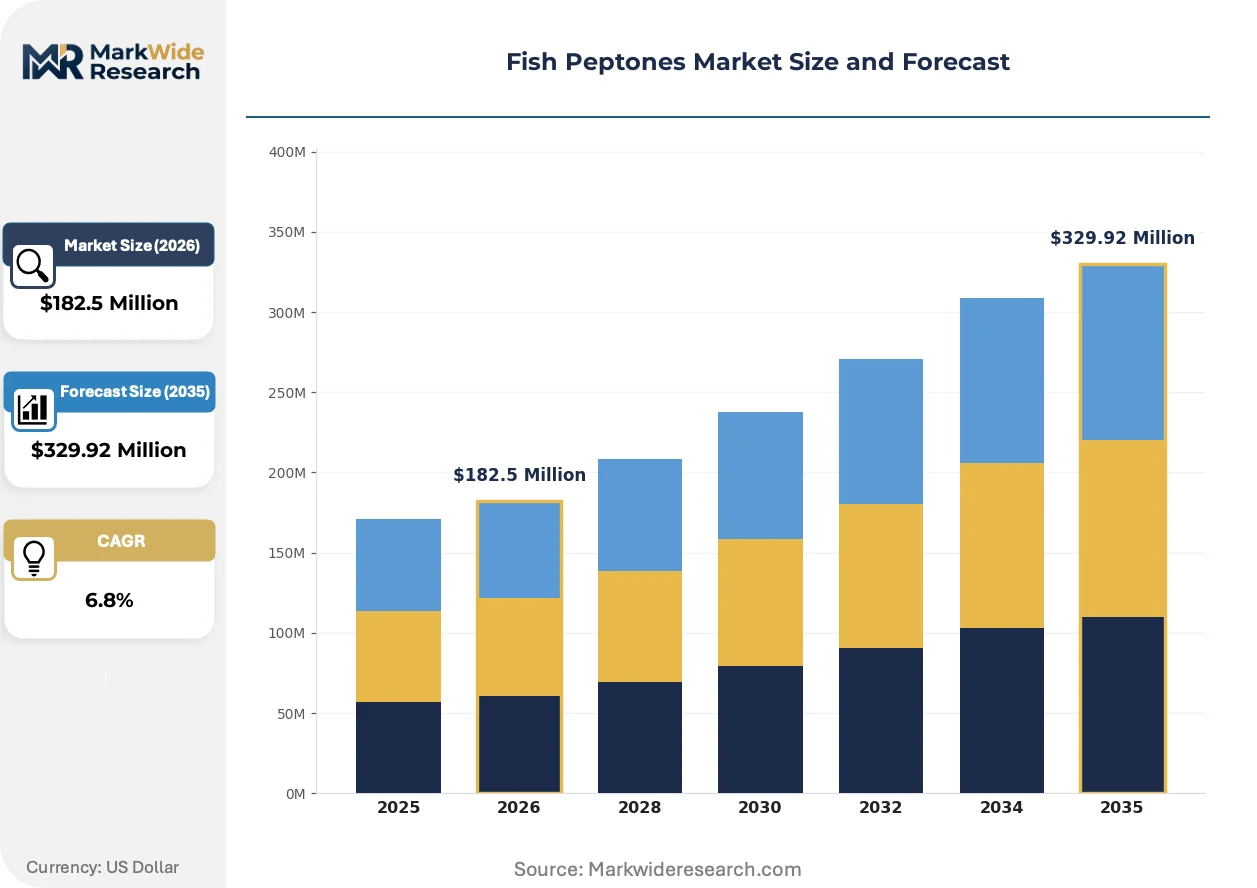
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $329.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray-Dried, Freeze-Dried, Liquid, Concentrated Application: Microbial Culture Media, Fermentation Processes, Pharmaceutical Production, Food & Beverage Enhancement End Use Industry: Biotechnology Firms, Pharmaceutical Manufacturers, Nutraceutical Companies, Food Processing Units Packaging Type: Bulk Bags, Sachets, Fiber Drums, Plastic Containers |
| Companies Covered | Kerry Group, Thermo Fisher Scientific, HiMedia Laboratories, Titan Biotech, Solabia Group, Hardy Diagnostics, Copalis, Bioibérica, Azelis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Peptones Market Shifts & Advancements
Continuous enzymatic reactor systems are displacing batch hydrolysis in commercial-scale facilities, while regulatory digitization mandates are forcing traceability infrastructure investments. These parallel developments are compressing margins for legacy processors while rewarding capital-intensive modernization.
Single-pass tangential flow filtration is expanding into peptide fractionation workflows, enabling molecular weight cutoff precision below five kilodaltons. Contract development and manufacturing organizations in Switzerland and Massachusetts are adopting these systems to meet cell therapy media specifications. The technology is expanding into mid-tier suppliers previously excluded from pharmaceutical-grade segments by capital barriers.
EMA GMP Annex 1 revisions effective across European Union member states now require real-time environmental monitoring data in raw material supplier audits. Sterile peptone manufacturers must demonstrate closed-system processing with automated contamination detection. German and French biologics producers are consolidating supplier panels to those with digitized batch records, excluding smaller Mediterranean processors.
Consolidated procurement frameworks are displacing spot purchasing in multinational pharmaceutical firms, with three-year supply agreements replacing quarterly tenders. Thermo Fisher Scientific and Merck KGaA are embedding technical service teams at buyer fermentation facilities to secure sole-source positions. This concentration is most visible in United States and German mammalian cell culture operations, where performance variability penalties now exceed material cost differentials.
Fish Peptones Market Segmentation
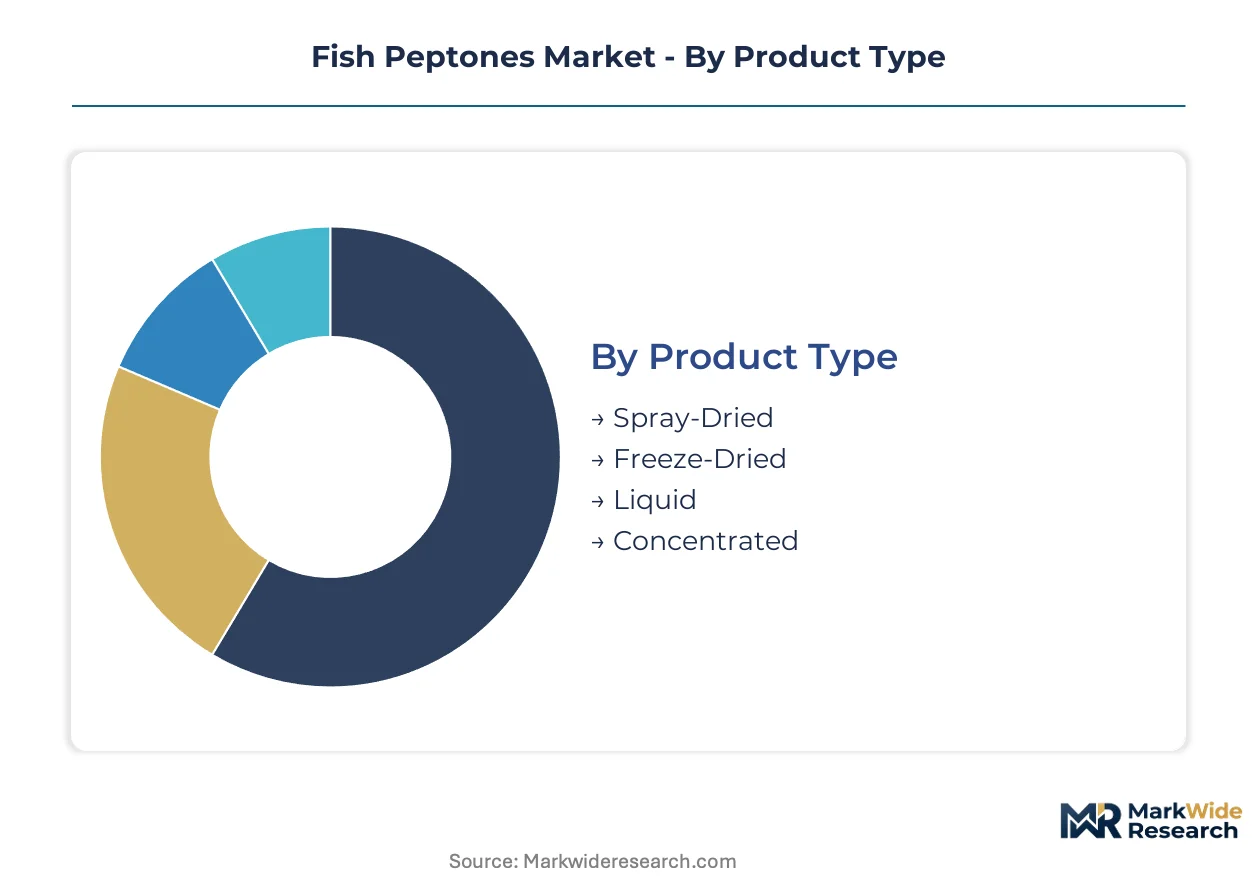
Fish peptone buyers navigate distinct specification tiers across formulation, application, and packaging dimensions. Upgrade cycles from research-grade to pharmaceutical-grade materials are accelerating as FDA and EMA qualification requirements harden.
Product Type:
Replacement decisions increasingly favor endotoxin-certified formats as mammalian cell culture applications displace traditional microbiology uses.
- Spray-Dried:Heat-processed powders with 12-18 month shelf stability dominate volume shipments. Food processing units in Germany and the United States specify this format for cost-sensitive fermentation media where endotoxin thresholds exceed 1.0 EU/mg.
- Freeze-Dried:Lyophilized formulations preserve heat-labile peptides below 0.25 EU/mg endotoxin specifications. Stem cell therapy developers in Switzerland and Massachusetts pay 40-50% premiums for this grade to mitigate lot-to-lot variability in critical cell line expansion.
- Liquid:Ready-to-use hydrolysate solutions eliminate reconstitution steps in high-throughput screening laboratories.
- Concentrated:Reduced-volume formulations cut cold-chain logistics costs for international biotechnology firm procurement.
Volume placements concentrate in Spray-Dried; the faster expansion belongs to Freeze-Dried.
Application:
Cost tier separation between diagnostic and therapeutic-grade uses is widening as regulatory documentation requirements diverge.
- Microbial Culture Media:Standard nitrogen supplementation for bacterial and fungal cultivation in research laboratories. Bulk pricing from Indian suppliers captures diagnostic infrastructure buildouts across Bangladesh and Pakistan where endotoxin sensitivity remains secondary to cost containment.
- Fermentation Processes:Industrial-scale bioreactor feeds for enzyme and organic acid production. Norwegian and Icelandic processors anchor supply through standardized enzymatic extraction protocols that reduce batch inconsistency.
- Pharmaceutical Production:Mammalian cell culture substrates for monoclonal antibody manufacturing. German and United States biologics producers substitute fish-derived peptones for plant-based alternatives to tighten specification control.
- Food & Beverage Enhancement:Flavor precursors and nutritional fortification in processed seafood products.
Microbial Culture Media holds the largest installed base; Pharmaceutical Production is climbing the fastest as biologics manufacturing scales.
End Use Industry:
Customer type determines margin capture, with certification-capable suppliers extracting premiums from regulated pharmaceutical channels.
- Biotechnology Firms:Cell line developers and contract research organizations with variable specification needs across discovery and preclinical phases.
- Pharmaceutical Manufacturers:GMP-compliant biologics producers requiring species traceability documentation and dedicated allergen-controlled production lines under EMA GMP Annex 1.
- Nutraceutical Companies:Dietary supplement formulators seeking marine protein hydrolysates with bioactive peptide fractions.
- Food Processing Units:Commercial kitchens and industrial food manufacturers using peptones as flavor enhancers and fermentation starters.
Pharmaceutical Manufacturers command the strictest qualification standards; Biotechnology Firms generate the highest transaction velocity through diversified sourcing.
Packaging Type:
Supply concentration in North Atlantic fishing cooperatives shapes logistics configuration for international distribution.
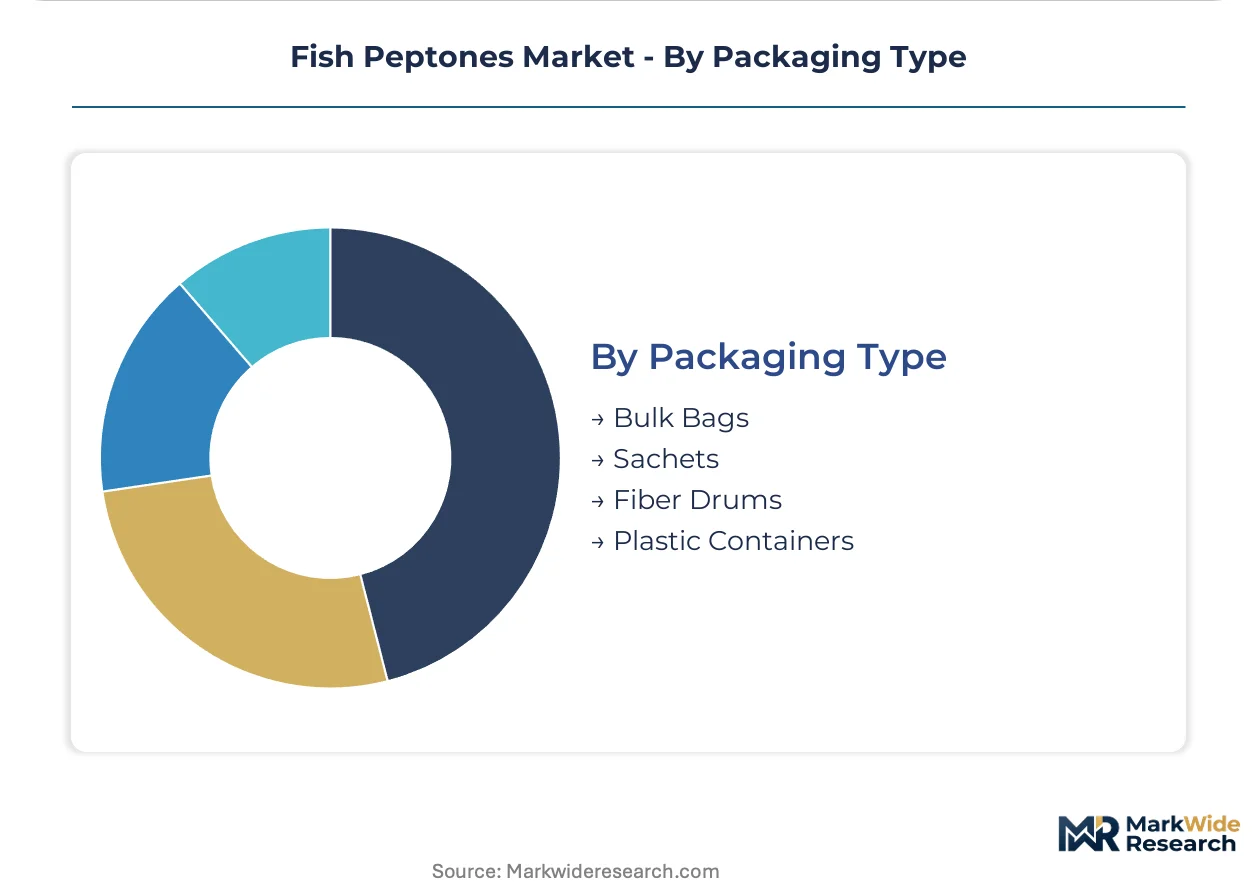
- Bulk Bags:500-1000 kg flexible intermediate bulk containers for high-volume fermentation facility intake. Norwegian processors ship directly to German and United States pharmaceutical manufacturing sites to minimize handling steps.
- Sachets:Pre-measured single-use portions for research laboratories with limited storage infrastructure.
- Fiber Drums:Multi-layer paperboard containers with moisture barriers for mid-scale biotechnology firm procurement.
- Plastic Containers:Rigid pails and jars for liquid and concentrated formulations requiring sealed containment.
Bulk Bags dominate tonnage movements; Sachets are expanding most quickly alongside South Asian laboratory infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Atlantic cod and salmon byproduct supply concentrates in Norwegian and Icelandic processing facilities, creating geographic single-point vulnerability for premium raw material sourcing. Biotechnology firms in Germany and the United States are scaling mammalian cell culture operations that depend on these marine protein hydrolysates.
United States
FDA biologics guidance tightens raw material qualification requirements for mammalian cell line developers in Massachusetts and North Carolina. The agency mandates species traceability documentation across every production batch. Greater Boston anchors pharmaceutical-grade peptone demand as stem cell therapy developers substitute fish-derived substrates for plant-based alternatives.
Germany
EMA GMP Annex 1 revisions force dedicated allergen-controlled production lines for biologics manufacturers in Bavaria and North Rhine-Westphalia. The country's national pharmaceutical regulator requires real-time environmental monitoring data in supplier audits. Munich-based fermentation facilities consolidate supplier panels to vendors with digitized batch records.
Norway
North Atlantic fishing cooperatives standardize enzymatic extraction protocols to secure pharmaceutical-grade output volumes for export markets. The Norwegian Food Safety Authority enforces species-level documentation for marine protein hydrolysates. Bergen and Trondheim processing clusters ship bulk formulations directly to German and United States pharmaceutical manufacturing sites.
Iceland
Marine-derived protein hydrolysate production consolidates as domestic processors achieve ISO 13485 certification for diagnostic-grade supply tiers. The Icelandic Food and Veterinary Authority aligns with REACH traceability mandates for EU market access. Reykjavik-area facilities leverage renewable energy integration to reduce enzymatic hydrolysis production costs.
India
Bulk pricing strategies capture microbiology laboratory buildouts across Maharashtra and Telangana where endotoxin sensitivity remains secondary to cost containment. CDSCO diagnostic regulations create tiered market entry barriers for imported pharmaceutical-grade materials. Mumbai-based suppliers compete aggressively on research-grade peptone volumes for South Asian diagnostic infrastructure expansion.
Fish Peptones Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue certification arbitrage between research-grade and pharmaceutical-grade supply tiers. The vendor base stratifies around three structural archetypes: integrated fishery operators with backward control over raw material supply, specialized bioprocessing firms with enzymatic extraction expertise, and diversified life science distributors with global logistics networks. Dominant competitive moves include capacity expansion in North Atlantic processing clusters and strategic partnerships bridging diagnostic-grade production with medical device quality systems.
Within the integrated fishery operator tier, Kerry Group exemplifies upstream control over sustainable supply chains, while Thermo Fisher Scientific anchors the certification-intensive pharmaceutical-grade segment. HiMedia Laboratories occupies a position in the bulk pricing tier targeting high-velocity research-grade transactions across South Asian markets.
| Leading Market Players |
|---|
| Kerry Group |
| Thermo Fisher Scientific |
| HiMedia Laboratories |
| Titan Biotech |
| Solabia Group |
| Hardy Diagnostics |
| Copalis |
| Bioibérica |
| Azelis |
| Others |
Supply & Pricing Matrix
EMA GMP Annex 1 traceability mandates are forcing biologics manufacturers toward certified suppliers with species-level documentation, compressing procurement options and elevating price premiums for compliant production tiers. This specification tightening concentrates purchasing power among integrated North Atlantic processors capable of delivering pharmaceutical-grade output with digitized batch records.
Pricing Analysis
Technical service bundling separates Thermo Fisher Scientific's pharmaceutical-grade offerings from unbundled research-grade alternatives, with embedded fermentation support justifying sole-source premiums. Three-tier pricing structure across pharmaceutical-grade, diagnostic-grade, and research-grade levels reflects endotoxin certification thresholds and documentation depth. Cost compression in the research-grade tier intensifies as Indian suppliers exploit bulk pricing for South Asian microbiology laboratories. Biotechnology firms with diversified discovery-phase needs exhibit highest price sensitivity; stem cell therapy developers in Switzerland and Massachusetts show lowest sensitivity due to performance variability penalties.
Supply Chain Analysis
Domestic-content alignment with REACH traceability protocols is reshaping sourcing toward Norwegian and Icelandic processing clusters with ISO 13485 certification infrastructure. Premium Atlantic cod and salmon byproduct supply draws from North Atlantic fishing cooperatives concentrated in Bergen, Trondheim, and Reykjavik processing hubs. Proteolytic enzyme inputs rest on three European specialty chemical firms, creating single-source vulnerability for controlled hydrolysis capacity. Distribution runs through direct bulk bag shipments to German and United States pharmaceutical manufacturing sites, minimizing handling steps for endotoxin-sensitive formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fish peptones market consolidation accelerates as FDA and EMA qualification requirements harden, eliminating smaller Mediterranean processors lacking digitized traceability infrastructure. This regulatory filtering favors capital-intensive modernizers with closed-system processing capabilities.
For Market Incumbents: Anticipate proteolytic enzyme supply bottlenecks by securing long-term contracts with European specialty chemical suppliers or investing in captive enzyme production capacity. Expand ISO 13485-certified freeze-dried formulation capacity in North Atlantic processing clusters to capture stem cell therapy premiumization. Defend against soy peptone substitution in research-grade segments by emphasizing lot-to-lot consistency documentation for mammalian cell culture applications.
For New Entrants and Emerging Players: Begin with diagnostic-grade supply tier arbitrage, bridging research-grade production infrastructure with medical device quality system investments to capture margin expansion opportunities. Target South Asian microbiology laboratory buildouts in Maharashtra and Telangana with bulk pricing strategies exploiting underpenetrated diagnostic infrastructure. Pursue CDSCO regulatory alignment for Indian market entry before attempting pharmaceutical-grade qualification for export markets.
For Investors and Strategic Acquirers: The window for entry favors integrated fishery operators with backward control over sustainable supply chains and existing North Atlantic processing assets. Acquisition candidates with renewable energy-integrated enzymatic hydrolysis capacity and ISO 13485 certification infrastructure offer strongest long-term viability through the biologics manufacturing scale-up cycle. Monitor LAL assay capacity constraints at third-party laboratories as an inflection signal for batch release timeline pressures affecting pharmaceutical customer switching costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Fishery Supply Chains | Kerry Group's upstream control secures raw material consistency for pharmaceutical-grade output. |
| Pharmaceutical-Grade Certification Programs | Thermo Fisher Scientific's technical service embedding filters smaller competitors from high-specification segments. |
| Continuous Enzymatic Reactor System Deployment | Commercial-scale facilities displace batch hydrolysis to compress production costs and improve batch consistency. |
| Single-Pass Tangential Flow Filtration Adoption | Swiss and Massachusetts CDMOs achieve molecular weight precision below five kilodaltons for cell therapy media. |
| Real-Time Environmental Monitoring Infrastructure | German biologics producers consolidate supplier panels to vendors with digitized batch records under EMA GMP Annex 1. |
Research Methodology
Multi-period observation of enzymatic extraction protocol standardization, certification tier migration patterns, and procurement framework consolidation anchored the trend analysis, supplemented by interviews with fermentation media procurement managers, GMP compliance officers at biologics manufacturers, North Atlantic fishing cooperative technical directors, and diagnostic laboratory supply chain heads. Secondary validation drew from FDA biologics guidance documents, EMA GMP Annex 1 revision texts, REACH traceability mandate filings, and Norwegian Food Safety Authority species documentation requirements. Bottom-up volume modeling across formulation, application, and packaging segments triangulated against top-down industry value estimates.
Input-output matrices mapped enzymatic hydrolysis capacity utilization, peptide molecular weight distribution, and endotoxin testing throughput constraints against biologics manufacturing expansion trajectories across the analysis window. Segmentation dimensions included product type, application tier, end-use industry certification requirements, and packaging format. CAGRs derived from regression analysis of historical pharmaceutical-grade adoption rates and projected mammalian cell culture substrate substitution patterns, incorporating qualified enzyme supplier concentration and LAL assay capacity expansion timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade production volumes with documented species traceability carry tighter precision than research-grade estimates dependent on spot purchasing patterns. Forecasts reflect assumptions regarding EMA GMP Annex 1 implementation timelines, proteolytic enzyme supplier capacity expansion, and South Asian diagnostic infrastructure buildout rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Protein Hydrolysate Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Truffle Oil Market
Ingredients
Vegetable Extract Market
Ingredients
Tapioca Market
Ingredients
Fucoidan Extract Market
Ingredients
Roll-Dried Starch Market
Ingredients
Almond Ingredients Market
Ingredients
Wort Concentrate Market
Ingredients
Mung Bean Starch Market
Ingredients
Acacia Gum Market
Ingredients
Bread Flour Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
North America Malt Ingredients Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Shortening Fats Market