
 Commercial Amino Acids Market | 2026-2036
Commercial Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Amino Acids Market Outlook
Multi-source fermentation supply is broadening across the commercial amino acids value chain as manufacturers diversify beyond traditional extraction routes. Ajinomoto Co., Inc. leverages its decades-long expertise in microbial fermentation to anchor premium-grade L-glutamine output for pharmaceutical clients. CJ CheilJedang Corporation competes through integrated corn-processing infrastructure that sustains cost leadership in feed-grade lysine and threonine. Evonik Industries AG specializes in precision-cultured amino acids for animal nutrition, positioning its European biotech assets against Asian volume producers.
Commercial amino acids are organic compounds containing amine and carboxyl functional groups, typically produced via microbial fermentation or enzymatic synthesis with purity grades ranging from feed-grade to injection-grade specifications exceeding 99.5% assay. These compounds serve as essential building blocks for protein synthesis, therapeutic formulations, and nutritional fortification across industrial and clinical applications. L-glutamine dominates pharmaceutical applications due to its role in cell culture media and critical care nutrition, while animal feed remains the largest volume pool with L-lysine and L-methionine commanding the greatest tonnage. Nutraceuticals represent the fastest-expanding margin segment as fitness enthusiasts and healthcare professionals drive demand for condition-specific amino acid blends in powder and tablet forms.
The FDA enforces Current Good Manufacturing Practice standards for amino acids destined for injectable drug products, while the EMA's REACH framework governs chemical registration and environmental release thresholds for European production facilities. China's NMPA and GB standards impose parallel purity and labeling requirements that shape export competitiveness for domestic manufacturers like Fufeng Group and Meihua Holdings. Stakeholders must monitor how diverging pharmacopeial standards between FDA, EMA, and NMPA jurisdictions will influence capital allocation for dedicated versus multi-compendial production lines.
Market Dynamics
Fermentation-based purification upgrades are compressing margins for legacy extraction operators while concentrating supply among biotech-capable producers who can meet tightened pharmacopeial standards.
Growth Catalysts
- Injectable-grade purity mandates:FDA and EMA enforcement of Current Good Manufacturing Practice standards for parenteral nutrition formulations is pulling capacity toward pharmaceutical-grade fermentation infrastructure.
- Metabolic disorder therapeutics:Pharmaceutical manufacturers are expanding amino acid-based therapeutic portfolios for rare metabolic conditions, creating dedicated demand streams for L-glutamine and L-arginine.
- China's fermentation scale-up:Domestic capacity expansion in Shandong and Hebei provinces is reducing import dependency for feed-grade lysine and threonine across Asian livestock operations.
Market Restraints
- Corn price volatility:Feedstock cost swings for dextrose and starch-based fermentation media directly compress margins for lysine and threonine producers without captive corn processing.
- Single-source supply risk:Concentration of pharmaceutical-grade L-glutamine fermentation in Japanese and South Korean facilities creates vulnerability to regional logistics disruptions.
- Enzymatic synthesis substitution:Cell-free biocatalytic routes for non-essential amino acids threaten traditional fermentation economics for specialty grades below 100-ton scale.
Strategic Opportunities
- Indian pharmaceutical formulation:CDSCO's streamlined approval pathways for parenteral nutrition products are opening dedicated demand for injection-grade amino acid imports.
- Precision fermentation convergence:Integration of CRISPR-edited microbial strains with continuous bioprocessing is enabling boutique production of rare amino acids for cell culture media.
- Direct-to-practitioner distribution:Compounding pharmacies and clinical nutritionists are bypassing traditional wholesale channels for condition-specific amino acid blends.
Industry Challenges
- Pharmacopeial harmonization gaps:Diverging assay methodologies between USP, EP, and ChP standards force redundant validation runs for multi-compendial production lines.
- Bioprocess engineering talent scarcity:Fermentation optimization and downstream purification expertise concentrates among retiring cohorts without adequate pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Amino Acids Market |
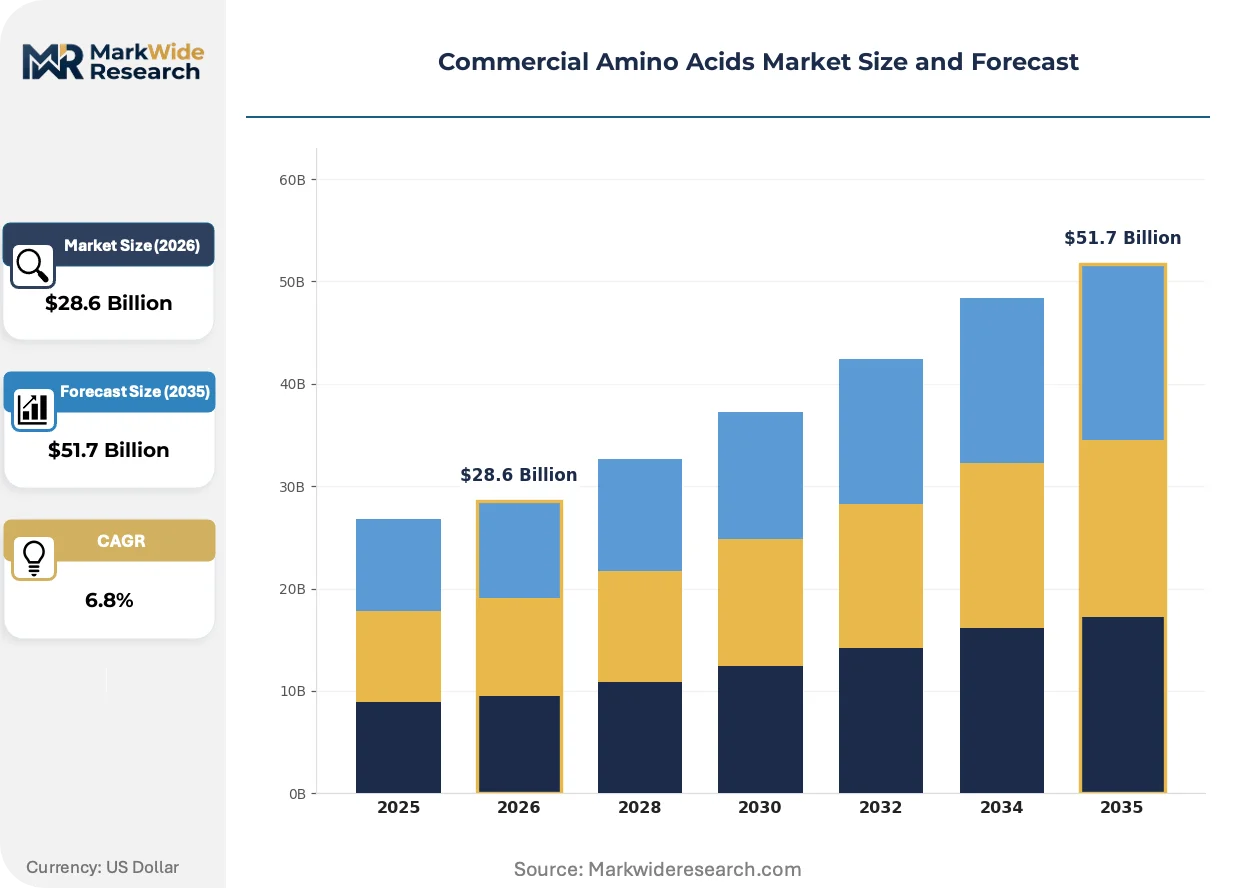
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
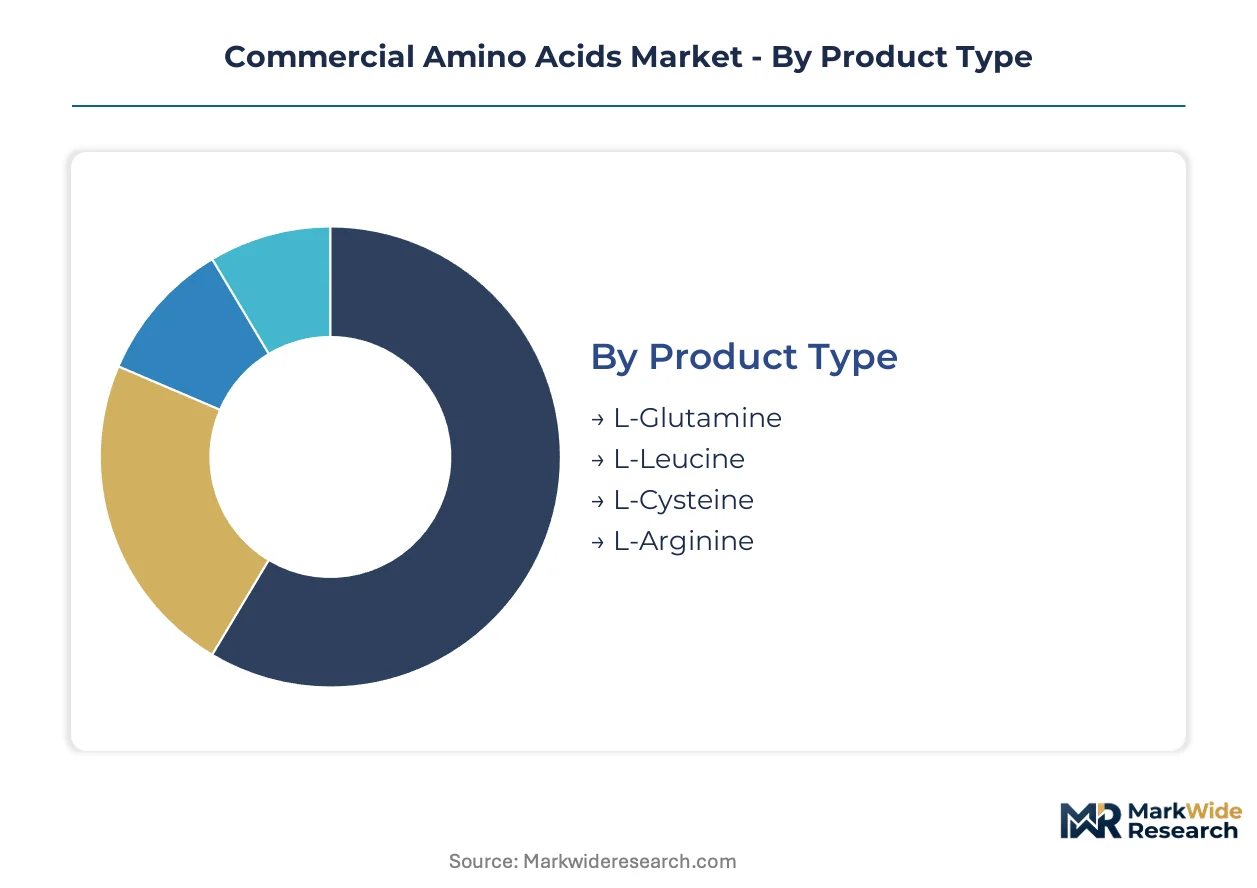
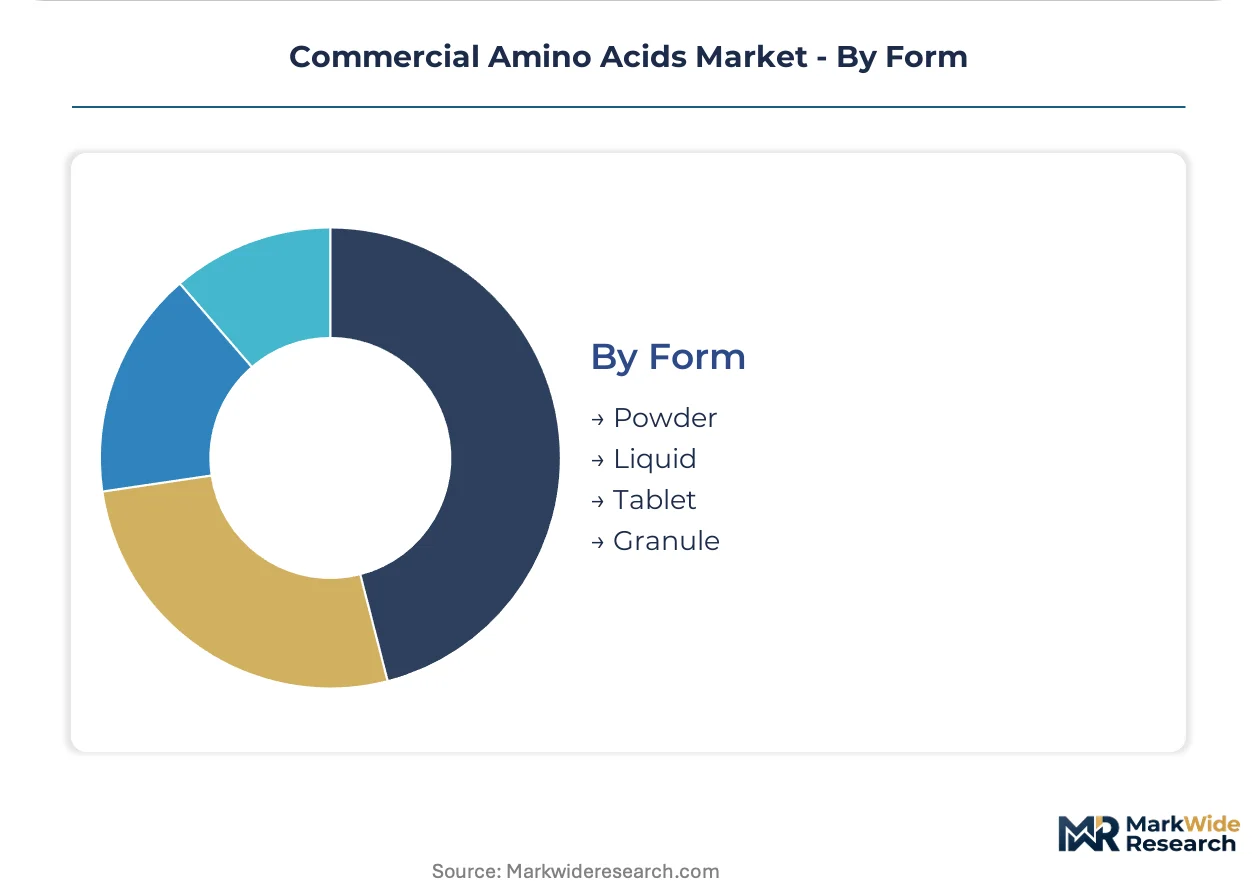
| Segmentation | Product Type: L-Glutamine, L-Leucine, L-Cysteine, L-Arginine Application: Animal Feed, Nutraceuticals, Food & Beverages, Pharmaceuticals End User: Food Industry, Healthcare Professionals, Fitness Enthusiasts, Researchers Form: Powder, Liquid, Tablet, Granule |
| Companies Covered | CJ CheilJedang Corporation, Kyowa Hakko Bio Co., Ltd., Ajinomoto Co., Inc., Meihua Holdings Group Co., Ltd., Fufeng Group Company Limited, Evonik Industries AG, Adisseo France S.A.S, Daesang Corporation, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Amino Acids Market Strategic Shifts
Continuous bioprocessing and precision fermentation are displacing batch-based manufacturing, while regulatory divergence between major jurisdictions is forcing capital-intensive compliance strategies.
Continuous fermentation technology with real-time metabolite monitoring is electrifying amino acid production economics by eliminating downtime between batches and reducing facility footprint requirements. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting these systems for injection-grade output. The technology is compressing capital recovery timelines for greenfield fermentation assets while raising barriers for batch-reliant incumbents.
REACH framework amendments on chemical registration and environmental release thresholds are tightening wastewater discharge requirements for European fermentation facilities. Producers in Germany and the Netherlands are investing in closed-loop water recovery systems to maintain operating licenses. Animal nutrition-grade output faces the steepest compliance cost escalation, pushing marginal capacity toward Asian jurisdictions with less stringent MEE oversight.
Clinical nutrition procurement is consolidating through hospital group purchasing organizations that unbundle amino acid sourcing from parenteral nutrition compound contracts. Academic medical centers in the United States are negotiating direct supply agreements with fermentation specialists, bypassing traditional pharmaceutical distributors. This disintermediation is most pronounced in pediatric and critical care units with specialized formulation requirements.
Commercial Amino Acids Market Segmentation
Commercial amino acid producers configure production lines around purity gradients and end-use specifications rather than commodity logic. Segmentation discipline separates feed-grade volume plays from pharmaceutical-grade margin capture, with form factor and customer channel adding further differentiation layers.
Product Type:
The customization-to-standardization spectrum runs from condition-specific therapeutic grades to bulk feed additives, with fermentation complexity and pharmacopeial certification determining positioning.
- L-Glutamine:Pharmaceutical-grade material exceeds 99.5% assay with endotoxin controls for parenteral nutrition and cell culture media. Demand concentrates in Japanese and South Korean fermentation facilities supplying critical care formulations, constrained by single-source supply risk and FDA purity mandates.
- L-Leucine:Branched-chain amino acid for muscle protein synthesis drives nutraceutical tablet and powder formulations. Fitness enthusiasts and sports nutrition brands in North America and Western Europe dominate procurement, with direct-to-practitioner channels bypassing traditional wholesale.
- L-Cysteine:Precursor for glutathione synthesis and pharmaceutical intermediates.
- L-Arginine:Nitric oxide pathway support for cardiovascular and metabolic disorder therapeutics.
Leading the category by volume: L-Glutamine. Growing fastest: L-Leucine.
Application:
Cost tier stratification separates commodity feed additives from premium therapeutic formulations, with regulatory burden and customer concentration shaping margin architecture.
- Animal Feed:Largest volume pool with L-lysine and L-methionine commanding greatest tonnage, though L-glutamine and L-leucine feature in specialized aquaculture and pet nutrition. China's Shandong and Hebei fermentation scale-up reduces import dependency across Asian livestock operations.
- Pharmaceuticals:Injectable-grade amino acids for metabolic disorder therapeutics and parenteral nutrition face tightened FDA and EMA Current Good Manufacturing Practice enforcement. Fermentation-based purification upgrades compress margins for legacy extraction operators unable to meet pharmacopeial standards.
- Nutraceuticals:Fastest-expanding margin segment as condition-specific amino acid blends gain traction.
- Food & Beverages:Fortification applications for processed foods and functional beverages.
Dominating by tonnage: Animal Feed. Steepest expansion trajectory: Nutraceuticals.
End User:
Customer type fragmentation spans industrial procurement at scale to individualized clinical prescribing, with channel economics and technical support requirements diverging sharply.
- Healthcare Professionals:Hospital group purchasing organizations and academic medical centers negotiate direct supply agreements with fermentation specialists, unbundling amino acid sourcing from parenteral nutrition compound contracts. Pediatric and critical care units drive specialized formulation demand.
- Fitness Enthusiasts:Direct-to-consumer powder and tablet purchases through specialty retailers and e-commerce platforms. Compounding pharmacies and clinical nutritionists increasingly bypass traditional wholesale for condition-specific amino acid blends.
- Food Industry:Industrial buyers sourcing feed-grade and food-grade material in bulk.
- Researchers:Cell culture media and laboratory reagent procurement for biotechnology applications.
Highest volume concentration: Food Industry. Gaining share fastest: Fitness Enthusiasts.
Form:
Supply concentration and logistics economics favor powder for industrial scale, while patient compliance and dosing precision drive pharmaceutical and nutraceutical form diversification.
- Powder:Dominant form for animal feed compounding, bulk nutraceutical manufacturing, and food fortification. Fermentation output typically dries to crystalline powder for cost-efficient transport and storage, with Chinese producers leveraging domestic corn-processing infrastructure for feed-grade lysine and threonine powder output.
- Tablet:Precision-dosed format for clinical nutrition and fitness applications. Hospital group purchasing organizations and direct-to-practitioner channels favor tablets for patient compliance in parenteral nutrition and metabolic disorder protocols.
- Liquid:Ready-to-use formulations for critical care and enteral nutrition.
- Granule:Intermediate form for feed milling and controlled-release applications.
Commanding greatest volume: Powder. Expanding most quickly: Tablet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade demand concentrates in Japanese and South Korean fermentation clusters, while feed-grade production scales across Chinese provincial hubs. Regulatory divergence between FDA, EMA, and NMPA jurisdictions shapes capital allocation for multi-compendial production lines.
China
Domestic fermentation capacity in Shandong and Hebei provinces drives feed-grade lysine and threonine output for Asian livestock operations. NMPA and GB standards impose parallel purity and labeling requirements that shape export competitiveness for manufacturers like Fufeng Group and Meihua Holdings. Corn-processing infrastructure in these provinces sustains cost leadership without captive starch supply.
Japan
Pharmaceutical-grade L-glutamine fermentation anchors critical care nutrition and cell culture media supply chains. METI and PMDA oversight maintains stringent endotoxin controls for injectable-grade material. Ajinomoto's decades-long microbial fermentation expertise in Tokyo and Kawasaki facilities concentrates premium-grade output for parenteral nutrition formulations.
United States
Hospital group purchasing organizations and academic medical centers negotiate direct supply agreements with fermentation specialists, unbundling amino acid sourcing from compound contracts. FDA enforcement of Current Good Manufacturing Practice standards for injectable drug products pulls capacity toward pharmaceutical-grade infrastructure. Pediatric and critical care units in Boston and Philadelphia drive specialized formulation demand.
Germany
REACH framework amendments tighten wastewater discharge requirements for European fermentation facilities, pushing investment into closed-loop water recovery systems. EMA pharmacopeial standards govern chemical registration and environmental release thresholds for production sites in Ludwigshafen and Marl. Animal nutrition-grade output faces steepest compliance cost escalation among German biotech assets.
Switzerland
Pharmaceutical contract manufacturers adopt continuous fermentation technology with real-time metabolite monitoring for injection-grade output. Swissmedic oversight aligns with EMA standards while maintaining distinct validation protocols for biologics and cell culture media. Basel and Geneva facilities compress capital recovery timelines through electrified production economics.
Commercial Amino Acids Market Competitive Environment
Capacity expansion dominates the current landscape as fermentation specialists scale pharmaceutical-grade infrastructure to meet tightened FDA and EMA purity mandates. The vendor base separates into three tiers: Asian volume producers with integrated corn-processing assets, European precision fermentation specialists, and Japanese premium-grade operators with decades-long microbial expertise. Strategic archetypes include feed-grade cost leaders, injection-grade purity specialists, and nutraceutical form factor innovators. M&A activity concentrates on biotech-capable targets with pharmacopeial certification, while geographic expansion targets Indian pharmaceutical formulation demand.
Within the premium-grade tier, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. occupy positions anchored by Japanese fermentation heritage. CJ CheilJedang Corporation exemplifies the integrated corn-processing archetype with Korean infrastructure sustaining feed-grade cost leadership. Evonik Industries AG represents European precision-cultured positioning against Asian volume competition.
| Leading Market Players |
|---|
| CJ CheilJedang Corporation |
| Kyowa Hakko Bio Co., Ltd. |
| Ajinomoto Co., Inc. |
| Meihua Holdings Group Co., Ltd. |
| Fufeng Group Company Limited |
| Evonik Industries AG |
| Adisseo France S.A.S |
| Daesang Corporation |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Continuous fermentation technology with real-time metabolite monitoring is simultaneously compressing production economics and concentrating supply among biotech-capable operators who can amortize capital-intensive upgrades across pharmaceutical-grade output. This technological transition rewards Japanese and South Korean facilities with legacy microbial expertise while marginalizing batch-reliant extraction operators unable to meet tightened FDA and EMA purity mandates.
Pricing Analysis
Service bundling separates pharmaceutical-grade amino acid supply into validated pharmacopeial packages versus unbundled feed-grade commodity transactions. Three-tier pricing structure across injection-grade, food-grade, and feed-grade levels reflects divergent certification burdens and endotoxin control requirements. Pricing pressure stems from China's corn-processing scale-up in Shandong and Hebei provinces, which compresses lysine and threonine margins without captive starch supply. Hospital group purchasing organizations exhibit lowest price sensitivity for parenteral nutrition formulations, while Asian livestock operations drive feed-grade procurement on cost-per-ton metrics.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO approval pathways for parenteral nutrition products are reshaping sourcing patterns toward local formulation partnerships. Supply concentrates in China for feed-grade lysine and threonine, Japan for pharmaceutical-grade L-glutamine, and South Korea for precision-cultured specialty grades. Corn dextrose, microbial seed stocks, and chromatography resins constitute critical input dependencies. Single-source vulnerability runs through Japanese L-glutamine fermentation clusters concentrated in Tokyo and Kawasaki facilities. Distribution runs through hospital group purchasing organizations in the United States, direct supply agreements with academic medical centers, and integrated corn-processing infrastructure in Asian feed-grade markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable-grade fermentation capacity operates under structural constraint, with pharmacopeial certification timelines and bioprocess engineering talent scarcity propping pricing power for qualified suppliers.
For Market Incumbents: Anchor pharmaceutical-grade margin capture through backward integration into chromatography resin supply and continuous bioprocessing infrastructure in Swiss and Singaporean contract manufacturing hubs. Defend against enzymatic synthesis substitution threats by deepening FDA and EMA validation moats for rare metabolic disorder therapeutics. Prioritize certification investment for multi-compendial production lines spanning USP, EP, and ChP standards. For New Entrants and Emerging Players: The price-point gap between premium injection-grade and economy feed-grade amino acids opens white-space targeting of nutraceutical tablet and powder formulations for fitness enthusiasts and direct-to-practitioner channels. India's CDSCO-streamlined parenteral nutrition approvals offer the most penetrable regulatory entry point for fermentation specialists seeking pharmaceutical-grade validation. Pursue precision fermentation convergence with CRISPR-edited strains for boutique cell culture media applications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical contract manufacturers seeking captive amino acid supply for biologics production. Long-term viability favors targets with demonstrated pharmacopeial certification and continuous fermentation technology deployment across the analysis window. Monitor bioprocess engineering talent pipeline indicators as the primary inflection signal for supply constraint duration.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Investment | FDA and EMA multi-compendial validation opens hospital group purchasing organization contracts. |
| Continuous Fermentation Technology Deployment | Real-time metabolite monitoring compresses capital recovery timelines for Swiss and Singaporean facilities. |
| Backward Integration into Corn Processing | Captive starch supply insulates lysine and threonine margins from dextrose price volatility. |
| Precision Fermentation Convergence | CRISPR-edited strains enable boutique production of rare amino acids for cell culture media. |
| Direct-to-Practitioner Distribution Buildout | Compounding pharmacy channels bypass traditional wholesale for condition-specific amino acid blends. |
Study Parameters
Independent corroboration across fermentation plant managers, pharmaceutical procurement leads at hospital group purchasing organizations, regulatory affairs specialists, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from FDA Current Good Manufacturing Practice guidance documents, EMA REACH framework amendments, NMPA GB standards filings, and customs trade data for corn-derived fermentation feedstocks. Bottom-up capacity assessments triangulate against top-down demand modeling from parenteral nutrition formulation volumes and animal feed compounding rates.
Rate-of-change decomposition across the projection horizon separates volume growth in feed-grade lysine and threonine from value expansion in pharmaceutical-grade L-glutamine and L-arginine. Segmentation dimensions include purity grade tier, end-use application, form factor, and regional regulatory cluster. CAGRs derive from installed fermentation capacity forecasts, pharmacopeial approval timelines, and substitution elasticity estimates for enzymatic synthesis routes. Industry-specific inputs incorporate corn price volatility indices and bioprocess engineering labor market tightness.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time continuous fermentation adoption rates and precision fermentation strain performance introduce uncertainty bands. Forecasts reflect documented assumptions regarding pharmacopeial harmonization progress and corn feedstock cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Dairy Ingredients Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Bleached Flour Market
Ingredients
Corn Gluten Meal Market
Ingredients
Germany Gelatin Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Chewing Gum Base Market
Ingredients
Cheese Cultures Market
Ingredients
Pet Food Ingredients Market
Ingredients
Compressed Yeast Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
North America Vegetable Oils Market
Ingredients
Mung Bean Starch Market
Ingredients
China Cane Sugar Market
Ingredients
Plant Extracts Market