
 Global Cocoa Products Market | 2026-2036
Global Cocoa Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cocoa Products Market Analysis
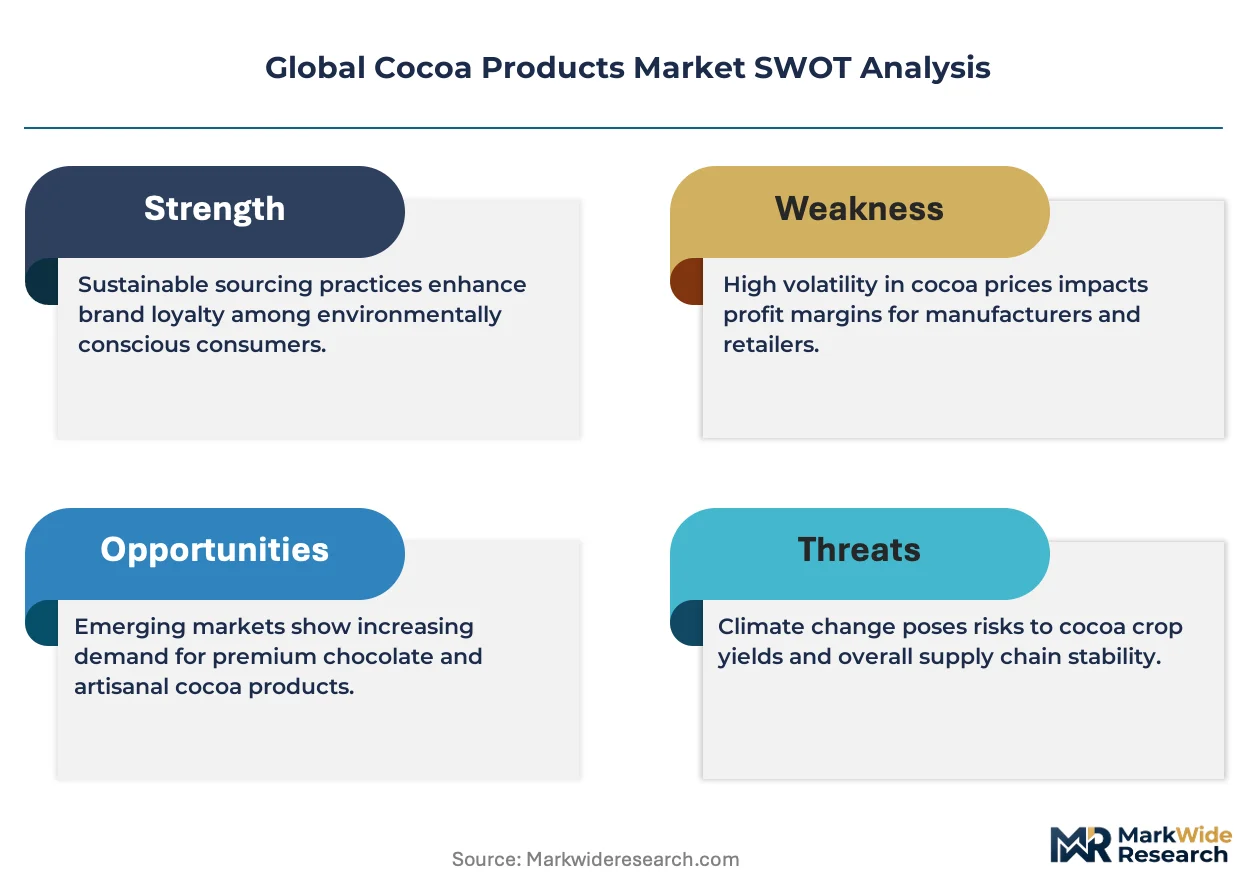
EU Deforestation Regulation is repositioning compliance costs for cocoa traders and processors entering European markets. Barry Callebaut AG leverages its vertical integration from bean sourcing to chocolate manufacturing to absorb traceability mandates. Cargill, Incorporated sustains its origination network across Côte d'Ivoire and Ghana while embedding GPS-mapping systems. Olam Group anchors its competitive stance through sustainability certification programs that preempt regulatory barriers.
Cocoa products encompass all processed derivatives from Theobroma cacao beans, including cocoa butter with its characteristic melting point near 34°C, cocoa powder containing 10-24% residual cocoa butter, and cocoa liquor produced through grinding roasted nibs into a smooth paste. These materials serve as foundational inputs across food manufacturing, providing flavor, texture, and shelf-stability to finished goods. Chocolate as a product type occupies the largest value pool due to premium positioning in confectionery and gifting channels, while cocoa butter commands margin concentration in cosmetics and pharmaceutical applications. Beverage applications represent a mature volume segment, whereas bakery integration is expanding fastest as clean-label cocoa powders replace synthetic flavoring systems.
EFSA standards on heavy metal thresholds in cocoa powders, FDA food safety modernization requirements for imported ingredients, and the EU Green Deal's embedded carbon accounting are collectively tightening product specifications and documentation burdens across the value chain. These frameworks advantage operators with pre-existing laboratory infrastructure and supplier audit capabilities. Stakeholders must monitor regulatory divergence between European and North American compliance thresholds to avoid stranded inventory or rejected shipments at port.
Market Dynamics
The EU Deforestation Regulation is compressing supplier margins and forcing rapid traceability infrastructure deployment across bean-to-bar networks, fundamentally restructuring how cocoa enters European processing facilities.
Growth Catalysts
- Bean-to-bar craft movement:Artisanal chocolate makers in Belgium and Switzerland are building direct farmer relationships that bypass commodity exchanges, capturing premium positioning through provenance storytelling.
- Clean-label bakery reformulation:Food manufacturers are replacing synthetic flavoring systems with natural cocoa powders, expanding industrial demand for standardized powder specifications.
- EU Green Deal carbon accounting:Embedded emissions tracking is creating competitive advantage for operators with pre-existing laboratory infrastructure and verified supply chain data.
Market Restraints
- West African supply concentration:Côte d'Ivoire and Ghana collectively originate over sixty percent of global cocoa beans, exposing processors to synchronized weather shocks and political instability.
- Heavy metal compliance costs:EFSA thresholds for cadmium and lead in cocoa powders are forcing expensive soil remediation programs and supplier switching at origin.
- Cocoa butter price volatility:Cosmetic and pharmaceutical manufacturers face margin pressure from butter price swings tied to confectionery demand cycles and grind ratios.
Strategic Opportunities
- Latin American fine flavor expansion:Ecuador, Peru, and Colombia are developing denomination-of-origin systems that command price premiums in specialty chocolate channels.
- Pharmaceutical cocoa butter applications:Excipient-grade butter for suppository and coating applications represents a high-margin segment with limited supplier competition.
- Blockchain traceability platforms:Distributed ledger technology is converging with satellite mapping to create immutable provenance records that satisfy EU Deforestation Regulation documentation burdens.
Industry Challenges
- Farmer certification capacity gaps:Scaling Rainforest Alliance and Fairtrade programs requires training extension services that do not exist at sufficient density in remote growing regions.
- Legacy ERP integration friction:Traceability mandates are forcing processors to retrofit decades-old inventory systems with GPS coordinate capture and batch-level genealogy tracking.
- Grinding facility reconfiguration timelines:Converting lines for segregated handling of certified versus conventional beans demands extended shutdown periods that compress quarterly output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cocoa Products Market |
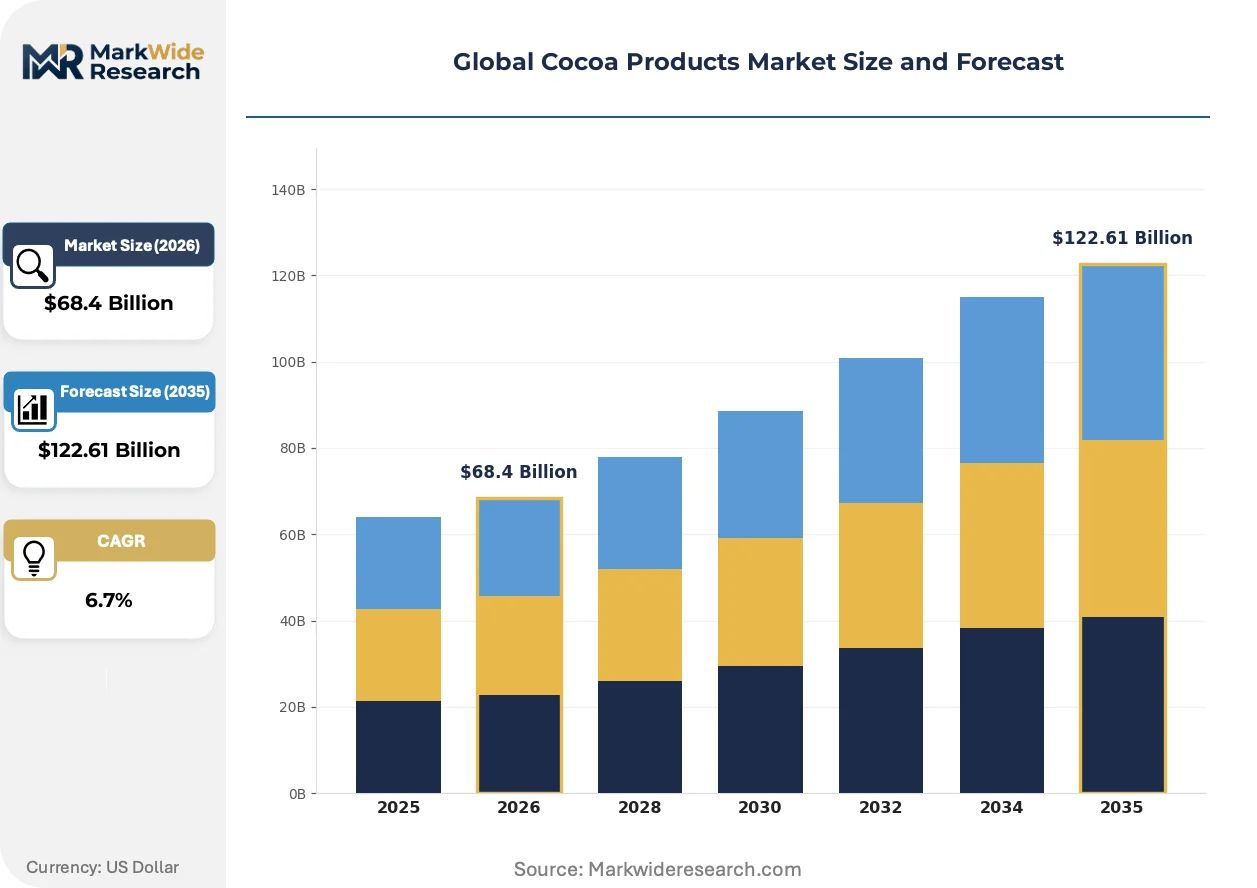
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $122.61 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Powder, Cocoa Butter, Chocolate, Cocoa Liquor Application: Beverages, Confectionery, Bakery, Dairy End User: Food Industries, Beverage Makers, Retailers, Restaurants Form: Solid, Liquid, Semi-Solid, Powdered |
| Companies Covered | Barry Callebaut AG, Cargill, Incorporated, Olam Group, Nestlé S.A., Mars Incorporated, Fuji Oil Holdings Inc., The Hershey Company, Ferrero Group, Mondelez International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cocoa Products Market Emerging Trajectories
Processing technology and regulatory compliance systems are converging to reshape competitive advantage, with traceability infrastructure now functioning as a core production capability rather than a peripheral cost center.
Precision fermentation-derived cocoa butter is expanding into cosmetic formulation pipelines as brands seek supply security independent of agricultural harvest variability. Personal care manufacturers in France and Germany are piloting microbial butter at commercial scale. This technology is expanding into premium chocolate applications as sensory parity with conventional butter improves.
REACH chemical registration requirements are tightening contaminant disclosure obligations for cocoa-derived ingredients entering European cosmetic and food contact applications. Manufacturers must now document full substance composition down to 0.1 percent weight-by-weight for previously exempt natural extracts. Mid-sized processors without dedicated regulatory affairs teams are outsourcing compliance to specialized consulting firms.
Confectionery buyers are consolidating supplier relationships to reduce audit burden under overlapping ESG frameworks. Multinational brands are shifting from transactional spot purchasing toward multi-year partnership contracts with integrated processors who control origination through manufacturing. This concentration is most visible in Swiss and Belgian industrial chocolate supply chains, where three processors now originate over half of certified sustainable volume.
Global Cocoa Products Market Segmentation
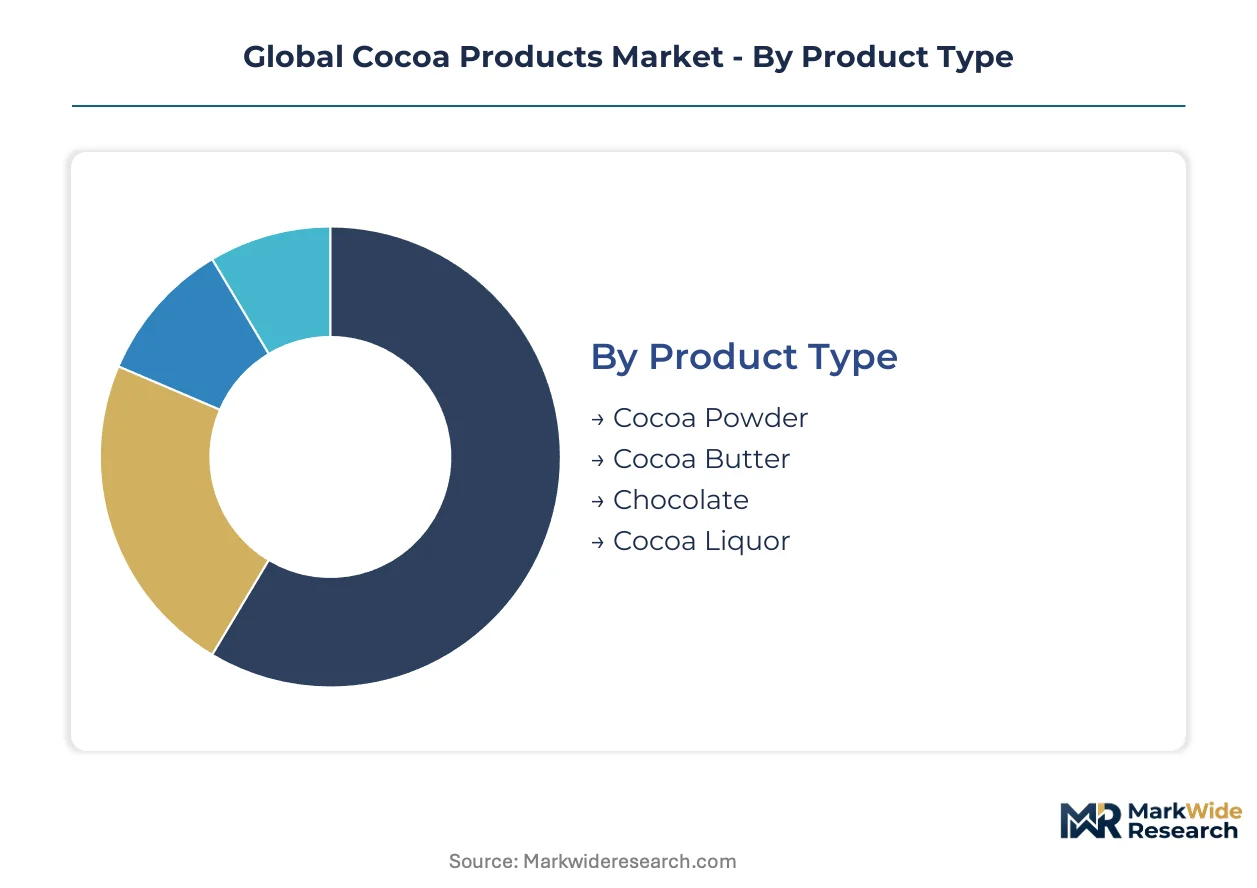
Cocoa product specifications vary dramatically across downstream applications, with confectionery demanding precise tempering properties while beverage formulations prioritize solubility and color stability. Segmentation clarity enables processors to align grinding ratios and butter extraction yields with specific customer performance requirements rather than commodity benchmarks.
Product Type:
Supply concentration in West African bean origination directly shapes which product types command margin stability versus volatility exposure.
- Chocolate:Finished chocolate combines cocoa liquor with sugar and cocoa butter in ratios calibrated for snap, gloss, and mouthfeel. European confectionery manufacturers in Belgium and Switzerland absorb premium positioning through controlled tempering and extended conching cycles. Demand concentrates in gift-box and premium tablet formats where provenance storytelling justifies price elevation.
- Cocoa Butter:This fat fraction melts at approximately 34°C, providing the signature snap and clean melt of quality confectionery. Cosmetic formulators in France and Germany secure pharmaceutical-grade supply for suppository excipients and coating applications where purity specifications exceed food-grade thresholds. Price volatility tracks confectionery grind ratios and harvest variability.
- Cocoa Powder:Press cake residue containing 10-24% residual butter serves clean-label bakery reformulation replacing synthetic flavoring systems.
- Cocoa Liquor:Ground roasted nibs form the paste foundation for chocolate manufacturing and industrial flavoring applications.
Today's leader: Chocolate. Tomorrow's challenger: Cocoa butter.
Application:
Cost tier differentiation separates commodity volume plays from premium positioning opportunities across downstream channels.
- Confectionery:Chocolate tablets, pralines, and enrobed products demand precise tempering curves and fat bloom resistance. EFSA heavy metal thresholds and EU Deforestation Regulation documentation requirements favor integrated processors with captive laboratory infrastructure. Swiss and Belgian industrial chocolate supply chains concentrate certified sustainable volume among three dominant processors.
- Bakery:Clean-label reformulation is accelerating natural cocoa powder substitution for synthetic flavoring systems in cakes, cookies, and pastries. North American and European food manufacturers specify standardized color and fat content for consistent batch performance. This segment is gaining share fastest as regulatory pressure on artificial ingredients intensifies.
- Beverages:Hot chocolate and malted drinks represent mature volume demand with emphasis on dispersibility and sediment control.
- Dairy:Ice cream and flavored milk applications utilize cocoa powder for cost-efficient color and flavor delivery.
Confectionery commands absolute value. Bakery offers the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with integrated manufacturers demanding batch genealogy while food service prioritizes cost efficiency.
- Food Industries:Industrial manufacturers of baked goods, cereals, and prepared desserts specify cocoa powders by pH, color, and fat content for formulation consistency. EFSA cadmium and lead thresholds force supplier switching and soil remediation programs at origin. These buyers consolidate relationships to reduce audit burden under overlapping ESG frameworks.
- Beverage Makers:Instant drink and ready-to-drink manufacturers require spray-dried powders with controlled particle size for solubility performance.
- Retailers:Private-label chocolate and baking cocoa programs compete on price positioning with limited traceability premiums.
- Restaurants:Food service channels prioritize volume pricing and reliable supply over certification complexity.
Food industries dominate procurement sophistication. Beverage makers are consolidating supplier relationships fastest.
Form:
Physical state determines handling infrastructure requirements and logistics cost structures across the value chain.
- Solid:Chocolate blocks and cocoa butter slabs require controlled temperature storage and specialized melting equipment for industrial processing. Belgian and Swiss bean-to-bar operations favor solid formats for artisanal tempering control and provenance verification.
- Liquid:Bulk cocoa liquor and melted butter reduce handling costs for high-volume confectionery manufacturers with continuous production lines.
- Powdered:Cocoa powder enables precise dosing and extended shelf stability for bakery and beverage applications.
- Semi-Solid:Intermediate viscosity products serve niche cosmetic and pharmaceutical compounding requirements.
Solid formats anchor premium positioning. Liquid forms are displacing solids in industrial scale operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss and Belgian confectionery clusters anchor the global workforce for cocoa processing expertise, with specialized tempering and conching skills concentrated in Alpine and Benelux industrial zones. Ghana and Côte d'Ivoire field the largest farming labor pools for bean cultivation and primary fermentation. Processing infrastructure concentrates in European port cities with deep logistics integration.
Switzerland
Artisanal chocolate manufacturing and industrial processing command premium positioning through controlled tempering expertise. Swissmedic regulates food contact materials and cosmetic-grade cocoa butter purity for pharmaceutical applications. The Lake Geneva corridor hosts bean-to-bar operations that bypass commodity exchanges through direct farmer relationships.
Belgium
Confectionery demand concentrates in praline and enrobed product manufacturing with exacting fat bloom resistance requirements. EFSA heavy metal thresholds for cadmium and lead force laboratory infrastructure investments at processing facilities. The Port of Antwerp anchors grinding operations with segregated handling lines for certified versus conventional bean flows.
Germany
Cosmetic formulators in France and Germany secure pharmaceutical-grade cocoa butter for suppository excipients and coating applications. REACH chemical registration requirements tighten contaminant disclosure obligations for cocoa-derived ingredients entering cosmetic pipelines. Hamburg and Frankfurt processing clusters embed GPS-mapping systems for EU Deforestation Regulation compliance.
United States
Clean-label bakery reformulation accelerates natural cocoa powder substitution for synthetic flavoring systems in cakes and cookies. FDA food safety modernization requirements for imported ingredients tighten documentation burdens at port entry. Pennsylvania and Illinois industrial zones consolidate supplier relationships to reduce audit burden under overlapping ESG frameworks.
Brazil
Chocolate tablet and confectionery manufacturing expands through domestic bean sourcing and regional distribution networks. ANVISA regulates food additive thresholds and contaminant limits for processed cocoa derivatives. São Paulo state grinding facilities retrofit legacy ERP systems with batch-level genealogy tracking for export compliance.
Global Cocoa Products Market Vendor Landscape
The competitive structure tilts toward integrated processors with captive origination networks. Three dominant processors in Swiss and Belgian supply chains now originate over half of certified sustainable volume. Two strategic archetypes define positioning: vertically integrated grinders controlling bean sourcing through manufacturing, and specialty chocolate houses leveraging provenance storytelling for premium tier access. Competitive moves concentrate on multi-year partnership contracts replacing spot purchasing, and blockchain traceability platform deployment.
Among Swiss- and Belgian-based integrated processors, Barry Callebaut AG exemplifies the vertically integrated archetype with bean-to-bar control spanning West African origination to European manufacturing. Cargill, Incorporated represents the agricultural commodity trader model with embedded GPS-mapping systems across Côte d'Ivoire and Ghana networks. Olam Group occupies a position within the sustainability certification tier, anchoring competitive stance through programs that preempt regulatory barriers.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill, Incorporated |
| Olam Group |
| Nestlé S.A. |
| Mars Incorporated |
| Fuji Oil Holdings Inc. |
| The Hershey Company |
| Ferrero Group |
| Mondelez International, Inc. |
| Others |
Supply Flow & Price Mechanics
Premium-commodity divergence between bean-to-bar artisanal channels and industrial bulk processing manifests in dual supply chain configurations: direct farmer relationships with GPS-verified provenance versus commodity exchange sourcing with minimal traceability. Certification ladders from Rainforest Alliance to Fairtrade organic create price stratification that tracks backward into segregated handling infrastructure at grinding facilities.
Pricing Analysis
Bean-to-bar bundling of provenance verification with finished chocolate commands 40-60% premiums over unbundled commodity cocoa liquor traded on futures exchanges. Price differentiation rests on certification grade and volume scale, with small-batch roasters absorbing higher per-unit costs for single-origin traceability. Pricing pressure intensifies in industrial cocoa powder segments as clean-label bakery reformulation accelerates demand for standardized specifications. Food manufacturers exhibit highest price sensitivity, while cosmetic formulators securing pharmaceutical-grade cocoa butter show lowest elasticity due to purity requirements.
Supply Chain Analysis
EU Deforestation Regulation local-content verification rules are reshaping sourcing patterns toward documented origin farms with polygon-mapped boundaries. Côte d'Ivoire, Ghana, and Ecuador anchor global bean supply, with grinding capacity concentrated in Belgian and Swiss industrial clusters. The chain draws from fermented dry beans, jute bagging materials, and ocean freight logistics vulnerable to West African port congestion. Single-source vulnerability concentrates in Ivorian political instability and synchronized harvest shocks. Distribution runs through Antwerp and Hamburg port terminals into European processing facilities, with secondary flows reaching North American confectionery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium chocolate tiers where EU regulatory compliance creates scarcity value for verified supply chains, while precision fermentation alternatives threaten commodity butter pricing power.
For Market Incumbents: Cement multi-year partnership contracts with multinational confectionery brands to lock in certified sustainable volume before traceability mandates fully phase in. Prioritize laboratory infrastructure investments for EFSA heavy metal compliance as a defensive moat against mid-sized processors lacking captive testing capabilities. Backward integration into Ecuadorian and Peruvian fine flavor origination secures premium tier access against Latin American specialty chocolate houses. For New Entrants and Emerging Players: EU Deforestation Regulation in Europe opens a window for blockchain traceability platform providers to capture compliance service revenue from legacy processors retrofitting decades-old ERP systems. Target pharmaceutical-grade cocoa butter excipient supply as the most penetrable segment, where limited supplier competition and purity premiums reward new entrants with laboratory capabilities. Pursue direct-to-farmer origination in Colombia's emerging denomination-of-origin zones as the go-to-market angle for specialty chocolate positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where traceability infrastructure investments exceed standalone processor cash generation capacity, creating distressed acquisition opportunities among mid-sized European grinders. Long-term viability favors vertically integrated operators with captive West African origination networks and European manufacturing footprint. Watch for inflection in precision fermentation butter sensory parity as the signal that agricultural supply security premiums may compress in cosmetic and pharmaceutical applications.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Platform Deployment | Immutable provenance records satisfy EU Deforestation Regulation documentation burdens at Antwerp grinding facilities. |
| Pharmaceutical-Grade Butter Capacity Expansion | Excipient-grade production captures suppository and coating margins exceeding food-grade thresholds in German cosmetic pipelines. |
| Latin American Fine Flavor Origination | Denomination-of-origin systems in Ecuador and Peru command specialty chocolate premiums through controlled fermentation protocols. |
| Legacy ERP Retrofit with GPS Integration | Batch-level genealogy tracking prevents stranded inventory from rejected shipments at European port entry. |
| Precision Fermentation Butter Pilot Scale-Up | Microbial butter production reduces harvest variability exposure for French and German personal care manufacturers. |
Methodological Framework
Coverage spans West African origination zones, European processing clusters, and North American downstream markets, with primary inputs from each. The analysis combines interviews with cocoa procurement directors at integrated processors, sustainability certification officers at Rainforest Alliance and Fairtrade programs, and regulatory affairs leads at Belgian and Swiss confectionery manufacturers. Secondary validation draws from EFSA contaminant threshold documentation, EU Deforestation Regulation implementation guidance, customs trade data for bean flows through Antwerp and Hamburg, and SEC filings for publicly traded processors. Bottom-up volume modeling triangulates against top-down value estimates from grinder capacity utilization and chocolate manufacturing output.
Granularity extends to product type, application, and end-user dimensions across the projection horizon, with additional modeling of certification tier and geographic origin cluster specific to cocoa supply chains. CAGRs derive from segmented growth rate analysis applied to baseline volume and value estimates. Forecast inputs incorporate EU Green Deal carbon accounting trajectory, EFSA heavy metal threshold enforcement timing, and precision fermentation butter commercialization pace in cosmetic applications.
Revisions become necessary when West African political instability disrupts bean flows, precision fermentation achieves sensory parity with conventional butter, or regulatory divergence between European and North American compliance thresholds strands cross-Atlantic inventory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Desiccated Coconut Market
Ingredients
Pine Needle Oil Market
Ingredients
North America Carrageenan Market
Ingredients
Asparagus Extract Market
Ingredients
Fluid Lecithin Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Industrial Sugar Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Bread Flour Market
Ingredients
Meat Tenderizer Powder Market