
 Indonesia Edible Oil Market | 2026-2036
Indonesia Edible Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Edible Oil Market Intelligence
Refined, bleached, and deodorized palm olein is redrawing quality benchmarks across Indonesia's edible oil trade. PT SMART TBK leverages its integrated plantation-to-refinery network to sustain supply continuity for industrial buyers. Wilmar International Ltd anchors its position through bulk distribution infrastructure spanning Sumatra and Kalimantan. PT Salim Ivomas Pratama Tbk differentiates via specialty fat formulations targeting bakery and confectionery segments.
Edible oil encompasses triglyceride-based fats extracted from oilseeds and fruits, refined to achieve specific free fatty acid thresholds, iodine values, and smoke points for culinary and food manufacturing applications. Palm oil dominates Indonesia's product type landscape due to the country's position as the world's largest crude palm oil producer, while coconut oil maintains niche premium positioning in traditional cooking and cosmetics-adjacent food sectors. The end user base tilts toward food manufacturers, which purchase bulk unpackaged volumes for instant noodle frying, margarine compounding, and snack production, whereas households increasingly shift toward pouches and bottles through supermarket channels.
Indonesia's Ministry of Agriculture and BIS-equivalent national standards body enforce fortification mandates and labeling rules that shape product formulations and market access requirements for domestic and imported oils. The country's biodiesel policy framework, administered by the Energy and Mineral Resources Ministry, creates direct competition for crude palm oil feedstock between energy and food applications. Stakeholders must monitor policy recalibrations on blend mandates and export levy structures to anticipate feedstock availability and pricing trajectories for edible oil production.
Market Dynamics
Indonesia's mandatory B35 biodiesel policy diverts roughly 35% of national crude palm oil output toward fuel blending, tightening feedstock availability for edible oil refiners and forcing food manufacturers to compete directly with state-mandated energy offtake.
Growth Catalysts
- Processed food manufacturing expansion:Instant noodle producers and snack manufacturers in Java are scaling bulk refined palm oil procurement to meet domestic and export demand.
- B35 mandate infrastructure:State-owned Pertamina's distribution network for biodiesel creates captive offtake channels that stabilize upstream plantation revenues.
- Fortification regulations:Indonesia's Ministry of Agriculture mandates vitamin A fortification in packaged cooking oils, driving product reformulation and premium positioning.
Market Restraints
- Feedstock competition:Crude palm oil price volatility intensifies as the same CPO stream splits between B35 biodiesel quotas and food-grade refining.
- Sumatra supply concentration:Over 70% of Indonesia's palm oil originates from Riau and North Sumatra estates, creating geographic vulnerability to El Niño drought patterns.
- Coconut oil substitution ceiling:Traditional cooking segments in Eastern Indonesia resist palm oil switching due to established taste preferences and cultural usage patterns.
Strategic Opportunities
- Eastern Indonesia penetration:Papua and Maluku provinces show underdeveloped retail distribution for branded pouch oils relative to Java's saturation.
- Specialty fat formulations:Bakery and confectionery manufacturers seek tailored palm fractions with specific melting profiles for tropical climate stability.
- Supermarket channel expansion:Modern trade formats in Surabaya and Medan are displacing traditional wet markets for household cooking oil purchases.
Industry Challenges
- Refinery certification timelines:RSPO and ISPO sustainability audits require 12-18 month compliance cycles that delay export market access.
- Skilled process engineering scarcity:Bleaching and deodorization unit optimization demands specialized talent concentrated in Jakarta and Singapore.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Edible Oil Market |
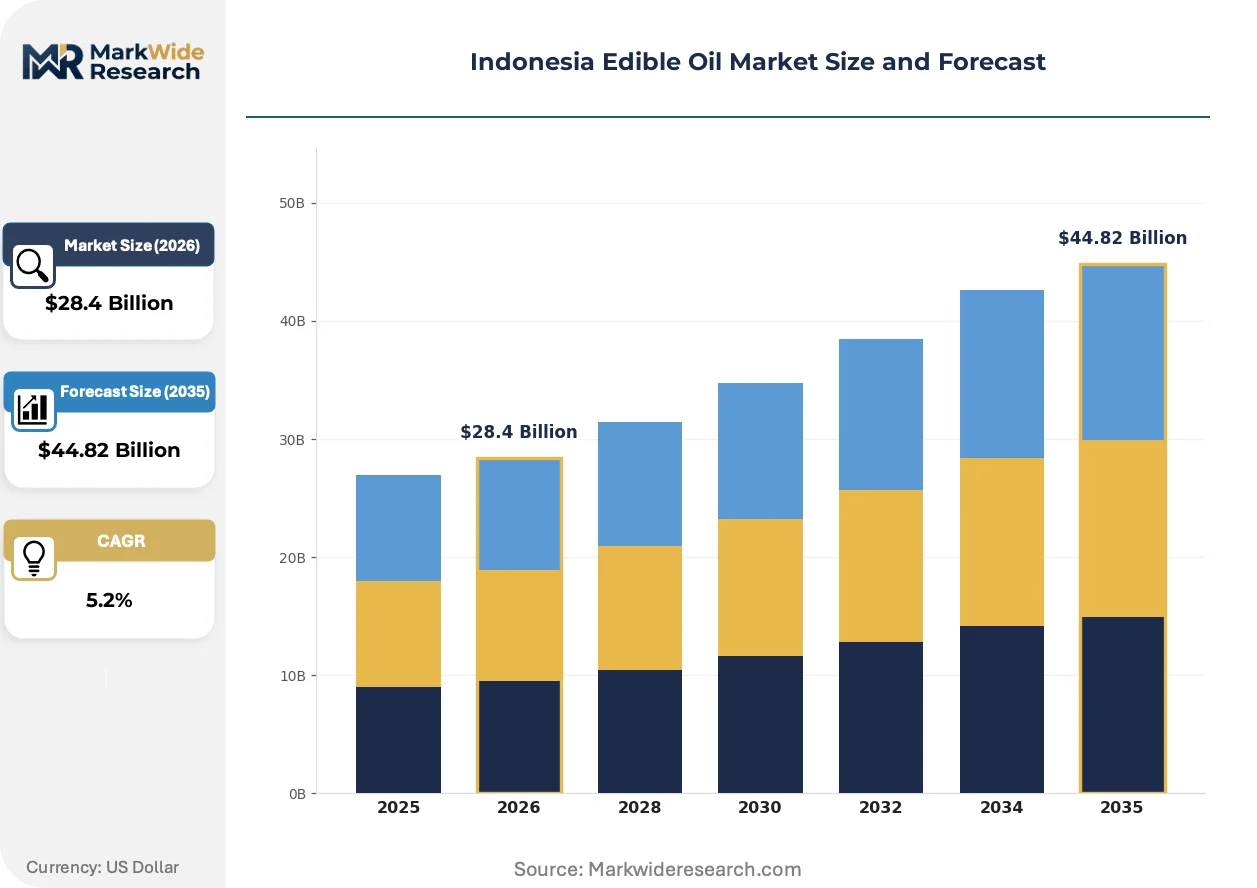
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $44.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Palm Oil, Soybean Oil, Sunflower Oil, Coconut Oil End User: Households, Food Manufacturers, Restaurants, Bakeries Distribution Channel: Online Retail, Supermarkets, Wholesalers, Convenience Stores Packaging Type: Bottles, Cans, Pouches, Bulk |
| Companies Covered | PT Salim Ivomas Pratama Tbk, PT Tunas Baru Lampung Tbk, PT SMART TBK, PT Socfin Indonesia, PT Cargill Indonesia, Wilmar International Ltd, PT PP London Sumatra Indonesia Tbk, PT Asianagri Hilir, Astra Agro Lestari Tbk PT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Edible Oil Market Strategic Shifts & Innovations
Physical refining technology is compressing operational margins and quality variance across Indonesia's edible oil sector. Three developments are restructuring competitive positioning.
Membrane filtration systems for crude palm oil pretreatment are miniaturizing capital requirements for mid-scale refiners. Regional processors in South Sumatra and Central Kalimantan are adopting skid-mounted units to bypass conventional clarification infrastructure. This technology is miniaturizing the minimum efficient scale for refined olein production.
Indonesia's Ministry of Energy and Mineral Resources enforces B35 blend mandates through domestic market obligation regulations. Refiners must allocate production quotas between energy and food applications under penalty of license suspension. Food manufacturers face feedstock rationing that prioritizes state-owned biodiesel offtake.
Household buyers are consolidating purchases through modern retail channels that bundle cooking oil with staple commodities. Supermarket chains in Jakarta and Surabaya now capture packaged oil volumes previously fragmented across independent kiosks. This concentration is most visible in Java's urban corridors where cold-chain logistics enable premium product segmentation.
Indonesia Edible Oil Market Segmentation
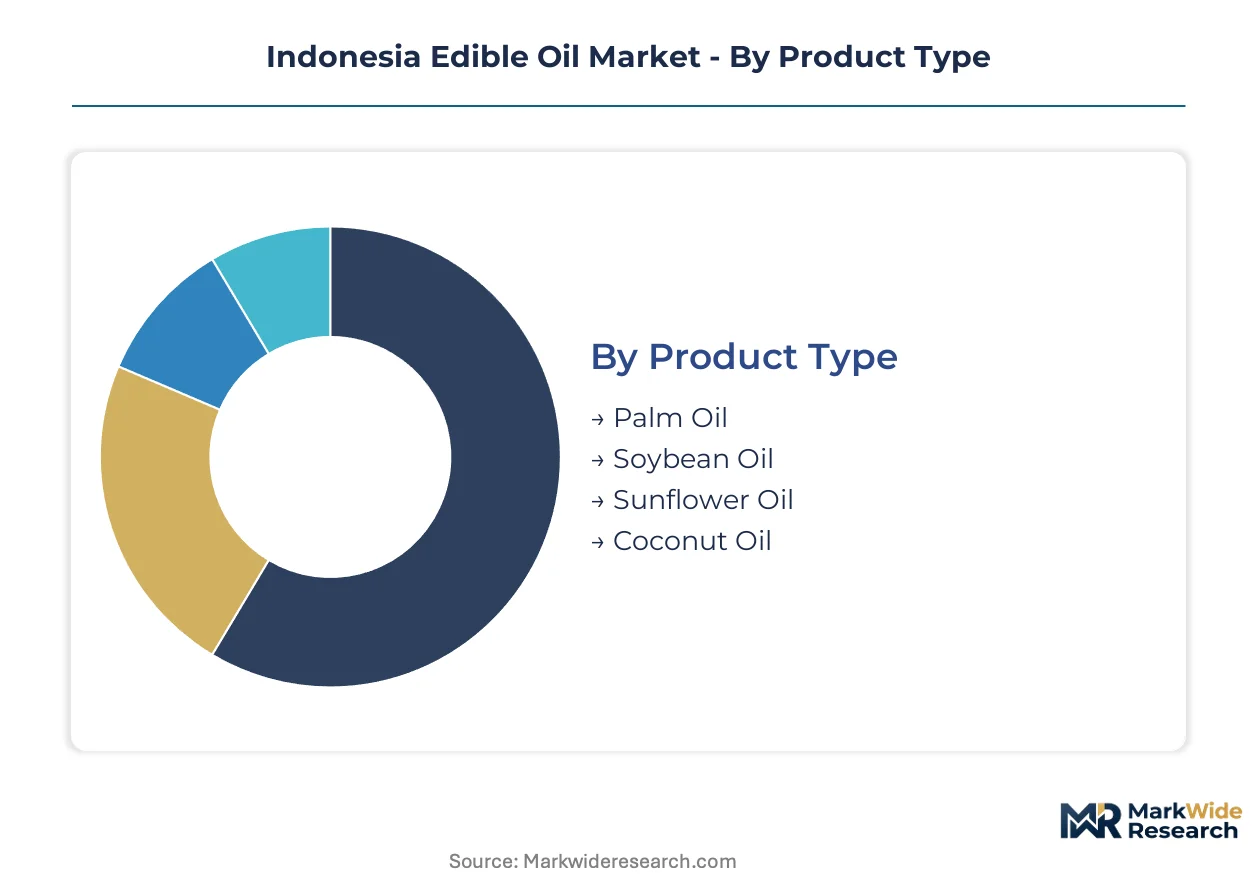
Segmentation in Indonesia's edible oil market reveals how B35 biodiesel diversion and fortification mandates reshape competitive priorities across product tiers and channel configurations. Manufacturers must align portfolio depth with the divergence between industrial bulk procurement and household packaged consumption.
Product Type:
Palm oil faces the most acute substitution pressure from biodiesel feedstock diversion, while coconut oil defends its position through taste loyalty in Eastern Indonesia.
- Palm Oil:Refined, bleached, and deodorized palm olein dominates industrial frying applications with specific free fatty acid thresholds below 0.1% and smoke points exceeding 230°C. Food manufacturers in Jakarta and Surabaya absorb the largest bulk volumes for instant noodle production, though B35 quotas tighten CPO availability for food-grade refining.
- Coconut Oil:Cold-pressed and copra-derived variants maintain premium positioning in traditional cooking segments across Maluku and Papua, where cultural usage patterns resist palm oil switching despite price differentials.
- Soybean Oil:Imported volumes serve reformulation needs for bakery applications requiring specific iodine values and oxidative stability profiles.
- Sunflower Oil:Niche positioning in premium supermarket channels targets health-conscious households in Jakarta's urban corridors.
Palm oil retains volume leadership; coconut oil holds the steepest expansion curve in premium household segments.
End User:
Cost tier stratification separates bulk industrial procurement from branded retail pricing, with food manufacturers capturing economies of scale unavailable to fragmented household buyers.
- Food Manufacturers:Instant noodle producers and snack manufacturers purchase unpackaged tanker volumes exceeding 20,000 liters per delivery, leveraging direct refinery relationships to bypass distribution markups. Java's processing clusters in Bekasi and Sidoarjo concentrate demand for standardized olein specifications.
- Households:Individual consumers shift from independent kiosks toward modern retail formats, purchasing 1-2 liter pouches and bottles with vitamin A fortification compliance.
- Restaurants:Small and medium enterprises in Surabaya and Medan source 18-liter jerrycans through wholesale distributors, prioritizing price stability over brand differentiation.
- Bakeries:Specialty fat requirements drive tailored palm fraction procurement with specific melting point ranges for tropical climate stability.
Food manufacturers command the largest volume share; bakeries are climbing the fastest as specialty formulation demand accelerates.
Distribution Channel:
Channel concentration in Java creates geographic asymmetry, with modern retail penetration in Eastern Indonesia lagging by 40-60 percentage points.
- Supermarkets:Jakarta and Surabaya chains bundle cooking oil with rice and sugar, displacing wet market fragmentation through cold-chain logistics that enable premium product segmentation.
- Wholesalers:Traditional distributors in Medan and Makassar serve restaurant and bakery segments with bulk breaking and credit terms unavailable through modern trade.
- Convenience Stores:Indomaret and Alfamart networks capture emergency household purchases in urban corridors, though unit economics favor higher-margin packaged goods.
- Online Retail:E-commerce platforms aggregate subscription-based replenishment for Jakarta households, with delivery logistics constraining penetration outside Java.
Wholesalers retain volume leadership; online retail is expanding most quickly as urban logistics infrastructure matures.
Packaging Type:
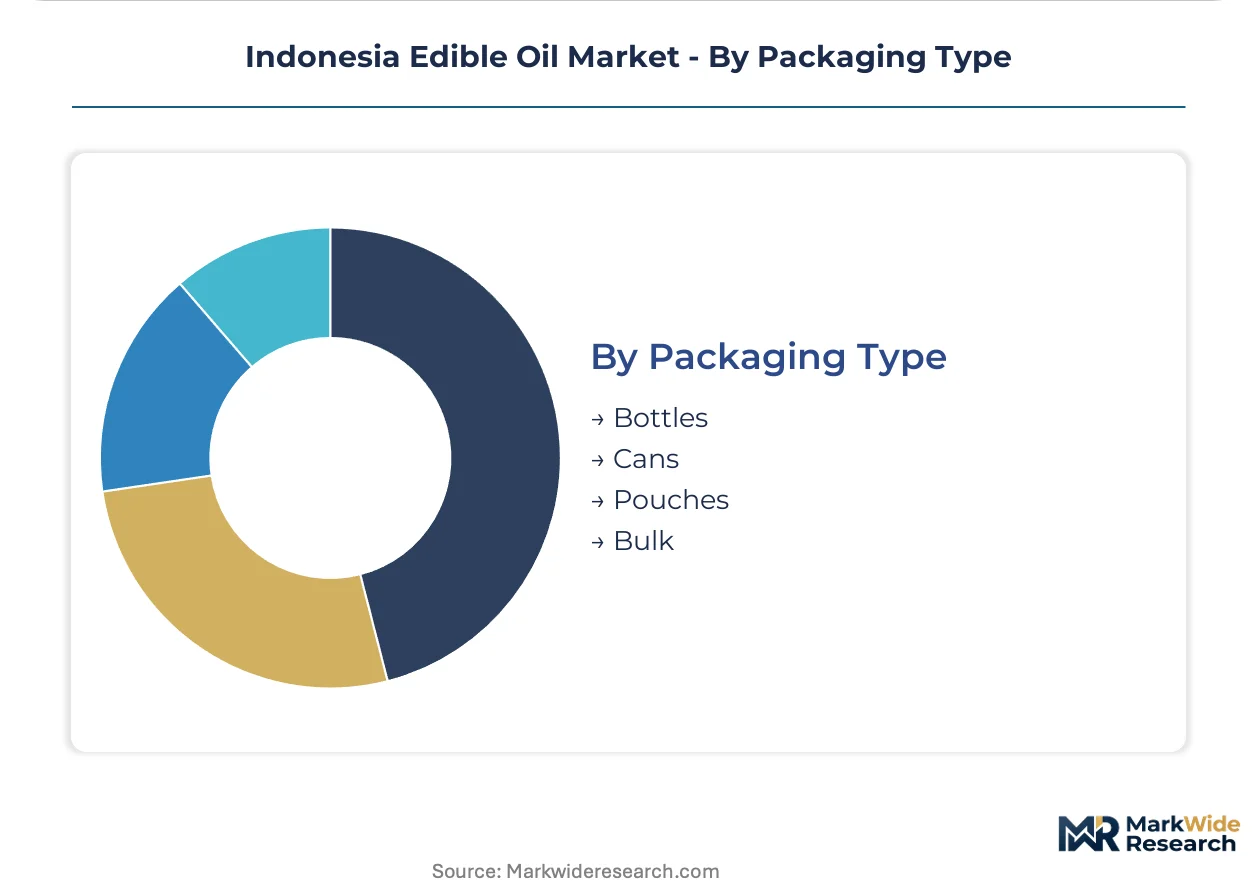
Margin structure inversely correlates with volume scale, with bulk tanker deliveries generating sub-5% margins while 250ml pouches capture 15-20% unit economics.
- Bulk:Tanker and flexitank deliveries serve food manufacturers with 20,000-40,000 liter minimum order quantities, eliminating packaging costs but requiring dedicated handling infrastructure at receiving facilities.
- Pouches:Flexible laminate sachets in 250ml-1 liter formats dominate Eastern Indonesia's price-sensitive rural markets, where per-use purchasing patterns persist.
- Bottles:PET and HDPE containers in 1-2 liter sizes anchor supermarket shelf space in Java, with transparent packaging enabling quality signaling through color clarity.
- Cans:Metal packaging preserves oxidative stability for coconut oil variants targeting premium export and gift segments.
Bulk commands absolute volume leadership; pouches are gaining share fastest as Eastern Indonesia retail infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia exports refined palm olein to India, China, and Pakistan, with Java's processing clusters serving as the primary consolidation points for international shipments. The archipelago's internal trade flows move CPO from Sumatra and Kalimantan estates to refineries in Jakarta and Surabaya before distribution to domestic manufacturers and export terminals.
Java
Instant noodle producers in Bekasi and Sidoarjo absorb the largest bulk volumes of RBD palm olein for frying applications. The Ministry of Agriculture enforces vitamin A fortification mandates that reshape product formulations for packaged retail oils. Jakarta's urban corridors concentrate supermarket distribution networks that displace traditional wet market fragmentation through cold-chain logistics.
Sumatra
Riau and North Sumatra estates generate over 70% of national crude palm oil output, creating geographic vulnerability to El Niño drought patterns. The Energy and Mineral Resources Ministry administers B35 biodiesel quotas that divert plantation output toward state-owned Pertamina offtake channels. Medan functions as the primary consolidation hub for CPO shipments to Java-based refineries and international export terminals.
Kalimantan
Central and East Kalimantan plantations are expanding mature hectarage to capture premium pricing from RSPO-certified sustainable production. Provincial governments enforce ISPO compliance timelines that extend 12-18 months for new refinery licensing. Samarinda and Balikpapan host emerging processing infrastructure that reduces dependency on Java-based refining capacity.
Sulawesi
Traditional coconut oil production in North Sulawesi maintains premium positioning for cold-pressed variants targeting export and gift segments. National standards bodies align local copra processing with BIS-equivalent quality thresholds for oxidative stability and free fatty acid content. Makassar serves as the distribution anchor for wholesale channels serving restaurant and bakery segments across Eastern Indonesia.
Papua and Maluku
Cultural usage patterns in these provinces resist palm oil switching despite price differentials, preserving coconut oil dominance in household cooking. Underdeveloped retail infrastructure creates penetration opportunities for branded pouch oils through Indomaret and Alfamart network expansion. Jayapura and Ambon represent nascent modern trade markets where per-use purchasing patterns still dominate rural consumption.
Indonesia Edible Oil Market Key Industry Players
Listed leaders compete with private specialists across plantation-to-refinery integration depth, with public entities commanding capital access for downstream expansion while private operators retain flexibility in specialty fractionation. The market structures around three tiers: integrated plantation-refinery conglomerates, standalone processing specialists, and trading houses with bulk distribution infrastructure. Strategic archetypes include backward-integrated upstream controllers, mid-scale regional processors with membrane filtration adoption, and logistics-anchored distributors with supermarket channel penetration. Dominant competitive moves involve refinery capacity expansion in Kalimantan and strategic partnerships between plantation groups and instant noodle manufacturers for captive offtake agreements.
Among Indonesia-based integrated producers, PT SMART TBK and PT Salim Ivomas Pratama Tbk occupy positions exemplifying the plantation-to-refinery archetype, while Wilmar International Ltd anchors the multinational trading and distribution tier. These entities represent contrasting strategic postures: domestic conglomerates with upstream estate control versus Singapore-headquartered operators with bulk infrastructure spanning Sumatra and Kalimantan. The competitive dynamic centers on feedstock security under B35 diversion pressure, with integrated players capturing margin stability unavailable to standalone refiners dependent on spot CPO procurement.
| Leading Market Players |
|---|
| PT Salim Ivomas Pratama Tbk |
| PT Tunas Baru Lampung Tbk |
| PT SMART TBK |
| PT Socfin Indonesia |
| PT Cargill Indonesia |
| Wilmar International Ltd |
| PT PP London Sumatra Indonesia Tbk |
| PT Asianagri Hilir |
| Astra Agro Lestari Tbk PT |
| Others |
Cost & Logistics Intelligence
ISPO certification timelines gate both refinery licensing and premium price realization for Indonesian palm oil exporters, compressing margin windows for processors caught between compliance costs and biodiesel quota pressures. Food manufacturers absorb feedstock volatility through long-term offtake contracts while household buyers face fortification-mandated price premiums at retail.
Pricing Analysis
Industrial food manufacturers anchor contract-based long-term offtake pricing for bulk RBD palm olein, with price differentiation driven by RSPO certification tier and volume scale commitments. Pricing pressure stems from B35 biodiesel quotas diverting crude palm oil feedstock toward state-mandated energy applications. Small restaurant operators in Surabaya and Medan exhibit highest price sensitivity due to thin operating margins, while instant noodle producers leverage direct refinery relationships to minimize procurement markups.
Supply Chain Analysis
Strait of Malacca transit underwrites CPO movement from Riau and North Sumatra estates to Java-based refineries, with the waterway handling over 70% of national palm oil output. Raw material dependencies center on mature fresh fruit bunches, harvesting labor pools, and caustic soda for refining processes. Single-source vulnerability concentrates in El Niño-exposed Sumatra growing regions. Distribution runs through Pertamina's biodiesel allocation system for energy quotas, with independent tanker networks serving food-grade refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's edible oil sector sits in early-cycle expansion as Eastern Indonesia retail infrastructure penetrates underdeveloped provinces. Supermarket channel consolidation in Java creates templateable expansion models for Papua and Maluku.
For Market Incumbents: Shield refinery margins by securing captive CPO supply through backward integration into Kalimantan plantation assets. Accelerate ISPO and RSPO certification investments to maintain export market access against tightening EU deforestation regulations. Prioritize specialty fat formulation capabilities to capture bakery and confectionery demand for tropical-stable melting profiles.
For New Entrants and Emerging Players: Lead with membrane filtration technology adoption to miniaturize efficient scale requirements for South Sumatra and Central Kalimantan regional processing. Target Papua and Maluku pouch oil distribution through Indomaret and Alfamart network partnerships. Deploy subscription-based e-commerce replenishment models for Jakarta households to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane-equipped mid-scale refiners, enabling asset-light entry strategies. Five-to-ten year viability favors processors with integrated plantation-to-retail footprints and fortification compliance infrastructure. Monitor B35 blend mandate recalibrations as the primary inflection signal for feedstock availability trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kalimantan Plantations | Captive CPO supply secures margin stability under B35 diversion pressure from Pertamina quotas. |
| Membrane Filtration Technology Adoption | Skid-mounted pretreatment units reduce minimum efficient scale for regional South Sumatra processors. |
| ISPO and RSPO Certification Investment | Twelve-to-eighteen month compliance cycles unlock EU export channels and premium price realization. |
| Eastern Indonesia Distribution Expansion | Indomaret and Alfamart network penetration captures underdeveloped Papua and Maluku retail demand. |
| Specialty Fat Formulation Development | Tailored palm fractions with tropical climate stability meet bakery and confectionery specification requirements. |
Research Approach
Cross-validation between primary interviews with refinery operations managers, plantation estate directors, and supermarket category buyers anchors the qualitative findings against customs export records, Ministry of Agriculture fortification compliance filings, and Energy and Mineral Resources biodiesel allocation data. Bottom-up volume estimates from individual processing facility capacities triangulate with top-down national CPO production statistics.
Sensitivity analysis around B35 mandate stringency and El Niño drought probability shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user category, distribution channel, and packaging format. CAGRs derive from fitted trend extrapolation against historical production and consumption trajectories, with inputs including plantation mature hectarage expansion schedules and retail modern trade penetration rates.
Forecasts assume regulatory continuity in Indonesia's biodiesel blending mandates and fortification requirements; material policy shifts would require re-modeling. Revision becomes warranted when B35 quota allocations or ISPO enforcement timelines cross threshold deviations from baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe BBQ Charcoal Market
Ingredients
Global Edible Oil Market
Ingredients
Bleached Flour Market
Ingredients
Kairomones Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
Mastic Gum Market
Ingredients
Torula Yeast Market
Ingredients
Camelina Oil Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Native Starch Market
Ingredients
Quark Powder Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Biotech Ingredients Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market