
 Propylene Terpolymer Market | 2026-2036
Propylene Terpolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Terpolymer Market Analytics
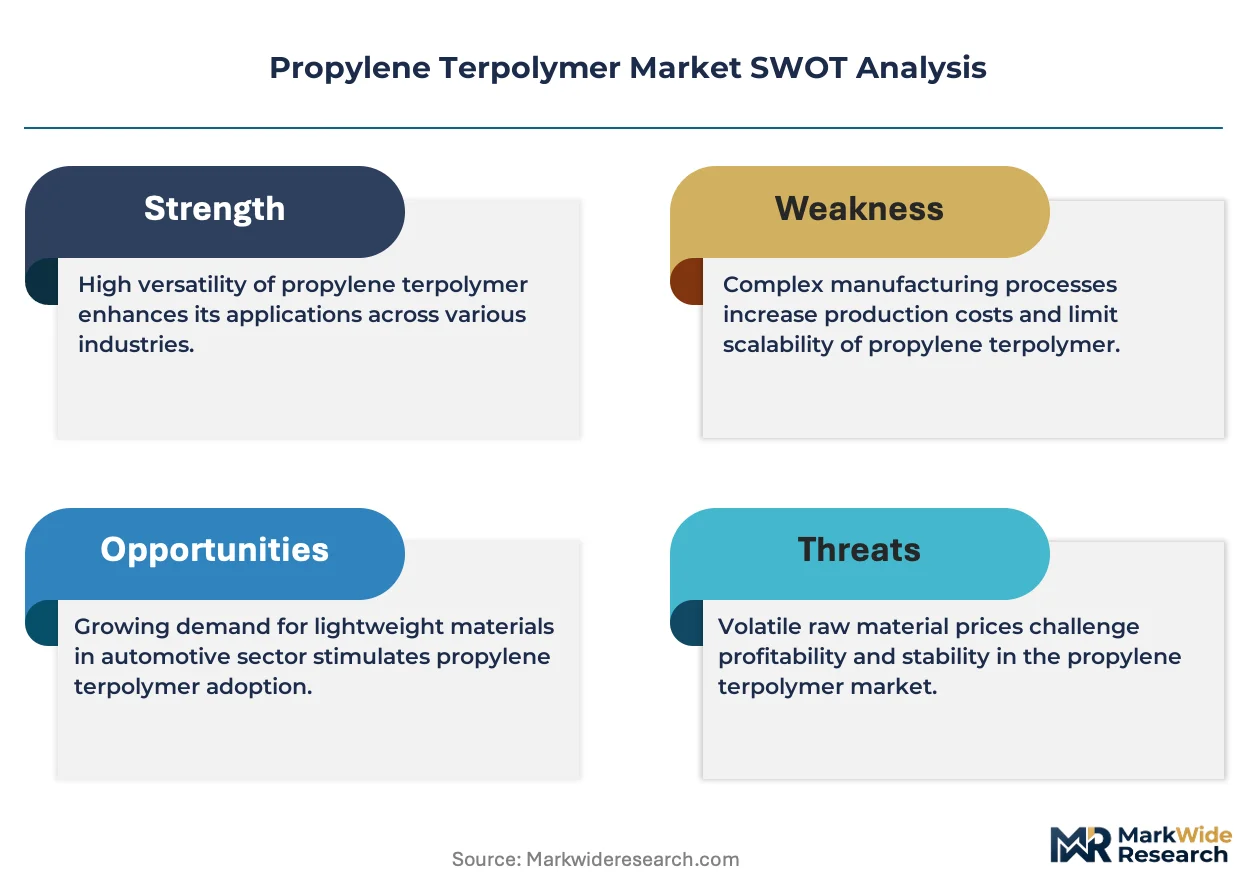
Polymer engineering talent is collapsing across European resin compounders, forcing producers to automate batch-control systems or relocate technical centers. LyondellBasell Industries leverages its Houston technology campus to sustain North American random copolymer leadership. Borealis AG anchors European medical-grade supply through its Borouge joint venture in Abu Dhabi. SABIC competes on feedstock-integrated cost positions across Middle Eastern pellet exports.
Propylene terpolymer denotes a polyolefin elastomer synthesized from propylene with two comonomers—typically ethylene and a diene or higher alpha-olefin—yielding vulcanizate-like performance without crosslinking, with Shore A hardness typically spanning 60–90 and service temperatures from minus 40 to 135 degrees Celsius. Random copolymer formulations dominate packaging film applications where optical clarity and heat-seal initiation temperatures below 110 degrees Celsius prove critical. Block copolymer grades occupy the automotive interior segment, balancing flexural modulus against low-temperature ductility for instrument panel skins and door seals. Grafted copolymer variants represent the fastest-growing product type, as maleic anhydride functionalization enables adhesion to polar substrates in multi-layer medical device constructions.
REACH registration requirements under ECHA govern monomer residual limits for European medical device applications, while FDA 21 CFR 177.1520 establishes olefin polymer migration thresholds for U.S. food-contact films. China's GB standards for plastic materials in food packaging, administered by SAMR, create divergent testing protocols that fragment qualification timelines for multinational suppliers. Stakeholders must monitor regulatory harmonization negotiations between the EU Green Deal chemical sustainability targets and emerging Chinese dual-carbon compliance deadlines for polymer carbon intensity certification.
Market Dynamics
Automotive OEMs are forcing propylene terpolymer specifications toward thinner-gauge, lower-density formulations that maintain impact resistance while cutting vehicle mass, compressing traditional random copolymer margins across European and Asian supply chains.
Growth Catalysts
- Lightweighting mandates:NHTSA fuel economy standards in the United States and EU CO2 fleet targets are accelerating instrument panel and door seal conversions from ABS and PVC to propylene terpolymer substrates.
- REACH registration:ECHA's streamlined monomer residual protocols for medical-grade polymers are reducing qualification timelines for European device manufacturers, expanding addressable formulation volumes.
- China's eastern corridor:Zhejiang and Jiangsu provinces are concentrating polymer compounding capacity, creating localized feedstock access that shortens delivery lead times for automotive Tier 1 suppliers.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker margins in Northeast Asia swing with crude oil differentials, compressing terpolymer producer spreads without long-term offtake contracts.
- Specialty catalyst concentration:Metallocene single-site catalyst supply concentrates among three technology licensors, creating bottleneck risk for grafted copolymer grade expansion.
- Polyamide substitution:High-temperature under-hood applications above 150 degrees Celsius remain inaccessible to propylene terpolymer, ceding share to PA6 and PA66 compounds in thermal management modules.
Strategic Opportunities
- India's medical device PLI scheme:The country's production-linked incentive framework for domestic manufacturing is attracting compounding joint ventures to serve catheter and IV bag demand previously met by European imports.
- Multi-layer film convergence:Maleic anhydride grafting technology is enabling adhesive tie layers between polyolefin barriers and polar substrates in retort pouches, opening processed food packaging previously closed to unmodified polypropylene.
- SAMR GB standard harmonization:China's administration for market regulation is aligning food-contact migration test protocols with FDA 21 CFR frameworks, potentially collapsing dual-qualification costs for multinational film suppliers.
Industry Challenges
- Polymer engineering talent scarcity:European resin compounders face collapsing technical workforce pipelines, forcing automation of batch-control systems or relocation of R&D functions to Middle Eastern and North American campuses.
- Medical-grade certification timelines:FDA 21 CFR 177.1520 olefin polymer migration studies require 24-36 month validation cycles, locking working capital in pre-revenue inventory for device-grade formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Terpolymer Market |
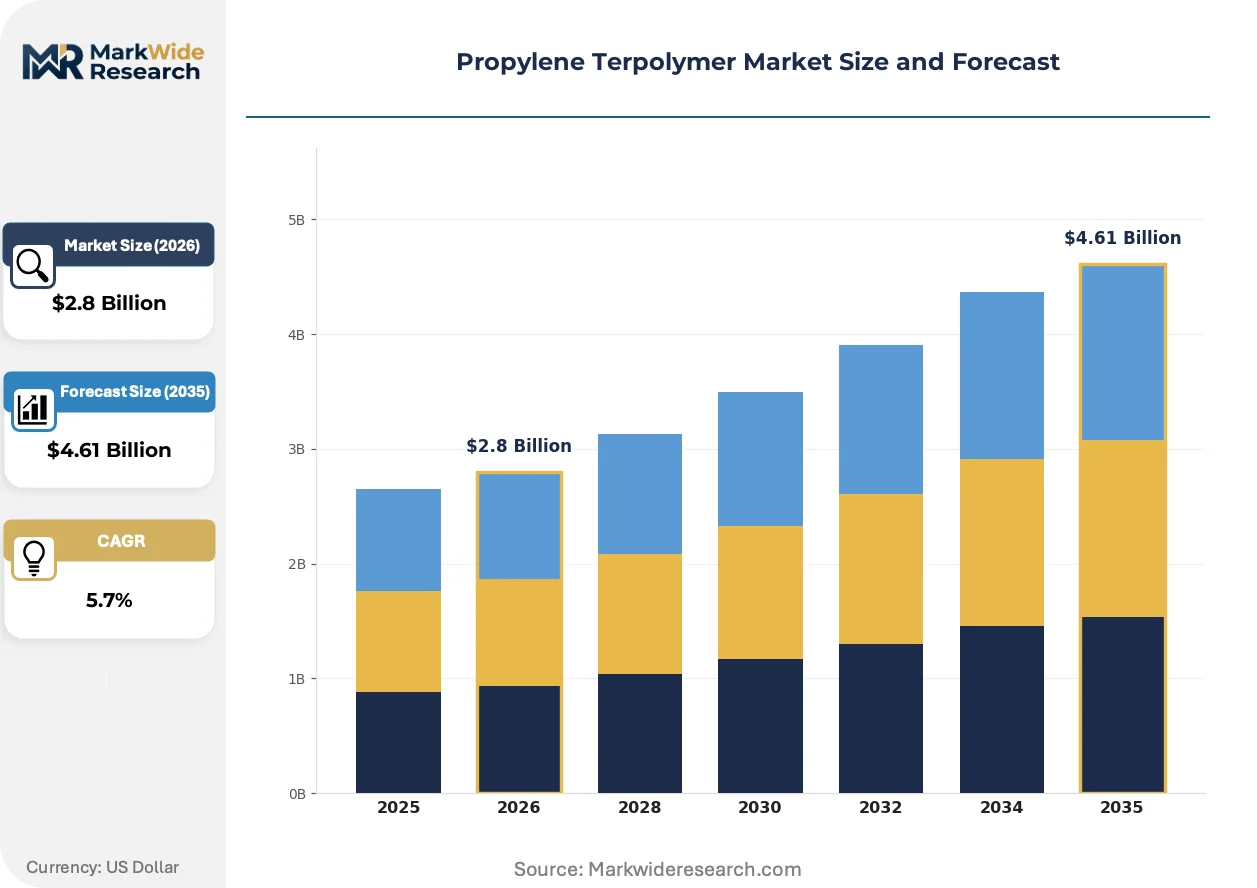
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Copolymer, Random Copolymer, Grafted Copolymer, Others Application: Automotive Interiors, Packaging Films, Medical Devices, Consumer Goods End User: OEMs, Tier-1 Suppliers, Food Industry, Electronics Form: Granules, Pellets, Sheets, Liquids |
| Companies Covered | LyondellBasell Industries, Borealis AG, SABIC, Braskem, INEOS, LG Chem, LOTTE Chemical Corporation, Mitsui Chemicals, HMC Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Terpolymer Market Evolving Landscape
Reactive extrusion capabilities and advanced grafting chemistries are compressing the performance gap between thermoplastic elastomers and vulcanized rubber, opening specification windows that incumbent materials cannot defend.
Metallocene-catalyzed propylene terpolymer is fragmenting the mid-performance elastomer segment by delivering Shore A hardness control within tighter bands than conventional Ziegler-Natta systems permit. Automotive seal manufacturers in Germany and Japan are adopting these grades for door weatherstrip applications where compression set requirements previously demanded EPDM vulcanizates. The technology is fragmenting supplier hierarchies by enabling compounders without rubber mixing assets to compete in sealing applications.
EU Green Deal chemical sustainability targets are tightening carbon intensity disclosure requirements for polymer imports into European medical device supply chains. ECHA is developing methodology for cradle-to-gate lifecycle assessment of olefin polymer production, with draft technical guidance expected to mandate supplier certification. Medical-grade propylene terpolymer formulations from Middle Eastern feedstock-integrated producers are most exposed, as European OEMs pivot procurement toward verified lower-carbon sources.
Specification consolidation among automotive Tier 1 suppliers is compressing approved vendor lists for interior elastomer components. Buyers at Magna, Faurecia, and Yanfeng are reducing qualified compounders from twelve to four per region, demanding dual-source security with identical material data sheets. This concentration is most visible in China's Yangtze River Delta, where local compounders without IATF 16949 certification are losing platform access despite cost advantages.
Propylene Terpolymer Market Segmentation
Propylene terpolymer specifications fragment across performance tiers that trade off optical clarity, impact resistance, and polar adhesion. Material selection hinges on whether converters prioritize heat-seal temperatures, low-temperature ductility, or multi-layer compatibility.
Product Type:
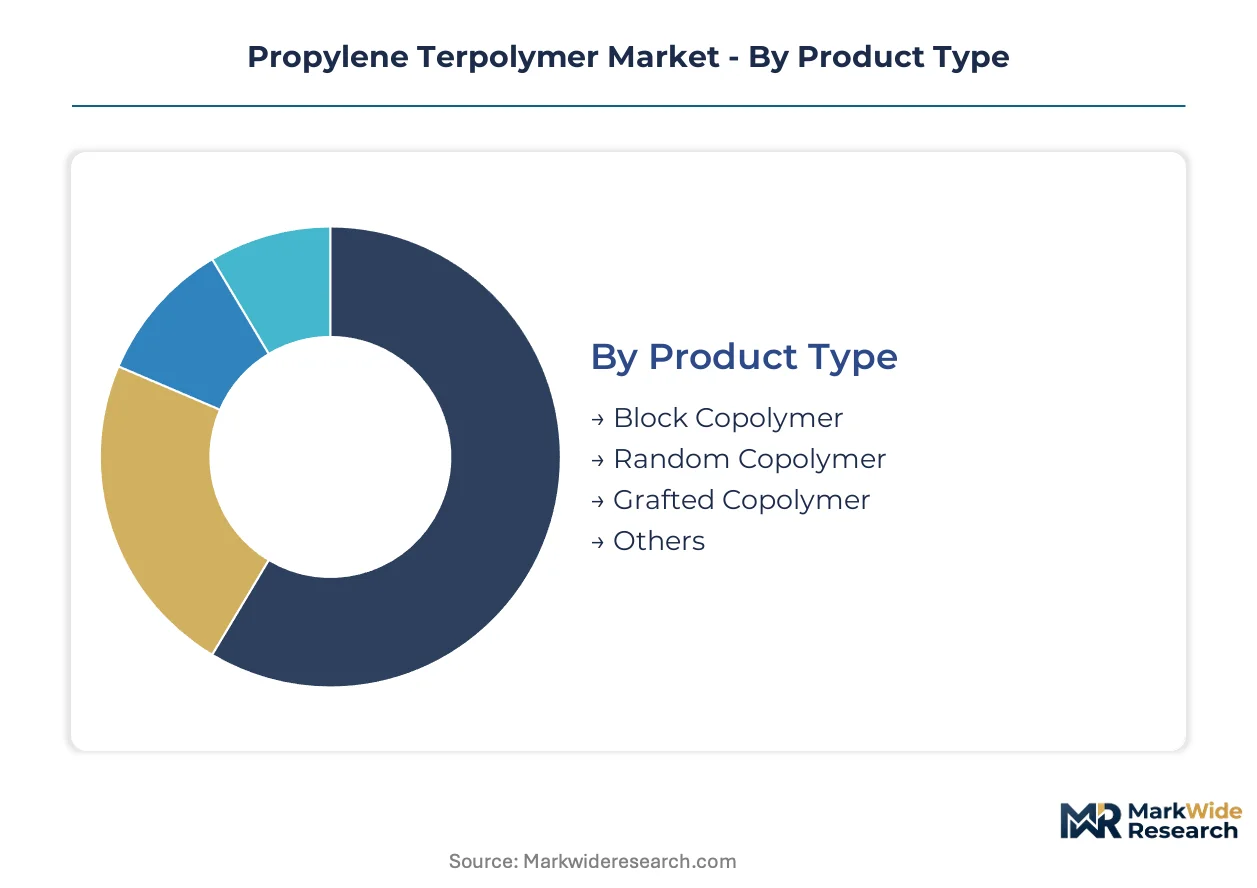
Random copolymer formulations dominate export-oriented film production, while block and grafted grades concentrate in domestic automotive and medical supply chains.
- Block Copolymer:Sequential polymerization yields distinct hard and soft segments, delivering flexural modulus above 800 MPa with retained ductility at minus 30 degrees Celsius. German and Japanese automotive seal manufacturers specify these grades for door weatherstrips and instrument panel skins where compression set resistance rivals EPDM vulcanizates.
- Random Copolymer:Statistical monomer distribution produces amorphous structures with haze below 5% and seal initiation temperatures between 105-115 degrees Celsius. Demand clusters in China's Zhejiang province for cast film exports to European food-packaging converters.
- Grafted Copolymer:Maleic anhydride functionalization enables adhesive tie layers in retort pouches.
- Others:Specialty ionomer and silane-crosslinked variants serve wire-cable jacketing.
Random copolymer commands the established base. The steepest expansion runs through grafted copolymer.
Application:
Automotive and medical segments absorb premium-priced grades, while packaging applications drive volume throughput with tighter margin structures.
- Automotive Interiors:Door seals, instrument panel skins, and pillar trim leverage low-density formulations to cut vehicle mass. NHTSA fuel economy standards and EU CO2 fleet targets are accelerating conversions from ABS and PVC across US and German OEM platforms.
- Packaging Films:Biaxially oriented structures demand optical clarity and broad heat-seal windows for high-speed form-fill-seal lines.
- Medical Devices:Catheter shafts and IV bag ports require FDA 21 CFR 177.1520 compliance with 24-36 month validation cycles.
- Consumer Goods:Appliance gaskets and tool grips utilize Shore A 70-85 grades.
Packaging films command the established base. The steepest expansion runs through medical devices.
End User:
OEM direct procurement concentrates specification control, while Tier-1 suppliers and food processors prioritize inventory velocity and lot-to-lot consistency.
- OEMs:Volkswagen, Toyota, and BYD maintain approved material lists with identical data sheet requirements across dual-source compounders.
- Tier-1 Suppliers:Magna, Faurecia, and Yanfeng are consolidating qualified vendors from twelve to four per region.
- Food Industry:Converters in Germany and China navigate divergent migration test protocols under EU 10/2011 and China's GB standards.
- Electronics:Cable jacketing and connector seals demand flame-retardant formulations.
Tier-1 suppliers command the established base. The steepest expansion runs through OEMs.
Form:
Pellet and granule formats align with bulk thermoplastic processing, while sheet and liquid variants serve niche fabrication routes.
- Granules:Irregular particle morphology suits dry-blend compounding with colorants and stabilizers.
- Pellets:Uniform cylindrical geometry enables precise dosing in injection molding and extrusion. Automotive Tier-1 suppliers in China's Yangtze River Delta specify pellet form for IATF 16949-certified production lines.
- Sheets:Calendered or extruded flat stock feeds thermoforming operations for medical tray applications.
- Liquids:Low-viscosity reactive grades enable rotomolding and slush molding of automotive interior skins.
Pellets command the established base. The steepest expansion runs through liquids.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration protocols govern European medical-grade formulations, while SAMR's GB standards fragment qualification timelines for multinational suppliers. China's eastern manufacturing corridor concentrates compounding capacity. Automotive OEMs in Germany and the United States enforce identical material data sheets across dual-source compounders.
United States
NHTSA fuel economy standards accelerate instrument panel conversions from ABS and PVC to propylene terpolymer substrates. FDA 21 CFR 177.1520 establishes olefin polymer migration thresholds for food-contact films. The Houston technology corridor anchors North American random copolymer leadership through integrated resin compounders.
Germany
Automotive seal manufacturers specify metallocene-catalyzed grades for door weatherstrips where compression set requirements previously demanded EPDM vulcanizates. EU Green Deal chemical sustainability targets tighten carbon intensity disclosure requirements for polymer imports. The Rhine-Ruhr industrial belt hosts compounders serving Volkswagen and Tier-1 suppliers with IATF 16949-certified production lines.
China
Zhejiang and Jiangsu provinces concentrate polymer compounding capacity, shortening delivery lead times for automotive Tier-1 suppliers. SAMR administers GB standards for plastic materials in food packaging that create divergent testing protocols from EU frameworks. The Yangtze River Delta exhibits specification consolidation as buyers reduce qualified compounders from twelve to four per region.
Japan
METI's industrial standards govern material specifications for automotive interior applications requiring low-temperature ductility. Domestic OEMs maintain approved material lists with identical data sheet requirements across dual-source compounders. The Nagoya industrial corridor hosts compounders serving Toyota and instrument panel skin manufacturers.
India
The production-linked incentive scheme for medical device manufacturing attracts compounding joint ventures to serve catheter and IV bag demand. CDSCO regulates material compliance for imported device-grade formulations. Maharashtra and Gujarat are emerging as compounding hubs for domestic automotive Tier-1 suppliers.
Propylene Terpolymer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with feedstock-integrated producers competing on cost positions and technology licensors commanding catalyst supply bottlenecks. Market structure reflects concentration among metallocene single-site catalyst technology holders and regional compounders serving automotive and medical qualification requirements. Strategic archetypes include feedstock-integrated petrochemical majors, technology-licensed regional compounders, and medical-grade specialists with validated FDA submission pathways. Dominant competitive moves encompass backward integration into propylene monomer supply and geographic expansion through joint ventures in high-growth Asian corridors.
Within the integrated petrochemical tier, LyondellBasell Industries and Borealis AG exemplify divergent geographic anchoring strategies. LyondellBasell represents North American technology campus-based leadership, while Borealis occupies a position linking European medical-grade supply to Middle Eastern feedstock integration through its Borouge joint venture structure. SABIC sits within the cost-driven export tier, leveraging Saudi Arabian feedstock positions across Middle Eastern pellet exports. These three entities collectively illustrate how feedstock access, technology licensing, and regulatory qualification capabilities segment competitive positioning in specialty polyolefin elastomers.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Borealis AG |
| SABIC |
| Braskem |
| INEOS |
| LG Chem |
| LOTTE Chemical Corporation |
| Mitsui Chemicals |
| HMC Polymers |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR 177.1520 migration thresholds and ECHA REACH registration protocols gate both supplier qualification timelines and price differentiation across medical-grade and food-contact tiers, compressing margins for compounders without validated submission pathways while enabling premium capture by feedstock-integrated majors.
Pricing Analysis
Northeast Asian naphtha-cracker spreads against European contract pricing create persistent arbitrage windows for propylene terpolymer pellets. Pricing stratifies across FDA-validated medical grades, IATF 16949-certified automotive formulations, and commodity packaging grades. Cost compression in random copolymer film tiers intensifies because Chinese compounding capacity expansion outpaces differentiated grade supply. Tier-1 automotive suppliers exhibit lowest price sensitivity due to platform lock-in requirements, while food-packaging converters in Zhejiang province prioritize inventory velocity over specification premiums.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes amplify inbound logistics costs for Middle Eastern pellet exports to German compounders. Manufacturing concentrates in China, Saudi Arabia, and Belgium, with feedstock-integrated positions in the Middle East feeding European medical-device demand. Metallocene single-site catalyst supply rests on three technology licensors, creating single-source vulnerability for grafted copolymer expansion. Distribution runs through qualified compounder networks serving IATF 16949-certified automotive lines and FDA-registered medical device molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propylene terpolymer incumbents face sustained substitution pressure from polyamide compounds in thermal management modules above 150 degrees Celsius, requiring defensive positioning around certification moats and feedstock integration.
For Market Incumbents: Secure captive propylene monomer supply through backward integration or long-term offtake agreements with Northeast Asian crackers. Deepen FDA 21 CFR 177.1520 submission expertise to extend validation timelines as competitive barriers against commodity compounders. Anchor automotive platform access through dual-source contracts with Volkswagen, Toyota, and BYD that specify identical material data sheets. For New Entrants and Emerging Players: CDSCO fast-track pathways for medical device manufacturing in Maharashtra and Gujarat offer lower qualification barriers than FDA cycles. Penetrate India's catheter and IV bag compounding demand through joint ventures with domestic converters leveraging production-linked incentive schemes. Target maleic anhydride grafting capabilities for retort pouch adhesive tie layers as the most penetrable technology gap. For Investors and Strategic Acquirers: EU Green Deal carbon intensity disclosure mandates reshape the acquisition landscape toward verified lower-carbon production sources. Five-to-ten year viability favors feedstock-integrated compounders with ECHA lifecycle assessment methodologies already deployed. Monitor ECHA draft technical guidance publication as the signal indicating procurement pivot timing toward certified low-carbon olefin polymer supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Monomer | Captive feedstock supply secures margin stability against naphtha-cracker volatility swings. |
| FDA 21 CFR 177.1520 Validation Investment | Twenty-four to thirty-six month submission cycles lock out commodity compounders from device-grade tiers. |
| Metallocene Catalyst Technology Licensing | Single-site catalyst access enables Shore A hardness control that fragments EPDM substitution defense. |
| Joint Venture in India's PLI Corridor | Maharashtra and Gujarat hubs capture catheter demand previously served by European imports. |
| ECHA Carbon Intensity Certification | Cradle-to-gate lifecycle assessment compliance secures European medical OEM procurement preference. |
Research Methodology
Operator-level perspectives from polymer compounding plant managers, automotive Tier-1 procurement leads, medical device regulatory affairs directors, and FDA submission consultants anchored the qualitative base. Primary interviews triangulated against customs trade data, ECHA registration filings, SEC 10-K petrochemical disclosures, and IATF 16949 certification databases. Bottom-up volume estimates from grade-specific production capacities reconciled with top-down demand modeling across automotive, packaging, and medical end-uses.
Sensitivity analysis tested forecast robustness against propylene feedstock price volatility, metallocene catalyst supply disruption scenarios, and regulatory timeline compression. Segmentation dimensions spanned product type tiers, application performance requirements, end-user procurement archetypes, and regional production hub concentrations. CAGRs derived from fitted growth curves incorporating automotive lightweighting mandate compliance schedules and medical device domestic manufacturing incentive expansions.
Underlying assumptions cover sustained NHTSA fuel economy standard enforcement and EU CO2 fleet target adherence, with deviation risk concentrated in polyamide substitution acceleration above thermal thresholds. Forecasts reflect these boundary conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
North America Epoxy Resins Market