
 Plastic Compounding Market | 2026-2036
Plastic Compounding Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Compounding Market Analysis
Market Context with Strategic Players
The capability gap between integrated resin producers and standalone compounders is collapsing as feedstock volatility erodes margin buffers for non-integrated operators. SABIC leverages its upstream petrochemical base to secure captive polymer supply for specialty compound lines across Europe and Asia. Avient Corporation anchors its position through color and additive masterbatch technology that commands premium positioning in medical and consumer electronics channels. Dow Inc. competes by extending its Engage polyolefin elastomer platform into automotive interior compounds where haptics and low-VOC performance define specification wins.
Technical Definition and Structural Segments
Plastic compounding is the melt-blending of base polymers with additives, fillers, reinforcements, and colorants to engineer materials with defined mechanical, thermal, or aesthetic properties, typically processed via twin-screw extrusion at temperatures between 180°C and 320°C depending on polymer chemistry. The output serves as feedstock for injection molding and blow molding operations that produce durable goods, packaging, and structural components across industrial sectors. Polypropylene compounds dominate volume flows due to their cost-performance balance in automotive under-hood and interior applications, while polyethylene formulations sustain growth in flexible packaging where post-consumer recycled content requirements are tightening. The 3D printing application segment represents the fastest-expanding demand pool as filament producers seek compounded grades with improved layer adhesion and warpage control for industrial additive manufacturing systems.
Regulatory Frame and Forward-Looking Close
The EPA's evolving rules on per- and polyfluoroalkyl substances are forcing reformulation of lubricated compounds across electronics and automotive segments, while REACH restrictions on phthalate plasticizers continue to redirect European demand toward bio-based and non-phthalate alternatives. China's GB standards on recycled plastic content in packaging, enforced through SAMR compliance audits, are reshaping import specifications and domestic sourcing patterns for compounders serving multinational brand owners. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment formulation strategies and create arbitrage opportunities for regionally adaptive compounders with agile technical service capabilities.
Market Dynamics
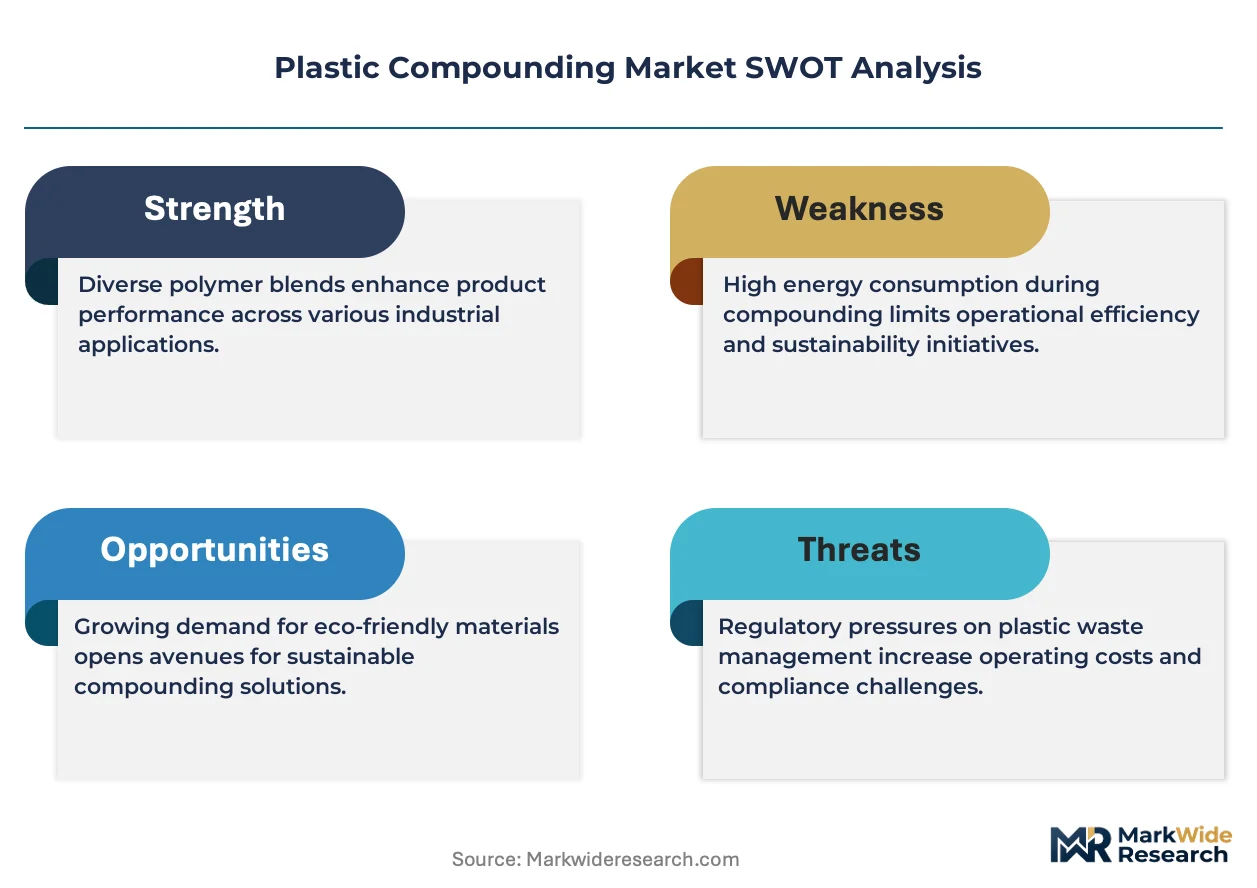
Automotive OEM lightweighting mandates are compressing formulation cycles as compounders race to certify glass-fiber-reinforced grades for EV battery housings and structural components before platform lock-in deadlines.
Growth Catalysts
- EPA recycled-content thresholds:Evolving standards on post-consumer resin incorporation are forcing packaging converters to source certified compounded grades, creating specification pull for compounders with verified mass-balance systems.
- EV battery housing programs:Chinese domestic automakers are scaling orders for flame-retardant polypropylene compounds to meet thermal runaway containment requirements in passenger cell architectures.
- Twin-screw extrusion scale-up:Chinese compounders are adding continuous production lines to serve charging infrastructure enclosures, tightening regional supply availability for multinational OEMs.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker margins in Asia and Middle Eastern supply disruptions transmit directly into polypropylene compound pricing, eroding margin predictability for non-integrated operators.
- REACH phthalate restrictions:ECHA's ongoing evaluations of plasticizer alternatives are extending reformulation timelines for European automotive and cable compounders, delaying new grade certifications.
- Mechanical recycling quality variance:Inconsistent melt-flow indices in post-consumer feedstock streams limit substitution rates in high-performance automotive and medical applications.
Strategic Opportunities
- India packaging compliance:BIS standards on recycled plastic content in rigid containers are creating first-mover advantage for compounders establishing local toll-compounding partnerships ahead of enforcement expansion.
- 3D printing filament industrialization:Material extrusion systems for tooling and jigs are driving demand for compounded grades with controlled crystallization kinetics and minimal warpage.
- EU Green Deal carbon-border adjustments:Embedded emissions accounting in imported plastics is incentivizing regional production of bio-based and mechanically recycled compounds to avoid tariff exposure.
Industry Challenges
- Color-matching technician scarcity:Masterbatch formulation expertise in metallic and effect pigments is concentrating among aging specialist workforces in European and Japanese compounders.
- Multi-jurisdictional certification lag:Simultaneous UL, VDE, and GB standard testing for electrical housing compounds extends time-to-revenue by 8-14 months for new grade introductions.
- Legacy ERP integration:Batch-level traceability requirements for recycled content claims are forcing mid-tier compounders to replace material ledger systems without disrupting just-in-time automotive supply commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Compounding Market |
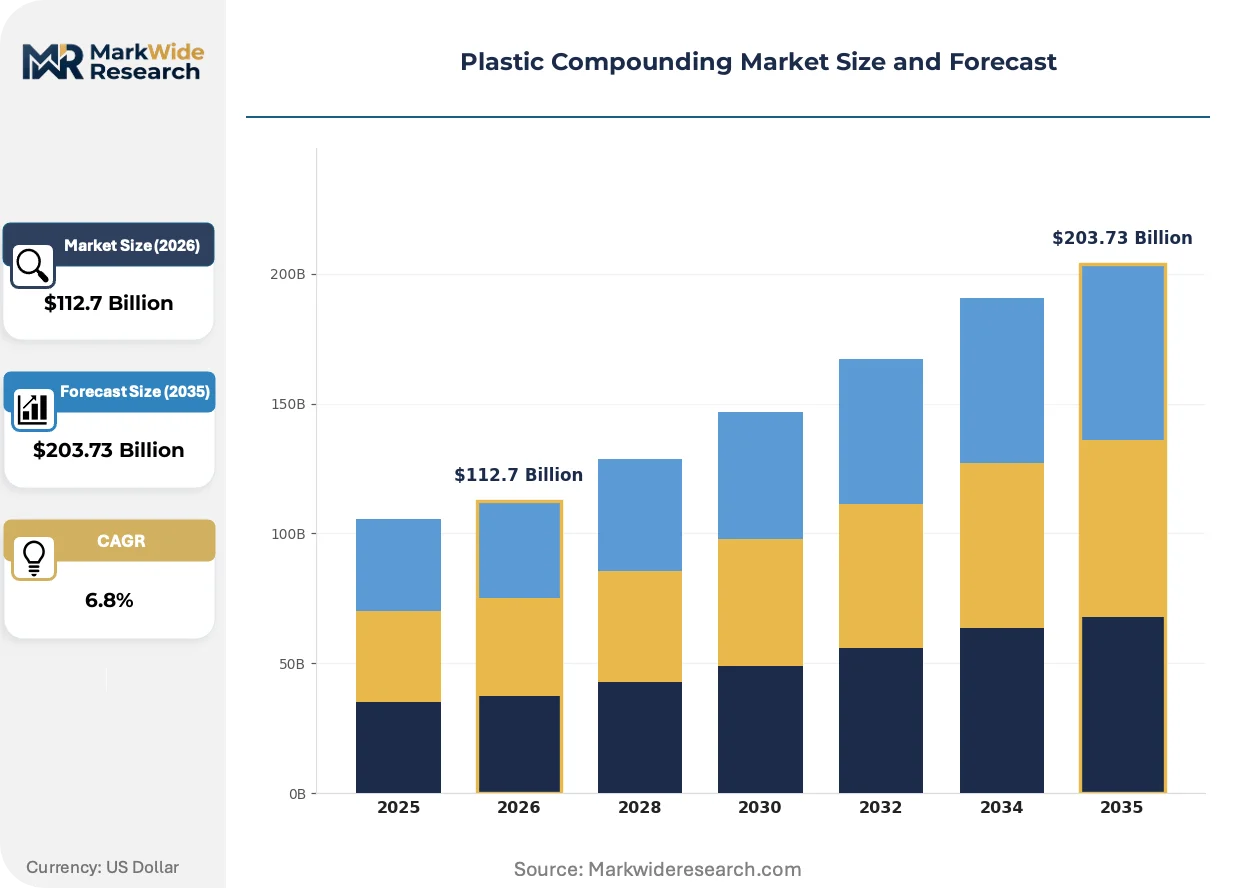
| Market Size in 2026 | $112.7 Billion |
| Market Size in 2035 | $203.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polyvinyl Chloride, Polystyrene End User: Automotive, Consumer Goods, Electronics, Construction Application: Packaging, Injection Molding, Blow Molding, 3D Printing Technology: Single Screw Extrusion, Twin Screw Extrusion, Batch Processing, Compounding Systems |
| Companies Covered | SABIC, Avient Corporation, LyondellBasell Industries Holdings B.V., Celanese Corporation, RTP Company, Dow Inc., Asahi Kasei Corporation, Solvay SA, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Compounding Market Emerging Trajectories
Reactive extrusion capabilities and real-time rheology monitoring are compressing development cycles while regulatory pressure on fluorinated additives is forcing fundamental reformulation of lubricated compounds across electronics and automotive channels.
Long-fiber thermoplastic (LFT) direct compounding is displacing short-fiber pellet feedstocks in automotive front-end modules and seat structures. Tier-1 suppliers in Germany and the US Midwest are qualifying these grades for metal replacement at 40-50% fiber loadings. The technology is displacing stamped steel and aluminum castings in crash-critical applications where energy absorption and weight reduction must coexist.
ECHA's restriction roadmap on per- and polyfluoroalkyl substances is eliminating PTFE and fluoropolymer lubricants from polyamide and POM compounds used in connector and gear applications. Compounders are pivoting to ionomeric and ceramic filler alternatives, though coefficient-of-friction performance gaps persist in high-cycle motion systems. European automotive and industrial automation OEMs are accelerating qualification timelines for PFAS-free grades ahead of 2025 enforcement windows.
Direct compounder-to-OEM specification relationships are compressing the traditional distributor-masterbatch-compounder value chain. Automotive and appliance manufacturers in China and Germany are issuing material datasheets that bypass regional compounder brands, instead certifying production lines at toll compounding facilities. This disintermediation is most pronounced in color-critical consumer electronics housings where haptics and visual consistency override supplier loyalty.
Plastic Compounding Market Segmentation
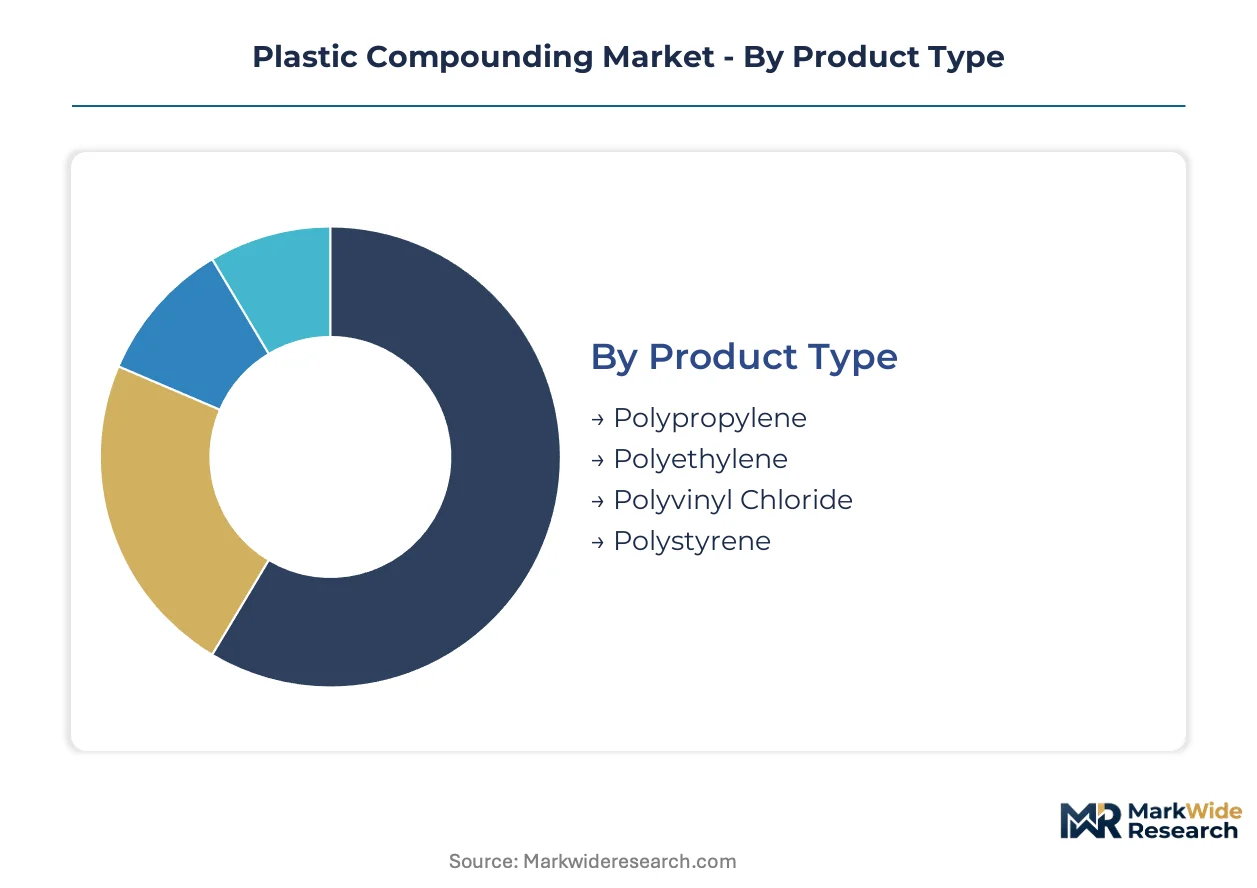
Segmentation in plastic compounding reveals how formulation requirements diverge across polymer chemistries, end-use specifications, and processing technologies. These distinctions determine capital allocation for extrusion assets and dictate where compounders must build technical service proximity to OEM development centers.
Product Type:
Domestic consumption patterns vary sharply by polymer family, with polypropylene and polyethylene serving largely regional automotive and packaging clusters while specialty grades ship across borders to certified converters.
- Polypropylene:Glass-fiber-reinforced grades dominate automotive under-hood and battery housing applications, with Chinese domestic automakers scaling orders for flame-retardant formulations to meet thermal runaway containment standards in passenger cell architectures.
- Polyethylene:Linear low-density formulations sustain flexible packaging demand where EPA recycled-content thresholds are forcing converters to source certified compounded grades with verified mass-balance systems.
- Polyvinyl Chloride:Rigid and plasticized compounds serve construction piping and medical tubing segments facing REACH phthalate restrictions.
- Polystyrene:High-impact grades concentrate in consumer electronics housings and appliance interiors where color-matching precision commands premium positioning.
Polypropylene commands the established base. The steepest expansion runs through polyethylene as recycled-content compliance tightens across North American and European packaging markets.
End User:
Customer concentration determines margin structure, with automotive and electronics buyers demanding dedicated technical service while construction and consumer goods segments tolerate more standardized grade portfolios.
- Automotive:OEM lightweighting mandates compress formulation cycles as compounders certify glass-fiber-reinforced grades for EV battery housings and structural components before platform lock-in deadlines.
- Electronics:Connector and gear applications are eliminating PTFE lubricants under ECHA's PFAS restriction roadmap, forcing pivot to ionomeric and ceramic filler alternatives.
- Consumer Goods:Appliance manufacturers in Germany and China are issuing material datasheets that bypass regional compounder brands, certifying production lines at toll compounding facilities directly.
- Construction:Pipe and profile extruders source rigid PVC and polyethylene compounds where regional building codes dictate flame-retardant and UV-stability specifications.
Automotive anchors volume concentration. Electronics is climbing the fastest as PFAS-free reformulation accelerates qualification timelines ahead of enforcement windows.
Application:
Processing method dictates rheological requirements, with injection molding demanding tight melt-flow tolerances while blow molding and 3D printing segments reward crystallization control innovations.
- Injection Molding:Thin-wall packaging and automotive structural components require compounded grades with precise melt-flow indices and minimal batch-to-batch variance.
- 3D Printing:Material extrusion systems for tooling and jigs drive demand for grades with controlled crystallization kinetics and minimal warpage.
- Packaging:Post-consumer recycled content requirements are tightening specifications for film and rigid container converters.
- Blow Molding:Fuel tanks and industrial containers utilize high-density polyethylene compounds where parison stability and environmental stress-crack resistance define grade selection.
Injection molding retains the largest installed base. 3D printing is gaining share fastest as filament producers industrialize compounded grades for additive manufacturing tooling.
Technology:
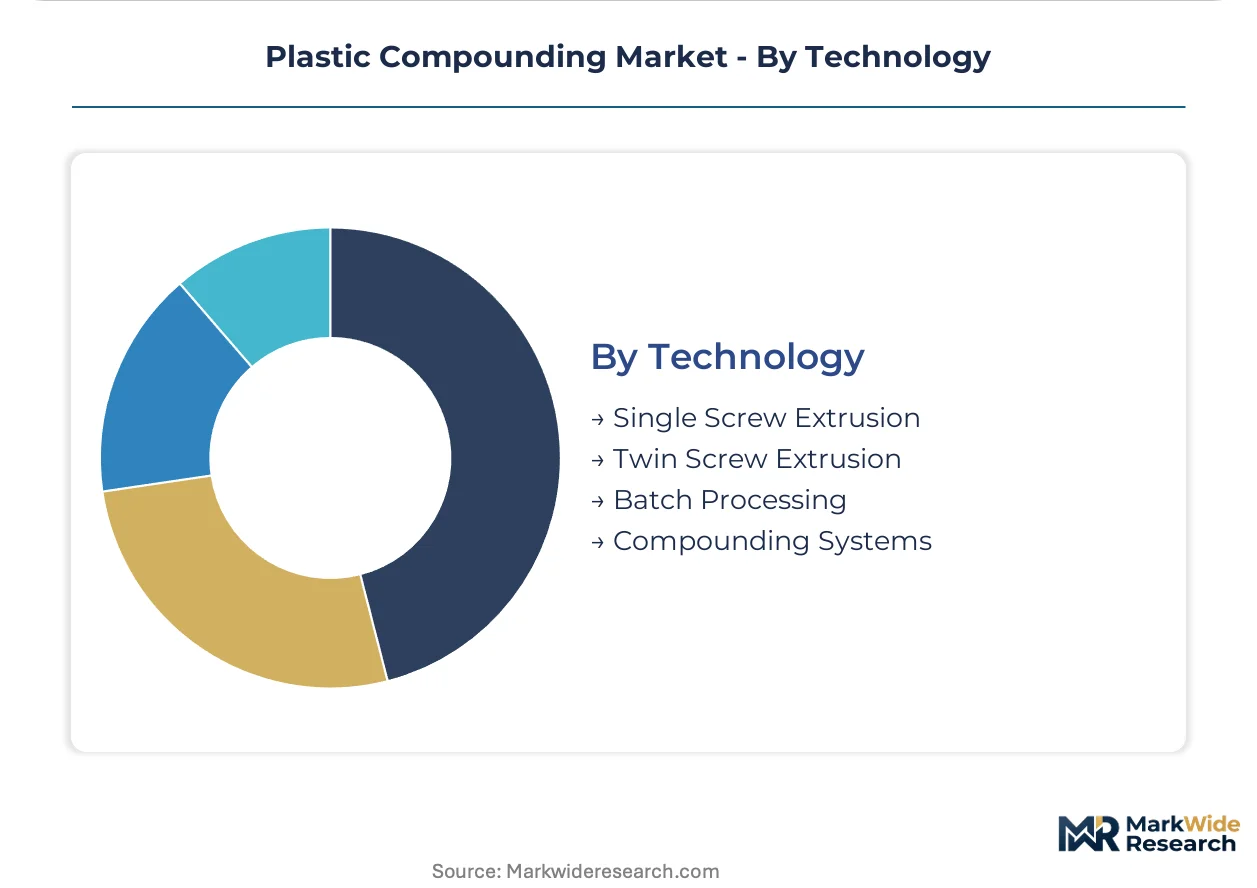
Equipment scale separates commodity producers from specialty compounders, with continuous twin-screw lines serving high-volume automotive programs while batch systems retain flexibility for medical and color-critical applications.
- Twin Screw Extrusion:Chinese compounders are adding continuous production lines to serve charging infrastructure enclosures, tightening regional supply availability for multinational OEMs.
- Single Screw Extrusion:Lower-shear processing suits heat-sensitive formulations and custom color-matching runs where batch sizes do not justify twin-screw capital investment.
- Compounding Systems:Integrated upstream-downstream configurations enable real-time rheology monitoring that compresses development cycles for reactive extrusion applications.
- Batch Processing:Medical and aerospace compounders retain discrete mixing capability for validated production lots requiring full batch traceability.
Twin screw extrusion commands capacity leadership. Compounding systems are expanding most quickly as reactive extrusion capabilities displace conventional melt-blending for advanced automotive grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb price volatility with minimal demand elasticity as EV battery housing programs scale, while European packaging converters exhibit acute sensitivity to polypropylene compound fluctuations under REACH compliance cost burdens.
China
Domestic automakers BYD and NIO are scaling flame-retardant polypropylene orders for thermal runaway containment in passenger cell architectures. SAMR enforces GB standards on recycled plastic content through compliance audits that reshape import specifications. Jiangsu and Zhejiang provinces host twin-screw extrusion scale-ups serving charging infrastructure enclosure programs for CATL and BYD supply chains.
United States
EPA recycled-content thresholds are forcing packaging converters at PepsiCo and Unilever to source certified compounded grades with verified mass-balance systems. The Agency's evolving PFAS rules are eliminating PTFE lubricants from polyamide compounds in automotive connector applications. Michigan and Ohio automotive clusters are qualifying glass-fiber-reinforced grades for Ford and GM EV platform lock-in deadlines.
Germany
ECHA's phthalate restriction evaluations are extending reformulation timelines for automotive and cable compounders serving Volkswagen and BMW. The EU Green Deal's carbon-border adjustment mechanism is incentivizing regional production of bio-based compounds to avoid tariff exposure on imported plastics. Bavaria and Baden-Württemberg host toll-compounding facilities where Tier-1 suppliers are bypassing regional compounder brands for direct OEM specification relationships.
India
BIS standards on recycled plastic content in rigid containers are creating first-mover advantage for compounders establishing local toll-compounding partnerships ahead of enforcement expansion. The PLI scheme for advanced chemistry cell batteries is pulling flame-retardant polypropylene demand toward Gujarat and Maharashtra manufacturing zones. Reliance Industries and domestic packaging converters are sourcing compounded grades for FMCG brand owners facing compliance deadlines.
Japan
METI's dual carbon goals are redirecting automotive compounders toward bio-based alternatives for interior applications at Toyota and Honda. JIS standards on material traceability are forcing batch-level ERP upgrades among mid-tier compounders serving electronics OEMs. Kansai and Chubu industrial corridors retain masterbatch formulation expertise in metallic and effect pigments that is concentrating among aging specialist workforces.
Plastic Compounding Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical majors leveraging upstream polymer supply against standalone compounders competing on formulation agility and color-matching precision. The market structure tilts toward consolidation at the commodity end and fragmentation among specialty medical and electronics grade producers. Three archetypes dominate: integrated resin producers with captive feedstock, standalone compounders with technical service proximity, and toll operators serving direct OEM specifications. Capacity expansion and portfolio diversification toward recycled-content grades constitute the dominant competitive moves as regulatory thresholds tighten across jurisdictions.
Within the integrated petrochemical tier, SABIC and LyondellBasell Industries Holdings B.V. exemplify players leveraging upstream control over polymer supply chains. Among specialty compounders with technical service depth, Avient Corporation occupies a position defined by color and additive masterbatch capabilities. These three companies represent the structural fault lines where feedstock security, formulation expertise, and OEM specification relationships determine competitive outcomes.
| Leading Market Players |
|---|
| SABIC |
| Avient Corporation |
| LyondellBasell Industries Holdings B.V. |
| Celanese Corporation |
| RTP Company |
| Dow Inc. |
| Asahi Kasei Corporation |
| Solvay SA |
| DuPont de Nemours Inc. |
| Others |
Supply Flow & Price Mechanics
Post-consumer recycled resin substitution for virgin polypropylene is redrawing supply geography toward Chinese compounders with verified mass-balance systems while compressing pricing premiums for European producers facing REACH compliance cost burdens.
Pricing Analysis
After-sales technical service contracts and formulation support agreements generate lifetime value that exceeds base resin sales for specialty compounders serving automotive OEMs. Three-tier pricing structure across certified recycled, prime virgin, and economy regrind grades separates compounders with mass-balance verification from commodity operators. Cost compression in standard polypropylene compounds is intensifying because Chinese domestic producers are scaling twin-screw capacity for EV battery housing programs. Packaging converters exhibit acute price sensitivity under EPA recycled-content mandates, while medical device OEMs tolerate premium positioning for validated batch traceability.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and Red Sea routing disruptions are elevating inbound logistics costs for European compounders sourcing flame-retardant additive packages from Chinese specialty chemical producers. Feedstock supply concentrates in Saudi Arabia, South Korea, and the US Gulf Coast where integrated petrochemical majors control propylene monomer output. Raw material flows draw from naphtha crackers, propane dehydrogenation units, and pyrolysis oil streams with inconsistent quality specifications. Single-source vulnerability in glass fiber roving supply from Chinese producers creates formulation bottlenecks for automotive structural grades. Distribution runs through toll-compounding facilities positioned near OEM assembly plants in Michigan, Bavaria, and Jiangsu provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against bio-based polymer substitution threats as automotive OEMs accelerate interior material decarbonization targets across European and Japanese platforms.
For Market Incumbents: Fortify feedstock security through captive polymer supply arrangements or long-term offtake agreements with Middle Eastern producers. Invest in reactive extrusion capabilities at existing European facilities to compress development cycles for PFAS-free formulations ahead of ECHA enforcement windows. Prioritize certification maintenance for UL and VDE electrical housing grades to preserve specification lock-in at Tier 1 automotive suppliers. For New Entrants and Emerging Players: Differentiate on recycled-content verification systems that command specification pull from multinational packaging brand owners facing compliance deadlines. Target India's rigid container segment where BIS standards enforcement is expanding and local toll-compounding partnerships remain underdeveloped. Pursue direct OEM specification relationships that bypass established distributor-masterbatch-compounder value chains in Chinese consumer electronics channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin producers with upstream petrochemical control over standalone compounders facing margin compression. Five-to-ten-year viability hinges on regulatory adaptation speed rather than scale alone. Monitor PFAS restriction implementation timelines as the critical inflection signal for reformulation capex cycles and specialty compounder valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | SABIC and LyondellBasell leverage upstream control to secure captive polymer for specialty compound lines. |
| Reactive Extrusion Capability Expansion | Real-time rheology monitoring compresses development cycles for automotive grades at German toll facilities. |
| Mass-Balance System Certification | Verified recycled content claims unlock specification wins from PepsiCo and Unilever packaging converters. |
| PFAS-Free Formulation Pivot | Ionomeric lubricant alternatives in polyamide compounds preserve connector supply relationships at automotive OEMs. |
| Direct OEM Specification Relationships | BYD and NIO material datasheets bypass regional compounder brands for toll facility production line certification. |
Methodological Framework
A spread of perspectives from plant managers at compounder facilities, procurement leads at automotive Tier 1 suppliers, technical R&D directors, and distribution channel partners converged on the working assumptions underlying volume and value estimates. Primary interview insights were validated against secondary sources including customs and trade flow data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and SAMR compliance audit disclosures. Bottom-up capacity assessments at twin-screw extrusion facilities were triangulated with top-down demand modeling across end-use segments.
Segmentation dimensions modeled include polymer chemistry family, end-use industry vertical, processing technology tier, and regional production hub configuration across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Forecast inputs incorporated EV battery housing program ramp timelines, REACH restriction implementation phases, and EPA recycled-content threshold enforcement patterns.
Material uncertainties — propylene feedstock volatility, mechanical recycling quality variance, and regulatory divergence between jurisdictions — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution rates and compliance cost pass-through. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Polyamide Precursors Market