
 Rotomolding Compound Market | 2026-2036
Rotomolding Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Rotomolding Compound Market Insights
Specialized polymer compounding expertise is redrawing the competitive map for rotomolding suppliers. Western Industries Plastic Products LLC leverages captive resin formulation capabilities to serve bulk tank OEMs across the Midwest. Centro Incorporated anchors its position through deep vertical integration into custom color and additive masterbatching. Myers Industries, Inc. competes via geographic density in agricultural and material handling segments.
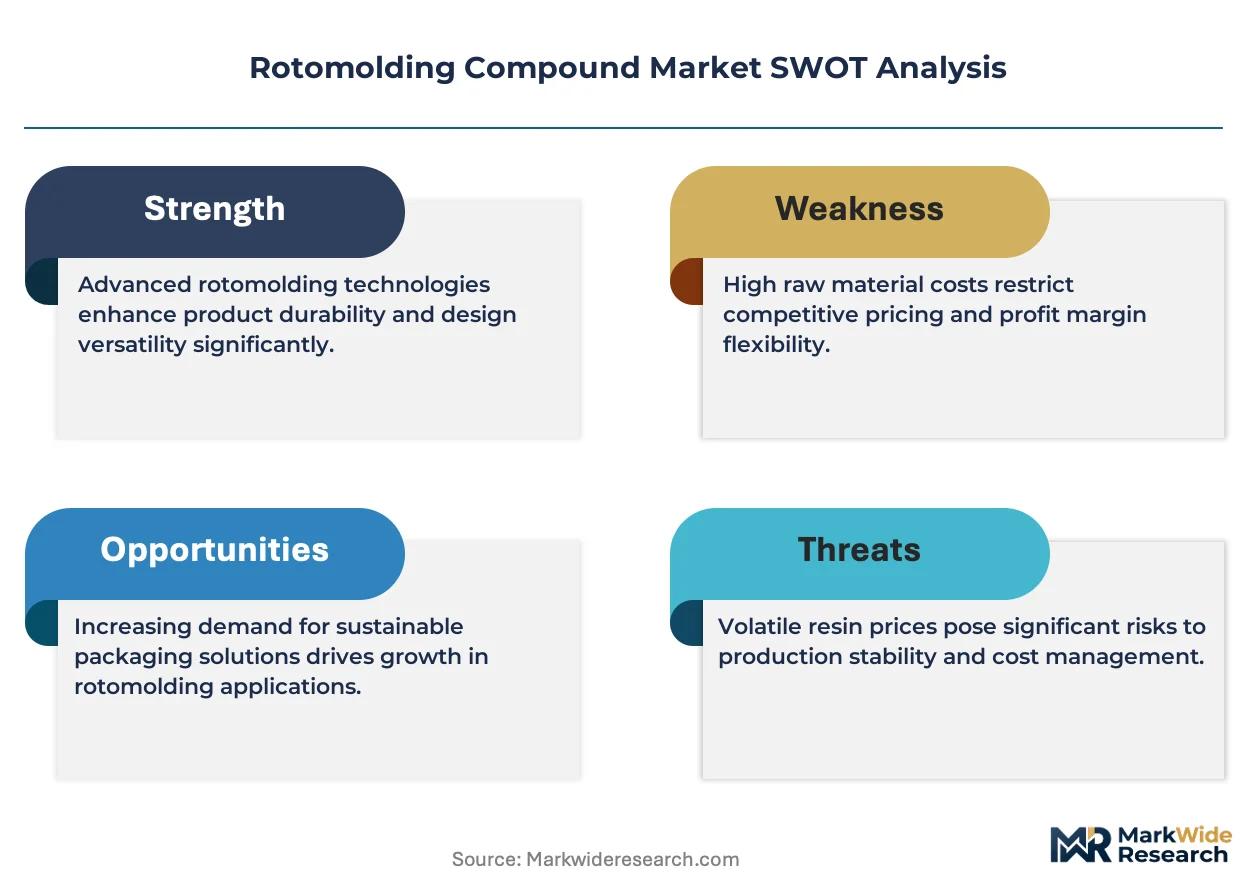
Rotomolding compounds are thermoplastic formulations—predominantly crosslinkable and linear polyethylene grades with melt indices between 2 and 8 g/10min—engineered for hollow-part fabrication through biaxial rotational casting. These materials must deliver uniform wall distribution, thermal stability across oven cycles, and impact resistance down to minus forty degrees Celsius for outdoor durability. Polyethylene dominates volume demand due to its cost position and process latitude, while thermoplastic elastomer segments capture disproportionate margin pools in playground and marine applications where soft-touch surfaces command specification premiums. Advanced rotomolding technology segments are expanding fastest as molders adopt in-mold labeling and foamed-wall techniques to differentiate tank and automotive component offerings.
FDA food-contact regulations and EPA emissions frameworks govern material approval and workplace exposure limits for rotomolding operations in the United States. REACH chemical registration requirements in Europe constrain phthalate-based additive packages and drive reformulation toward bio-based plasticizers. ISO 9001 quality management and ASTM D1998 tank standards further shape procurement criteria for storage tank fabricators. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as pending EPA designations threaten incumbent release-agent chemistries and compounding additive portfolios.
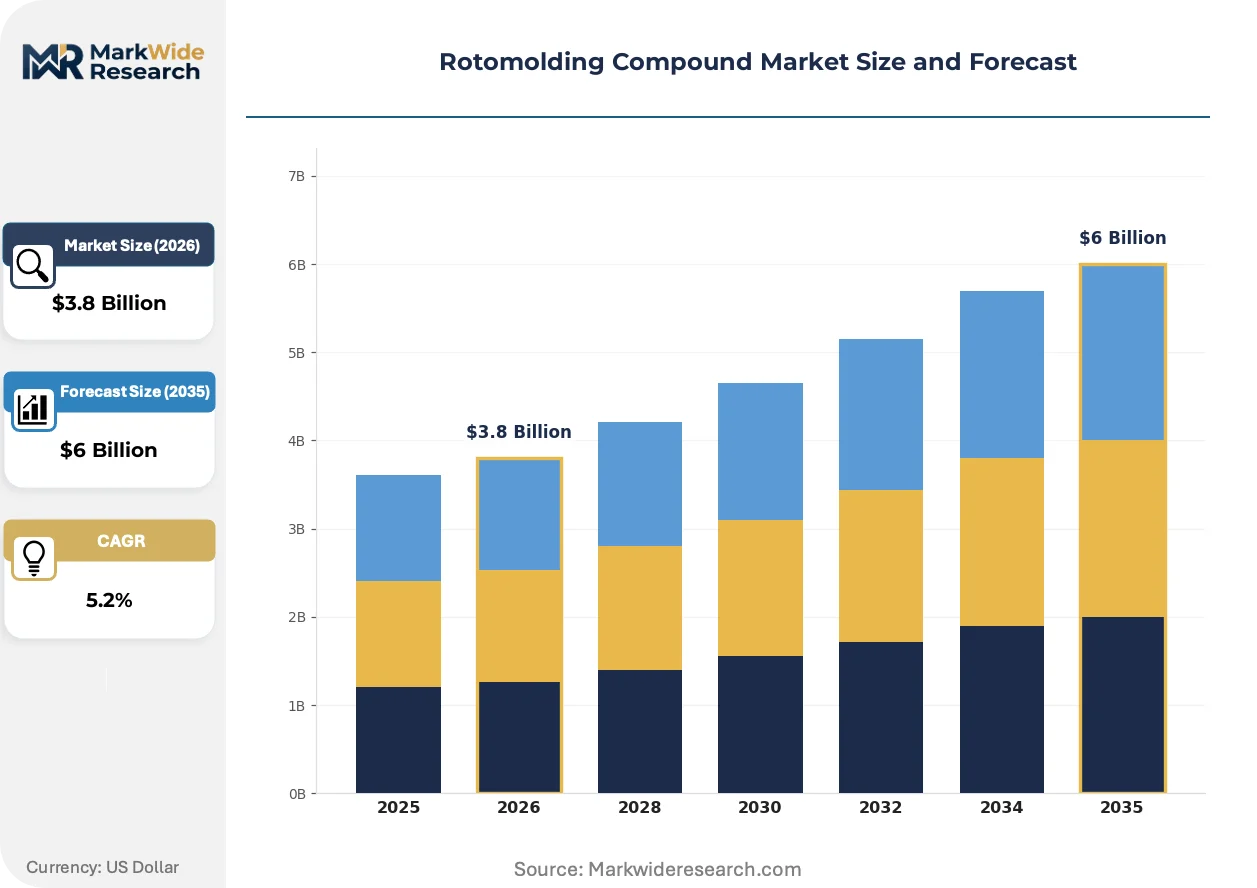
Market Dynamics
Specialty polymer compounding expertise is redrawing competitive boundaries as tank fabricators and automotive molders expand specifications for impact-resistant polyethylene grades. EPA emissions standards and FDA food-contact regulations are tightening material compliance requirements across the value chain.
Growth Catalysts
- Industrial packaging demand:Chemical and agricultural distribution networks in China's industrial heartland are scaling rotomolded container output for bulk liquid handling.
- REACH chemical registration:European reformulation toward bio-based plasticizers is opening specification windows for compliant compound suppliers.
- In-mold labeling adoption:Advanced rotomolding technology segments are expanding as molders adopt foamed-wall techniques to differentiate tank offerings.
Market Restraints
- Phthalate additive phase-out:REACH constraints on phthalate-based packages force compounders to rebuild formulation portfolios from raw material bases.
- Release-agent chemistry uncertainty:Pending EPA designations on per- and polyfluoroalkyl substances threaten incumbent additive portfolios and qualification timelines.
- Linear polyethylene supply concentration:Melt-index-grade resin availability clusters with integrated petrochemical producers, constraining formulation flexibility for independent compounders.
Strategic Opportunities
- Playground equipment surfaces:Thermoplastic elastomer segments capture disproportionate margin pools where soft-touch specifications command premium positioning.
- Marine component applications:Dock fender and buoy manufacturers specify UV-stabilized compounds with enhanced salt-water resistance for coastal infrastructure.
- ISO 9001 procurement criteria:Storage tank fabricators are embedding quality management certifications into vendor qualification, favoring compounders with documented process control.
Industry Challenges
- Rotational molding technician scarcity:Oven cycle optimization and mold-flow simulation require specialized skills that outpace vocational training pipeline output.
- ASTM D1998 certification timelines:Tank standard compliance testing extends product launch schedules, compressing window for specification capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotomolding Compound Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyamide, Polycarbonate, Thermoplastic Elastomer Application: Storage Tanks, Automotive Components, Playground Equipment, Industrial Containers, Agricultural Items End User: Manufacturers, Fabricators, Construction Firms, Equipment Suppliers, Packaging Producers Technology: Basic Rotomolding, Advanced Rotomolding, Co-rotational Molding, Low Pressure Rotomolding, Twin-Sheet Rotomolding |
| Companies Covered | Western Industries Plastic Products LLC, Elkhart Plastics LLC, Centro Incorporated, K. K. Nag Private Limited, U.S. Plastic Corp., Den Hartog Industries Inc., Myers Industries, Inc., Rototek Limited, Fibertech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotomolding Compound Market Trends and Innovations
Rotomolding compound development is fragmenting along performance-versus-cost axes as molders face divergent specification pressures from infrastructure and consumer durables end-uses. Three distinct vectors are reshaping formulation priorities and equipment investment patterns.
Foamed-wall rotomolding technology is bifurcating the tank fabrication segment. Water and chemical containment OEMs are adopting microcellular structures for thermal insulation and weight reduction at accelerated qualification paces. This structural shift is compressing demand for solid-wall grades in bulk storage applications while opening specification premiums for compounders with nucleating-agent expertise.
EPA per- and polyfluoroalkyl substance designations are forcing reformulation of mold-release chemistries. The industrial consequence extends beyond release agents to compounding additive portfolios that incorporate fluorinated processing aids. Tank fabricators serving potable water applications face the most acute compliance pressure, with procurement teams accelerating supplier audits to exclude restricted substances ahead of enforcement windows.
Specification-driven procurement is consolidating vendor relationships around compounders with captive resin formulation capabilities. Midwest tank OEMs now require batch-level traceability and custom color masterbatching as standard terms, displacing spot-market purchasing. Agricultural equipment manufacturers in the Corn Belt exhibit the most concentrated buying patterns, with multi-year supply agreements replacing quarterly tenders.
Rotomolding Compound Market Segmentation
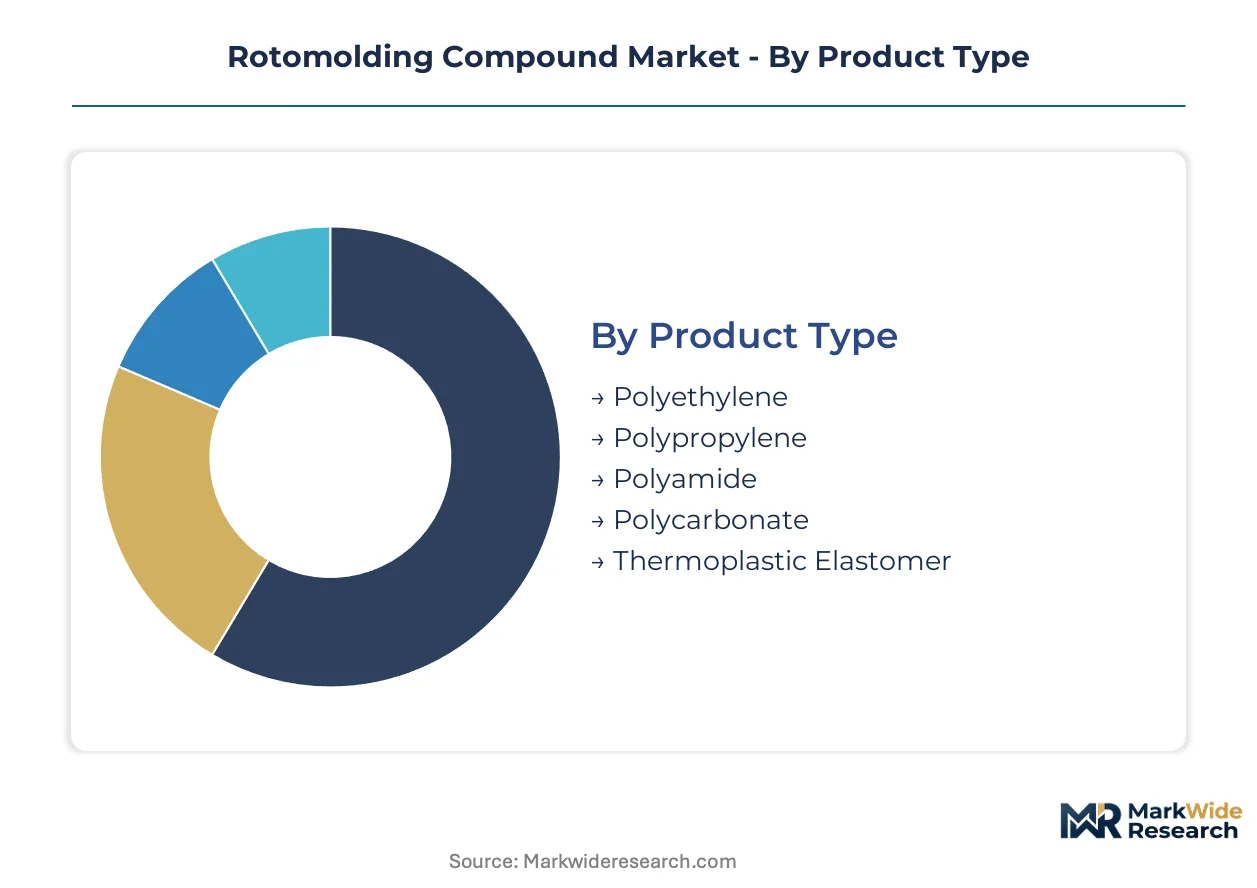
Rotomolding compound specifications diverge sharply across end-use applications, with FDA food-contact rules, EPA emissions frameworks, and ASTM tank standards each privileging different material grades. Procurement teams now weight compliance documentation equally with price and performance, compressing qualified supplier pools within each segment.
Product Type:
FDA and EPA designations reshape formulation priorities across polymer families, with REACH constraints on phthalate additives accelerating reformulation timelines for European-bound shipments.
- Polyethylene:Crosslinkable and linear grades with melt indices between 2 and 8 g/10min dominate volume demand due to cost position and process latitude. Tank fabricators across the Midwest specify these grades for bulk storage applications requiring impact resistance down to minus forty degrees Celsius.
- Thermoplastic Elastomer:Soft-touch formulations capture disproportionate margin pools in playground and marine applications where surface feel commands specification premiums. Dock fender manufacturers specify UV-stabilized grades with enhanced salt-water resistance for coastal infrastructure.
- Polypropylene:Higher thermal stability suits automotive underhood components facing sustained heat exposure.
- Polyamide:Nylon-based compounds serve chemical resistance applications in industrial container segments.
- Polycarbonate:Optical clarity grades address specialized lighting and inspection equipment housings.
Established volume favors Polyethylene; emerging adoption favors Thermoplastic Elastomer.
Application:
Customer procurement patterns stratify by certification burden, with potable water tank fabricators demanding batch-level traceability that agricultural equipment buyers rarely require.
- Storage Tanks:Water and chemical containment OEMs drive foamed-wall adoption for thermal insulation and weight reduction. ASTM D1998 compliance testing extends launch schedules, compressing windows for specification capture among compounders.
- Playground Equipment:Soft-touch surface specifications command premium positioning where safety standards mandate impact-absorbing materials. Municipal procurement teams embed ISO 9001 certifications into vendor qualification criteria.
- Automotive Components:Underhood and interior part molders specify heat-stabilized grades with consistent shrinkage control.
- Industrial Containers:Chemical distribution networks scale output for bulk liquid handling across China's industrial heartland.
- Agricultural Items:Sprayer tanks and feeder bins prioritize cost efficiency over advanced formulation features.
Specification density concentrates in Storage Tanks; margin expansion concentrates in Playground Equipment.
End User:
Supply relationships harden around compounders with captive resin formulation capabilities as multi-year agreements displace quarterly tenders.
- Manufacturers:Tier-one molders with in-house design teams specify custom color and additive masterbatching as standard procurement terms. These buyers consolidate vendor relationships around suppliers with documented process control systems.
- Fabricators:Regional tank builders spot-purchase commodity grades but accelerate supplier audits to exclude restricted substances ahead of EPA enforcement windows.
- Construction Firms:Project-based purchasing favors flexible delivery schedules over formulation customization.
- Equipment Suppliers:OEM integration demands consistent lot-to-lot performance for warranty compliance.
- Packaging Producers:High-volume container makers prioritize melt-index consistency for thin-wall molding cycles.
Long-term contracting favors Manufacturers; spot-market flexibility favors Fabricators.
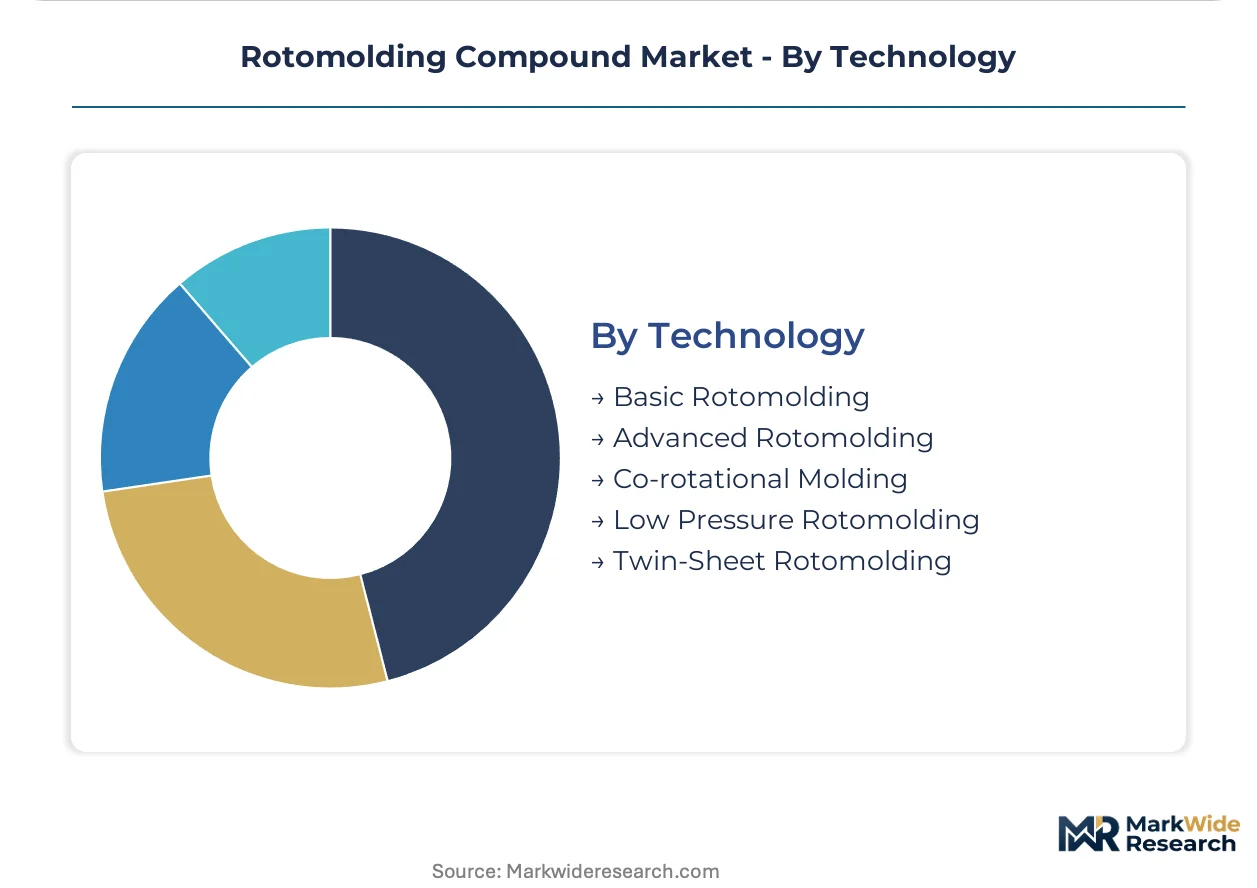
Technology:
Equipment investment patterns fragment as molders weigh foamed-wall differentiation against basic process reliability.
- Advanced Rotomolding:In-mold labeling and foamed-wall techniques differentiate tank and automotive component offerings. Nucleating-agent expertise opens specification premiums as water containment OEMs adopt microcellular structures.
- Basic Rotomolding:Solid-wall processing retains dominance in agricultural and material handling segments where cost discipline outweighs performance premiums. Corn Belt equipment manufacturers exhibit concentrated buying patterns with captive resin suppliers.
- Co-rotational Molding:Multi-layer structures enable barrier properties for chemical containment.
- Low Pressure Rotomolding:Reduced energy cycles appeal to high-volume packaging producers.
- Twin-Sheet Rotomolding:Hollow-core panels serve marine and playground structural applications.
Process maturity anchors Basic Rotomolding; technology differentiation expands fastest in Advanced Rotomolding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and FDA food-contact regulations anchor the United States as the primary demand center for compliant rotomolding compounds. Tank fabricators across the Midwest and agricultural equipment manufacturers in the Corn Belt drive specification intensity for impact-resistant polyethylene grades.
United States
Water and chemical containment OEMs in the Midwest specify foamed-wall structures for thermal insulation and weight reduction. ASTM D1998 tank standards govern procurement criteria for bulk storage fabricators. The Corn Belt agricultural equipment corridor concentrates buying patterns around compounders with captive resin formulation capabilities.
China
Chemical and agricultural distribution networks scale rotomolded container output for bulk liquid handling across the industrial heartland. MIIT industrial standards and GB quality certifications shape material approval processes for packaging producers. The Yangtze River Delta cluster hosts equipment suppliers scaling output for domestic and export markets.
Germany
REACH chemical registration requirements constrain phthalate-based additive packages and drive reformulation toward bio-based plasticizers. Automotive molders specify heat-stabilized grades for underhood components facing sustained thermal exposure. The North Rhine-Westphalia industrial basin concentrates compounders serving tank and automotive segments.
India
BIS certification requirements and FSSAI food-contact regulations govern material compliance for domestic and export-bound shipments. Agricultural sprayer tank fabricators in Gujarat and Maharashtra prioritize cost-efficient linear polyethylene grades. The Mumbai-Pune industrial corridor hosts packaging producers scaling rotomolded container output for chemical distribution.
Brazil
ANVISA pharmaceutical and food-contact regulations shape material approval timelines for compounders serving regulated end-uses. Agricultural equipment manufacturers in São Paulo state specify UV-stabilized grades for outdoor durability. The Campinas industrial cluster concentrates molders serving playground and marine component applications.
Rotomolding Compound Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive resin formulation capabilities separating premium compounders from spot-market suppliers. The structure rewards backward integration into custom color and additive masterbatching while penalizing formulation-dependent independents. Three archetypes dominate: integrated petrochemical-backed compounders, regional specialists with geographic density, and captive in-house operations at major tank OEMs. Competitive moves center on multi-year supply agreements displacing quarterly tenders and accelerated supplier audits to exclude restricted substances ahead of enforcement windows.
Among Midwest-based fabricators, Western Industries Plastic Products LLC and Centro Incorporated exemplify the integrated-compounder archetype through captive formulation capabilities. Myers Industries, Inc. occupies a position representing geographic-density specialists with concentrated presence in agricultural and material handling segments. K. K. Nag Private Limited anchors the Asia-Pacific specialist tier, while Den Hartog Industries Inc. and Rototek Limited sit within the premium fabricator-compounder segment serving regulated tank applications.
| Leading Market Players |
|---|
| Western Industries Plastic Products LLC |
| Elkhart Plastics LLC |
| Centro Incorporated |
| K. K. Nag Private Limited |
| U.S. Plastic Corp. |
| Den Hartog Industries Inc. |
| Myers Industries, Inc. |
| Rototek Limited |
| Fibertech Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day resin qualification cycles concentrate pricing power with integrated petrochemical producers holding captive polyethylene formulation capabilities. Midwest tank OEMs and Corn Belt agricultural equipment manufacturers face compressed negotiation leverage when melt-index-grade availability tightens, forcing spot-market buyers to absorb premium spreads or accept longer delivery windows.
Pricing Analysis
Geographic price spreads widen between United States Gulf Coast petrochemical hubs and inland Midwest fabrication clusters, reflecting freight differentials and regional inventory imbalances. Three-tier pricing structure across premium certified grades, standard commercial formulations, and economy bulk volumes dominates procurement contracts. Price differentiation rests on FDA food-contact certification status and ASTM D1998 compliance documentation. Pricing pressure stems from REACH-driven reformulation costs as compounders rebuild additive portfolios away from phthalate-based packages. Agricultural equipment manufacturers exhibit highest price sensitivity, while potable water tank fabricators prioritize certification over unit cost.
Supply Chain Analysis
China and the United States anchor global polyethylene resin production, with integrated petrochemical complexes along the Gulf Coast and Yangtze River Delta feeding regional compounding operations. Formulation draws from linear polyethylene feedstocks, nucleating agents for foamed-wall grades, and bio-based plasticizer alternatives replacing restricted phthalates. Single-source vulnerability concentrates in specialized additive packages where REACH compliance has thinned qualified supplier pools. Distribution runs through captive in-house operations at major tank OEMs, multi-year supply agreements with regional compounders, and spot-market procurement for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotomolding compound procurement is consolidating around platform economics as tank OEMs demand batch-level traceability and custom masterbatching as standard terms, creating interoperability requirements that favor integrated compounders over formulation-dependent independents.
For Market Incumbents: Compound defensive positioning through accelerated backward integration into additive masterbatching and nucleating-agent formulation capabilities. Secure captive resin supply agreements ahead of potential EPA per- and polyfluoroalkyl substance designations that threaten incumbent release-agent portfolios. Invest in ASTM D1998 certification infrastructure to compress qualification timelines for specification capture.
For New Entrants and Emerging Players: Lead with bio-based plasticizer expertise serving REACH-compliant European shipments and domestic reformulation demand. Target thermoplastic elastomer segments in playground and marine applications where soft-touch specifications command premium positioning and qualified supplier pools remain thin. Pursue partnership routes with regional tank fabricators seeking alternatives to integrated petrochemical suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical parents with underutilized rotomolding compound divisions lacking captive resin integration. Long-term viability hinges on compounders controlling formulation inputs rather than blending commodity resins. Monitor EPA enforcement windows for per- and polyfluoroalkyl substances as inflection indicators for portfolio restructuring among incumbent additive suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Masterbatching | Captive nucleating-agent production secures foamed-wall specification premiums from water containment OEMs. |
| Long-term Supply Agreement | Multi-year contracts displace quarterly tenders among Corn Belt agricultural equipment manufacturers. |
| Green Manufacturing Transition | Bio-based plasticizer portfolios capture REACH-compliant European reformulation windows. |
| Joint Venture | Regional compounding partnerships penetrate China's Yangtze River Delta industrial cluster. |
| Capacity Expansion | Melt-index-grade resin flexibility reduces dependence on integrated petrochemical producers. |
Research Methodology
Cross-validation between primary interviews with rotomolding plant managers, tank OEM procurement leads, and polymer R&D directors anchors the qualitative findings against secondary validation from customs trade data, ACC industry reports, and SEC filings from listed compounders. Bottom-up triangulation across resin consumption patterns and top-down market sizing from end-use demand modeling ensure dimensional consistency. The analysis draws from technical discussions with rotational molding equipment suppliers and distribution channel partners serving Midwest fabrication clusters.
Sensitivity analysis around regulatory enforcement timelines and resin price volatility shapes the analytical framework across the projection horizon. Segmentation dimensions include polymer family, end-use application, technology tier, and geographic production hub. CAGRs derive from modeled demand drivers including foamed-wall adoption rates and thermoplastic elastomer penetration in playground equipment. Industry-specific inputs capture ASTM D1998 certification timelines and EPA per- and polyfluoroalkyl substance designation scenarios.
Forecasts assume regulatory continuity in EPA emissions frameworks and FDA food-contact regimes; material policy shifts would require re-modeling compliance cost burdens and qualification timelines. Specific risks include accelerated phthalate additive phase-outs and single-source resin supply disruptions. Recalibration cycles align with material shifts in enforcement windows and adoption curves for advanced rotomolding technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
South America Engineering Plastics Market