
 Global Polymeric Adsorbents Market | 2026-2036
Global Polymeric Adsorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymeric Adsorbents Market Foresight
Modular packaging configurations for polymeric adsorbents is broadening procurement flexibility for mid-scale water treatment operators. BASF SE leverages its integrated polymer precursor network to sustain cost advantages across macroporous resin lines. Mitsubishi Chemical Corporation anchors Asian supply through dedicated manufacturing platforms in Japan and China. Purolite Corporation differentiates via specialized chelating resin portfolios tailored to pharmaceutical-grade specifications.
Polymeric adsorbents are synthetic, cross-linked organic polymers engineered with controlled pore architectures typically ranging from 100 to 800 square meters per gram surface area, functioning primarily to selectively capture target molecules from liquid or gas streams through physical adsorption or ionic interaction. Adsorptive resins command the largest current volume position due to their versatility across water and food processing applications, while ion exchange resins represent the fastest-expanding margin pool as semiconductor-grade purity requirements tighten. Macroporous resins retain mature, stable demand in bulk wastewater management where specification tolerance remains wider.
The EPA enforces discharge limits that directly mandate adsorbent performance thresholds in US industrial effluent systems, while REACH registration obligations in Europe constrain raw monomer sourcing for non-compliant resin manufacturers. China's SAMR implements GB standards that govern food-contact adsorbent safety, creating divergent certification burdens for exporters. Stakeholders must monitor regulatory convergence between FDA pharmaceutical purity guidelines and emerging EFSA food-contact specifications to anticipate compliance-driven product redesign cycles.
Market Dynamics
REACH registration obligations and EU Green Deal mandates are forcing resin manufacturers to redesign monomer feedstocks and purification protocols, compressing margins for non-compliant suppliers while advantaging integrated polymer producers with captive precursor supply.
Growth Catalysts
- Biologics manufacturing scale-up:Pharmaceutical purification demand is accelerating as monoclonal antibody and gene therapy production expands, requiring high-purity adsorbent resins for downstream processing.
- EPA discharge mandates:Industrial effluent limits in the United States are mandating adsorbent performance thresholds that upgrade treatment infrastructure across chemical and electronics manufacturing clusters.
- Semiconductor-grade purity requirements:Ion exchange resins are capturing expanded margin pools as chip fabrication nodes advance below 7 nanometers, demanding parts-per-trillion contaminant removal.
Market Restraints
- Styrene-divinylbenzene feedstock volatility:Crude oil-linked aromatic monomer costs swing resin production economics unpredictably, squeezing compounders without long-term supply contracts.
- Specialized manufacturing concentration:Germany, Japan, and China host the majority of pharmaceutical-grade resin capacity, creating geographic supply risk for buyers in other regions.
- Activated carbon substitution:Lower-cost granular activated carbon retains share in bulk wastewater applications where specification tolerance permits wider performance bands.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with FDA standards is opening contract manufacturing demand for US- and EU-certified resin specifications.
- Carbon capture solvent purification:Amine scrubbing systems for post-combustion capture require specialized adsorbent polishing, creating new demand from power and cement sector decarbonization projects.
- SAMR GB standard convergence:China's food-contact safety regulations are tightening toward EFSA equivalence, enabling qualified exporters to consolidate position in Asia-Pacific food processing.
Industry Challenges
- Resin regeneration expertise shortage:Operating continuous ion exchange systems requires specialized chemical engineering talent that remains scarce outside established chemical processing hubs.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and PMDA pharmaceutical-grade approvals extend product launch cycles by 18-36 months for new resin formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymeric Adsorbents Market |
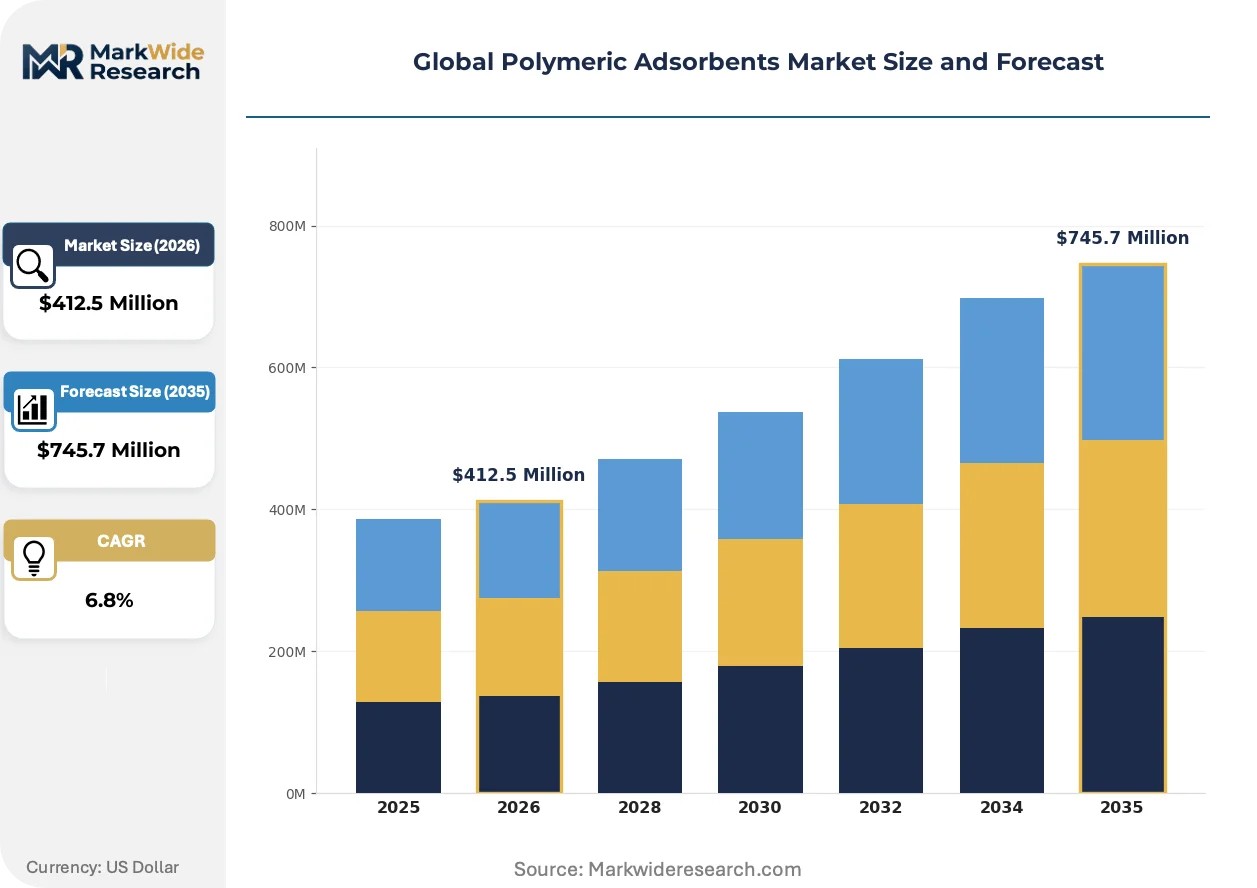
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Exchange Resins, Chelating Resins, Adsorptive Resins, Macroporous Resins, Gel Type Resins Application: Water Treatment, Pharmaceutical Purification, Food & Beverage Processing, Chemical Separation, Catalysis End User Industry: Wastewater Management, Biopharmaceutical Manufacturing, Food Processing Units, Specialty Chemicals Plants Packaging Type: Big Bags, Drums, Bulk Bags, Jumbo Bags, Carboys |
| Companies Covered | BASF SE, Mitsubishi Chemical Corporation, Purolite Corporation, DuPont de Nemours, Lanxess AG, Thermax Limited, Sunresin New Materials Co. Ltd., Chemra GmbH, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymeric Adsorbents Market Shifts & Advancements
Modular skid-mounted adsorption systems are compressing deployment timelines for mid-scale operators, while digital process monitoring and predictive regeneration algorithms reshape asset utilization economics across water and pharmaceutical processing verticals.
Continuous countercurrent ion exchange technology is decentralizing purification capacity from centralized bulk chemical plants toward distributed pharmaceutical and biotechnology manufacturing sites. Mid-scale biologics producers in Ireland and Singapore are adopting these systems to reduce solvent consumption and resin inventory requirements. The shift is compressing demand for traditional batch column configurations while expanding service and resin replacement revenue streams for equipment suppliers.
REACH authorization restrictions on persistent organic pollutants are forcing reformulation of hydrophobic macroporous resins used in food-contact applications. ECHA substance evaluations have flagged legacy crosslinking agents, compelling producers to validate alternative polymerization chemistries. European food ingredient processors are accelerating qualification of compliant resin grades ahead of 2027 sunset dates for certain authorized uses.
Specification-driven procurement is consolidating buyer power among large pharmaceutical and semiconductor manufacturers, displacing spot-market resin purchases with multi-year framework agreements tied to quality audits. Tier-1 CDMOs in Switzerland and South Korea are unbundling resin supply from equipment procurement, creating direct supplier relationships that bypass traditional distribution channels. This reconfiguration is compressing margins for regional distributors while rewarding resin producers with dedicated technical service capabilities.
Global Polymeric Adsorbents Market Segmentation
Segmentation in polymeric adsorbents reveals distinct procurement patterns across standalone resin applications versus embedded purification systems. Understanding these structural divisions clarifies where formulation customization commands premium pricing versus where commoditized bulk supply dominates purchasing decisions.
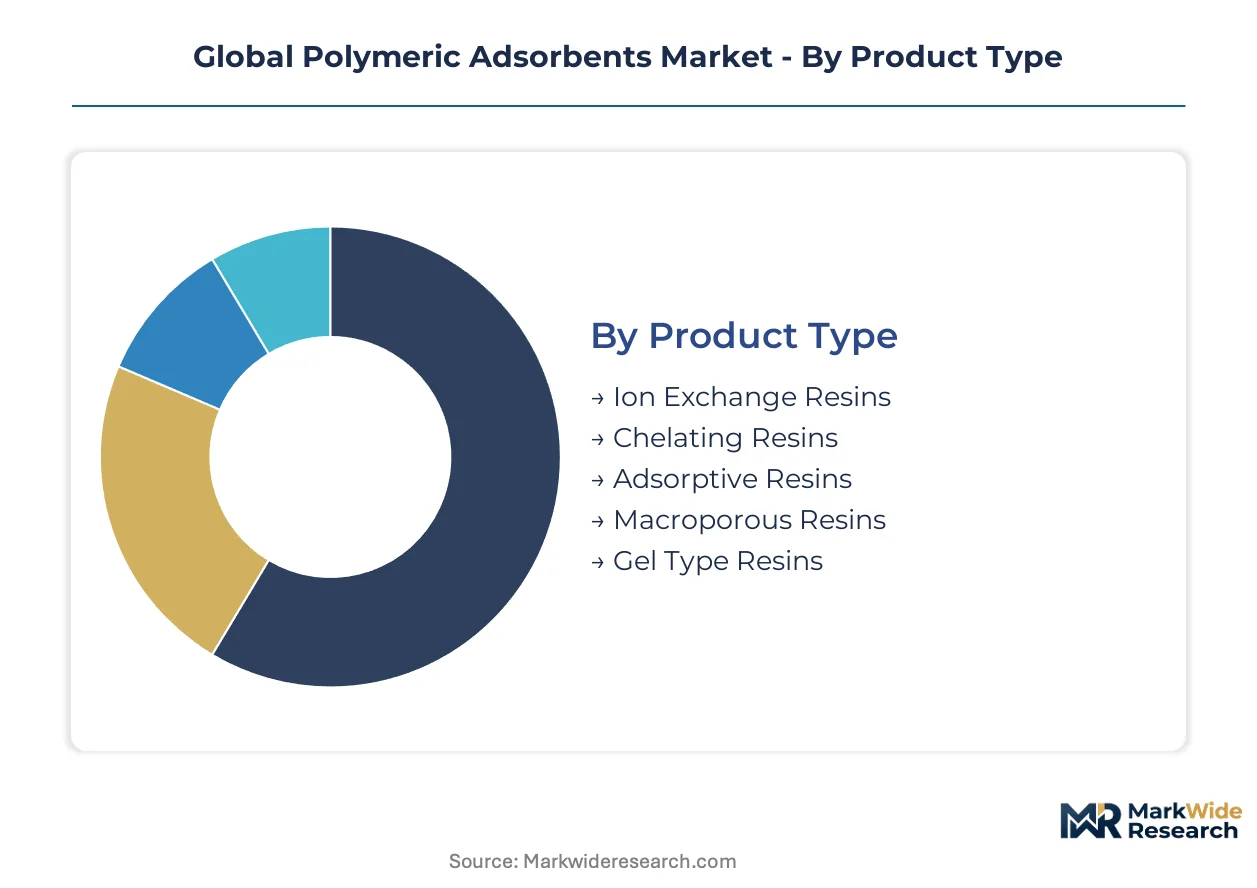
Product Type:
Integration depth varies sharply across product categories, with some resins functioning as standalone process equipment while others embed within larger purification trains.
- Ion Exchange Resins:Synthetic polymers bearing charged functional groups enable selective ion capture through electrostatic binding. Demand concentrates in semiconductor fabrication facilities across Taiwan, South Korea, and Germany as chip nodes advance below 7 nanometers requiring parts-per-trillion purity. EPA discharge mandates for industrial effluent are simultaneously upgrading specifications for power plant boiler water treatment.
- Adsorptive Resins:Macroporous polymers engineered with 100-800 square meter per gram surface areas capture target molecules via physical adsorption. Food and beverage processors in France and Italy are expanding deployment for decolorization and flavor stabilization applications. REACH authorization restrictions on legacy hydrophobic formulations are forcing rapid qualification of alternative polymerization chemistries ahead of regulatory sunset dates.
- Chelating Resins:Functionalized polymers with selective metal-binding ligands enable targeted heavy metal recovery.
- Macroporous Resins:Cross-linked matrices with permanent pore structures dominate bulk wastewater management where specification tolerance permits wider performance bands.
- Gel Type Resins:Non-porous homogeneous polymers serve specialized pharmaceutical chromatography applications requiring precise molecular sieving.
Adsorptive resins lead volumes today; ion exchange resins are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive pharmaceutical installations from operational-expense-driven water treatment deployments.
- Pharmaceutical Purification:Downstream processing of monoclonal antibodies and gene therapies demands resin grades meeting FDA, EMA, and PMDA pharmaceutical purity guidelines simultaneously. CDMOs in Switzerland and Singapore are unbundling resin supply from equipment procurement, creating direct supplier relationships that bypass traditional distribution channels. Multi-jurisdiction certification timelines extend product launch cycles substantially for new resin formulations in this segment.
- Water Treatment:Municipal and industrial effluent systems deploy resins for contaminant removal across diverse flow rates. EPA discharge limits in the United States mandate specific adsorbent performance thresholds that upgrade treatment infrastructure across chemical and electronics manufacturing clusters. Modular skid-mounted systems are compressing deployment timelines for mid-scale operators in this application tier.
- Food & Beverage Processing:Decolorization, deodorization, and contaminant removal in edible oil and sugar refining.
- Chemical Separation:Purification of specialty chemicals and solvent recovery operations.
- Catalysis:Polymer-supported catalyst carriers for heterogeneous reaction systems.
Water treatment leads volumes today; pharmaceutical purification is expanding most quickly.
End User Industry:
Customer type differentiation separates integrated chemical producers with captive resin regeneration capabilities from outsourced service-dependent operators.
- Wastewater Management:Municipal utilities and industrial effluent treatment operators handle diverse contaminant profiles across varying flow scales. Germany's chemical clusters anchor mature demand for bulk resin supply, while India's emerging treatment infrastructure creates qualification opportunities for exporters meeting CDSCO regulatory alignment with FDA standards. Activated carbon substitution pressure persists where specification tolerance permits wider performance bands.
- Biopharmaceutical Manufacturing:Monoclonal antibody and gene therapy producers require resin grades with validated extractables profiles and batch-to-batch consistency. Continuous countercurrent ion exchange technology is decentralizing purification capacity from centralized bulk chemical plants toward distributed manufacturing sites in Ireland and Singapore. Resin regeneration expertise shortage constrains operating continuous systems outside established chemical processing hubs.
- Food Processing Units:Edible oil refiners and sugar processors deploying adsorbents for quality upgrading.
- Specialty Chemicals Plants:High-purity chemical producers requiring contaminant removal and solvent purification.
Wastewater management leads volumes today; biopharmaceutical manufacturing is climbing the fastest.
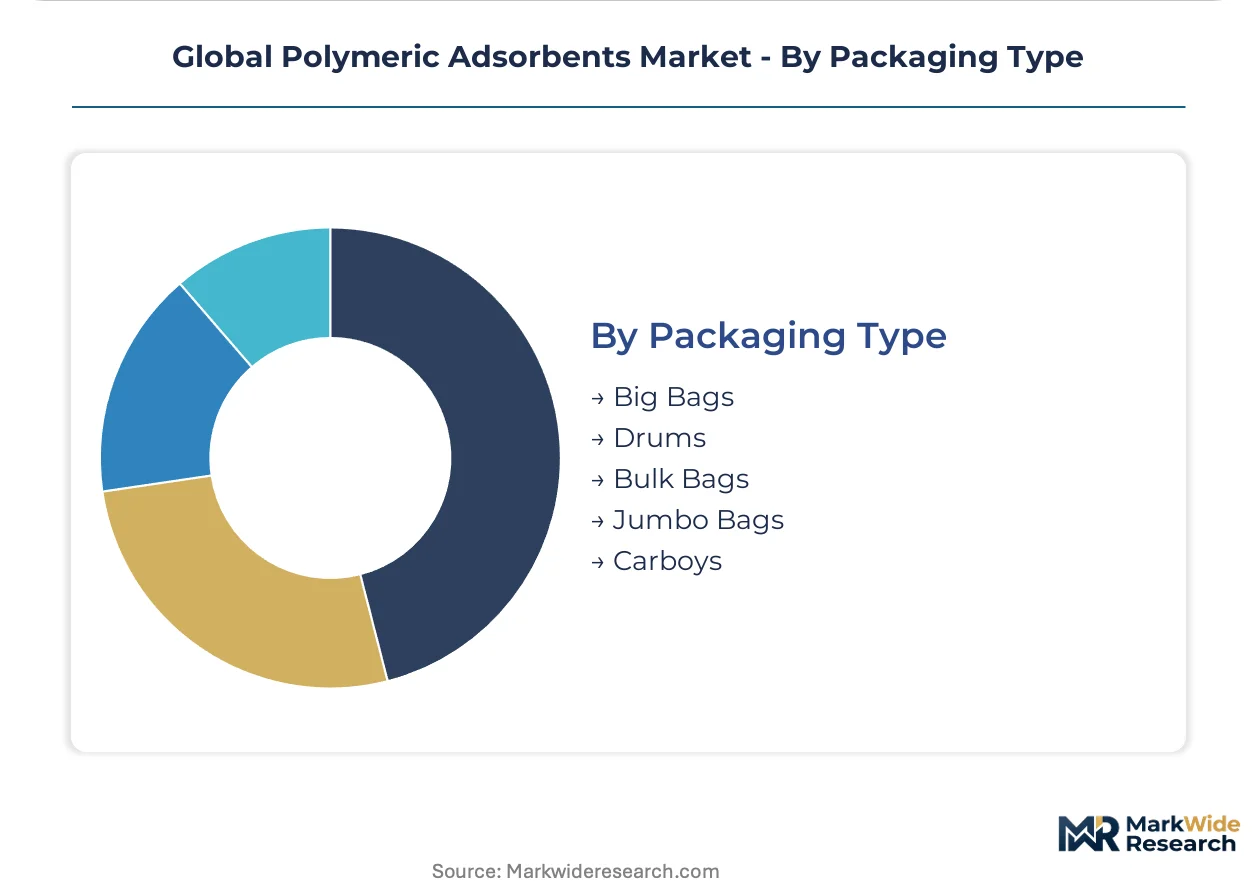
Packaging Type:
Supply concentration in packaging formats reflects downstream handling infrastructure and inventory turnover requirements across customer segments.
- Drums:Standardized 200-liter containers serve pharmaceutical and food-grade resin deliveries requiring contamination prevention. Swiss and South Korean CDMOs specify drum packaging for direct supplier relationships that bypass traditional distribution channels. Drum logistics concentrate around specialized chemical clusters in Germany, Japan, and China where pharmaceutical-grade resin capacity is concentrated.
- Big Bags:Intermediate bulk containers handle high-volume water treatment resin shipments to municipal utilities. Modular packaging configurations are broadening procurement flexibility for mid-scale operators seeking to optimize inventory carrying costs. Big bag demand tracks EPA-mandated infrastructure upgrades across United States chemical and electronics manufacturing clusters.
- Bulk Bags:Large-format flexible containers for high-tonnage industrial applications.
- Jumbo Bags:Specialized oversized packaging for continuous process feed systems.
- Carboys:Small-volume containers for laboratory and pilot-scale applications.
Drums lead volumes today; big bags are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale polymeric resin production during the post-war chemicals expansion, establishing the technical foundations that spread to Japan and the United States through licensing partnerships and joint ventures in the 1970s and 1980s.
Germany
Leverkusen and Ludwigshafen chemical corridors sustain Europe's densest concentration of pharmaceutical-grade resin capacity. REACH authorization timelines and EU Green Deal carbon border adjustments are accelerating feedstock transitions among integrated polymer producers. BASF SE's precursor networks anchor supply security for downstream macroporous formulations serving food-contact applications.
United States
EPA discharge mandates for industrial effluent are mandating adsorbent performance upgrades across Texas and Louisiana petrochemical clusters. The IRA's clean water infrastructure provisions are expanding municipal procurement for advanced ion exchange systems. Delaware and Michigan host specialized manufacturing platforms supplying semiconductor fabrication facilities in Arizona and Oregon.
China
SAMR's GB standard convergence toward EFSA equivalence is tightening food-contact resin specifications for domestic and export markets. The Yangtze River Delta concentrates adsorptive resin production for edible oil refining and sugar processing. Dual carbon goals are driving amine scrubber deployments in power and cement sectors requiring specialized polishing resins.
Japan
PMDA pharmaceutical purity guidelines and METI industrial standards govern resin specifications for biologics manufacturing. The Osaka-Kobe corridor maintains specialized ion exchange capacity for semiconductor-grade water treatment serving Kyushu chip fabrication complexes. Continuous countercurrent technology adoption is decentralizing purification systems toward distributed pharmaceutical sites.
India
CDSCO regulatory alignment with FDA standards is opening contract manufacturing demand for US- and EU-certified resin specifications. Gujarat and Maharashtra chemical parks are emerging as qualification hubs for pharmaceutical-grade adsorbent imports. SAMR-equivalent food safety protocols are creating parallel certification pathways for exporters targeting Asia-Pacific processing markets.
Global Polymeric Adsorbents Market Competitive Landscape
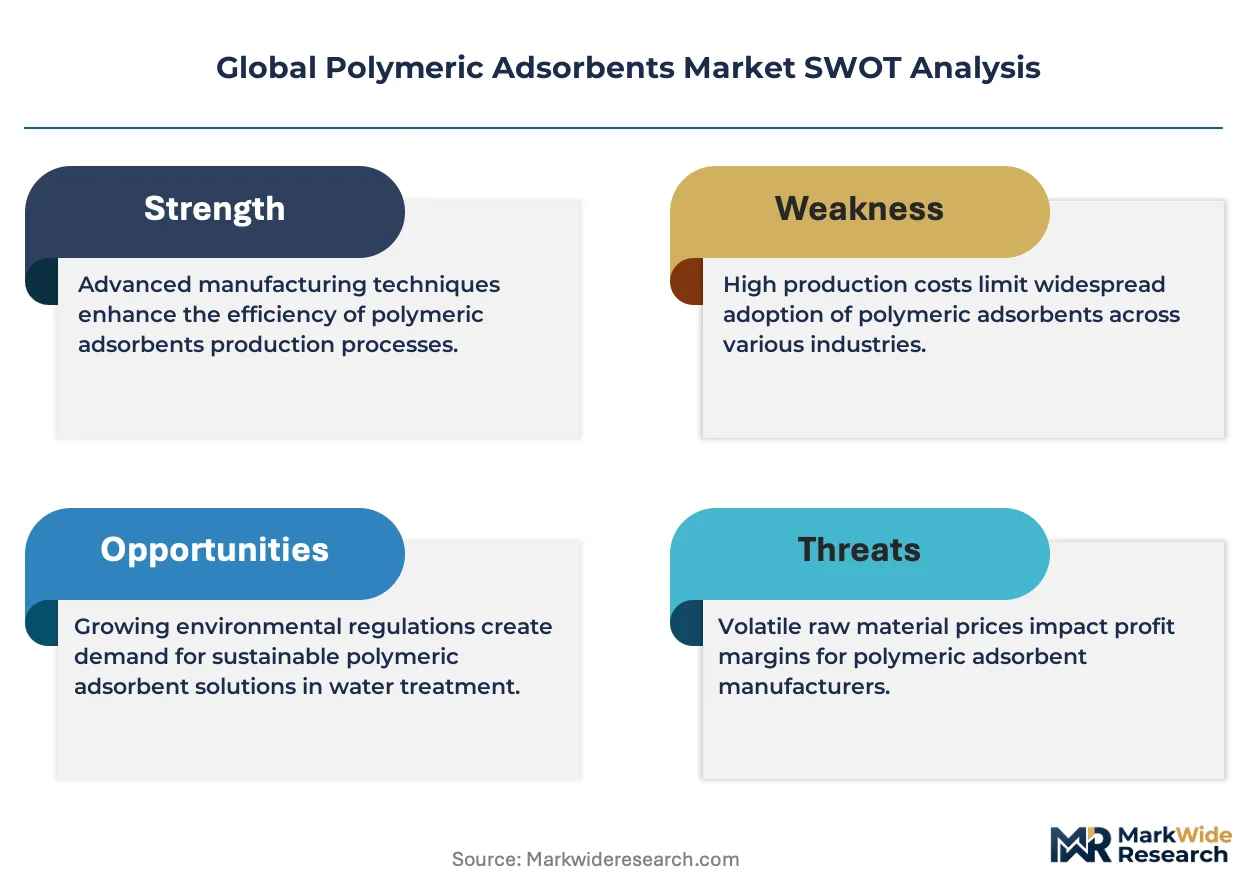
Premium-margin players sit above commodity-margin players across certification-tier and application-specific dimensions. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with captive monomer supply, specialized resin manufacturers with dedicated pharmaceutical-grade platforms, and regional compounders serving bulk water treatment procurement. Dominant competitive moves include backward integration into polymer precursor production and geographic expansion through technical service partnerships.
Among European integrated producers, BASF SE and Lanxess AG exemplify the conglomerate archetype with upstream control over styrenic monomer networks. Mitsubishi Chemical Corporation anchors Asian supply through Japan-based manufacturing platforms. Purolite Corporation occupies a specialist position within the pharmaceutical-grade chelating resin segment.
| Leading Market Players |
|---|
| BASF SE |
| Mitsubishi Chemical Corporation |
| Purolite Corporation |
| DuPont de Nemours |
| Lanxess AG |
| Thermax Limited |
| Sunresin New Materials Co. Ltd. |
| Chemra GmbH |
| The Dow Chemical Company |
| Others |
Supply & Pricing Matrix
Specialized resin regeneration engineers concentrated in Germany's Leverkusen-Ludwigshafen corridor command wage premiums that widen pricing spreads between pharmaceutical-grade and bulk water-treatment tiers. Labor-cost differentials between European technical hubs and emerging Asian manufacturing zones compress margins for commodity resin suppliers while sustaining premium capture for certified pharmaceutical grades.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-certified, industrial-grade, and bulk wastewater tiers anchors commercial negotiations. Price differentiation hinges on FDA-EMA-PMDA multi-jurisdiction certification status and captive monomer supply integration. Cost compression in industrial-grade segments intensifies as styrene-divinylbenzene feedstock volatility squeezes compounders lacking long-term supply contracts. Municipal water treatment operators exhibit highest price sensitivity; semiconductor fabricators demonstrate lowest sensitivity due to parts-per-trillion purity requirements.
Supply Chain Analysis
Dual-sourcing mandates from tier-1 CDMOs in Switzerland and South Korea force pharmaceutical buyers to qualify multiple resin suppliers simultaneously. Manufacturing concentrates in Germany, Japan, and China where specialized chemical clusters anchor downstream consumption. Raw material dependencies draw from crude oil-linked aromatic monomers, specialized polymerization catalysts, and high-purity solvents. Single-source vulnerability persists for semiconductor-grade ion exchange resins below 7-nanometer node specifications. Distribution runs through direct technical-service relationships for pharmaceutical grades and regional distributors for bulk water treatment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs in Europe run substantially above SAMR registration burdens in China, creating arbitrage opportunities for resin producers with dual-qualification capabilities. Geographic cost differentials favor integrated producers with captive precursor supply spanning both regulatory jurisdictions.
For Market Incumbents: To counter activated carbon substitution in bulk wastewater applications, BASF SE and Lanxess AG should deepen backward integration into styrenic monomer networks and expand technical-service partnerships in India's Gujarat chemical parks. Certification investment in CDSCO-FDA aligned resin grades represents the priority defensive lever.
For New Entrants and Emerging Players: Direct-to-CDMO digital procurement platforms offer the lowest-friction entry path for qualified resin suppliers. White-space targets include India's contract manufacturing demand for US- and EU-certified specifications and carbon capture solvent polishing for power sector decarbonization. Specialty chelating resins for heavy metal recovery present the most penetrable segment.
For Investors and Strategic Acquirers: Integrated chemical conglomerates are the most active acquirer in this space, seeking pharmaceutical-grade resin capabilities to complement captive monomer supply. Five-to-ten-year viability favors producers with REACH-compliant feedstock transitions and SAMR-EFSA convergence positioning. The signal to watch is ECHA substance evaluation timelines for legacy crosslinking agent sunset dates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Precursors | BASF SE's captive styrenic supply secures cost advantages across macroporous resin lines. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA-EMA-PMDA approvals extend product launch cycles but lock in CDMO relationships. |
| Continuous Countercurrent Technology Deployment | Mid-scale biologics producers in Ireland adopt distributed purification to reduce solvent consumption. |
| REACH-Compliant Feedstock Reformulation | ECHA evaluations of legacy crosslinking agents force alternative polymerization chemistry validation. |
| Technical Service Partnership Expansion | Purolite Corporation's specialized chelating expertise bypasses traditional distribution channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged resin plant managers, pharmaceutical procurement leads at CDMOs, water treatment utility engineers, and distribution channel partners across Germany, China, and the United States. Secondary validation drew from customs trade data, ECHA substance evaluation databases, SEC 10-K filings, and SAMR GB standard publications. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Comparable-period anchoring linked projection assumptions to historical performance across the analysis window. Segmentation modeling captured product type, application tier, end-use industry, and packaging format dimensions. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific inputs included EPA discharge mandate implementation timelines and semiconductor node advancement trajectories.
Feedstock volatility, regulatory authorization delays, and substitution by activated carbon are the dominant revision risks. Deviation in styrene-divinylbenzene pricing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market