
 Starch Polymer Market | 2026-2036
Starch Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Starch Polymer Market Outlook
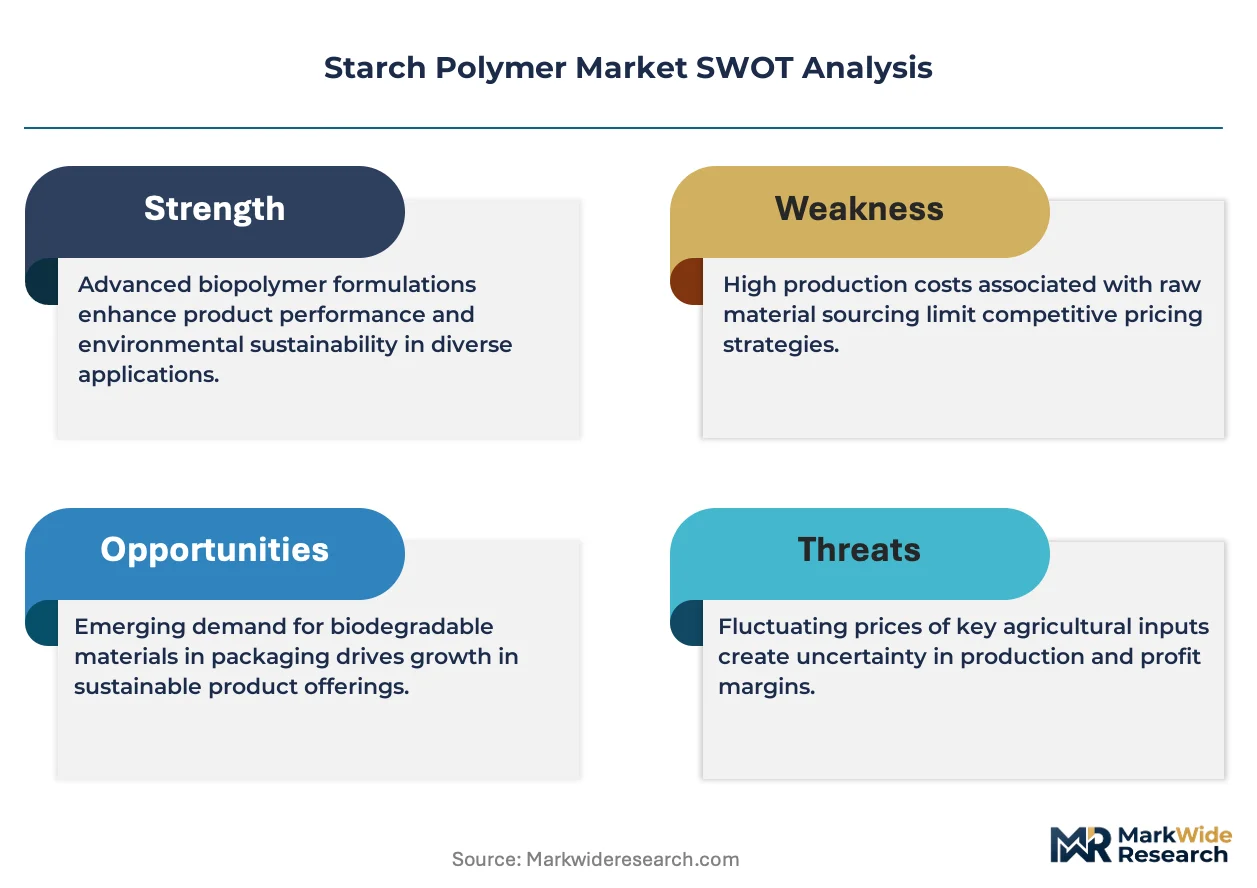
Compounding margin pools is narrowing as raw starch processors lose pricing power to blend formulation specialists. Novamont S.p.A dominates Italian biopolymer compounding through backward integration into vegetable oil feedstocks. BASF SE leverages its polymer science infrastructure to anchor high-performance starch blend development for automotive and durable goods applications.
Starch polymer denotes thermoplastic materials derived from native or modified starch granules, typically plasticized with glycerol or sorbitol and processed via extrusion or injection molding to achieve mechanical properties comparable to conventional polyolefins. Thermoplastic starch represents the largest volume category though margin pools concentrate in biodegradable starch blends where formulation complexity creates defensible intellectual property. Packaging applications lead absolute consumption while medical supplies represent the fastest-growing segment as sterilizable starch-based films gain regulatory clearance for device draping and short-cycle implants.
The EU Green Deal and REACH frameworks enforce biodegradability certification and restrict persistent microplastics, directly shaping product specifications and market access conditions for imported materials. FDA food contact notifications and EPA sustainable materials management programs govern US commercialization pathways, with compostability standards diverging between ASTM D6400 and EN 13432 certification regimes. Stakeholders must monitor regulatory fragmentation between industrial composting and home composting standards as this divergence determines which formulation investments yield commercial traction.
Market Dynamics
Composting infrastructure gaps are fragmenting addressable demand for starch polymers, as industrial composting capacity concentrates in Northern Europe while home composting certification requirements diverge sharply across national borders.
Growth Catalysts
- EU Green Deal mandates:The directive's material substitution targets compel food packaging converters to source certified biodegradable films, creating pull-through demand for thermoplastic starch formulations.
- Medical device sterilization protocols:FDA clearance pathways for gamma-sterilizable starch films are opening device draping and short-cycle implant applications previously served by petroleum-based barrier materials.
- Germany's packaging converter density:Industrial composting facility proximity in Baden-Württemberg and Bavaria enables closed-loop collection systems that validate total-cost-of-ownership models for brand owners.
Market Restraints
- Glycerol plasticizer cost volatility:Biodiesel co-product supply fluctuations transmit directly to thermoplastic starch input costs, compressing compounder margins during feedstock price spikes.
- Industrial composting concentration:Facility scarcity in Eastern European member states limits market penetration despite regulatory alignment, forcing suppliers to absorb logistics premiums or forfeit volume.
- EN 13432 certification friction:Divergent national implementation timelines create inventory stranding risk for materials producers holding blended formulations awaiting multi-jurisdiction approval.
Strategic Opportunities
- Agricultural film mulching:Soil-biodegradable starch blends for specialty crop cultivation remain underpenetrated in Italy's Po Valley vegetable production belt due to limited field trial data.
- Automotive interior panels:Convergence of thermoplastic starch with natural fiber reinforcement is enabling tier suppliers to meet OEM volatile organic compound reduction targets without petrochemical engineering plastics.
- France's extended producer responsibility expansion:Upcoming revisions to packaging waste regulations will mandate bio-based content thresholds that favor domestic starch polymer sourcing over imported conventional plastics.
Industry Challenges
- Formulation chemistry specialization:Shortage of polymer scientists trained in starch plasticization and compatibilization limits R&D throughput for blend developers seeking performance parity with polyolefins.
- Dual certification timelines:Parallel ASTM D6400 and EN 13432 testing requirements extend product commercialization cycles by 18-24 months, freezing capital in pre-revenue inventory.
- Legacy extrusion asset retrofitting:Conventional plastics processors face downtime and yield loss during equipment conversion to handle starch polymer moisture sensitivity and lower thermal stability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch Polymer Market |
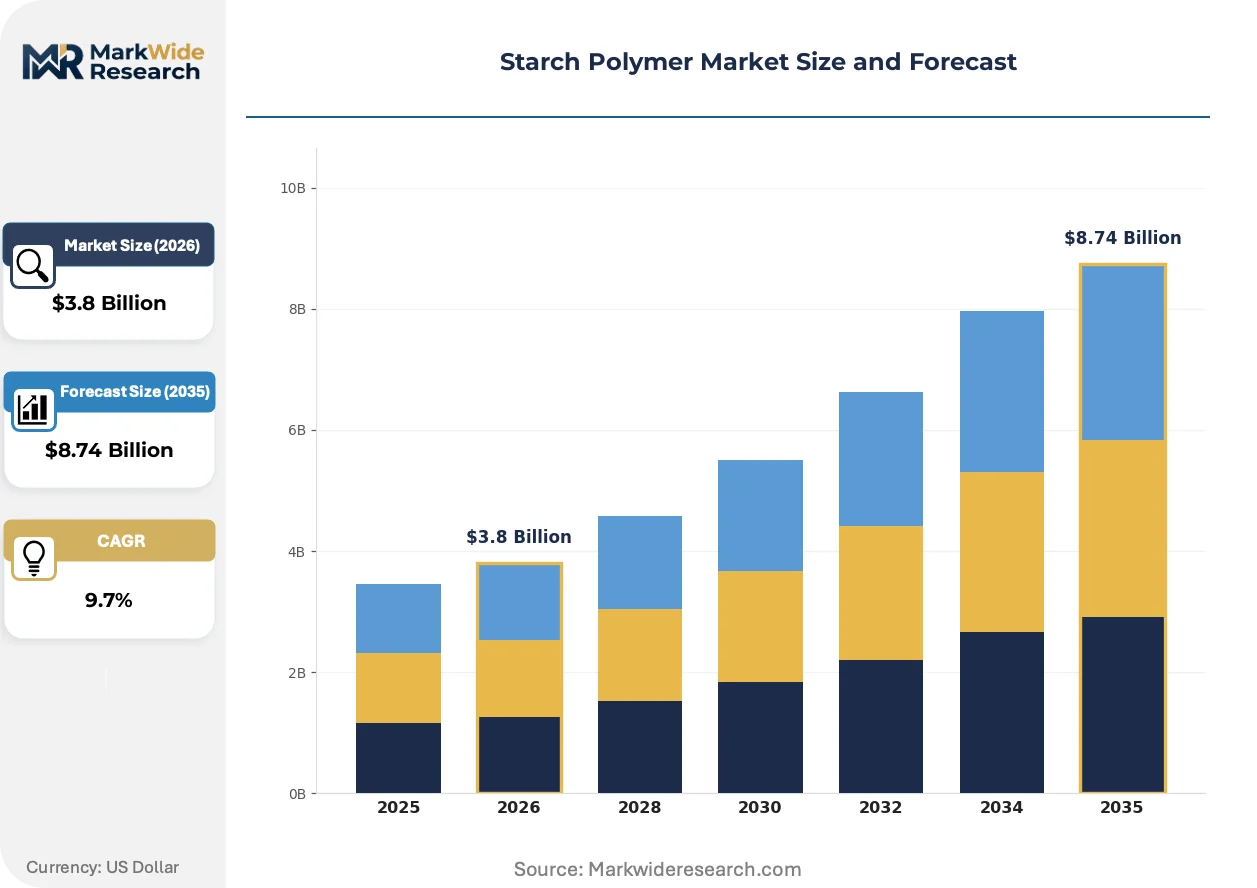
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Starch, Biodegradable Starch Blends, Starch-Based Composites, Starch Granules Application: Packaging, Agriculture, Consumer Goods, Medical Supplies End User: Food Industry, Textile Industry, Automotive Sector, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | United Biopolymers, S.A, Balson Industries, Novamont S.p.A, BIOTEC, BASF SE, Rodenburg Biopolymers, Plantic, Biome Bioplastics, JAPAN CORN STARCH CO., LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch Polymer Market Strategic Shifts
Reactive extrusion technology is compressing the performance gap between thermoplastic starch and conventional engineering polymers, while regulatory pressure on persistent microplastics intensifies formulation investment cycles across European compounders.
Reactive compatibilization via maleic anhydride grafting is collapsing the mechanical property differential between starch-polymer blends and petroleum-based alternatives. Automotive tier suppliers in Stuttgart and Turin are qualifying these materials for non-structural interior components at accelerated timelines. The technology is collapsing the historical premium pricing structure for bio-based automotive plastics by enabling drop-in processing on existing injection molding lines.
REACH microplastic restriction proposals are forcing reformulation of conventional multilayer packaging films. The European Chemicals Agency's restriction roadmap is compelling converters to eliminate synthetic polymer layers in favor of all-biodegradable starch-based barrier structures. Food contact applications in Germany and the Netherlands are experiencing the most acute displacement pressure as brand owners pre-empt enforcement with packaging redesigns.
Certification-driven procurement mandates are reshaping supplier selection criteria for European retail chains. Carrefour and REWE Group purchasing departments now require industrial composting certification as a gate condition for produce packaging tenders, displacing price-only sourcing models. France and Germany's organized retail sectors exhibit the most pronounced preference shift, with private-label commitments accelerating volume commitments to certified starch polymer suppliers.
Starch Polymer Market Segmentation
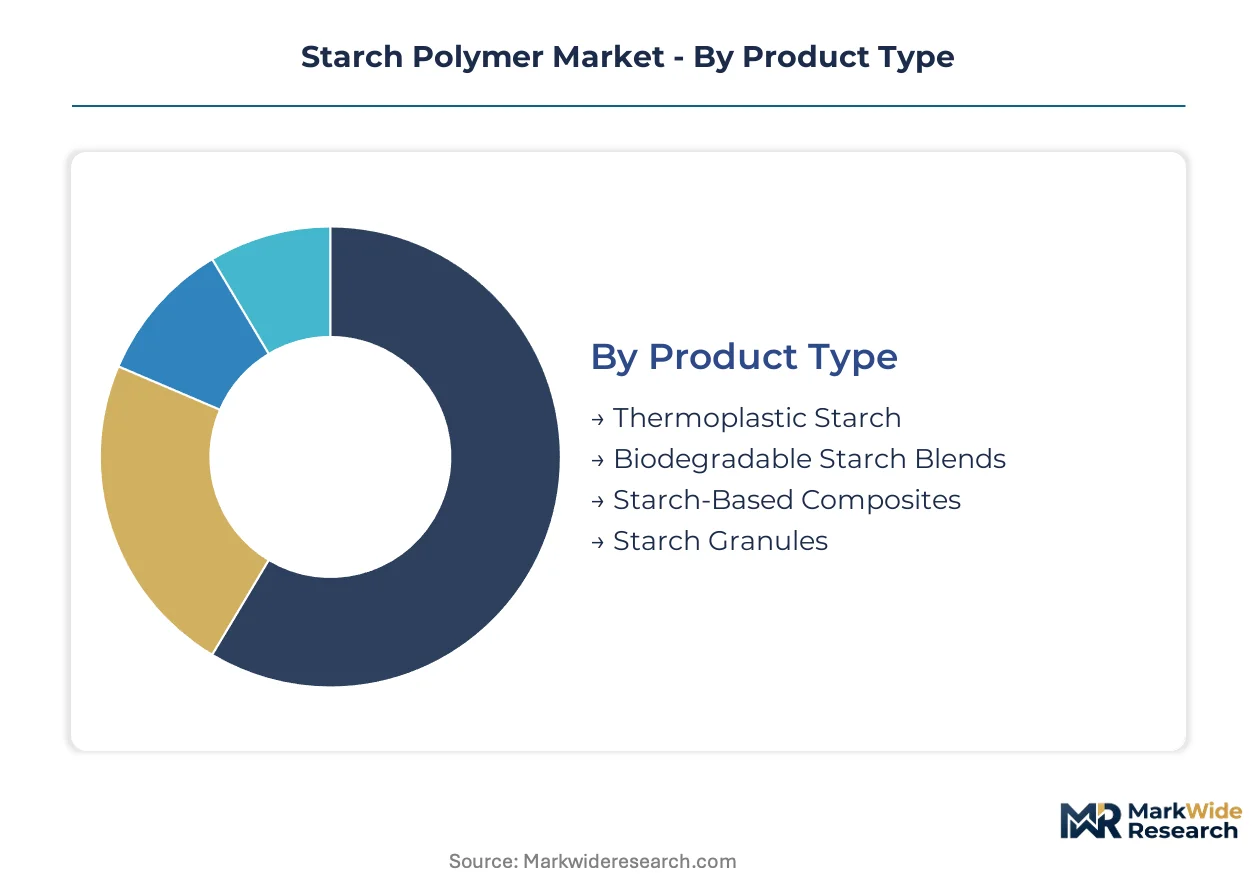
Starch polymer formulations exhibit divergent margin profiles and certification requirements across product architectures, while application segments face uneven infrastructure readiness for composting end-of-life pathways. Segmentation clarity enables suppliers to align R&D investment with the highest-conversion demand pockets.
Product Type:
Mature thermoplastic starch formulations anchor baseline volume, while emerging composite architectures command formulation premiums through performance differentiation.
- Thermoplastic Starch:Native or modified starch granules plasticized with glycerol or sorbitol, processed via extrusion to achieve polyolefin-comparable mechanical properties. Demand concentrates in German and Italian food packaging where industrial composting infrastructure validates total-cost-of-ownership models for brand owners.
- Biodegradable Starch Blends:Compatibilized formulations combining starch with aliphatic polyesters or polyhydroxyalkanoates, creating defensible intellectual property through formulation complexity. French and Dutch retail chains now mandate industrial composting certification as a procurement gate condition, accelerating displacement of conventional multilayer films.
- Starch-Based Composites:Reinforced architectures with natural fibers or mineral fillers for dimensional stability in durable goods.
- Starch Granules:Unplasticized feedstock for downstream compounders and masterbatch producers.
Thermoplastic starch handles the majority of throughput; biodegradable starch blends are climbing the fastest on share.
Application:
Cost tier stratification separates commodity packaging from specialty medical and agricultural films where certification premiums justify higher formulation investment.
- Packaging:Films, trays, and pouches for fresh produce and dry goods, requiring EN 13432 or ASTM D6400 certification for retail acceptance. Carrefour and REWE Group purchasing departments now require compostability documentation as a tender prerequisite.
- Agriculture:Soil-biodegradable mulch films and planting trays, with Italy's Po Valley vegetable belt representing underpenetrated demand pending field trial completion.
- Consumer Goods:Disposable cutlery, tableware, and personal care packaging with shorter certification pathways.
- Medical Supplies:Gamma-sterilizable films for device draping and short-cycle implants, representing the steepest expansion trajectory as FDA clearance pathways open barrier applications previously served by petroleum-based materials.
Packaging commands the largest absolute volume; medical supplies is expanding most quickly on regulatory clearance momentum.
End User:
Customer type diversity spans price-sensitive commodity buyers to performance-specifying OEMs, with automotive and construction segments requiring thermal stability beyond standard starch formulations.
- Food Industry:Brand owners and converters replacing conventional plastics with compostable alternatives under EU Green Deal substitution mandates, with Germany's packaging converter density enabling closed-loop collection systems.
- Textile Industry:Sizing agents and temporary stiffeners for yarn processing, with lower composting infrastructure dependency.
- Automotive Sector:Tier suppliers in Stuttgart and Turin qualifying starch-natural fiber composites for non-structural interior panels to meet volatile organic compound reduction targets.
- Construction:Biodegradable void formers and temporary molds with limited current penetration.
Food industry procurement drives the majority of volume commitments; automotive sector qualification timelines are accelerating fastest on OEM sustainability mandates.
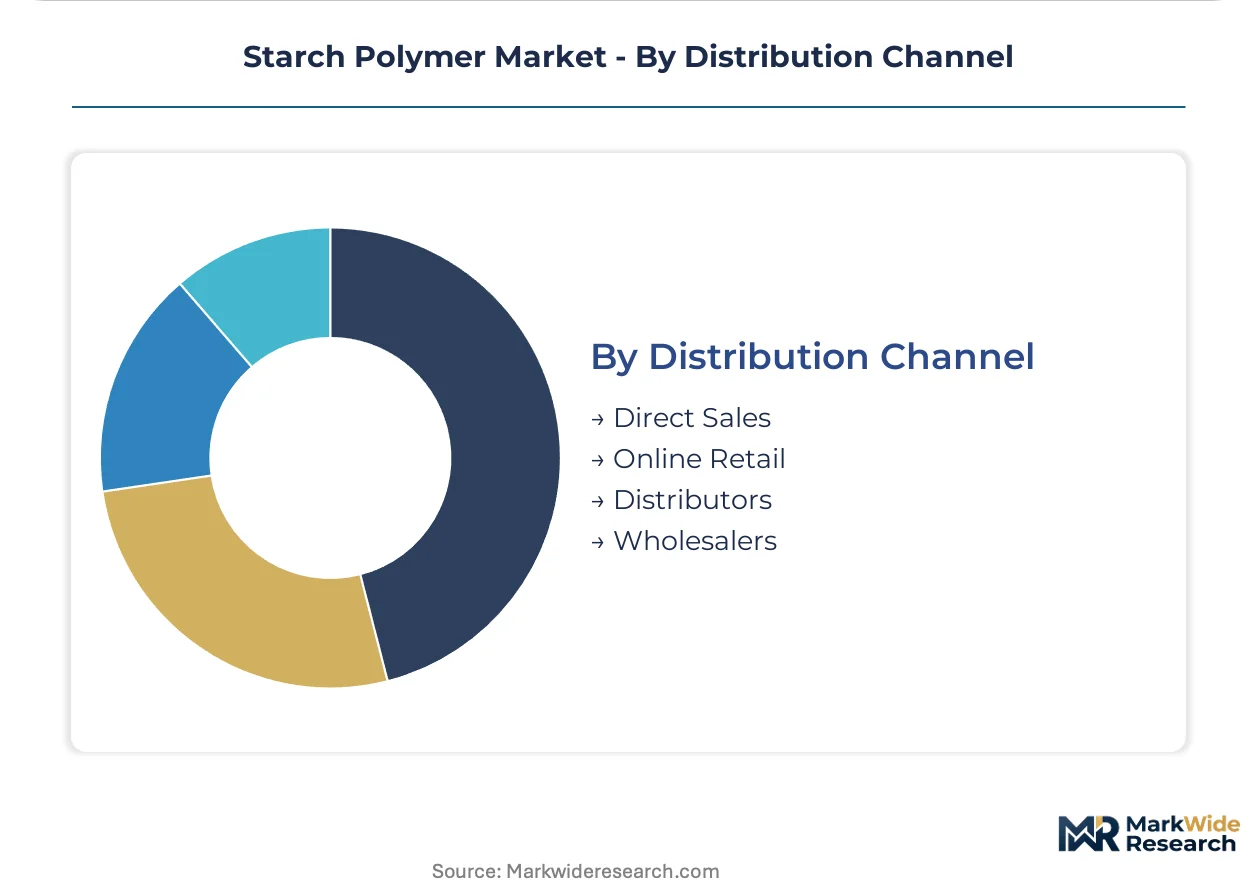
Distribution Channel:
Supply concentration favors direct relationships with large compounders, while distributor networks fragment margin capture across smaller converters in Eastern European markets with sparse industrial composting infrastructure.
- Direct Sales:Long-term supply agreements between starch polymer producers and major packaging converters, capturing volume premiums through formulation co-development and technical service integration.
- Distributors:Regional inventory positioning for mid-tier converters in markets with fragmented logistics, absorbing working capital requirements for certification-holding stock.
- Online Retail:Sample and small-batch procurement for R&D and qualification trials.
- Wholesalers:Bulk commodity movement of unmodified starch granules to downstream compounders.
Direct sales channels handle the majority of value throughput; distributor networks are gaining share fastest in Eastern European member states where facility scarcity forces suppliers to absorb logistics premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern Europe remain highly price-sensitive due to sparse industrial composting infrastructure, while German and Italian converters absorb formulation premiums where closed-loop collection validates total-cost-of-ownership models.
Germany
Baden-Württemberg and Bavaria host Europe's densest packaging converter clusters, with industrial composting facility proximity enabling brand owners to justify starch polymer premiums. The country's national packaging regulator enforces extended producer responsibility revisions that mandate bio-based content thresholds. Stuttgart's automotive tier suppliers qualify starch-natural fiber composites for interior panels under OEM volatile organic compound reduction mandates.
Italy
The Po Valley vegetable belt presents underpenetrated demand for soil-biodegradable mulch films pending field trial completion, while Northern Italian compounders dominate European biopolymer formulation. EU Green Deal implementation timelines accelerate material substitution mandates for food packaging converters. Novamont S.p.A anchors the country's backward integration model through captive vegetable oil feedstock supply.
France
Carrefour's procurement department now requires industrial composting certification as a gate condition for produce packaging tenders, displacing price-only sourcing models. Upcoming revisions to national packaging waste regulations under the EU Green Deal framework will strengthen bio-based content mandates. The country's organized retail sector exhibits the most pronounced preference shift toward certified starch polymer suppliers.
Netherlands
REWE Group's Dutch operations mirror French certification-driven procurement patterns, with retail chains prioritizing EN 13432 documentation over conventional polymer cost advantages. REACH microplastic restriction proposals from the European Chemicals Agency intensify converter pressure to eliminate synthetic polymer layers. Amsterdam-Rotterdam logistics corridors enable efficient distribution to fragmented Eastern European markets.
United States
FDA food contact notification pathways for gamma-sterilizable starch films are opening medical device applications previously served by petroleum-based barrier materials. EPA sustainable materials management programs govern commercialization timelines, with ASTM D6400 certification diverging from European EN 13432 standards. Midwestern agricultural processors evaluate soil-biodegradable mulch formulations for specialty crop cultivation.
Starch Polymer Market Competitive Environment
Capability concentration sits with formulation specialists who command margin pools through compatibilization chemistry; scale advantage sits with diversified chemical conglomerates leveraging polymer science infrastructure across multiple bio-based material categories. The market structure exhibits tiered competition between backward-integrated European compounders, Asian starch processors, and global diversified materials suppliers. Strategic archetypes include vegetable oil-integrated biopolymer specialists, petrochemical majors with bio-based divisions, and regional starch granule processors expanding downstream. Dominant competitive moves center on reactive extrusion technology licensing and captive feedstock integration.
Among European specialists, Novamont S.p.A and Rodenburg Biopolymers exemplify the backward-integrated archetype through upstream control over agricultural feedstocks. BASF SE anchors the diversified chemical conglomerate tier, representing scale-driven positioning across multiple biodegradable polymer platforms. These three occupy positions that illustrate the market's fundamental segmentation between formulation complexity defenders and commodity scale players.
| Leading Market Players |
|---|
| United Biopolymers, S.A |
| Balson Industries |
| Novamont S.p.A |
| BIOTEC |
| BASF SE |
| Rodenburg Biopolymers |
| Plantic |
| Biome Bioplastics |
| JAPAN CORN STARCH CO., LTD |
| Others |
Value Chain & Pricing Dynamics
Amsterdam-Rotterdam corridor freight differentials compress margins for Eastern European converters while amplifying pricing power for German compounders with captive industrial composting access. Certification-holding inventory concentrates in Northern European logistics nodes, forcing price stratification between EN 13432-validated formulations and uncertified commodity grades.
Pricing Analysis
Long-term offtake contracts dominate volume procurement between major compounders and retail chains, insulating German and Italian suppliers from glycerol plasticizer spot volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical grades from food-contact packaging and unmodified granule feedstock. Cost compression in standard-tier biodegradable blends is intensifying because biodiesel co-product supply fluctuations transmit directly to input costs. Price-sensitive buyers in Eastern European markets with sparse composting infrastructure forfeit volume to logistics-absorbing distributors, while German automotive tier suppliers absorb formulation premiums for VOC-compliant interior specifications.
Supply Chain Analysis
EU dual-use export controls on reactive extrusion compatibilization technology constrain technology transfer to Asian starch processors, preserving formulation complexity advantages for European compounders. Manufacturing gravity centers on Germany, Italy, and the Netherlands, with downstream conversion capacity concentrated in Baden-Württemberg and Northern Italian industrial districts. Feedstock supply draws from Brazilian cassava, Ukrainian corn, and EU rapeseed oil streams, creating tariff exposure at biodiesel policy friction points. Distribution runs through direct technical-service relationships with major converters, with distributor networks fragmenting margin capture across mid-tier Eastern European processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial composting certification interoperability is emerging as the platform-economics inflection, with EN 13432 and ASTM D6400 convergence determining which formulation investments achieve cross-border scale. Ecosystem lock-in effects favor early movers who anchor retail chain procurement specifications.
For Market Incumbents: Insulate formulation IP through reactive extrusion technology licensing to automotive tier suppliers, locking in multi-year qualification cycles. Deepen backward integration into vegetable oil feedstocks to offset glycerol plasticizer cost volatility from biodiesel market swings. Prioritize dual-certification capacity expansion before upcoming EU Green Deal packaging waste mandate enforcement tightens supply.
For New Entrants and Emerging Players: Build out soil-biodegradable mulch film field trial infrastructure in Italy's Po Valley vegetable belt, where limited performance data has stalled penetration despite regulatory tailwinds. Target French extended producer responsibility revisions by anchoring bio-based content threshold compliance for domestic sourcing mandates. Lead with technical service partnerships rather than price competition against established compounder relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors with orphaned bio-based divisions lacking backward integration into agricultural feedstocks. Five-to-ten year viability hinges on certification infrastructure convergence rather than formulation chemistry alone. Watch for EN 13432 home composting standard adoption as the inflection signal determining which blended formulation portfolios achieve addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Extrusion Technology Licensing | Automotive tier suppliers in Stuttgart qualify starch-natural fiber composites for interior panels under OEM VOC mandates. |
| Backward Integration into Vegetable Oil Feedstocks | Novamont's captive agricultural supply insulates Italian compounders from biodiesel co-product price transmission. |
| Dual Certification Capacity Expansion | Parallel ASTM D6400 and EN 13432 testing extends commercialization cycles by 18-24 months for market access. |
| Soil-Biodegradable Field Trial Infrastructure | Italy's Po Valley vegetable belt awaits performance validation for mulch film displacement of polyethylene. |
| Extended Producer Responsibility Compliance Positioning | France's upcoming packaging waste revisions mandate bio-based content thresholds favoring domestic sourcing. |
Study Parameters
Operator-level perspectives from compounder plant managers, retail procurement directors, automotive tier supplier engineers, and industrial composting facility operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EU ECHA restriction roadmap filings, ASTM D6400 and EN 13432 certification registries, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data on glycerol and sorbitol plasticizer flows. Bottom-up capacity modeling across German, Italian, and French production facilities was triangulated against top-down demand estimates from retail chain sustainability commitments and EU Green Deal substitution targets.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning thermoplastic starch versus biodegradable blend architectures, packaging versus medical versus agricultural applications, and direct sales versus distributor channel structures. CAGRs were derived from regression analysis of historical certification-driven procurement patterns and forward projections of composting infrastructure buildout timelines. Industry-specific forecast inputs included biodiesel co-product supply elasticity, FDA food contact notification clearance velocity, and REACH microplastic restriction implementation phasing.
Stress conditions across glycerol price volatility bands, industrial composting capacity buildout delays, and dual-certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory harmonization trajectories and feedstock supply continuity. Material shifts in EU Green Deal enforcement timing or ASTM-EN certification convergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Geopolymer Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Polyol Esters Market