
 Formaldehyde-Free Resin Market | 2026-2036
Formaldehyde-Free Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Formaldehyde-Free Resin Market Analysis
German chemical producers is restructuring capacity toward bio-based aldehyde alternatives as EU REACH restrictions on formaldehyde intensify. BASF SE leverages its Ludwigshafen integrated site to sustain polyurethane resin output for automotive interiors. Huntsman Corporation anchors North American supply through its Geismar, Louisiana manufacturing complex. DIC Corporation competes in Asian electronics coatings with specialized acrylic formulations.
Formaldehyde-free resins are synthetic or bio-derived polymers engineered to deliver bonding, coating, or composite matrix functions without releasing formaldehyde emissions, typically achieving VOC thresholds below 0.05 ppm in finished products. These resins serve industries where indoor air quality mandates prohibit traditional urea-formaldehyde or phenol-formaldehyde systems. Epoxy resins dominate structural adhesives applications due to superior shear strength and chemical resistance in load-bearing joints. Polyurethane formulations command premium positioning in automotive sealants where flexibility and weathering performance justify higher formulation costs. Acrylic resins lead electronics coatings growth as miniaturization drives demand for low-temperature cure, non-yellowing protection.
EPA TSCA Title VI and CARB ATCM Phase 2 set binding emission limits on composite wood products sold in the United States, directly converting compliance cost into product differentiation. ECHA REACH restrictions on formaldehyde classification as a Category 1B carcinogen force reformulation across European construction supply chains. Japan METI's Green Purchasing Act extends preferential procurement to buildings certified under CASBEE indoor environment criteria. Stakeholders must monitor regulatory divergence between California's incremental standards and EU hazard-based bans to anticipate which chemistry platforms achieve cross-jurisdictional scale.
Market Dynamics
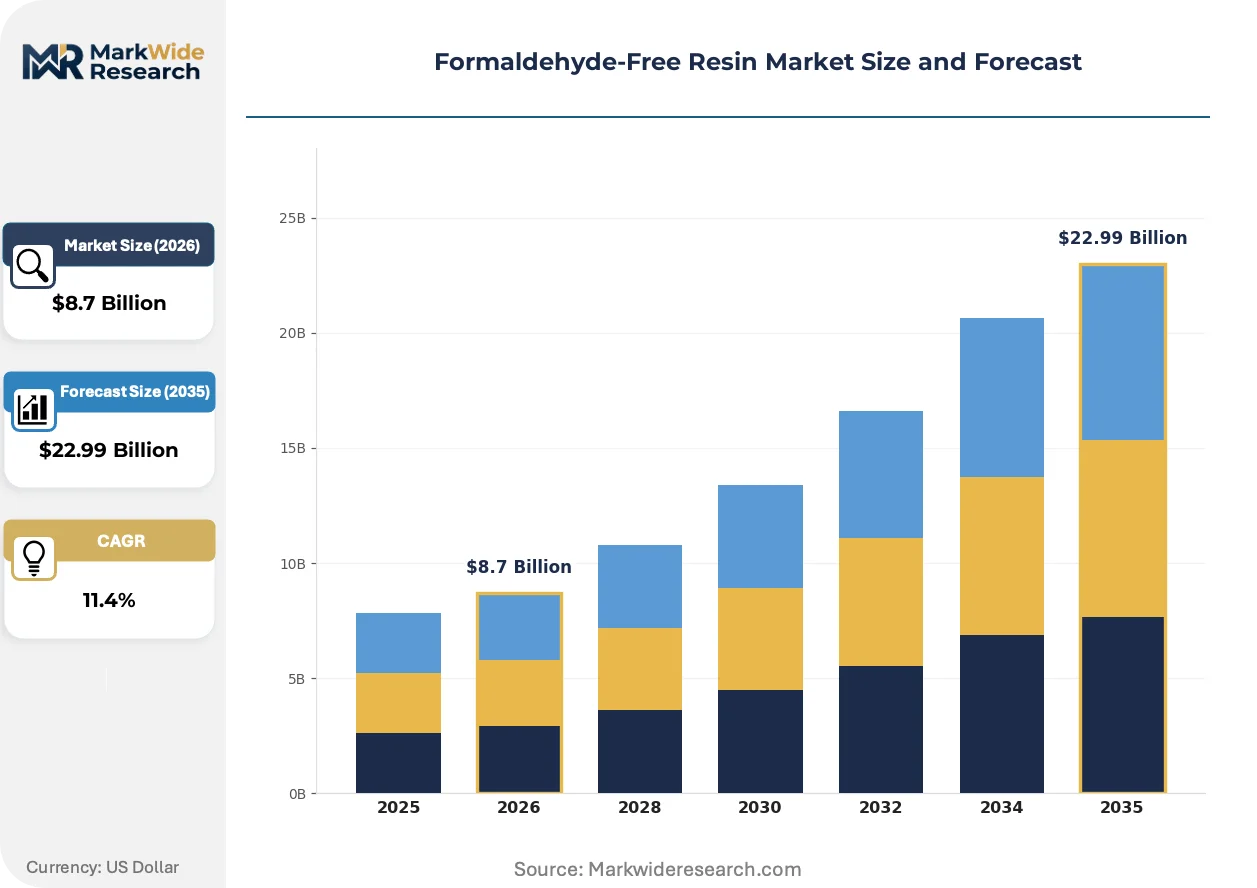
EPA TSCA Title VI and CARB Phase 2 emission ceilings are compressing the addressable market for conventional urea-formaldehyde binders while accelerating capital redeployment toward bio-based aldehyde alternatives and polyurethane systems.
Growth Catalysts
- CARB Phase 2 Enforcement:California's binding composite wood emission limits force residential furniture manufacturers to specify formaldehyde-free binders for regulatory access.
- Passivhaus Construction:Germany's low-energy building standard mandates material specifications below 0.05 ppm VOC thresholds, concentrating specification demand in Central European supply chains.
- Acrylic Electronics Coatings:Miniaturization trends in semiconductor packaging drive low-temperature cure formulations that avoid formaldehyde crosslinkers entirely.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane resin costs fluctuate with isocyanate and polyol pricing, compressing margin stability for automotive sealant formulators.
- Specialized Curing Infrastructure:Epoxy and polyurethane systems require controlled temperature and humidity conditions incompatible with legacy urea-formaldehyde production lines.
- Performance Trade-offs in Moisture Resistance:Early-generation bio-based alternatives exhibit hydrolytic instability in exterior structural applications, limiting specification in marine and infrastructure segments.
Strategic Opportunities
- Japanese Green Procurement:METI's CASBEE-certified building preferences create a specification channel for low-emission interior materials in public construction.
- Automotive Interior Consolidation:OEM tier-one suppliers are unbundling adhesive specification from laminate purchasing, enabling direct resin producer relationships.
- Hybrid Bio-Synthetic Formulations:Convergence of lignin-derived platforms with conventional polyurethane chemistry opens cost-performance positioning between premium and economy tiers.
Industry Challenges
- Cross-Jurisdictional Certification Complexity:Manufacturers must maintain parallel EPA TSCA Title VI, ECHA REACH, and CARB compliance documentation, extending product launch timelines.
- Formulation Chemistry Talent Scarcity:Polymer scientists with expertise in both bio-based feedstocks and high-performance adhesive engineering command premium compensation, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formaldehyde-Free Resin Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Silicone End User: Construction, Automotive, Furniture, Electronics Application: Adhesives, Coatings, Composites, Sealants Form: Liquid, Powder, Gel, Granule |
| Companies Covered | BASF SE, Huntsman Corporation, DIC Corporation, Sika AG, Ashland Global Holdings, Hexion Inc., Dynea AS, SI Group Inc., Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formaldehyde-Free Resin Market Emerging Trajectories
Bio-based aldehyde platforms are overtaking petrochemical-derived systems as the primary innovation vector, with regulatory pressure and feedstock cost trajectories converging to compress conventional chemistry margins.
Polyurethane dispersions are overtaking solvent-borne epoxy systems in automotive interior lamination. Tier-one seating suppliers in Germany and the US Midwest have converted specification protocols to water-based alternatives since 2023. The shift is overtaking capital allocation patterns, with resin producers redirecting R&D expenditure from high-VOC epoxy modifications toward dispersion stability and adhesion promotion chemistry.
REACH restrictions on formaldehyde classification as Category 1B carcinogen are forcing reformulation across European construction supply chains. The hazard-based approach creates immediate substitution pressure distinct from California's incremental emission standards. Wood panel producers in Poland and Romania are accelerating qualification of alternative binders to maintain access to German and Benelux distribution channels.
Building certification systems are displacing conventional procurement specifications as the primary demand filter. Architects and developers in Germany, Japan, and California now specify CASBEE, Passivhaus, or LEED-compliant material packages rather than individual product performance metrics. This compression of buying criteria is concentrating volume among resin producers with pre-certified formulation portfolios, marginalizing smaller suppliers lacking documentation infrastructure.
Formaldehyde-Free Resin Market Segmentation
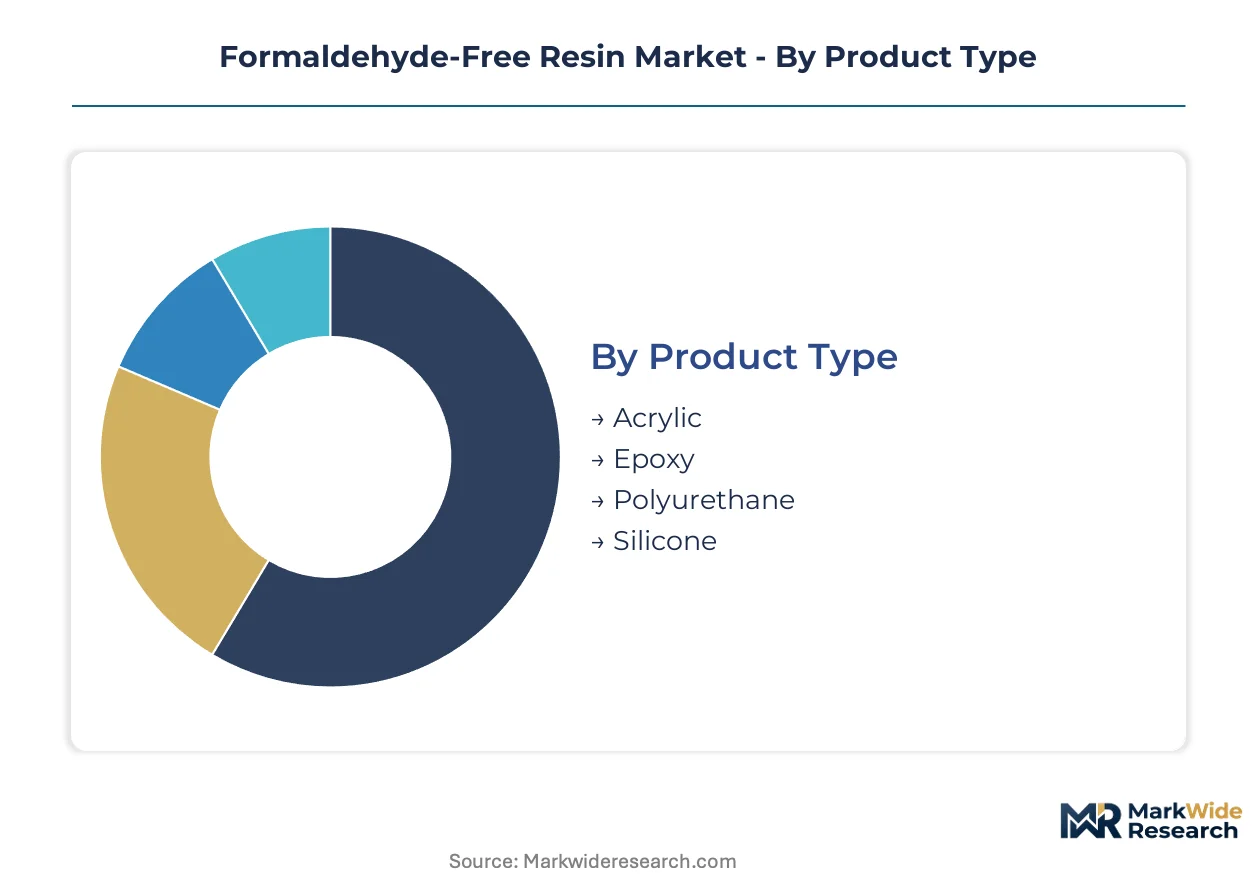
Segmentation in formaldehyde-free resins reveals how chemistry platforms align with regulatory pressure points and end-use performance thresholds. Product type and application dimensions determine which suppliers capture specification authority in high-compliance markets.
Product Type:
Customization intensity varies sharply across this category, with commodity acrylics at one pole and engineered polyurethanes at the other.
- Polyurethane:These resins combine isocyanate-terminated prepolymers with polyol backbones to deliver flexible, durable bonds without formaldehyde crosslinkers. Automotive sealant specifications in Germany and the US Midwest concentrate demand here, driven by OEM interior air quality mandates and weathering performance requirements.
- Epoxy:Bisphenol-A or bisphenol-F diglycidyl ethers cured with amine hardeners provide structural adhesive strength and chemical resistance. Load-bearing joint applications in construction and marine sectors specify these systems where moisture resistance and shear strength override cost sensitivity.
- Acrylic:Methacrylate and acrylate monomers polymerized via free-radical initiation serve electronics coatings and light-cure adhesives with low-temperature processing.
- Silicone:Siloxane backbone polymers deliver thermal stability and weathering resistance for exterior sealants and high-temperature gaskets.
Most installed capacity flows through polyurethane systems. Expansion is steepest in acrylic formulations for semiconductor packaging.
End User:
Cost tier stratification separates specification-heavy segments from price-sensitive volume applications.
- Construction:Wood panel binders, structural adhesives, and concrete coatings serve residential and commercial building. CARB Phase 2 and EPA TSCA Title VI compliance deadlines in the United States compress the addressable market for conventional urea-formaldehyde alternatives.
- Automotive:Interior lamination adhesives, sealants, and NVH damping materials require low-VOC formulations meeting OEM air quality protocols. Tier-one seating suppliers in Germany and the US Midwest have converted specification protocols to water-based polyurethane alternatives.
- Furniture:Residential and office furniture manufacturers specify low-emission binders for particleboard, MDF, and plywood substrates to access California and European distribution channels.
- Electronics:Conformal coatings, encapsulants, and die-attach adhesives protect semiconductor packages and printed circuit boards from moisture and thermal cycling.
Construction absorbs the largest volume share. Automotive specifications are climbing the fastest as OEMs unbundle adhesive procurement from laminate purchasing.
Application:
Volume concentration versus margin potential distinguishes commodity coatings from specialized composite matrices.
- Adhesives:Structural bonding formulations for wood, metal, and composite substrates replace urea-formaldehyde and phenol-formaldehyde systems in load-bearing joints. Passivhaus construction standards in Germany mandate material specifications below 0.05 ppm VOC thresholds, concentrating specification demand for high-performance alternatives.
- Coatings:Protective and decorative films applied to substrates ranging from electronics to automotive exteriors demand low-temperature cure and non-yellowing performance.
- Composites:Matrix resins binding fiber reinforcements in wind blades, automotive panels, and marine structures require tailored rheology and cure kinetics.
- Sealants:Flexible gap-filling formulations for construction and automotive joints balance elongation, adhesion, and durability under thermal and moisture cycling.
Adhesives command the greatest installed base. Composite applications are expanding most quickly with wind energy and electric vehicle lightweighting programs.
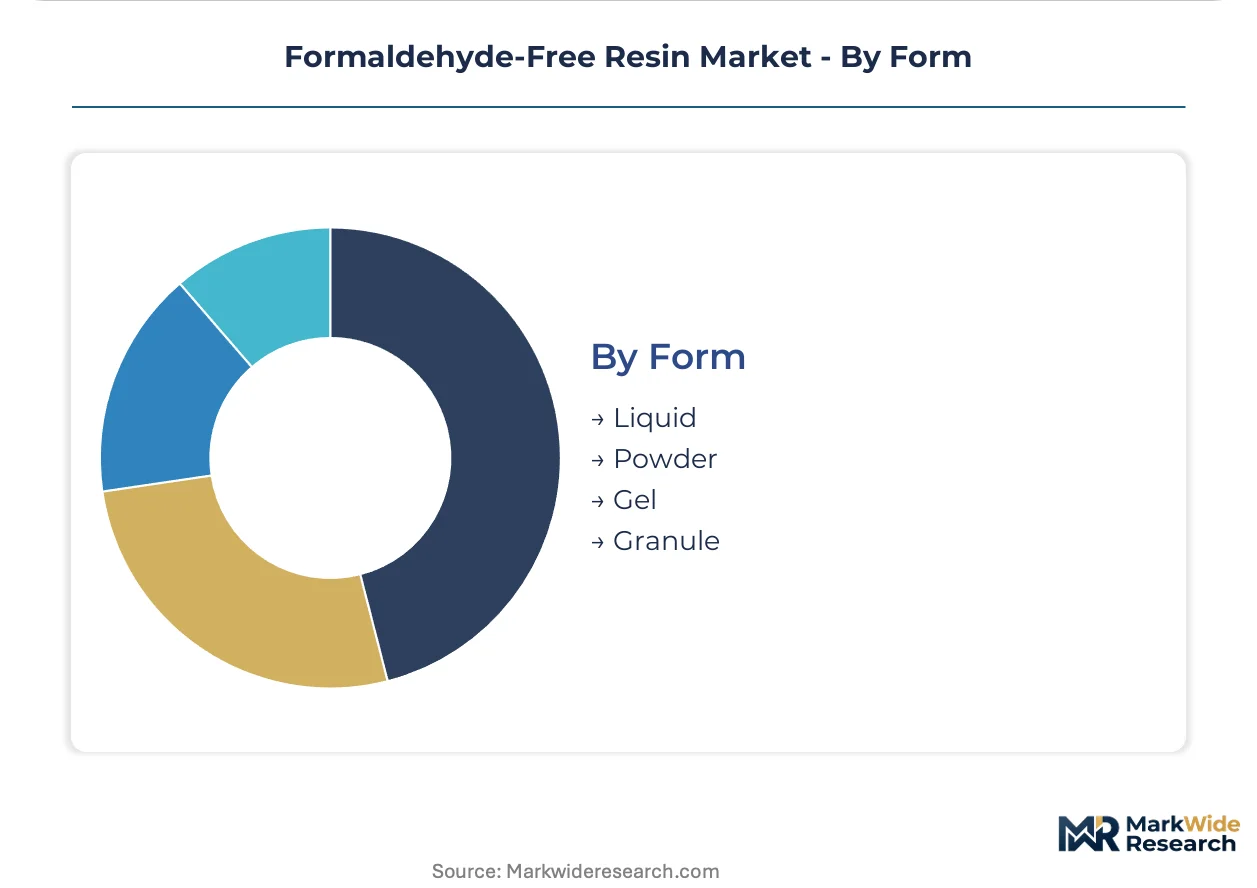
Form:
Supply chain configuration and customer handling infrastructure segment this category by operational compatibility.
- Liquid:Pumpable dispersions and solutions dominate continuous manufacturing processes in automotive and furniture lamination. Water-based polyurethane dispersions are overtaking solvent-borne systems in German and US Midwest tier-one seating operations.
- Powder:Solid particulate resins enable hot-melt compounding and powder coating applications where solvent elimination is critical.
- Gel:Thixotropic formulations provide sag resistance in vertical joint applications and controlled flow in electronics potting.
- Granule:Free-flowing solid pellets support extrusion compounding and bulk handling in wood panel hot-press operations.
Liquid formulations carry the majority of throughput. Powder systems are gaining share fastest with tightening solvent emission regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions where regulatory arbitrage minimizes compliance cost burdens. Manufacturers reposition supply chains across compliance gradients, concentrating investment where emission standards remain binding but enforcement infrastructure permits operational scale.
United States
EPA TSCA Title VI and CARB Phase 2 emission ceilings compress the addressable market for conventional urea-formaldehyde binders. The Geismar petrochemical corridor in Louisiana anchors North American polyurethane resin output for automotive interior specifications. Tier-one seating suppliers across the US Midwest have converted procurement protocols to water-based alternatives since 2023.
Germany
Bauhaus and Passivhaus construction standards drive material specifications below 0.05 ppm VOC thresholds across residential and commercial building segments. ECHA REACH restrictions on formaldehyde classification as Category 1B carcinogen force immediate reformulation across European supply chains. The Ludwigshafen chemical complex sustains integrated polyurethane production for automotive and construction adhesive applications.
Japan
METI's Green Purchasing Act extends preferential procurement to buildings certified under CASBEE indoor environment criteria. Semiconductor packaging miniaturization accelerates demand for low-temperature cure acrylic formulations in electronics coatings. The Kanto region concentrates resin formulation capacity serving tier-one electronics manufacturers.
China
GB standards for indoor air quality in residential construction tighten emission limits on wood panel products. Dual carbon policy objectives redirect chemical industry investment toward bio-based aldehyde platforms. The Yangtze River Delta clustering of furniture manufacturing drives specification demand for compliant binders in export-oriented production.
India
BIS certification requirements for low-emission building materials gain traction in premium residential construction. The PLI scheme for chemical manufacturing incentivizes domestic capacity expansion in specialty resin segments. Maharashtra and Gujarat industrial corridors attract formulation investments targeting automotive and furniture export markets.
Formaldehyde-Free Resin Market Vendor Landscape
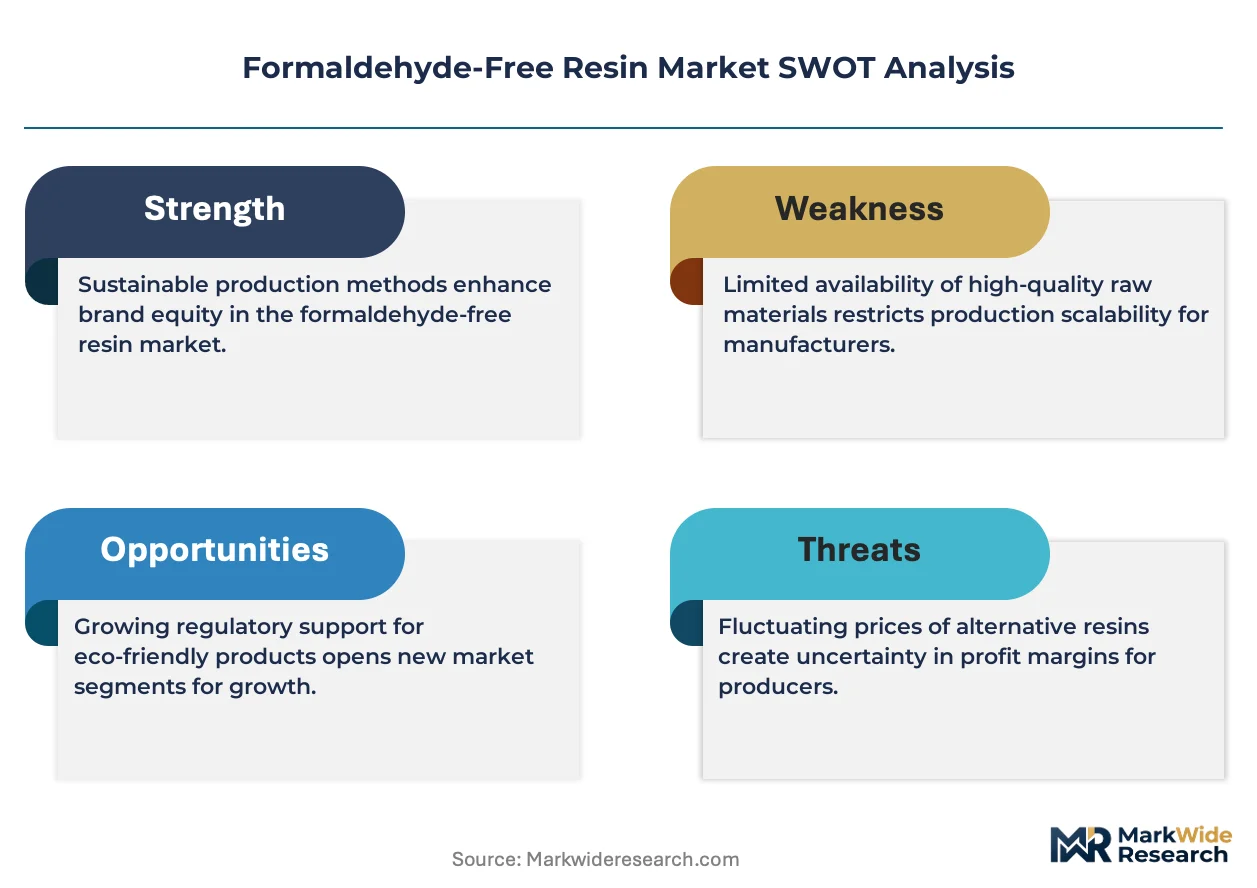
Established producers occupy the standard tier; emerging entrants pursue bio-based aldehyde alternatives and hybrid synthetic formulations. The vendor base stratifies across three maturity tiers: integrated petrochemical majors with captive isocyanate supply, regional specialists in application-specific formulations, and venture-backed bio-platform developers. Market structure rewards documentation infrastructure and pre-certified formulation portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as producers secure feedstock access and qualification timelines.
Among integrated chemical majors, BASF SE exemplifies the scale-driven archetype through its Ludwigshafen manufacturing complex. Huntsman Corporation anchors North American supply positioning from its Louisiana operations. DIC Corporation occupies a specialist position in Asian electronics coatings with acrylic formulation expertise. These three represent distinct competitive postures: petrochemical integration, regional supply security, and application-specific technical service.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman Corporation |
| DIC Corporation |
| Sika AG |
| Ashland Global Holdings |
| Hexion Inc. |
| Dynea AS |
| SI Group Inc. |
| Mitsubishi Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CARB Phase 2-compliant formulations and economy-tier bio-based alternatives manifests in both margin structures and raw material sourcing patterns. Premium polyurethane systems command channel leverage through pre-qualified documentation portfolios, while commodity acrylics compete on polyol feedstock arbitrage across German and US Gulf Coast supply nodes.
Pricing Analysis
Distributor margin compression in European construction supply chains is intensifying as REACH documentation costs concentrate volume among integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates pre-certified automotive formulations from provisional construction binders. Price differentiation hinges on VOC certification tier and captive isocyanate supply. Tier-one furniture manufacturers in California exhibit lowest price sensitivity due to regulatory lock-in, while Southeast Asian export processors face acute cost pressure from dual carbon compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with MDI isocyanate supply concentrated in Germany, Belgium, and the US Gulf Coast. Lignin-derived polyol alternatives draw from Nordic pulp mill integration, while conventional aromatic inputs rest on benzene-toluene-xylene refining in Rotterdam and Singapore. Tariff exposure on Chinese epoxy resin imports threatens electronics coating formulators. Distribution runs through regional chemical distributors serving tier-one automotive seating clusters in Bavaria and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formaldehyde-free resin demand is shifting toward pre-certified specification packages as building certification systems displace conventional procurement criteria, compressing volume toward documentation-heavy integrated suppliers.
For Market Incumbents: To counter margin erosion from bio-based aldehyde entrants, BASF and Huntsman should deepen captive isocyanate integration at Ludwigshafen and Geismar respectively, while accelerating parallel EPA TSCA Title VI and REACH dossier maintenance to extend qualification timelines for challengers. For New Entrants and Emerging Players: Digital specification platforms serving Passivhaus architects in Germany represent the most penetrable channel, bypassing incumbent distributor relationships. Target Polish and Romanian wood panel producers facing German distribution access barriers with hybrid lignin-polyurethane formulations and bundled certification support. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap acrylic specialists holding semiconductor packaging qualifications. Five-to-ten-year viability favors producers with dual US-European regulatory infrastructure. The inflection signal to monitor is tier-one automotive OEM unbundling of adhesive procurement from laminate purchasing, which would redirect volume toward direct resin relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | BASF's Ludwigshafen complex secures MDI feedstock for automotive sealant formulations against petrochemical volatility. |
| Green Manufacturing Transition | Lignin-derived polyol platforms align with EU Green Deal bio-content mandates for construction adhesive specifications. |
| Long-term Supply Agreement | Huntsman's Geismar anchoring binds tier-one seating suppliers in Michigan through water-based polyurethane offtake commitments. |
| Joint Venture | Nordic pulp mill partnerships enable bio-based aldehyde scale without greenfield petrochemical capital exposure. |
| Capacity Expansion | Acrylic dispersion additions in Kanto serve semiconductor miniaturization demand from Japanese electronics manufacturers. |
Methodological Framework
Direct dialogue with polyurethane plant managers, automotive procurement leads at tier-one seating suppliers, construction adhesive distributors, and ECHA regulatory affairs specialists grounded the qualitative framework. Secondary validation drew from EPA TSCA Title VI compliance filings, ACC resin production surveys, REACH substance dossiers, and customs trade data for isocyanate and polyol flows. Bottom-up segment sizing triangulated against top-down chemical industry capacity assessments.
Bottom-up modeling of chemistry platform volumes across adhesives, coatings, composites, and sealants converged with top-down construction and automotive production forecasts over the projection horizon. Segmentation dimensions included resin chemistry type, end-use industry tier, formulation form, and regional regulatory cluster. CAGRs derived from elasticity-adjusted substitution rates of formaldehyde-containing binders against compliance deadline schedules and feedstock cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for lignin-derived polyol commercialization would alter the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and petrochemical feedstock correlation structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Global Synthetic Polymers Market