
 Polymer Plastic Plain Bearings Market | 2026-2036
Polymer Plastic Plain Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Plastic Plain Bearings Market Intelligence
Asset-light leasing models for precision manufacturing equipment are narrowing the capital barrier for mid-tier competitors entering polymer bearing fabrication. Igus GmbH leverages its vertically integrated resin-to-bearing production to sustain margin control across European automation markets. SKF Group anchors its position through captive R&D in high-temperature polymer formulations. Saint-Gobain Performance Plastics differentiates via specialized FDA-compliant bearing lines serving North American food processing OEMs.
Polymer plastic plain bearings are self-lubricating, low-friction rotational or sliding elements molded from engineered thermoplastics such as polytetrafluoroethylene, polyether ether ketone, or ultra-high molecular weight polyethylene, typically operating without external lubrication at temperatures from -200°C to 250°C depending on base resin. These bearings serve primarily to reduce maintenance intervals, eliminate grease contamination, and extend service life in machinery where metal-to-metal contact would fail from corrosion or lubricant starvation. Self-lubricating grades dominate volume due to their penetration across automotive and conveyor applications where grease-free operation is mandatory. High-temperature formulations represent the fastest-expanding margin pool as aerospace and electric vehicle thermal management requirements intensify. FDA-compliant bearings occupy a defensible niche with concentrated demand from medical device and food equipment manufacturers facing strict surface-contact regulations.
REACH substance restrictions in the European Union and EPA toxicity evaluations in the United States are reshaping permissible filler chemistries and lubricant additives in polymer bearing compounds. FDA 21 CFR compliance requirements govern direct food-contact bearing surfaces in North American processing equipment, while China's GB standards and evolving MEE environmental directives influence resin selection for export-bound production. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that could erode the cost advantage polymer bearings hold against metal alternatives.
Market Dynamics
Electric powertrain thermal management requirements are compressing development cycles for high-temperature polymer formulations as automotive OEMs eliminate external lubrication systems from drivetrain assemblies.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving SVHC candidate list accelerates substitution of metal bearings with PTFE and PEEK alternatives in European automation equipment.
- Food processing OEMs:FDA 21 CFR compliance mandates for direct food-contact surfaces expand procurement of self-lubricating grades across North American packaging and handling machinery.
- Guangdong precision clusters:Concentrated demand from electronics assembly and semiconductor equipment manufacturers drives localized compound formulation capabilities.
Market Restraints
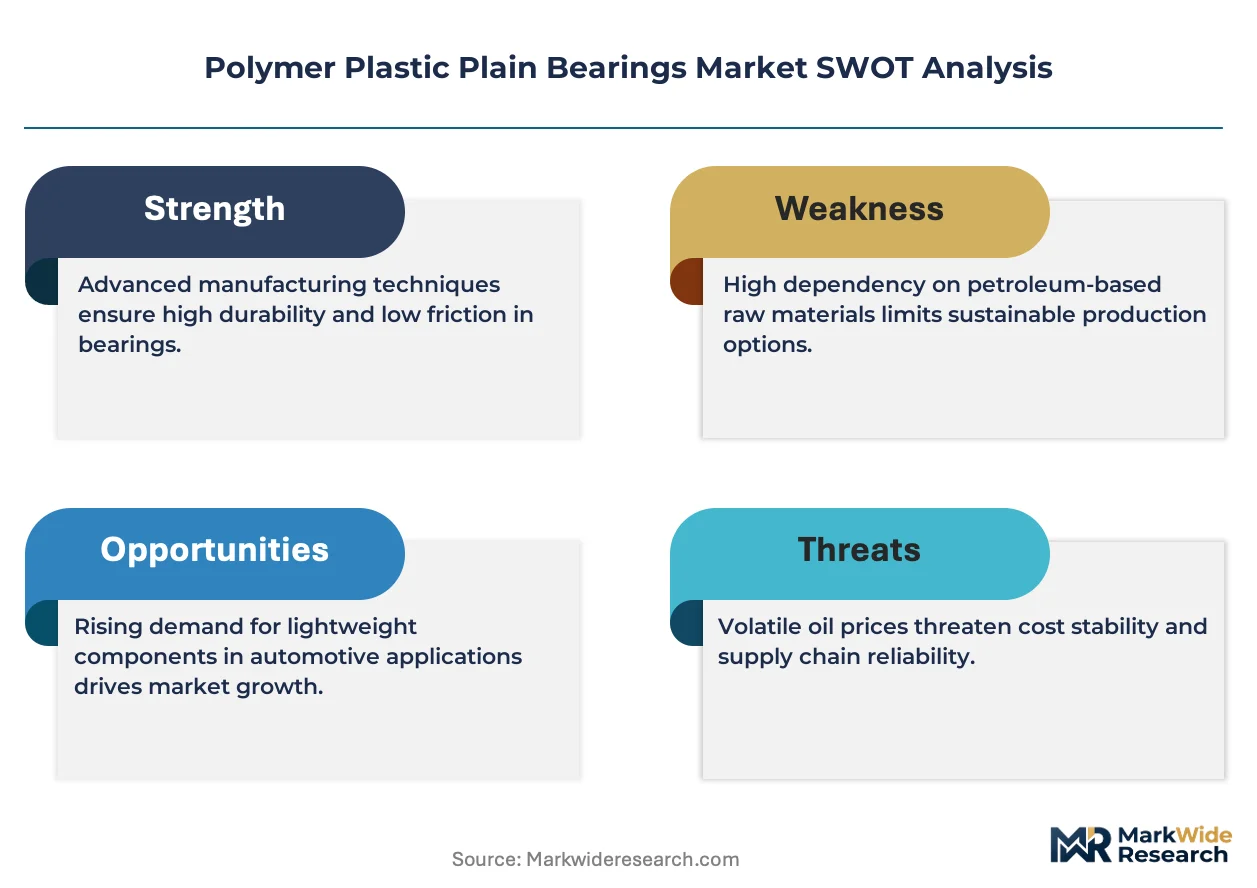
- Resin cost volatility:Fluctuating prices for virgin PEEK and PTFE feedstocks compress margins for compounders lacking backward integration into polymer production.
- Specialized tooling requirements:Multi-cavity molds for thin-walled bearing geometries demand capital outlays that deter mid-tier fabricators from high-volume automotive contracts.
- Technical performance ceiling:Load-bearing capacity limitations above 150 MPa restrict penetration into heavy-haul mining and construction equipment segments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Incentivized domestic production of automation components creates localized demand for cost-optimized UHMW-PE bearing grades.
- Medical device miniaturization:Robotic surgical platforms require sub-millimeter precision bearings with ISO 10993 biocompatibility certification.
- Closed-loop recycling infrastructure:Post-industrial regrind streams for engineering thermoplastics enable circular material claims in sustainability-focused procurement.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tribology and filler-matrix interaction commands premium compensation that strains R&D budgets at emerging compounders.
- Cross-jurisdictional compliance:Divergent substance restrictions between REACH, EPA TSCA, and China's MEE directives multiply testing and documentation burdens for export-bound production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Plastic Plain Bearings Market |
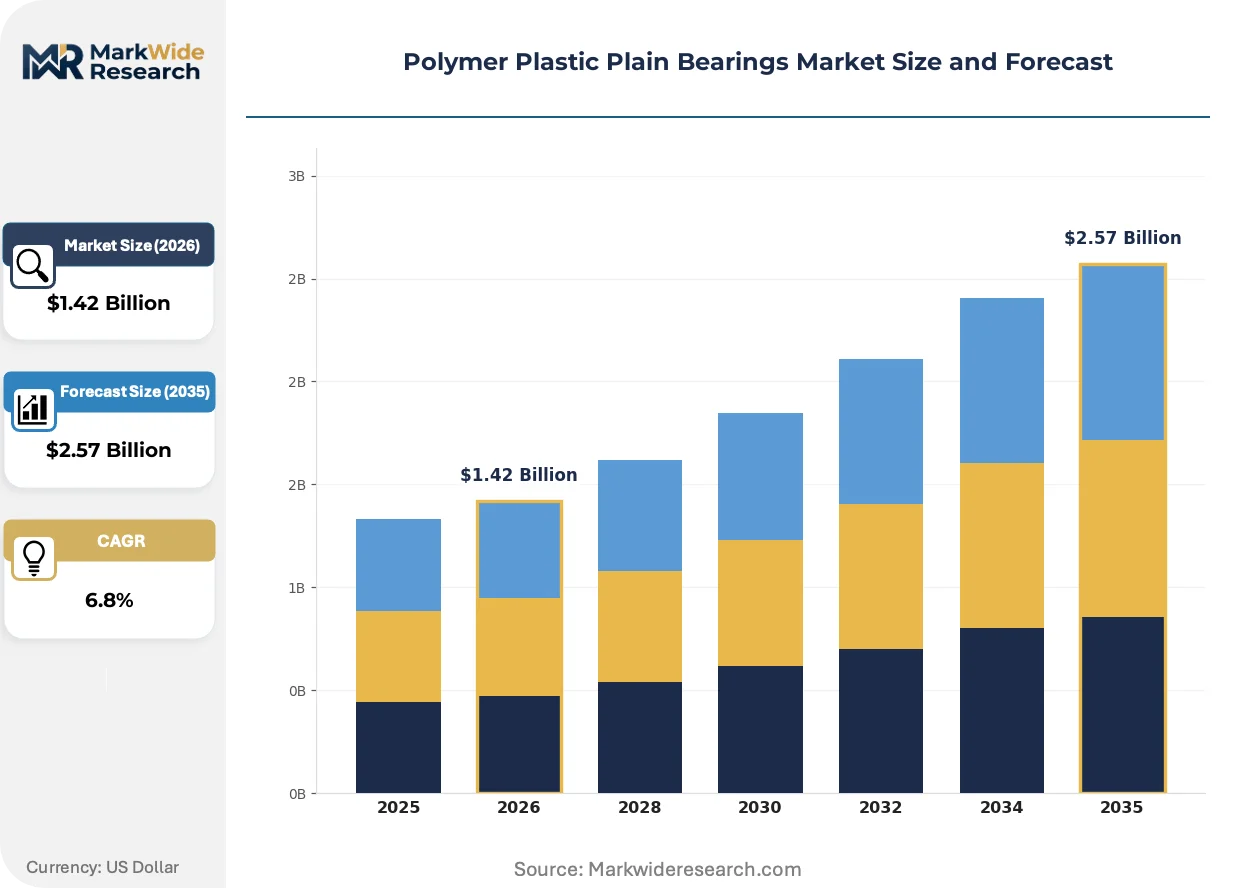
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Lubricating, High-Temperature, FDA Compliant, Specialty End User: Automotive, Aerospace, Food Processing, Medical Devices Application: Power Transmission, Automation, Conveyor Systems, Robotics Technology: Injection Molding, 3D Printing, Machining, Extrusion |
| Companies Covered | Igus GmbH, SKF Group, Saint-Gobain Performance Plastics, NSK Ltd., NTN Corporation, Schaeffler AG, GGB Inc., Regal Rexnord Corporation, Oiles Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Plastic Plain Bearings Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are converging to redefine performance benchmarks and supplier qualification protocols across bearing applications.
Continuous fiber-reinforced thermoplastic compounds are migrating from prototype aerospace brackets into production electric vehicle battery tray assemblies. Tier-1 automotive suppliers in Germany and Japan specify these grades for their specific stiffness-to-weight ratios and galvanic corrosion immunity. The technology is migrating from premium niche applications toward cost-competitive high-volume platforms as compression molding cycle times compress below ninety seconds.
EPA toxicity evaluations under TSCA Section 6 are restricting legacy perfluoroalkyl substance lubricant additives in polymer bearing compounds. Compounders must reformulate with approved alternatives or face import barriers into US-manufactured equipment. Medical device and food processing OEMs face the tightest compliance windows as FDA aligns with state-level PFAS prohibitions.
Asset-light leasing arrangements for precision injection molding cells are fragmenting the supplier base. Mid-tier fabricators in Bavaria and Michigan access high-cavitation tooling without capital commitment, compressing traditional volume discounts from integrated producers. This model concentrates most visibly among automotive tier-2 suppliers seeking flexible capacity for electric powertrain bearing programs.
Polymer Plastic Plain Bearings Market Segmentation
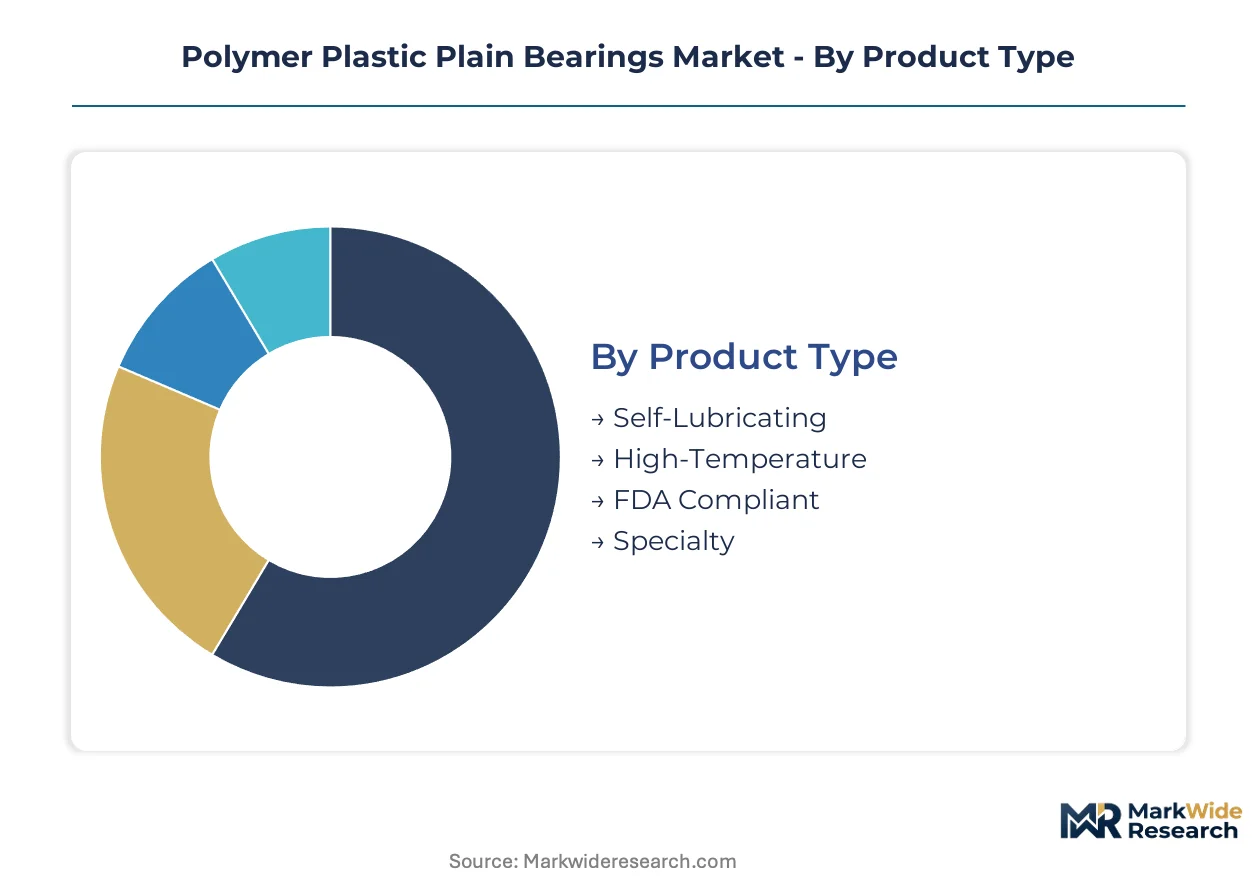
Polymer plastic plain bearings fragment across four critical dimensions that determine procurement cycles, margin profiles, and technical qualification requirements. Each segmentation axis reveals distinct velocity patterns—some segments turn inventory quarterly while others lock into multi-year platform contracts.
Product Type:
Cycle times vary dramatically: self-lubricating grades rotate inventory fastest due to automotive volume contracts, while FDA-compliant lines endure 18-month qualification cycles before food OEMs approve supplier changes.
- Self-Lubricating:PTFE-impregnated or solid-lubricant-filled compounds eliminate external grease systems. German and Japanese automotive OEMs specify these for electric powertrain assemblies where maintenance access is restricted. REACH substance restrictions accelerate substitution from metal bearings in European automation equipment.
- High-Temperature:PEEK and polyimide-based formulations withstand continuous operation above 200°C. Aerospace thermal management and electric vehicle battery tray applications in Germany and Japan concentrate procurement. EPA toxicity evaluations under TSCA Section 6 are restricting legacy lubricant additives, forcing reformulation.
- FDA Compliant:Materials certified under FDA 21 CFR for direct food-contact surfaces.
- Specialty:Custom-compounded grades for nuclear, cryogenic, or chemically aggressive environments.
Self-lubricating grades anchor the volume base while high-temperature formulations gain share at the steepest rate.
End User:
Cost tiers stratify sharply: automotive buyers negotiate platform-scale pricing with 3-5 year visibility, while medical device OEMs absorb premium pricing for biocompatibility certification and lot traceability.
- Automotive:Electric powertrain assemblies, chassis systems, and interior mechanisms. Michigan and Guangdong Province house concentrated demand from tier-1 suppliers eliminating external lubrication from drivetrain designs.
- Aerospace:Flight control surfaces, landing gear, and engine ancillary systems. Continuous fiber-reinforced thermoplastic compounds migrate from prototype brackets into production battery tray assemblies.
- Food Processing:Packaging machinery, conveying equipment, and processing lines requiring direct food-contact compliance.
- Medical Devices:Robotic surgical platforms and diagnostic equipment demanding sub-millimeter precision with ISO 10993 biocompatibility certification.
Automotive procurement anchors the volume base while medical devices expand at the steepest trajectory due to miniaturization requirements.
Application:
Volume concentration tracks manufacturing automation intensity: power transmission and conveyor systems serve mature industrial bases, while robotics applications climb fastest alongside precision automation cluster expansion.
- Power Transmission:Gearboxes, linkages, and rotational drive systems in industrial machinery.
- Automation:Linear motion systems, pick-and-place mechanisms, and precision positioning equipment. Bavaria's electronics assembly and semiconductor equipment manufacturers drive localized compound formulation capabilities.
- Conveyor Systems:Material handling, packaging lines, and distribution center sortation equipment. FDA 21 CFR compliance mandates expand procurement of self-lubricating grades across North American packaging machinery.
- Robotics:Articulated arm joints, end-effector bearings, and collaborative robot pivot points.
Conveyor systems anchor the volume base while robotics climbs fastest alongside precision automation deployment.
Technology:
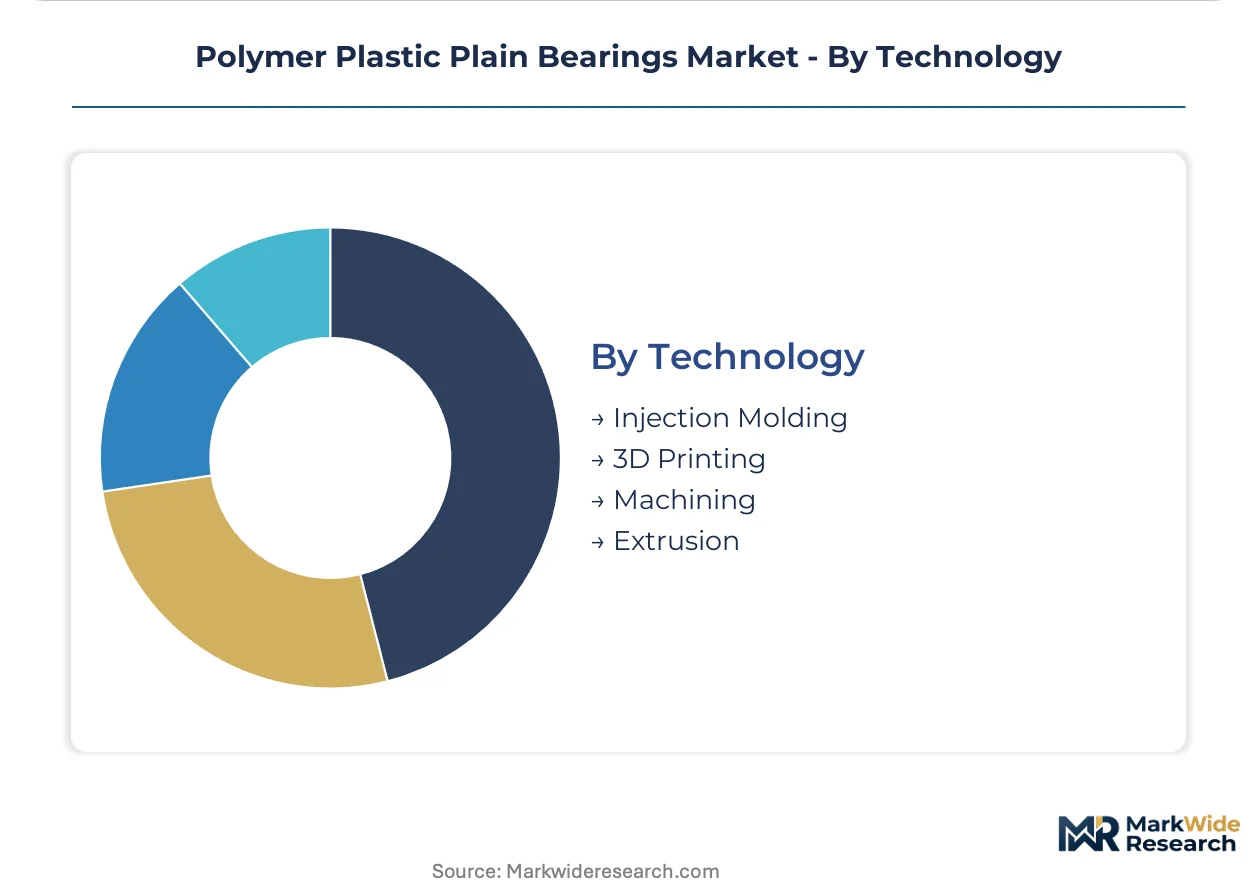
Capital barriers and tooling amortization periods segment the supplier landscape: injection molding demands multi-cavity mold investments that deter mid-tier entrants, while 3D printing enables prototype-to-production transitions without tooling commitment.
- Injection Molding:High-cavitation production of thin-walled bearing geometries. Asset-light leasing arrangements in Bavaria and Michigan fragment the supplier base by enabling mid-tier fabricators to access precision tooling without capital commitment.
- 3D Printing:Fused filament fabrication and selective laser sintering for complex geometries and low-volume production.
- Machining:CNC turning and milling of rod and plate stock for precision tolerances.
- Extrusion:Continuous profile production for bushings and sleeve bearings.
Injection molding anchors the volume base while 3D printing expands most quickly for prototype-to-production transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and regulatory chemistry restrictions are redrawing procurement geography. Automotive electrification mandates, environmental compliance deadlines, and precision manufacturing cluster formation concentrate demand in specific national markets.
Germany
Electric powertrain thermal management requirements from BMW, Volkswagen, and Mercedes-Benz accelerate high-temperature PEEK bearing adoption. ECHA's REACH SVHC candidate list forces compounders to eliminate legacy lubricant additives from formulations. Bavaria's automation equipment manufacturers in Munich and Nuremberg drive localized resin-to-bearing production capabilities.
United States
EPA toxicity evaluations under TSCA Section 6 restrict perfluoroalkyl substance lubricants in polymer compounds destined for automotive and industrial applications. FDA 21 CFR compliance mandates expand procurement of food-contact bearing grades across North American packaging machinery. Michigan's tier-1 automotive suppliers in Detroit and Grand Rapids eliminate external lubrication from electric drivetrain designs.
China
Guangdong Province's electronics assembly and semiconductor equipment manufacturers generate concentrated demand for precision automation bearings. MEE environmental directives and evolving GB standards influence resin selection for export-bound production. Shenzhen and Dongguan house the fastest-growing regional cluster for localized compound formulation capabilities.
Japan
METI's carbon neutrality roadmap accelerates substitution of metal bearings with self-lubricating polymer alternatives in automotive and robotics applications. JIS standards govern dimensional tolerances for precision automation equipment. Toyota City and Nagoya's industrial corridor anchor procurement from domestic bearing fabricators serving electric vehicle programs.
India
The PLI scheme for manufacturing incentivizes domestic production of automation components, creating localized demand for cost-optimized UHMW-PE bearing grades. BIS standards increasingly align with international certification requirements for industrial machinery. Maharashtra's Pune and Nashik industrial belts attract compounders establishing regional formulation facilities.
Polymer Plastic Plain Bearings Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated resin producers and fragmenting among asset-light fabricators accessing leased precision tooling. Three archetypes dominate: integrated polymer-to-bearing manufacturers controlling raw material costs, specialized compounders serving FDA-compliant niches, and regional fabricators leveraging flexible capacity arrangements. Competitive moves center on backward integration into polymer production and geographic expansion through distributor partnerships.
Among European integrated manufacturers, Igus GmbH and Saint-Gobain Performance Plastics exemplify contrasting strategic positions. Igus anchors the resin-to-bearing archetype with captive polymer production, while Saint-Gobain occupies the regulatory-specialist tier through FDA-compliant bearing lines. SKF Group represents the diversified industrial incumbent archetype, leveraging established distribution networks across automotive and aerospace segments.
| Leading Market Players |
|---|
| Igus GmbH |
| SKF Group |
| Saint-Gobain Performance Plastics |
| NSK Ltd. |
| NTN Corporation |
| Schaeffler AG |
| GGB Inc. |
| Regal Rexnord Corporation |
| Oiles Corporation |
| Others |
Cost & Logistics Intelligence
German resin compounders anchor upstream supply for European polymer bearing fabrication, concentrating margin capture among integrated producers while mid-tier fabricators in Bavaria and Michigan absorb cost volatility through leased tooling arrangements.
Pricing Analysis
Certification level (FDA-grade versus industrial-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects REACH compliance burden and biocompatibility testing depth. Cost compression in standard industrial grades is intensifying because asset-light leasing models fragment supplier pricing power. Automotive tier-1 buyers exhibit lowest price sensitivity due to platform-scale contracts, while mid-tier automation OEMs drive hardest bargain terms.
Supply Chain Analysis
Export-control restrictions on advanced polymer formulations and continuous fiber-reinforced compounds limit technology transfer between jurisdictions. Supply concentrates in Germany, Japan, and China for virgin PEEK and PTFE feedstocks. Fabrication draws from specialized multi-cavity molds, resin-to-bearing integration capabilities, and precision machining cells. Single-source vulnerability runs through German resin compounders serving automotive qualification programs. Distribution runs through tier-1 automotive supplier networks and industrial distributor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as electric powertrain thermal requirements splinter demand across high-temperature, self-lubricating, and FDA-compliant niches, each demanding distinct formulation expertise and qualification timelines.
For Market Incumbents: Entrench platform-scale relationships with German and Japanese automotive OEMs through captive R&D in high-temperature polymer formulations. Deepen backward integration into resin production to offset virgin PEEK cost volatility threatening margin stability. Prioritize REACH-compliant additive portfolios ahead of ECHA SVHC list expansions.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized automation component manufacturing, where cost-optimized UHMW-PE grades face limited domestic competition. Target medical device miniaturization segments requiring ISO 10993 certification, as incumbent qualification cycles create entry windows. Pursue distributor partnerships with Bavarian precision automation clusters rather than direct OEM confrontation.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated resin-to-bearing manufacturers with REACH-compliant formulation libraries and automotive platform qualifications. The five-to-ten year viability window favors assets with backward integration into polymer production over pure-play fabricators exposed to feedstock volatility. Monitor EPA TSCA Section 6 enforcement intensity as inflection signal for reformulation cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive PEEK and PTFE supply shields margin from virgin feedstock price swings. |
| FDA 21 CFR Certification Investment | Direct food-contact bearing qualification unlocks North American packaging machinery procurement. |
| High-Temperature Formulation R&D | PEEK and polyimide development addresses electric vehicle battery tray thermal requirements. |
| Asset-Light Leasing Partnerships | Precision injection molding cell access enables mid-tier fabricators without capital commitment. |
| Regional Compound Formulation Facilities | Localized production in Guangdong and Maharashtra reduces logistics costs and tariff exposure. |
Research Approach
Desk research of customs trade databases, ECHA regulatory filings, and automotive production statistics preceded structured interviews with polymer compounders, tier-1 automotive procurement managers, precision automation equipment engineers, and FDA regulatory consultants. Primary fieldwork across Bavaria, Michigan, and Guangdong Province validated secondary estimates of localized demand concentration. Bottom-up bearing volume estimates triangulated against top-down polymer resin consumption data.
Assumptions held fixed include REACH SVHC list evolution trajectory, EPA TSCA Section 6 enforcement timeline, and electric vehicle powertrain thermal management specifications across the projection horizon. Segmentation modeling spanned product type, end user industry, application, and manufacturing technology dimensions. CAGRs derived from regression analysis of historical polymer bearing adoption rates against automotive electrification and automation intensity indices.
Stress conditions across resin cost volatility bands, regulatory compliance timeline compression, and automotive platform qualification failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including PFAS additive prohibitions and single-source resin supply disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market