
 Europe Polyvinyl Chloride (PVC) Market | 2026-2036
Europe Polyvinyl Chloride (PVC) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyvinyl Chloride (PVC) Market Foresight
Modular piping configurations for building infrastructure is repositioning procurement patterns across European construction supply chains. INEOS Group leverages integrated chlor-alkali assets to sustain feedstock cost advantages across its continental manufacturing footprint. VESTOLIT anchors its competitive stance through specialized suspension-grade resins tailored to German automotive specifications. Kem One dominates Mediterranean markets with backward integration into chlorine production and port-adjacent logistics.
Polyvinyl chloride is a thermoplastic polymer synthesized from vinyl chloride monomer through suspension, emulsion, or bulk polymerization, typically containing 56.7% chlorine by mass and exhibiting Shore hardness ranging from 65A to 85D depending on plasticizer loading; its primary industrial purpose spans rigid pressure piping, flexible medical tubing, wire insulation, and weather-resistant building profiles. Rigid PVC commands the dominant volume share across European construction applications due to its superior tensile strength and flame-retardant properties, while flexible PVC captures expanding margin pools in medical device and automotive interior segments where phthalate-free formulations command specification premiums. Suspension polymerization remains the prevailing manufacturing technology, though emulsion routes gain traction in specialty paste resin applications for coated fabrics and flooring.
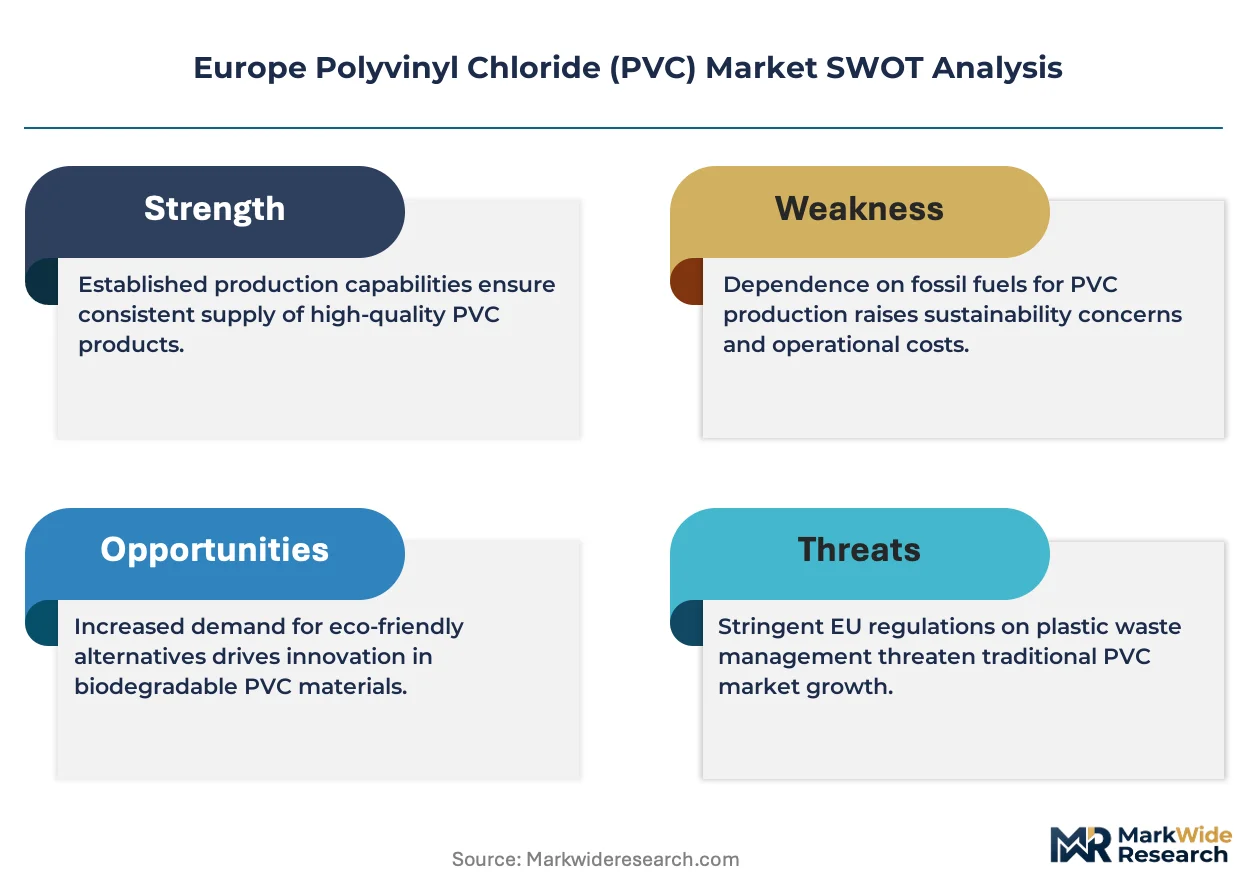
The EU Green Deal and REACH frameworks are tightening additive restrictions and accelerating substitution timelines for legacy plasticizers across all PVC formulations sold within the single market. ECHA's persistent organic pollutant assessments and the F-Gas Regulation's indirect pressure on chlorinated supply chains are reshaping raw material sourcing requirements for compounders. EMA and national health regulators in France and Germany are elevating medical-grade PVC purity standards, constraining import access for non-certified Asian suppliers. Stakeholders must monitor the interplay between EU carbon border adjustments and domestic recycling infrastructure buildout to anticipate cost structure shifts.
Market Dynamics
REACH additive restrictions and EU Green Deal chemical phase-down timelines are compressing formulation choices while simultaneously creating premium tiers for compliant bio-based alternatives across European compounding operations.
Growth Catalysts
- Sustainable piping infrastructure:German and French construction codes now mandate recycled content thresholds in municipal water systems, pulling suspension-grade resin volumes into certified supply chains.
- REACH plasticizer substitution mandates:Legacy phthalate restrictions under ECHA persistent organic pollutant assessments are forcing compounders toward bio-based alternatives with superior thermal stability profiles.
- Medical-grade purity escalation:EMA and ANSM elevated extractables testing protocols for blood-contact tubing, disqualifying non-certified Asian suppliers from French and German hospital procurement.
Market Restraints
- Chlor-alkali feedstock concentration:Electrolysis capacity clusters along the German Rhine and Rotterdam Antwerp corridor expose compounders to regional energy price spikes and force majeure risks.
- Legacy formulation lock-in:Decades-old building infrastructure specifications in Southern Europe reference obsolete additive packages that conflict with current REACH authorization lists.
- Concrete and cross-linked polyethylene substitution:Pressure piping specifications in Nordic municipal tenders increasingly specify ductile iron or PEX-A for hot-water distribution networks.
Strategic Opportunities
- Benelux recycling infrastructure:Port-adjacent chemical recycling clusters in Antwerp and Rotterdam offer integrated VCM recovery from post-consumer construction waste at scale unmatched elsewhere in Europe.
- Automotive interior air-quality mandates:KBA emission testing protocols for cabin materials create specification premiums for ultra-low-VOC flexible formulations in German OEM supply chains.
- CSRD supply-chain disclosure requirements:Corporate sustainability reporting obligations are forcing construction majors to document polymer provenance, advantaging integrated producers with certified mass-balance systems.
Industry Challenges
- Phthalate-free formulation chemistry:Replacement plasticizers for medical-grade applications require revalidation of entire extrusion parameter sets, extending qualification timelines by 18-24 months.
- Certification fragmentation across member states:French CSTB, German DIBt, and Italian UNI maintain non-harmonized fire-performance testing protocols for building profiles, multiplying compliance costs for pan-European product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyvinyl Chloride (PVC) Market |
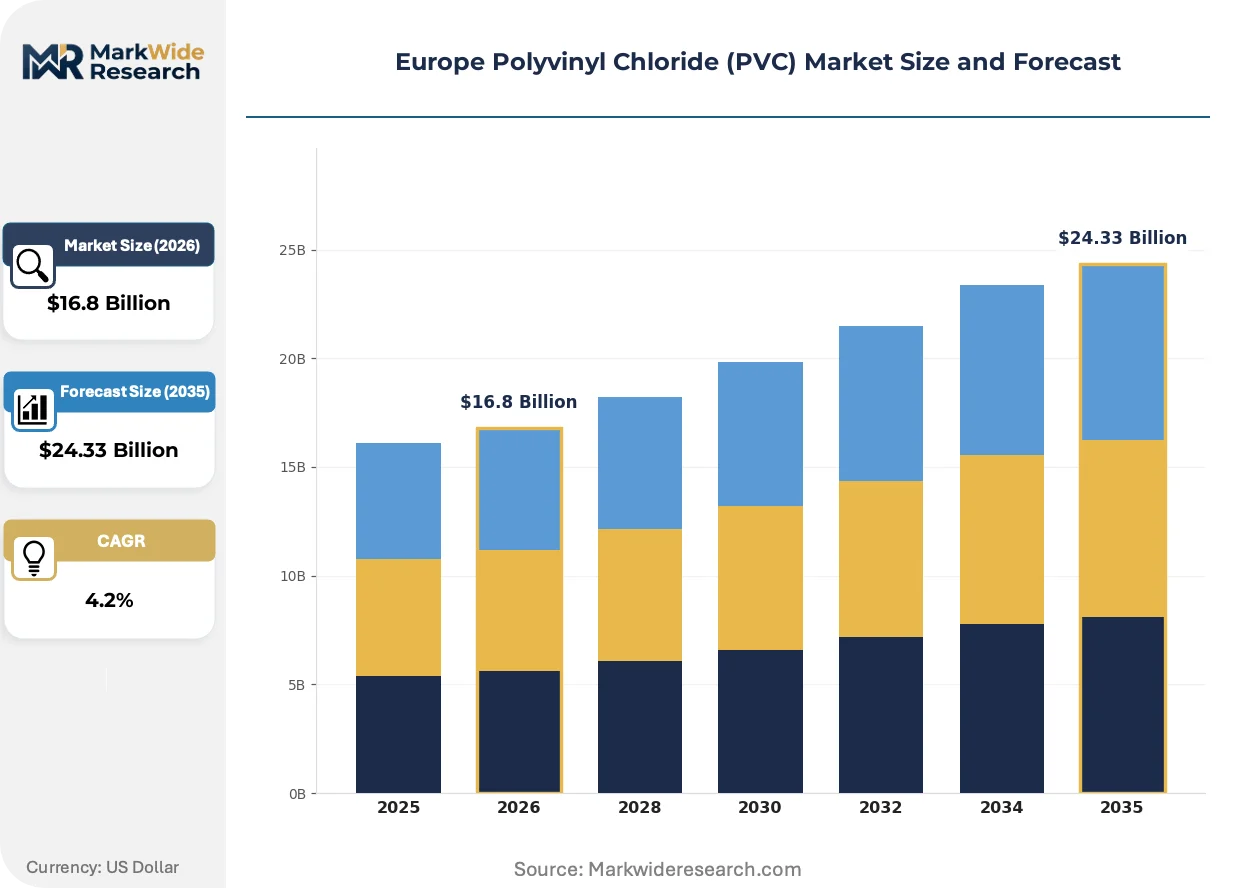
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $24.33 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, PVC Foam, PVC Film Application: Construction, Packaging, Automotive, Electrical End User: Manufacturers, Contractors, Retailers, Distributors Technology: Suspension Polymerization, Emulsion Polymerization, Bulk Polymerization, Solution Polymerization |
| Companies Covered | Kem One, BorsodChem, INEOS Group, Arkema, VESTOLIT, INOVYN, Vinnolit, Shin-Etsu Chemical, Solvay, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyvinyl Chloride (PVC) Market Shifts & Advancements
Digital mass-flow metering and real-time rheology control are compressing batch-to-batch variation in suspension polymerization trains, enabling tighter specification windows for automotive and medical buyers.
Continuous inline spectroscopy is automating vinyl chloride residual detection during stripping operations, allowing Antwerp and Rotterdam producers to guarantee sub-ppm monomer levels without offline laboratory holds. German automotive compounders are adopting these systems fastest, using the data to negotiate premium tier pricing against Southern European competitors still running statistical sampling protocols.
ECHA's 2024 update to Substances of Very High Concern candidate list is forcing reformulation of heat-stabilizer packages across all European rigid profile extrusion, with calcium-zinc systems displacing legacy tin and lead options in outdoor building applications. Italian and Spanish producers face the steepest conversion costs due to older calendar line configurations optimized for traditional stabilizer rheology.
Construction procurement departments in France and Germany are consolidating polymer purchasing through digital platforms that benchmark real-time resin pricing against additive and freight components separately. Tier-one contractors in the Paris and Munich metropolitan areas now run monthly reverse auctions for certified recycled-content compounds, compressing margin pools for distributors who previously captured information asymmetry gains.
Europe Polyvinyl Chloride (PVC) Market Segmentation
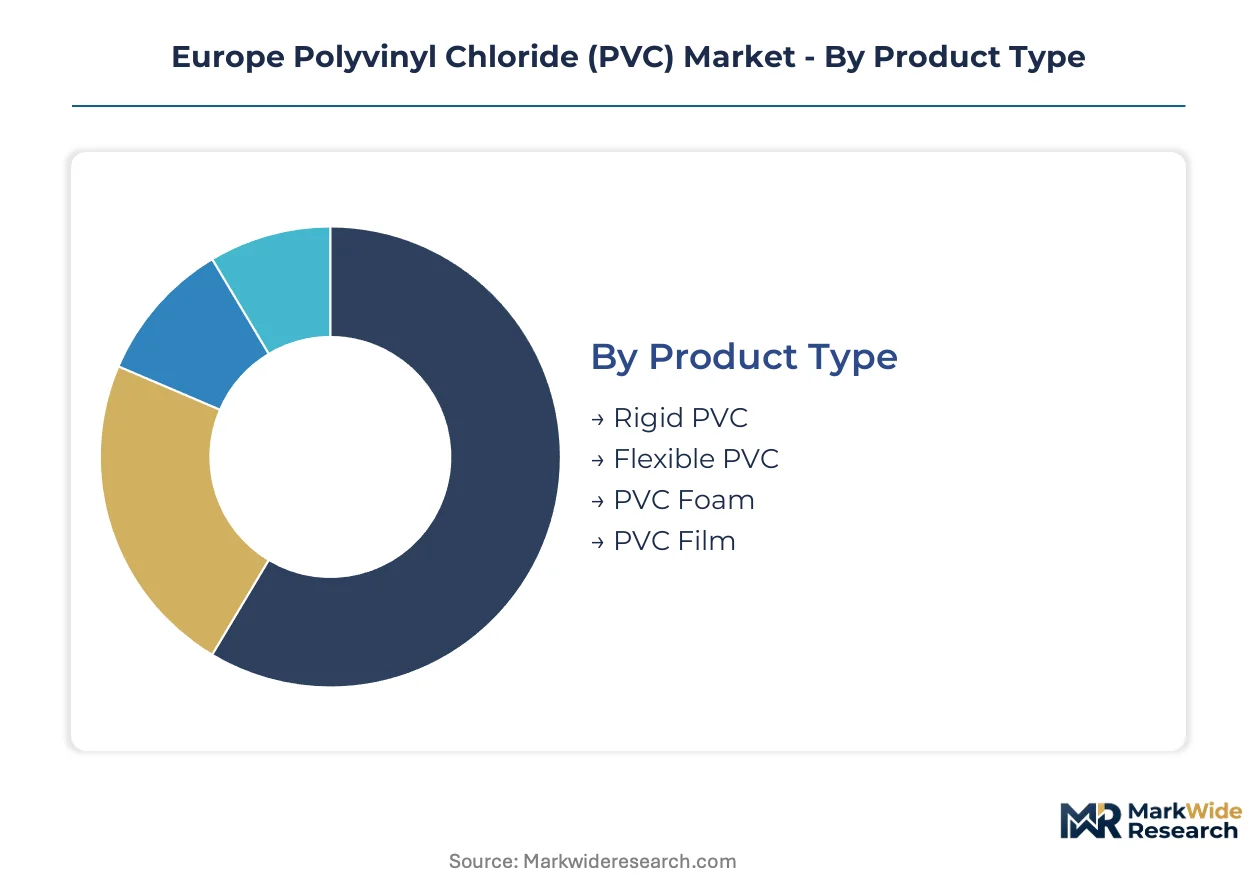
European PVC procurement increasingly separates commodity-grade volumes from specification-critical compounds where REACH compliance and recycled-content certification command price premiums. Segmentation discipline allows suppliers to align polymerization assets with diverging margin pools across construction, medical, and automotive qualification tiers.
Product Type:
Customization intensity spans from mass-volume suspension resins to engineered foam grades requiring precise cell-structure control.
- Rigid PVC:Unplasticized formulations containing zero external plasticizers deliver Shore D hardness above 80 and superior tensile strength for pressure-rated piping. German municipal water infrastructure mandates now specify recycled-content thresholds, pulling certified rigid compounds through Rotterdam-Antwerp supply chains.
- Flexible PVC:Plasticizer loadings between 15-50 phr enable Shore A hardness from 65-90 for medical tubing and automotive interior skins. EMA and ANSM extractables protocols are disqualifying non-certified Asian suppliers from French and German hospital procurement, tightening qualified supplier lists.
- PVC Foam:Cellular structures with controlled density gradients serve signage and display applications.
- PVC Film:Calendered or extruded sheet formats supply packaging and stationary end-uses.
Most installed capacity flows through Rigid PVC. Expansion is steepest in Flexible PVC.
Application:
Volume concentration versus margin capture divides construction commodity demand from automotive specification premiums.
- Construction:Pressure piping, window profiles, and roofing membranes consume the dominant resin share. German and French building codes now mandate recycled-content thresholds in municipal water systems, pulling suspension-grade volumes into certified supply chains.
- Automotive:Interior skins, wire harness insulation, and underbody coatings require ultra-low-VOC formulations. KBA emission testing protocols create specification premiums for compliant flexible compounds in German OEM supply chains.
- Packaging:Blister packs and shrink films serve pharmaceutical and consumer goods sectors.
- Electrical:Cable jacketing and conduit systems leverage flame-retardant properties.
Construction absorbs the greatest resin tonnage. Automotive commands the steepest price premiums per kilogram.
End User:
Channel structure separates direct mill relationships from distributor-captured specification influence.
- Manufacturers:Integrated compounders and extrusion houses purchase base resin for captive compounding operations. CSRD supply-chain disclosure requirements are forcing documentation of polymer provenance, advantaging producers with certified mass-balance systems.
- Contractors:Tier-one construction firms in Paris and Munich metropolitan areas now run monthly reverse auctions for certified recycled-content compounds, compressing distributor margins.
- Retailers:DIY channels move standardized building profiles and repair fittings.
- Distributors:Regional stockists bridge compounders with fragmented fabrication customers.
Manufacturers control the largest volume flows. Contractors are gaining procurement leverage fastest.
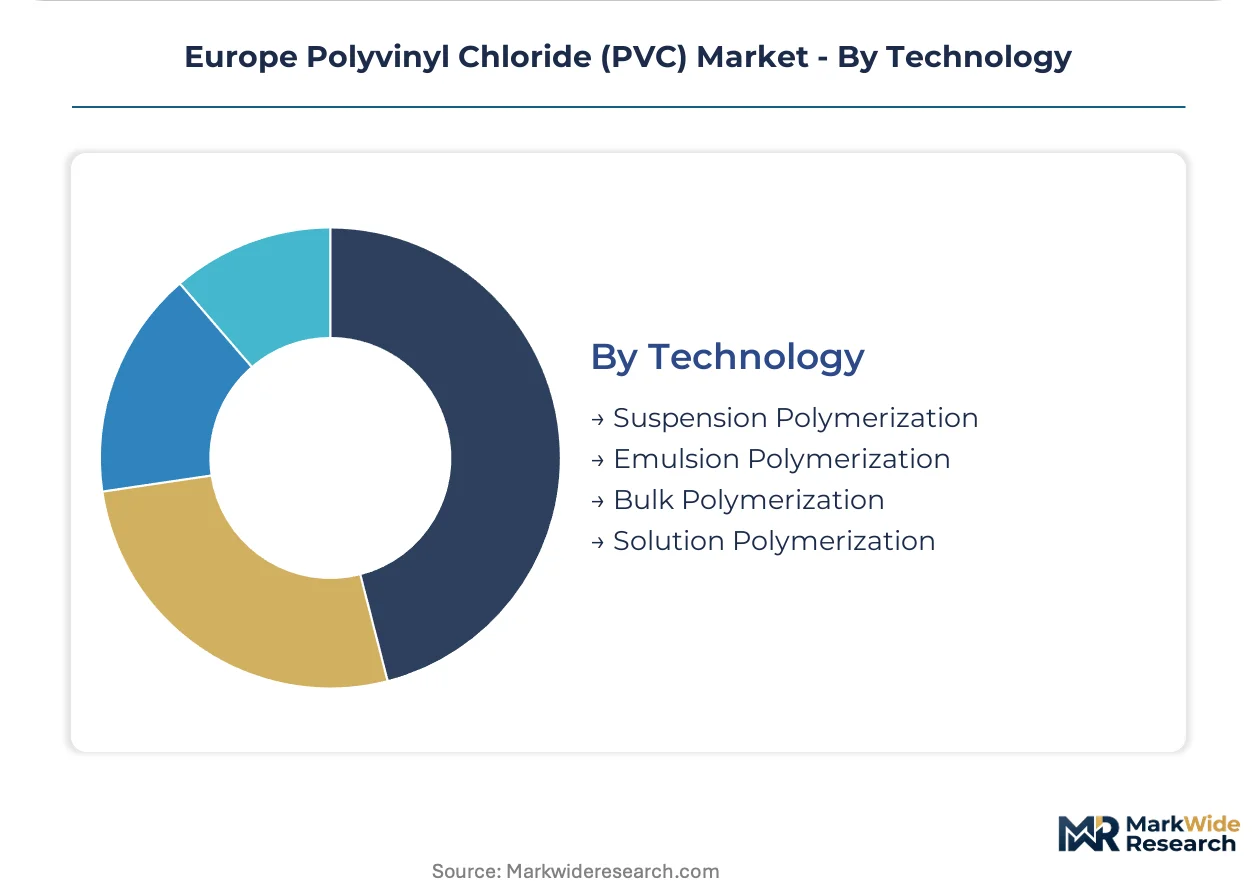
Technology:
Process economics and product granularity separate high-volume suspension trains from specialty emulsion routes.
- Suspension Polymerization:Dominant industrial process producing porous grains with controlled particle size distribution for general-purpose extrusion and injection molding. Digital mass-flow metering and real-time rheology control are compressing batch-to-batch variation, enabling tighter specification windows for automotive and medical buyers.
- Emulsion Polymerization:Produces fine paste resins for plastisol applications in coated fabrics and flooring. Specialty paste resin applications are gaining traction where surface finish requirements exceed suspension-grade capabilities.
- Bulk Polymerization:Solvent-free routes yield high-purity resins for optical and medical applications.
- Solution Polymerization:Niche process for ultra-high molecular weight specialty grades.
Suspension Polymerization anchors installed capacity. Emulsion Polymerization is climbing the fastest on specialty demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineers pioneered large-scale PVC suspension polymerization during the 1930s, establishing production templates that still dominate European manufacturing architecture today.
Germany
Rhine corridor chlor-alkali clusters feed integrated VCM-to-resin operations serving automotive and construction compounders. KBA cabin air-quality protocols mandate ultra-low-VOC flexible formulations for OEM interiors. The North Rhine-Westphalia industrial belt concentrates backward-integrated producers with captive chlorine electrolysis and pipeline-linked ethylene feedstock.
France
Municipal water infrastructure renewal drives specification-grade rigid resin demand across metropolitan networks. ANSM extractables testing protocols for blood-contact tubing disqualify non-certified Asian suppliers from hospital procurement. The Lyon-Grenoble chemical corridor hosts specialized compounders serving medical device and automotive Tier-1 customers.
Netherlands
Rotterdam port-adjacent logistics enable integrated VCM import and resin export across Atlantic and Rhine-Alpine corridors. EU Green Deal chemical phase-down timelines accelerate bio-based plasticizer adoption among Benelux compounders. The Antwerp chemical cluster anchors construction waste chemical recycling infrastructure with unmatched post-consumer PVC recovery scale.
Italy
Southern European building infrastructure specifications reference legacy additive packages conflicting with current REACH authorization lists. CSTB fire-performance testing protocols for building profiles multiply compliance costs for pan-European product lines. The Lombardy-Veneto manufacturing belt concentrates calendering operations for flooring and coated fabric applications.
Spain
Window profile and roofing membrane fabrication sustains commodity resin demand amid slower REACH compliance conversion. UNI fire-performance protocols diverge from German DIBt standards, fragmenting certification requirements. The Catalonia chemical corridor maintains older calendar line configurations optimized for traditional stabilizer rheology.
Europe Polyvinyl Chloride (PVC) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across REACH compliance certification and recycled-content mass-balance documentation. The vendor base clusters around three strategic archetypes: integrated chlor-alkali producers with captive VCM supply, specialized suspension-grade resin specialists serving automotive specifications, and Mediterranean-focused compounders leveraging port logistics. Dominant competitive moves include backward integration into chlorine electrolysis capacity and technology licensing for digital mass-flow metering systems.
Among integrated chemical conglomerates, INEOS Group and Arkema occupy positions defined by continental manufacturing footprints and diversified polymer portfolios. VESTOLIT exemplifies the specialized resin archetype through its focus on suspension-grade formulations. Kem One anchors the Mediterranean logistics tier with port-adjacent production serving Southern European construction markets. These three company structures illustrate how scale, specialization, and geographic positioning stratify competitive returns across the European PVC value chain.
| Leading Market Players |
|---|
| Kem One |
| BorsodChem |
| INEOS Group |
| Arkema |
| VESTOLIT |
| INOVYN |
| Vinnolit |
| Shin-Etsu Chemical |
| Solvay |
| Others |
Supply & Pricing Matrix
German automotive OEM procurement offices and French hospital purchasing committees concentrate demand for specification-grade compounds, anchoring a contract-based long-term offtake model that rewards certified mass-balance documentation with price premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified medical-grade compounds from commodity construction resins. Price differentiation rests on certification grade and volume scale, with bio-based plasticizer formulations commanding specification premiums. Cost compression in standard-tier rigid piping intensifies because contractor reverse auctions compress distributor margins. Municipal procurement teams exhibit highest price sensitivity; German automotive compounders show lowest sensitivity due to KBA air-quality mandates.
Supply Chain Analysis
Single-source vulnerability sits with chlor-alkali electrolysis capacity clustered along the German Rhine and Rotterdam-Antwerp corridor. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for integrated VCM-to-resin operations. Raw material dependencies hinge on ethylene feedstock, chlorine electrolysis output, and plasticizer additive packages. Tariff exposure on imported VCM from non-EU sources threatens cost structures. Distribution runs through port-adjacent chemical clusters with pipeline-linked compounder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal chemical phase-down timelines are reshaping formulation economics and pulling premium volumes into certified supply chains.
For Market Incumbents: Lock in backward integration into chlorine electrolysis capacity along the Rhine corridor to secure feedstock cost advantages against energy price volatility. Invest in digital mass-flow metering systems to compress batch-to-batch variation for automotive and medical qualification tiers. Defend against concrete and cross-linked polyethylene substitution in Nordic municipal tenders by accelerating recycled-content certification. For New Entrants and Emerging Players: Begin with specialty emulsion polymerization for medical-grade paste resin applications where EMA extractables protocols have disqualified non-certified Asian suppliers. Target the Lyon-Grenoble chemical corridor for medical device compounder relationships. Pursue a go-to-market angle built on phthalate-free formulation chemistry with pre-validated extrusion parameter sets. For Investors and Strategic Acquirers: Integrated chemical conglomerates with diversified polymer portfolios are the most active acquirer in this space, seeking specialized suspension-grade resin capabilities. Long-term viability over a multi-year horizon favors targets with port-adjacent logistics and chemical recycling infrastructure access. Watch for CSRD supply-chain disclosure requirements tightening as the signal for mass-balance certification premiums to widen.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorine Electrolysis | Captive VCM supply secures cost advantages against Rotterdam energy price spikes. |
| Digital Mass-Flow Metering Deployment | Real-time rheology control enables tighter specification windows for KBA-compliant automotive compounds. |
| Chemical Recycling Infrastructure Buildout | Antwerp and Rotterdam clusters offer unmatched post-consumer PVC recovery scale for circular supply chains. |
| Bio-Based Plasticizer Formulation Investment | ECHA persistent organic pollutant assessments are displacing legacy phthalates with thermal-stable alternatives. |
| REACH Certification Acceleration | EMA and ANSM elevated extractables protocols disqualify non-certified suppliers from hospital procurement. |
Research Methodology
Multiple input streams — technical discussions with plant managers and procurement leads at downstream construction OEMs, regulatory consultations with ECHA and national competent authorities, and validation sessions with distribution channel partners — were reconciled against customs data, Cefic industry reports, and SEC filings from listed chemical conglomerates. Bottom-up resin volume estimates from polymerization train capacities were triangulated with top-down construction and automotive demand models.
Historical consumption patterns were cross-referenced against expert panel inputs to construct analytical frameworks across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry vertical, and regional production hub cluster. CAGRs were derived from regression analysis of correlated macroeconomic indicators and industry-specific drivers including chlor-alkali capacity utilization rates and REACH compliance conversion timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to SVHC candidate lists and force majeure events affecting Rhine corridor electrolysis operations. Forecasts reflect assumptions about recycled-content mandate enforcement consistency and bio-based plasticizer cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Styrenics Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Europe Engineering Plastics Market