
 Global Injection Molding Plastic Market | 2026-2036
Global Injection Molding Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Injection Molding Plastic Market Foresight
Modular packaging configurations is hardening as the dominant procurement pattern among food and beverage brand owners, who now specify interchangeable container platforms across multiple SKUs. Dow leverages its polyethylene portfolio to anchor supply agreements with tier-one packaging converters across North America. Berry Global competes through vertical control over both resin sourcing and blow-fill-seal operations, sustaining margin capture that pure molders cannot replicate.
Injection molding plastic encompasses thermoplastic and thermoset polymers shaped under controlled heat and pressure into precision-engineered components, typically achieving tolerances within 0.1 millimeters for critical-fit applications. The process serves as the backbone of mass-produced durable goods, converting pelletized raw material into finished parts in cycle times ranging from seconds to minutes depending on wall thickness and complexity. Thermoplastics command the largest volume share due to recyclability and reprocessability, though bioplastics represent the fastest-expanding category as brand owners face EPR mandates and consumer preference shifts. Electric molding technology leads capital investment flows, displacing hydraulic systems in cleanroom medical device production where energy efficiency and repeatability determine supplier qualification.
FDA device master file requirements and EU MDR technical documentation standards are reshaping material qualification protocols, forcing molders to maintain batch-level resin traceability from pellet to finished part. REACH substance restrictions and evolving state-level packaging EPR laws in California and New York are accelerating substitution toward post-consumer recycled content and bio-based feedstocks. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs in one geography increasingly determine which production networks qualify for cross-border supply contracts.
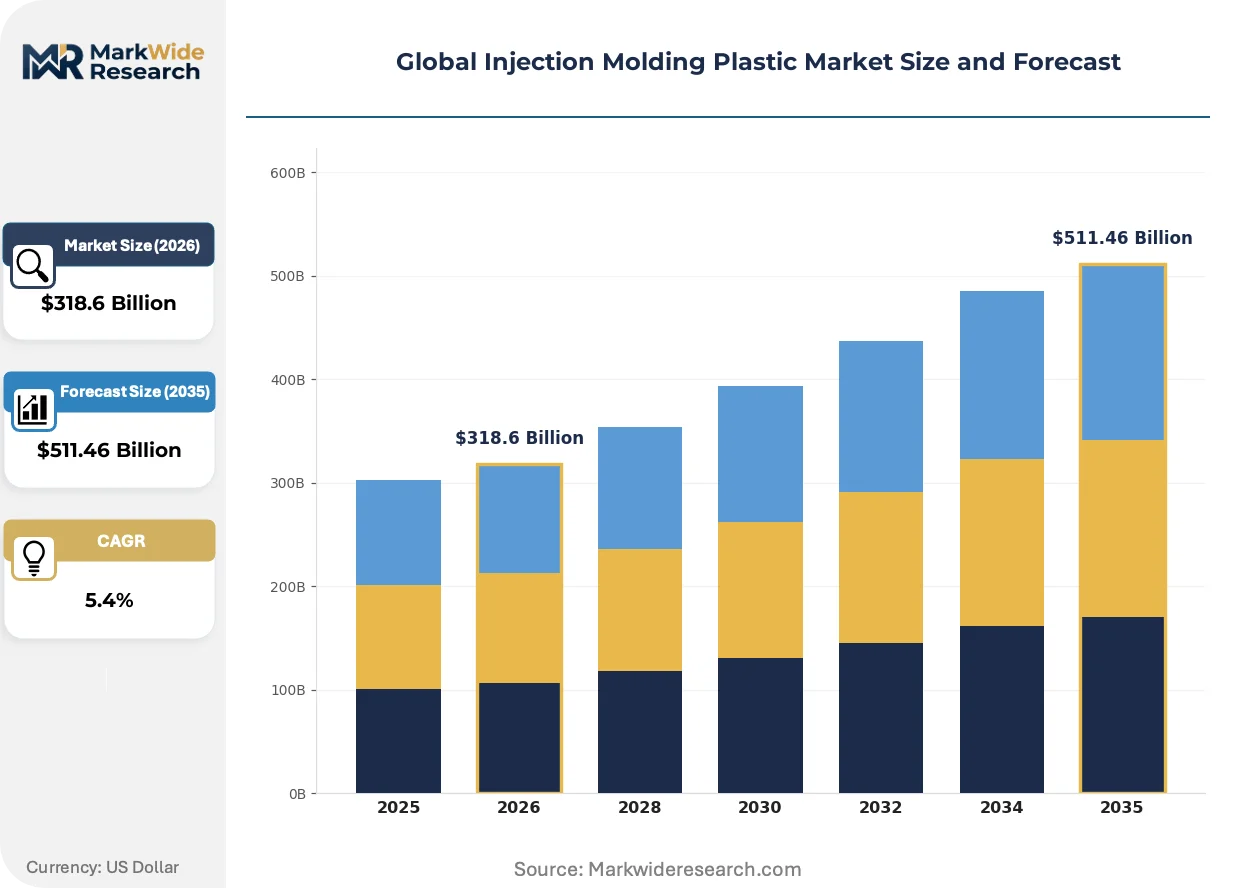
Market Dynamics
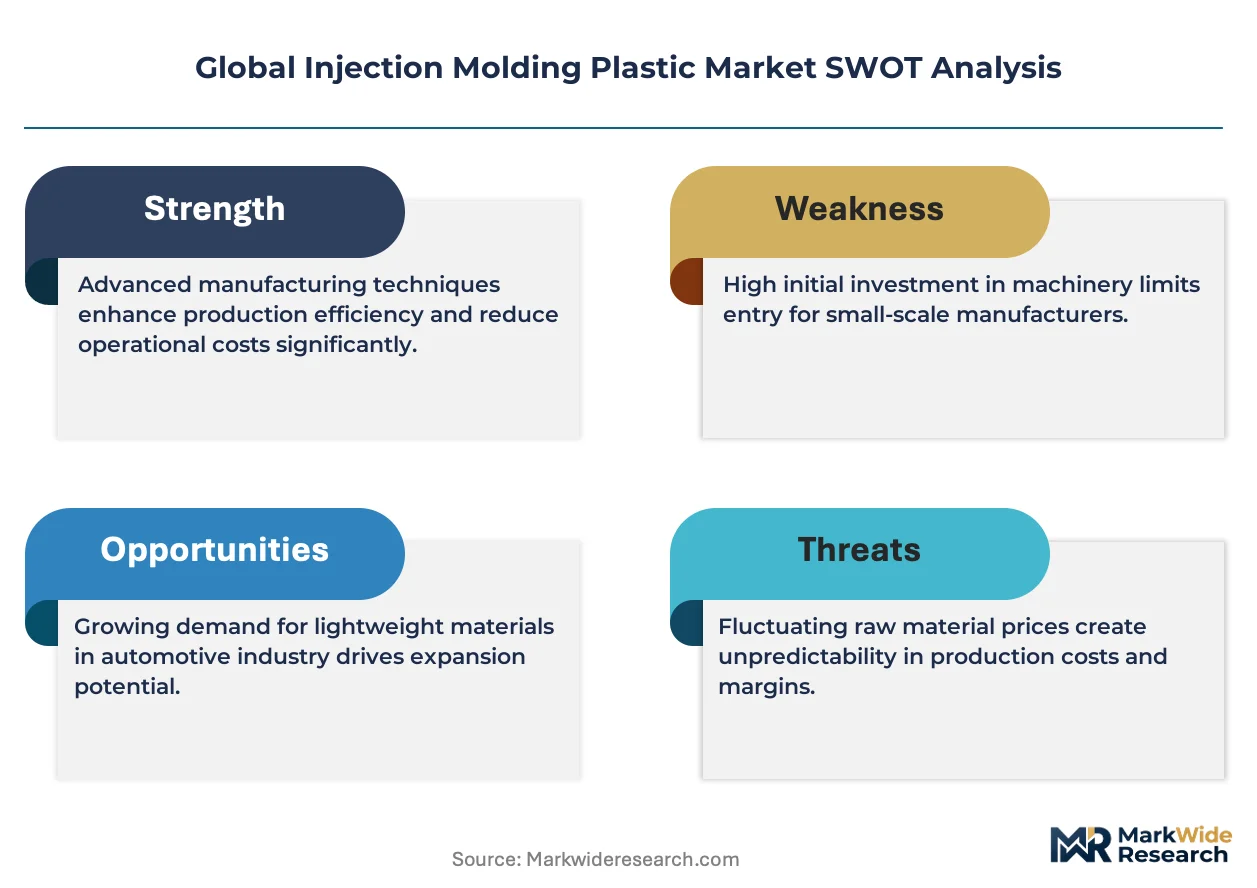
Automotive lightweighting mandates and medical device traceability requirements are compressing supplier qualification timelines while elevating capital barriers for molders serving regulated end-uses.
Growth Catalysts
- EU MDR batch traceability:Medical device manufacturers must document resin lineage from pellet to finished component, creating captive demand for qualified molders with validated quality systems.
- Electric molding systems:Cleanroom medical production now specifies servo-electric presses for energy efficiency and shot-to-shot repeatability, displacing hydraulic equipment in new capital budgets.
- Stuttgart-Wolfsburg corridor:Germany's automotive supplier density concentrates demand for glass-filled nylon structural components among tier-one system integrators.
Market Restraints
- Resin price volatility:Polypropylene and nylon feedstock costs track naphtha and benzene spot markets, compressing molder margins during upstream commodity spikes.
- REACH substance restrictions:ECHA's evolving SVHC candidate list forces reformulation of flame-retardant compounds and colorant masterbatches, extending material qualification cycles.
- Bioplastic performance gaps:PLA and PHA alternatives exhibit inferior heat deflection temperatures and moisture sensitivity, limiting substitution in under-hood automotive and sterilizable medical applications.
Strategic Opportunities
- California packaging EPR:Extended producer responsibility mandates for post-consumer recycled content create premium positioning for molders with certified PCR supply chains.
- India medical device PLI:Production-linked incentive schemes for domestic manufacturing attract molders establishing cleanroom capacity near Mumbai and Chennai pharmaceutical clusters.
- Digital thread integration:Convergence of injection molding simulation software with real-time cavity pressure sensors enables predictive quality control and reduced scrap rates.
Industry Challenges
- Tooling engineer scarcity:Complex multi-cavity mold design and hot runner system optimization require specialized expertise that outpaces vocational training pipeline output.
- FDA master file maintenance:Device manufacturers face recurring costs to update drug master files for polymer changes, creating friction in supplier switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Injection Molding Plastic Market |
| Market Size in 2026 | $318.6 Billion |
| Market Size in 2035 | $511.46 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosets, Elastomers, Bioplastics, Composite Materials Technology: Hydraulic Molding, Electric Molding, Hybrid Molding, Micro Injection, Overmolding Application: Consumer Electronics, Packaging Solutions, Automotive Components, Medical Devices, Construction Materials End User: OEM Manufacturers, Medical Equipment Suppliers, Packaging Companies, Electronics Assemblers, Construction Firms |
| Companies Covered | BASF SE, DuPont, Dow, HTI Plastics, Magna International, LyondellBasell, SABIC, Berry Global, EVCO Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Injection Molding Plastic Market Shifts & Advancements
Process digitization and material traceability requirements are redefining competitive advantage away from cycle-time optimization toward data-integrated production ecosystems.
Electric servo-hydraulic hybrid presses are converging with cloud-based manufacturing execution systems to enable real-time viscosity compensation and automatic cavity balancing. Automotive and medical device molders in Germany and Japan are retrofitting existing machine bases with IoT sensor arrays rather than full fleet replacement. This convergence is compressing the traditional separation between process control and enterprise resource planning, forcing molders to develop in-house data architecture capabilities or cede margin to platform vendors.
REACH authorization requirements for phthalate plasticizers and certain brominated flame retardants are compelling compounders to reformulate engineering resins ahead of sunset dates. The industrial consequence is a bifurcation between legacy formulations for existing device approvals and next-generation compounds requiring new biocompatibility testing. Medical device molders serving EU markets face the steepest compliance burden, with many qualifying dual-source material strategies to mitigate supply discontinuation risk.
Modular packaging platforms specified by food and beverage brand owners are consolidating SKU proliferation into interchangeable container systems with shared base dimensions. Tier-one converters now contract for multi-year resin supply agreements indexed to volume commitments across product families rather than individual SKUs. This concentration is most visible in North American dairy and condiment segments, where blow-fill-seal operations are being retooled for rapid changeover between container formats.
Global Injection Molding Plastic Market Segmentation
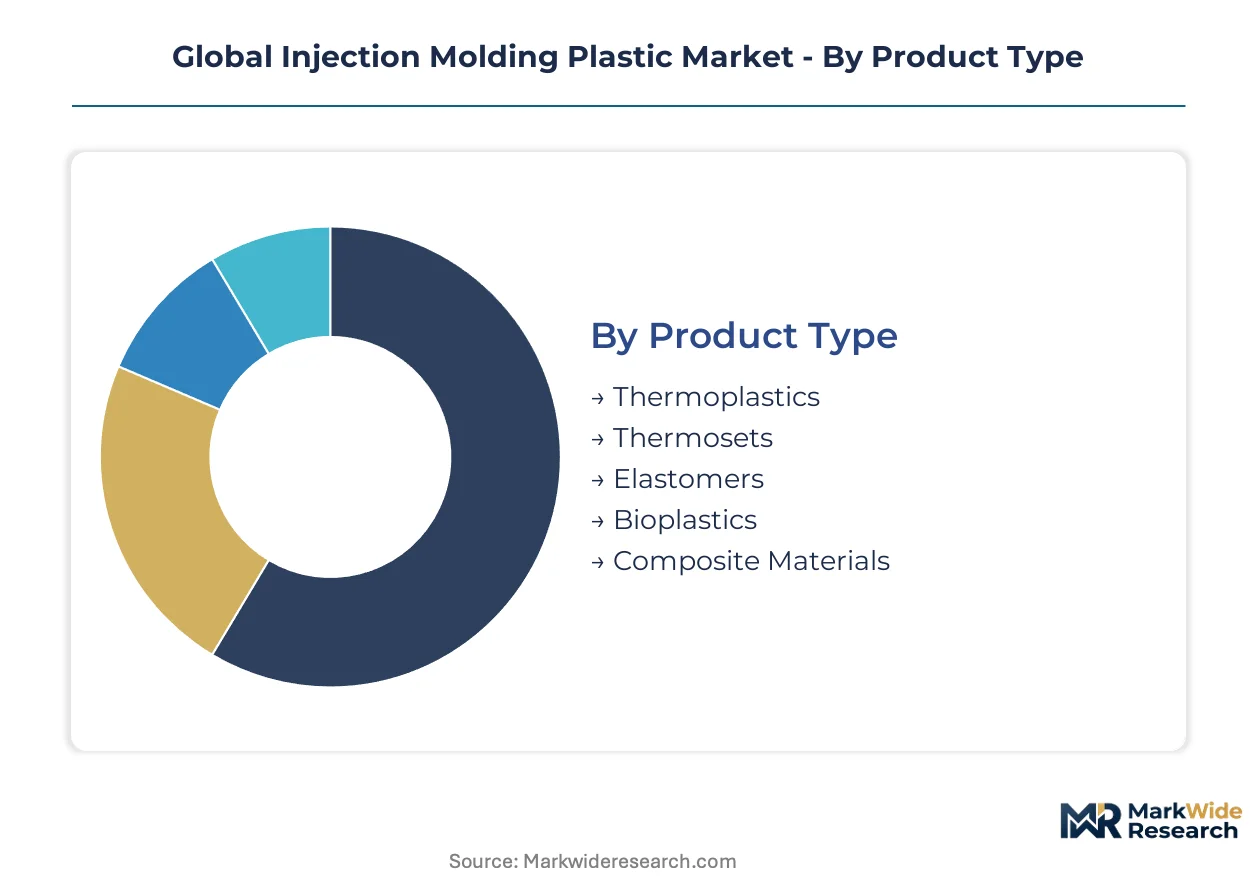
Injection molding plastic markets fragment along material chemistry, machine architecture, and end-use qualification requirements. Procurement decisions in automotive and medical channels prioritize validated supply chains over unit cost, reshaping how segments gain commercial traction.
Product Type:
Material selection hinges on recyclability mandates and heat performance specifications that vary sharply across automotive under-hood, medical sterilization, and food contact applications.
- Thermoplastics:Polypropylene and ABS dominate mass production due to reprocessability and established recycling infrastructure. Volume concentrates in Stuttgart automotive suppliers and North American packaging converters facing California EPR mandates for post-consumer content quotas.
- Bioplastics:PLA and PHA compounds serve brand owners with carbon reduction commitments, though moisture sensitivity limits deployment in sterilizable medical devices. Demand expansion tracks EU Green Deal procurement guidelines and corporate plastic pacts in Germany and Japan.
- Thermosets:Epoxy and phenolic resins retain structural integrity under sustained thermal load in electrical housings and appliance components.
- Elastomers:TPE and TPU grades enable soft-touch surfaces and sealing functions in consumer electronics and medical grips.
- Composite Materials:Glass-filled nylon and carbon fiber compounds deliver stiffness-to-weight ratios for structural automotive parts.
Volume sits with Thermoplastics; growth tilts toward Bioplastics.
Technology:
Capital deployment patterns reflect cleanroom qualification requirements and energy cost differentials that favor precision over raw throughput.
- Electric Molding:Servo-electric presses achieve shot-to-shot repeatability within 0.01 millimeters for medical device production. EU MDR batch traceability requirements and FDA device master file standards are accelerating displacement of hydraulic systems in cleanroom environments across Germany, Switzerland, and Massachusetts pharmaceutical corridors.
- Hybrid Molding:Servo-hydraulic systems balance clamp force with energy recovery, serving automotive structural components where wall thickness varies. Adoption concentrates among tier-one German suppliers retooling for glass-filled nylon bumper beams and battery housings.
- Hydraulic Molding:Conventional oil-driven systems persist in commodity packaging and construction fitting production where capital constraints dominate.
- Micro Injection:Specialized screw and plunger configurations process sub-gram shot weights for drug delivery devices and microfluidic components.
- Overmolding:Multi-material sequencing bonds rigid substrates with elastomeric or decorative layers in tool handles and electronic enclosures.
Installed base remains Hydraulic; expansion concentrates in Electric and Hybrid configurations.
Application:
End-use qualification timelines and regulatory burden determine molder margin structure and customer switching costs.
- Automotive Components:Glass-filled nylon structural parts support lightweighting mandates in European CO2 compliance frameworks. Demand clusters around Stuttgart-Wolfsburg supplier corridors and Toyota City manufacturing networks, with China's MIIT new energy vehicle standards driving parallel specification shifts.
- Medical Devices:Implantable and drug-delivery components require FDA master file maintenance and EU MDR technical documentation. NMPA regulations in China and PMDA standards in Japan add parallel qualification layers that extend material approval cycles.
- Packaging Solutions:Blow-fill-seal and thin-wall container production serves food and beverage brand owners with modular platform requirements.
- Consumer Electronics:Precision housings and connectors demand tight tolerances for miniaturized assemblies in smartphones and wearables.
- Construction Materials:Fittings, junction boxes, and insulation components prioritize flame retardancy under evolving ECHA REACH restrictions.
Revenue concentration favors Automotive; regulatory complexity peaks in Medical Devices.
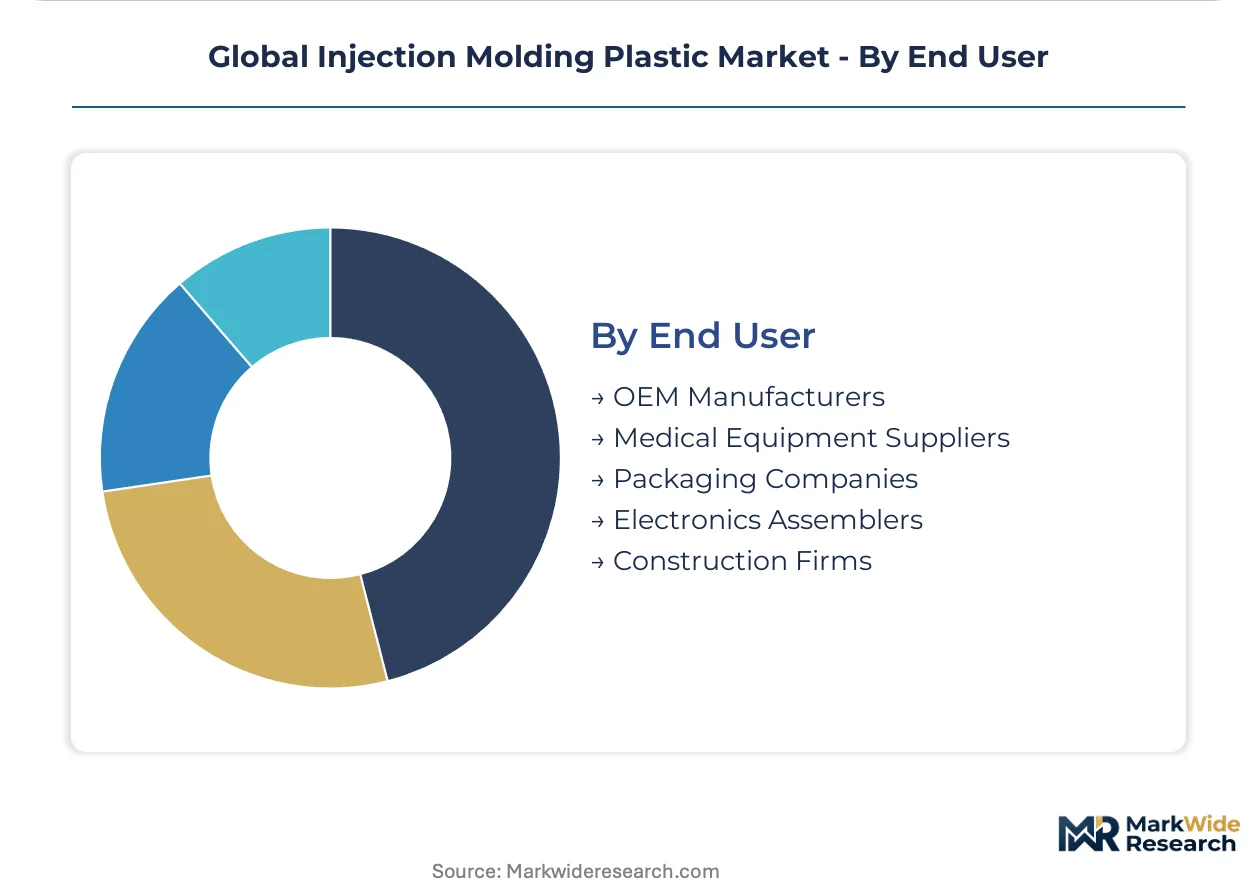
End User:
Buyer sophistication regarding material traceability and mold design capability separates premium supplier relationships from transactional procurement.
- OEM Manufacturers:Automotive and appliance brand owners specify resin grade and cavity pressure monitoring requirements in supply agreements. Volkswagen, BMW, and Whirlpool operations in Germany, Mexico, and China enforce batch-level documentation that qualified molders must maintain.
- Medical Equipment Suppliers:Device manufacturers like Medtronic and Becton Dickinson require validated quality systems with drug master file cross-referencing. EU MDR and FDA dual compliance creates captive supplier relationships with high switching friction.
- Packaging Companies:Berry Global and AptarGroup converters negotiate multi-year resin supply agreements indexed to volume commitments across SKU families.
- Electronics Assemblers:Foxconn and Flex contract for precision housings with tight tolerances and rapid design iteration cycles.
- Construction Firms:Infrastructure contractors source commodity fittings through distributor networks with limited technical specification involvement.
Procurement sophistication concentrates with Medical Equipment Suppliers; volume scale peaks with OEM Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of injection molding machinery while Germany and the United States concentrate the highest-value precision applications. Production capacity expansion in Asia-Pacific outpaces demand growth in mature markets, creating divergent margin structures across geographies.
China
MIIT new energy vehicle standards accelerate demand for glass-filled nylon battery housings and structural components. NMPA medical device regulations enforce batch-level resin traceability from pellet to finished part, extending qualification timelines for domestic molders. The Yangtze River Delta clusters injection molding capacity around Shanghai, Suzhou, and Ningbo, serving automotive tier-one suppliers and pharmaceutical packaging converters with integrated cleanroom operations.
Germany
EU MDR technical documentation standards and REACH substance restrictions compel reformulation of flame-retardant compounds ahead of sunset dates. The Stuttgart-Wolfsburg automotive supplier corridor concentrates demand for precision structural components among Volkswagen and BMW tier-one integrators. Bavaria and Baden-Württemberg host the densest concentration of servo-electric press installations for medical device cleanroom production.
United States
FDA device master file requirements create captive supplier relationships with high switching friction for implantable and drug-delivery components. California and New York state-level packaging EPR laws mandate post-consumer recycled content quotas, reshaping resin procurement patterns. The Midwest automotive belt around Detroit and the Massachusetts pharmaceutical corridor drive contrasting qualification requirements for structural versus medical-grade molding.
Japan
PMDA standards add parallel qualification layers to EU MDR and FDA compliance for polymer supply chains serving global device manufacturers. METI carbon neutrality targets accelerate electric molding system adoption in precision component production. The Nagoya automotive manufacturing network and Osaka medical device clusters maintain stringent cavity pressure monitoring specifications in supply agreements.
India
PLI schemes for domestic medical device manufacturing attract cleanroom capacity investment near Mumbai and Chennai pharmaceutical clusters. BIS standards for automotive components converge with global OEM specifications, enabling export qualification for tier-one suppliers. Gujarat and Maharashtra concentrate blow-fill-seal packaging operations for domestic dairy and condiment brand owners with modular platform requirements.
Global Injection Molding Plastic Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with captive resin supply and specialized molders with validated quality systems. Tier-one automotive and medical device procurement concentrates volume among qualified suppliers, while packaging segments sustain fragmented converter competition. Two strategic archetypes dominate: integrated resin-to-part producers leveraging backward integration, and precision specialists capturing premium positioning through regulatory qualification. Capacity expansion and portfolio diversification toward bio-based feedstocks represent the dominant competitive moves across both archetypes.
Within the integrated chemical conglomerate tier, BASF SE, Dow, and SABIC exemplify backward integration into polymer compounding and captive molding operations. These Germany-based and US-based entities anchor supply agreements through polyethylene and polypropylene portfolio breadth. Among specialized molders, Berry Global occupies a position representing vertical control over resin sourcing and blow-fill-seal operations that pure molders cannot replicate. The competitive dynamic separates volume-scale resin producers from precision-qualified specialists, with regulatory compliance costs determining which production networks qualify for cross-border medical and automotive supply contracts.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| Dow |
| HTI Plastics |
| Magna International |
| LyondellBasell |
| SABIC |
| Berry Global |
| EVCO Plastics |
| Others |
Supply & Pricing Matrix
Tooling engineer scarcity in the Stuttgart-Wolfsburg corridor widens pricing-tier spreads between qualified precision molders and commodity converters, as labor-cost differentials compound resin qualification burdens.
Pricing Analysis
Margin tightening in medical-grade molding reflects EU MDR batch traceability compliance costs and FDA master file maintenance overhead. Three-tier pricing structure across premium, standard, and economy levels separates validated cleanroom suppliers from automotive structural specialists and commodity packaging converters. Price differentiation hinges on certification grade and volume scale, with automotive tier-one procurement showing lowest price sensitivity due to lightweighting mandate urgency.
Supply Chain Analysis
Resin supply rests on Saudi Arabia, South Korea, and Germany for virgin polymer feedstock, with post-consumer recycled content sourcing fragmenting across North American and European reclaimers. Naphtha and benzene spot volatility, compounded by REACH substance restrictions on flame-retardant formulations, creates single-source vulnerability for qualified compounds. Distribution runs through regional compounding hubs serving tier-one automotive corridors and pharmaceutical packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with resin-to-part control and validated quality systems as the decisive levers separating premium positioning from margin compression.
For Market Incumbents: Anticipate bioplastic performance gaps and REACH reformulation cycles by qualifying dual-source material strategies ahead of sunset dates. Deepen backward integration into compound development to capture margin otherwise lost to resin price volatility, while retrofitting electric molding fleets for EU MDR compliance. For New Entrants and Emerging Players: Mid-tier medical device suppliers underserved by qualified cleanroom capacity in India and Southeast Asia present the most penetrable entry point. Establish certified PCR supply chains for California packaging EPR mandates, leveraging modular platform specifications to secure multi-year resin offtake agreements with dairy and condiment brand owners. For Investors and Strategic Acquirers: The window for entry favors specialized molders with validated EU MDR and FDA dual compliance. Target acquisition candidates with captive electric molding capacity in Germany, Switzerland, or Massachusetts pharmaceutical corridors. Watch NMPA regulatory alignment in China as the inflection indicator for cross-border medical supply contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from naphtha volatility for Stuttgart automotive suppliers. |
| Electric Molding Fleet Conversion | Qualifies cleanroom production for EU MDR batch traceability mandates. |
| Certified PCR Supply Chain Development | Positions converters for California and New York EPR content quotas. |
| Dual-Source Material Qualification | Mitigates REACH reformulation risk for implantable device manufacturers. |
| Digital Thread Integration | Enables predictive quality control through cavity pressure sensor convergence. |
Research Methodology
Multi-period observation of resin price spreads, machine architecture adoption rates, and regulatory qualification timelines anchored the trend analysis, supplemented by interviews with plant managers at tier-one automotive suppliers, procurement leads at medical device OEMs, technical R&D directors at compounders, and quality systems managers at cleanroom molders. Secondary validation drew from ECHA REACH substance restriction updates, FDA device master file databases, SEC 10-K filings of integrated chemical conglomerates, and customs data tracking polymer trade flows. Bottom-up capacity estimates and top-down demand segmentation were triangulated against installed base surveys.
The input-output matrix framed volume projections across material chemistry, machine technology, end-use qualification requirements, and regional regulatory clusters. Modeled dimensions included thermoplastic versus bioplastic grade tiers, electric versus hydraulic versus hybrid press configurations, automotive structural versus medical device versus packaging applications, and production hub concentration in Germany, China, United States, Japan, and India. CAGRs were derived from elasticity-adjusted demand curves and capital expenditure tracking across the projection horizon, with naphtha-benzene feedstock correlations and EPR mandate implementation schedules as industry-specific forecast inputs.
Revisions become necessary when REACH authorization timelines accelerate, bioplastic heat deflection temperatures achieve automotive under-hood thresholds, or NMPA traceability standards diverge from EU MDR alignment. Forecasts reflect assumptions about resin qualification cycle stability and electric molding cost parity achievement. A small set of triggers—regulatory harmonization shifts, feedstock price regime changes, and cleanroom capacity buildout rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market