
 Global Scleroderma Diagnostics and Therapeutics Market | 2026-2036
Global Scleroderma Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scleroderma Diagnostics and Therapeutics Market Intelligence
The focus within end-user settings on Specialty Clinics for managing complex scleroderma cases is hardening. F. Hoffmann-La Roche Ltd. leverages its extensive immunology portfolio to develop targeted biologics. Boehringer Ingelheim International GmbH specializes in antifibrotic treatments for associated interstitial lung disease. Novartis AG competes with novel therapies aimed at modifying underlying disease mechanisms.
Scleroderma diagnostics and therapeutics encompass methods and drugs for an autoimmune disease marked by excessive collagen deposition and fibrosis. The primary goal is early detection and management to slow disease progression. Immunosuppressants and antifibrotic agents form the core of treatment, while the biologics product category represents a high-growth frontier. Therapeutic development often targets the severe diffuse cutaneous scleroderma therapy area due to its high unmet need.
Regulatory bodies like the U.S. FDA, the European Medicines Agency (EMA), and Japan's PMDA shape market access for novel therapies. Their orphan drug designations and accelerated approval pathways are critical for bringing new treatments to patient populations. Stakeholder success will hinge on navigating evolving clinical trial endpoints and securing favorable reimbursement policies.
Market Dynamics
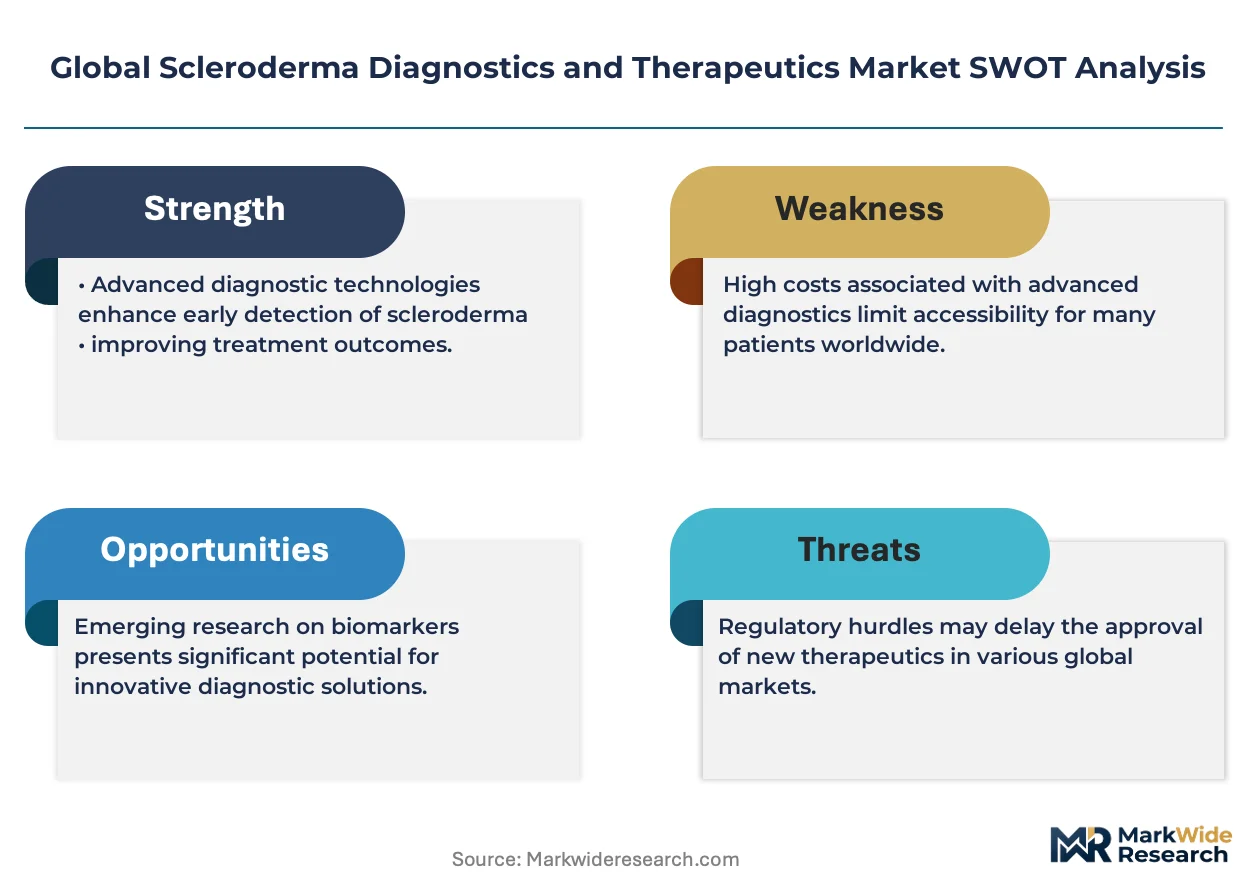
The central force shaping this market is the convergence of genomic biomarker discovery and accelerated regulatory pathways for orphan diseases. This pull is shifting investment from broad immunosuppression toward the development of mechanism-specific biologics and antifibrotic agents.
Growth Catalysts
- Orphan Drug Designations:The U.S. FDA's and EMA's frameworks provide incentives like market exclusivity and reduced fees, which de-risk development for rare diseases like scleroderma.
- Specialty Clinic Expansion:Concentrating complex case management in specialty clinics improves patient outcomes and provides centralized sites for advanced clinical trials, accelerating data collection.
- Advanced Imaging Techniques:Adoption of high-resolution computed tomography (HRCT) and novel MRI sequences for assessing organ involvement enables earlier and more precise therapeutic intervention.
Market Restraints
- Disease Heterogeneity:Scleroderma's varied clinical presentation complicates clinical trial design, making it difficult to establish universally effective endpoints for regulatory approval.
- High Cost of Biologics:The manufacturing complexity and research investment for biologic therapies result in premium pricing, limiting patient access in healthcare systems with strict reimbursement controls.
- Diagnostic Code Ambiguity:Inconsistent application of ICD codes for scleroderma subtypes across healthcare systems in countries like Germany and France can hinder epidemiological studies and reimbursement.
Strategic Opportunities
- Untapped Asian Markets:Expanding diagnostic screening and patient education programs in countries like South Korea and Australia presents an opportunity for market entry beyond the established hub of Japan.
- AI in Drug Discovery:Integrating artificial intelligence with genomic and proteomic data can identify novel therapeutic targets and predict patient response, shortening preclinical development timelines.
- Pediatric Investigation Plans:Mandates from the EMA and FDA for pediatric investigation plans create an opportunity to develop and validate treatments specifically for juvenile scleroderma.
Industry Challenges
- Specialized Rheumatologist Scarcity:A shortage of rheumatologists with deep expertise in scleroderma limits patient access to specialized care, particularly outside of major urban centers in the United States and Europe.
- Complex Clinical Trial Endpoints:Navigating the evolving requirements from regulators like the PMDA and FDA for composite endpoints in clinical trials creates significant operational hurdles for trial sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scleroderma Diagnostics and Therapeutics Market |
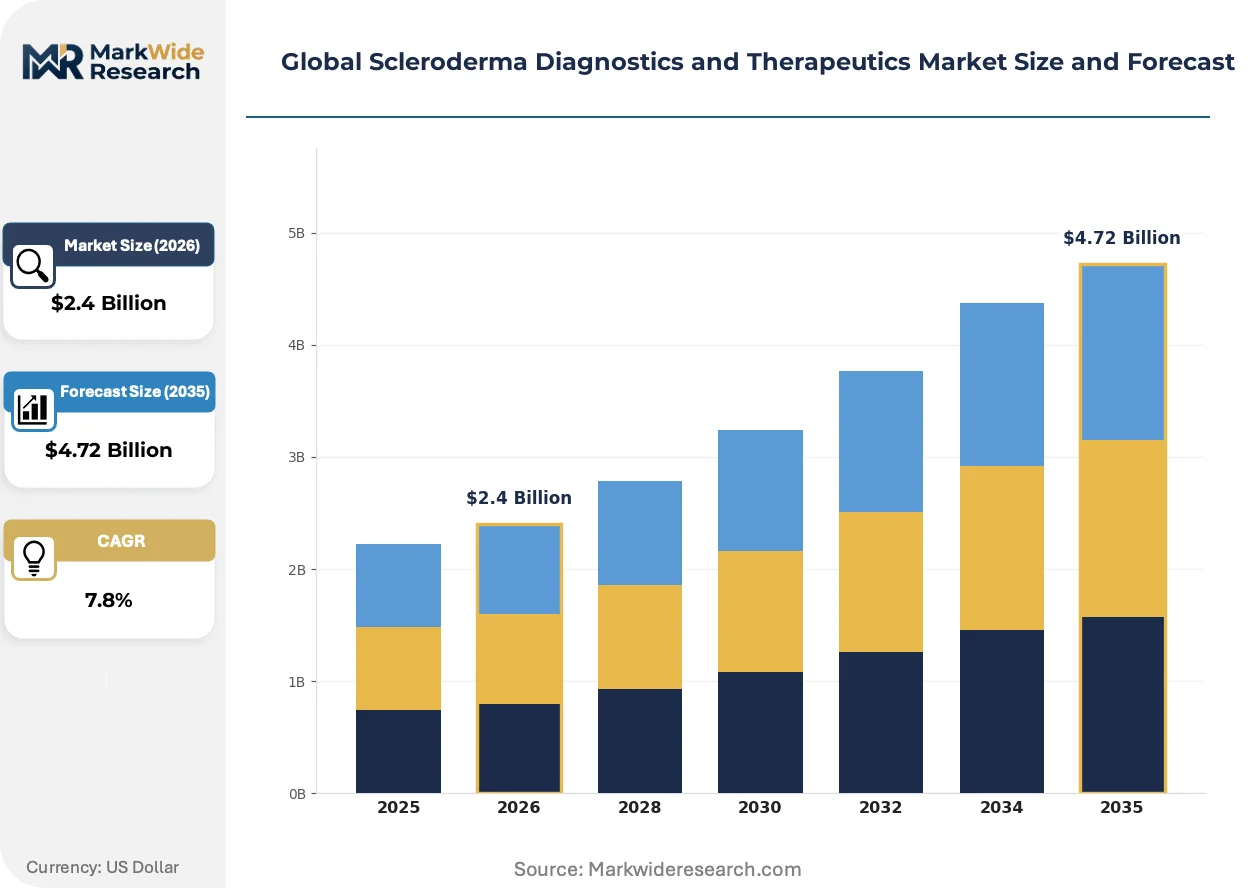
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Immunosuppressants, Antifibrotic Agents, Vasodilators, Biologics Application: Early Detection, Disease Monitoring, Symptom Management, Organ Protection End User: Specialty Clinics, Research Institutions, Academic Centers, Contract Research Organizations Therapy Area: Limited Cutaneous, Diffuse Cutaneous, Overlap Syndromes, Localized Scleroderma |
| Companies Covered | Bayer AG, Novartis AG, Johnson and Johnson, Sanofi S.A., Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd., Pfizer Inc., Corbus Pharmaceuticals Holdings Inc., Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scleroderma Diagnostics and Therapeutics Market Strategic Shifts & Innovations
A fundamental shift toward precision medicine is reshaping the market's trajectory. This move from symptom management to targeting underlying fibrotic and immune pathways is altering diagnostic protocols and therapeutic development priorities.
Digital pathology combined with AI algorithms provides quantitative analysis of fibrosis in skin biopsies, moving beyond subjective histological scoring. Diagnostic laboratories and contract research organizations are adopting this technology to improve clinical trial data accuracy. The ability to precisely quantify treatment effects at a tissue level is electrifying the development of new antifibrotic agents.
The European Medicines Agency's PRIME (PRIority MEdicines) scheme offers enhanced scientific and regulatory support for medicines targeting unmet medical needs. This initiative accelerates the assessment of promising scleroderma therapies, potentially shortening the time to market authorization. Biologics and novel small molecules for diffuse cutaneous scleroderma are the product categories most impacted by this pathway.
Patient advocacy groups are increasingly influencing clinical trial design and the selection of meaningful outcome measures. This shift moves the focus from purely clinical or laboratory markers to patient-reported outcomes (PROs), such as quality of life, pain, and fatigue. This trend is most prominent in the United States and the UK, where organizations actively collaborate with researchers and regulatory bodies.
Global Scleroderma Diagnostics and Therapeutics Market Segmentation
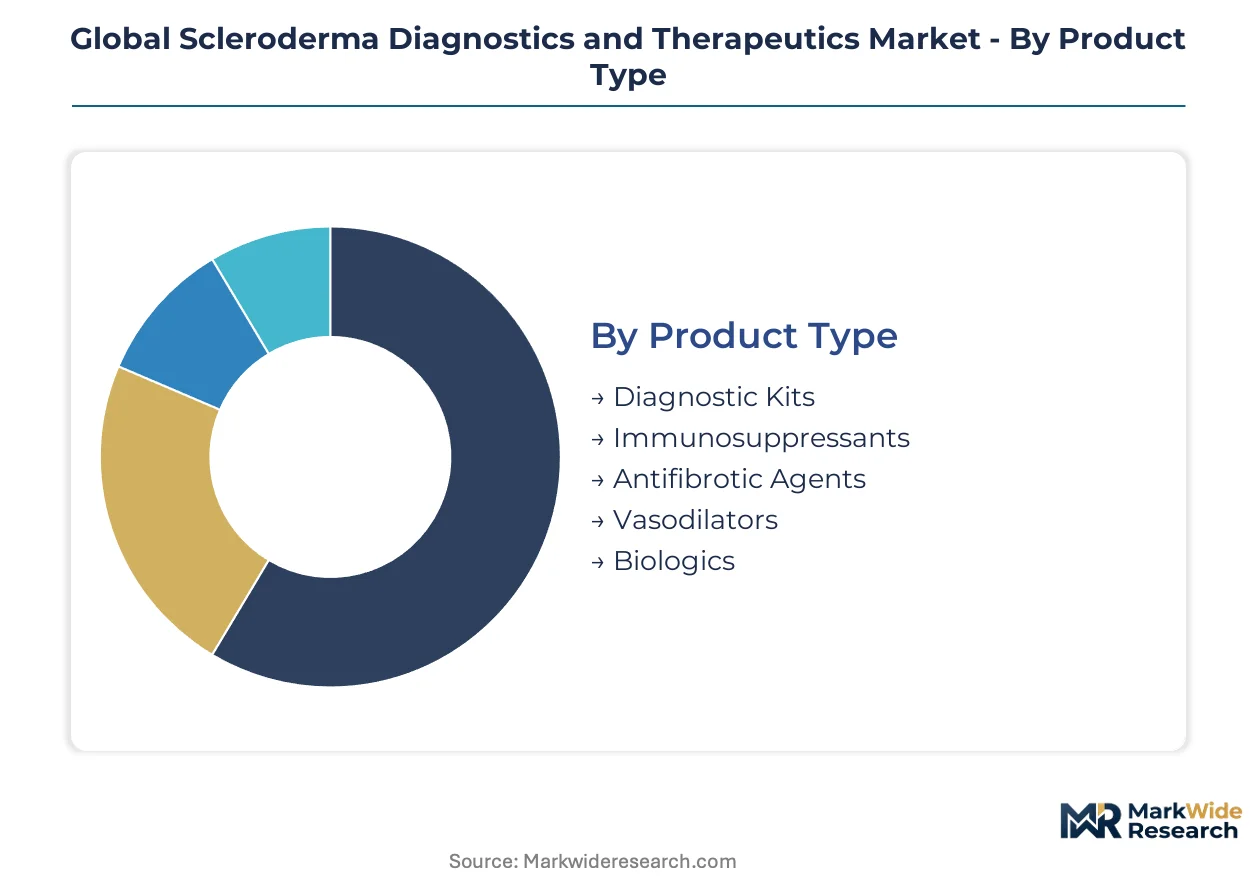
The Global Scleroderma Diagnostics and Therapeutics Market is structured to address the complex and varied manifestations of this autoimmune disease. Segmentation provides a granular view of market dynamics, revealing specific areas of demand for early detection tools and advanced therapeutic interventions. Understanding these distinct segments helps stakeholders tailor product development and market access strategies.
Product Type:
The varied product types in scleroderma treatment face distinct regulatory pathways, with biologics and novel agents often requiring extensive clinical validation from bodies like the U.S. FDA and the European Medicines Agency (EMA).
- Biologics:These advanced therapies, often monoclonal antibodies, target specific immune pathways implicated in scleroderma pathogenesis, offering a more precise treatment approach than traditional immunosuppressants. Demand for biologics is concentrating in high-income countries like the United States and Germany, driven by favorable reimbursement policies and specialized clinical infrastructure.
- Antifibrotic Agents:Medications like nintedanib work by inhibiting multiple tyrosine kinases, thereby reducing fibroblast proliferation and collagen production, primarily used to manage interstitial lung disease associated with scleroderma. Their demand is particularly strong in patient populations with significant pulmonary involvement, especially in regions with comprehensive diagnostic capabilities for lung fibrosis.
- Diagnostic Kits:These kits include serological tests for autoantibodies and genetic markers, aiding in the early and accurate diagnosis of scleroderma.
- Immunosuppressants:Traditional drugs such as methotrexate and cyclophosphamide modulate the immune system to reduce inflammation and slow disease progression.
- Vasodilators:These agents, including calcium channel blockers and prostacyclin analogs, alleviate vascular symptoms like Raynaud's phenomenon and pulmonary hypertension.
Immunosuppressants sit at the top of the volume ranking, with Biologics climbing the fastest.
Application:
The diverse applications reflect the multifaceted nature of scleroderma, requiring targeted interventions across various stages of disease progression.
- Early Detection:This application focuses on identifying scleroderma at its earliest stages, often before significant organ damage occurs, using advanced biomarker panels and imaging techniques. Demand is concentrating in academic centers and specialty clinics focused on improving long-term patient outcomes through timely intervention.
- Organ Protection:Therapies and diagnostics aimed at preventing or mitigating damage to internal organs such as the lungs, heart, and kidneys are crucial for improving patient survival and quality of life. This application is particularly critical in severe diffuse cutaneous scleroderma, where systemic involvement is common and progression can be rapid.
- Disease Monitoring:This involves regular assessment of disease activity, organ involvement, and treatment response using clinical evaluations, laboratory tests, and imaging.
- Symptom Management:This application addresses specific symptoms like pain, fatigue, and gastrointestinal issues, improving the patient's daily comfort and functional capacity.
Early Detection is gaining significant traction, while Organ Protection remains a critical area for therapeutic advancement.
End User:
End-user segments demonstrate varying levels of specialization and infrastructure, influencing the adoption of advanced diagnostics and complex therapeutic regimens.
- Specialty Clinics:These facilities offer comprehensive, multidisciplinary care for scleroderma patients, integrating advanced diagnostics, specialized treatment protocols, and clinical trial participation. Their expansion, particularly in the United States and Japan, enhances access to complex case management and drives demand for novel therapies.
- Research Institutions:Academic and private research institutions are at the forefront of understanding scleroderma pathogenesis, identifying new therapeutic targets, and conducting preclinical studies. These institutions are critical for the early-stage development and validation of innovative diagnostic and therapeutic approaches.
- Academic Centers:These centers combine patient care with medical education and research, often serving as referral hubs for complex scleroderma cases.
- Contract Research Organizations:CROs provide specialized services for clinical trials, including study design, patient recruitment, and data management, supporting pharmaceutical companies in drug development.
Specialty Clinics drive significant demand for advanced treatments, with Contract Research Organizations exhibiting expanding activity in clinical development.
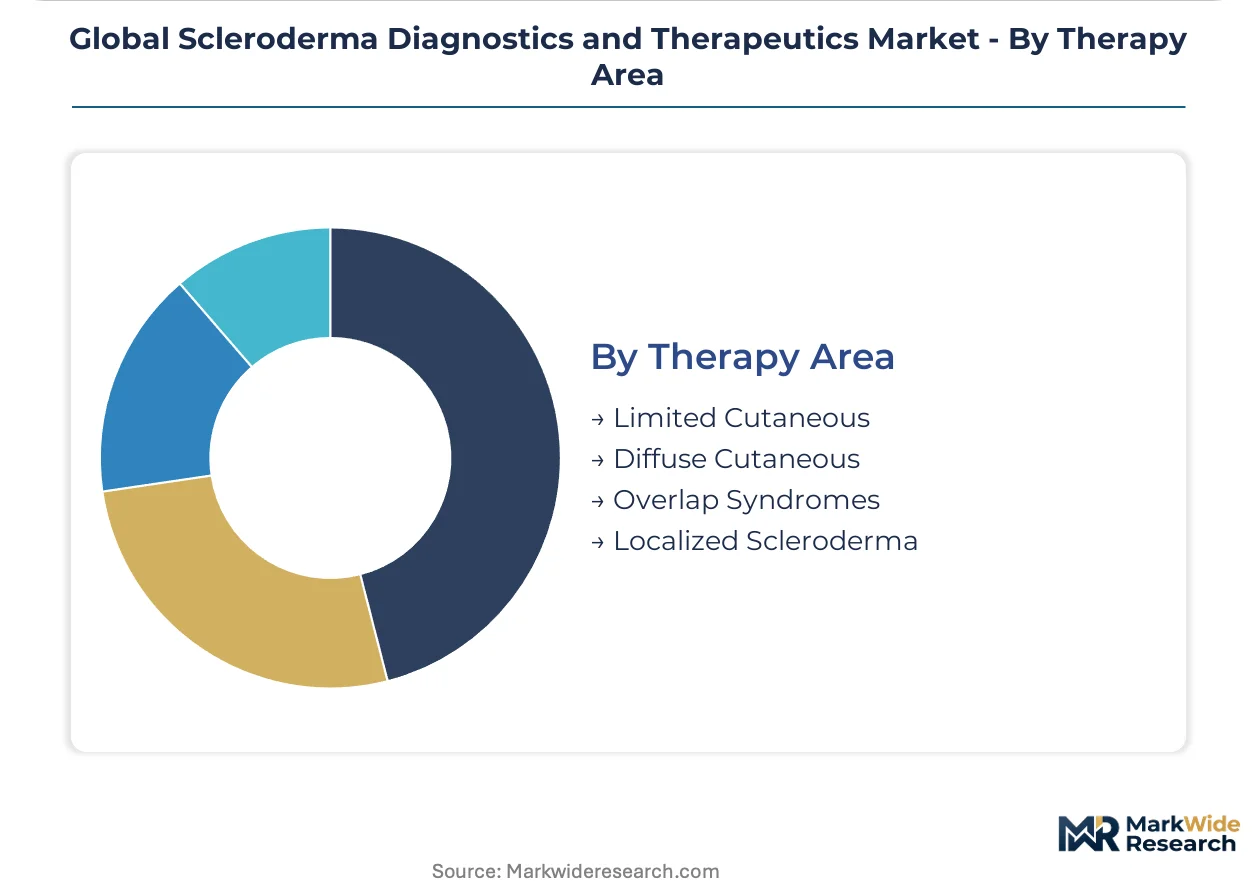
Therapy Area:
Scleroderma's clinical heterogeneity dictates distinct therapy area approaches, each addressing specific disease manifestations and patient needs.
- Diffuse Cutaneous:This severe form of scleroderma involves widespread skin thickening and rapid progression to internal organ damage, representing a significant unmet medical need and a focus for novel therapeutic development. Therapies for this area often target fibrotic pathways, with regulatory bodies like the PMDA and FDA prioritizing accelerated approval for effective treatments.
- Limited Cutaneous:Characterized by skin thickening primarily affecting the face, hands, and feet, this form often progresses more slowly and is associated with specific complications like pulmonary hypertension. Treatment strategies for limited cutaneous scleroderma frequently focus on managing vascular symptoms and preventing long-term complications.
- Overlap Syndromes:These cases present with features of scleroderma combined with other autoimmune diseases, requiring individualized diagnostic and therapeutic approaches.
- Localized Scleroderma:This form primarily affects the skin in specific areas without internal organ involvement, commonly treated with topical or localized therapies.
Diffuse Cutaneous scleroderma represents a therapy area with substantial unmet needs, while Localized Scleroderma requires focused diagnostic development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences the global scleroderma diagnostics and therapeutics market, with companies seeking optimal environments for research and commercialization. Compliance costs and approval timelines vary significantly across major economies. This disparity drives strategic investment decisions and market entry patterns.
United States
Demand for advanced biologics is high due to robust healthcare spending and patient advocacy. The U.S. FDA's orphan drug designation provides significant incentives for novel therapeutic development. Major biopharmaceutical clusters in Boston and San Francisco drive innovation in precision medicine and complex disease management.
Germany
Patient access to innovative treatments is strong, supported by comprehensive health insurance systems. The European Medicines Agency (EMA) offers accelerated pathways like PRIME for unmet medical needs, benefiting scleroderma therapies. Munich and Berlin host significant research institutions advancing scleroderma therapy and clinical trials.
Japan
Early detection and organ protection are prioritized, driven by an aging population and advanced diagnostic capabilities. Japan's PMDA actively streamlines approval for therapies addressing rare diseases, including scleroderma. Pharmaceutical hubs in Tokyo and Osaka are centers for clinical trial activity and novel drug development.
United Kingdom
Demand for patient-reported outcomes in clinical trials is growing, influenced by active patient groups and regulatory bodies. The National Institute for Health and Care Excellence (NICE) assesses cost-effectiveness for market access, influencing therapeutic adoption. London's biomedical campuses foster collaborative research in autoimmune diseases and precision diagnostics.
South Korea
Advanced imaging techniques are gaining traction for precise disease monitoring and early intervention. The Ministry of Food and Drug Safety (MFDS) supports the development of innovative medical devices and biologics. Seoul's medical research parks contribute significantly to genomic biomarker discovery and therapeutic validation.
Global Scleroderma Diagnostics and Therapeutics Market Key Industry Players
Strategic partnerships dominate the current landscape, reflecting a drive for shared R&D costs and expanded market reach. The market structure is moderately consolidated, with a few large pharmaceutical companies holding significant sway. Archetypes include diversified immunology giants, specialized antifibrotic developers, and innovative biotech startups. Technology licensing and geographic expansion are also prevalent competitive moves.
Within the diversified immunology archetype, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify extensive portfolios across various autoimmune conditions, driving broad therapeutic development. Boehringer Ingelheim International GmbH occupies a specialized position, anchoring expertise in antifibrotic treatments, particularly for associated interstitial lung disease. These major pharmaceutical entities leverage their global presence and substantial research capabilities to address unmet needs in complex disease areas like scleroderma, often through targeted biologics and novel small molecules. Their strategies often involve navigating stringent regulatory pathways to bring advanced therapies to patient populations worldwide.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis AG |
| Johnson and Johnson |
| Sanofi S.A. |
| Bristol Myers Squibb Company |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Corbus Pharmaceuticals Holdings Inc. |
| Boehringer Ingelheim International GmbH |
| Others |
Cost & Logistics Intelligence
Specialty Clinics, as concentrated buyers of advanced therapies, largely influence the value-based pricing models prevalent for innovative scleroderma treatments. This structure ensures that therapies with demonstrated efficacy command premium pricing, reflecting their development costs and clinical impact.
Pricing Analysis
Hospital pharmacy margins significantly impact the final cost of biologics for scleroderma patients. Value-based pricing models dominate, driven by the clinical efficacy and orphan drug designation of novel therapies, particularly for diffuse cutaneous scleroderma. Pricing pressure stems from stringent reimbursement policies by bodies like the National Institute for Health and Care Excellence in the UK. Specialty clinics, managing complex cases and demonstrating improved patient outcomes, exhibit the least price sensitivity for these advanced treatments.
Supply Chain Analysis
Dual-sourcing requirements for critical biologic active pharmaceutical ingredients (APIs) enhance supply chain resilience for scleroderma treatments. Manufacturing of finished biologics concentrates in the United States, Germany, and Japan, drawing from specialized raw materials like cell culture media and recombinant proteins. Single-source vulnerability for highly specialized reagents and novel small molecule intermediates remains a structural risk. Distribution runs through a direct-to-specialty-pharmacy model, ensuring controlled access and cold-chain integrity for complex therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scleroderma market acts as a regulatory compounder, with initiatives like the U.S. FDA's Orphan Drug Designation significantly accelerating therapeutic development. This framework provides incentives that directly drive demand for novel diagnostic and treatment solutions.
For Market Incumbents: Anchor R&D efforts in next-generation biologics targeting specific fibrotic pathways to counter emerging novel small molecule threats. Pursue strategic licensing agreements for advanced diagnostic platforms to maintain a competitive edge. Expand clinical trial networks in specialty clinics to accelerate data collection and regulatory submissions. Invest in patient education programs to reinforce brand loyalty and improve treatment adherence.
For New Entrants and Emerging Players: Digital pathology platforms offer a white-space opportunity for quantitative fibrosis assessment, improving diagnostic accuracy. Target the juvenile scleroderma segment, leveraging pediatric investigation plans for accelerated regulatory pathways. Partner with Contract Research Organizations to navigate complex clinical trial endpoints effectively. Focus on developing mechanism-specific small molecules that address unmet needs in diffuse cutaneous scleroderma.
For Investors and Strategic Acquirers: Diversified biopharma giants are the most active acquirers in this space, seeking to expand their immunology portfolios. The market demonstrates long-term viability, driven by persistent unmet medical needs and regulatory support for orphan diseases. Target innovative biotech startups with AI-driven drug discovery platforms or promising early-stage biologics. A successful Phase 3 readout for a novel antifibrotic agent indicates a significant inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for promising therapies by meeting evolving regulatory endpoints. |
| Licensing Agreement | Expands therapeutic portfolios and reduces R&D risk for novel scleroderma treatments. |
| Manufacturing Scale-Up | Ensures adequate supply of complex biologics to meet global patient demand efficiently. |
| Platform Integration | Combines AI with genomic data to identify new therapeutic targets more rapidly. |
| Hospital System Partnership | Improves patient access to specialized care and advanced diagnostic tools for scleroderma. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming the bedrock of this analysis. Primary research involved discussions with leading rheumatologists, R&D executives, regulatory affairs specialists, and patient advocacy representatives. Secondary validation drew from U.S. FDA filings, European Medicines Agency submissions, clinical trial registries, and academic literature. This approach ensured robust bottom-up and top-down triangulation of market data.
Comparable historical periods anchored the forecast window, informing the analytical framework applied across the modeling period. Segmentation dimensions included product type, application, end-user, therapy area, and regional regulatory clusters. Compound annual growth rates were derived from observed historical trends and projected market dynamics. Key inputs included clinical trial success rates and orphan drug approval timelines.
The model assumes a particular technology adoption path; alternative pathways for AI in drug discovery would alter the outlook. Forecasts reflect assumptions regarding clinical trial outcomes and market access policies. Deviation in major regulatory shifts or unexpected clinical trial failures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
HER2 Positive Gastric Cancer Market