
 Colon Cleansing Supplements Market | 2026-2036
Colon Cleansing Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Colon Cleansing Supplements Market Analytics
Subscription-based direct-to-consumer financing is reconfiguring competitive entry barriers in colon cleansing supplements. Health Plus Inc leverages its established retail pharmacy relationships to sustain shelf dominance across conventional channels. Irwin Naturals anchors its position through specialized herbal formulation expertise that commands premium positioning. NOW Foods competes on manufacturing scale, operating vertically integrated production facilities that control raw material quality from fiber sourcing through finished packaging.
Colon cleansing supplements comprise orally administered formulations containing fiber matrices, probiotic cultures, or botanical laxatives engineered to accelerate intestinal transit and eliminate accumulated waste. Standard products deliver psyllium husk at concentrations between 3.5 and 5 grams per serving, or senna-based sennosides standardized to 8.6 to 17.2 milligrams for acute relief. The pills category dominates volume due to dosing convenience and travel portability, while probiotic-active formulations represent the fastest-expanding margin pool as refrigerated supply chain investments mature. Fiber-based applications maintain the largest installed base among consumers seeking routine digestive maintenance rather than acute intervention.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity testing and contamination screening that elevate compliance costs for new entrants. The USDA Organic certification and NSF International third-party verification programs shape consumer trust hierarchies and retail access decisions at major pharmacy chains. Stakeholders must monitor how state-level attorney general actions against unsubstantiated detox claims reshape permissible marketing language and channel strategies.
Market Dynamics
Subscription-based direct-to-consumer platforms are compressing traditional retail pharmacy margins while elevating quality verification requirements through FDA's evolving dietary supplement enforcement priorities.
Growth Catalysts
- Millennial Wellness Prioritization:Health-conscious consumers aged 25-40 are driving recurring revenue through automated replenishment models that lock in lifetime value.
- CGMP Compliance Maturation:FDA's Current Good Manufacturing Practice regulations for dietary supplements are filtering out substandard operators and concentrating trust among verified brands.
- Probiotic Cold Chain Investment:Refrigerated logistics infrastructure expansion is unlocking viability for live-culture formulations previously constrained by temperature stability limitations.
Market Restraints
- Psyllium Husk Supply Volatility:Indian subcontinent weather patterns and export restrictions create raw material cost instability for fiber-based formulations.
- Third-Party Certification Burden:NSF International and USDA Organic verification programs impose six-figure annual compliance costs that disadvantage emerging entrants.
- Clinical Efficacy Skepticism:Gastroenterology professional societies' position statements questioning colon cleansing necessity limit physician recommendation channels.
Strategic Opportunities
- Telehealth Integration:Virtual gut health consultations are creating prescription-adjacent recommendation pathways for clinically positioned supplement brands.
- Personalized Microbiome Testing:At-home stool analysis kits are converging with customized probiotic formulation services to capture precision wellness spending.
- Clean Label Positioning:California's Proposition 65 enforcement and similar state-level contaminant standards are rewarding brands with transparent supply chain documentation.
Industry Challenges
- Refrigerated Last-Mile Logistics:Temperature-controlled fulfillment networks require capital deployment that strains direct-to-consumer unit economics outside dense urban corridors.
- Detox Claim Substantiation:State attorney general actions against unsubstantiated marketing language are forcing wholesale creative asset revisions and channel strategy overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colon Cleansing Supplements Market |
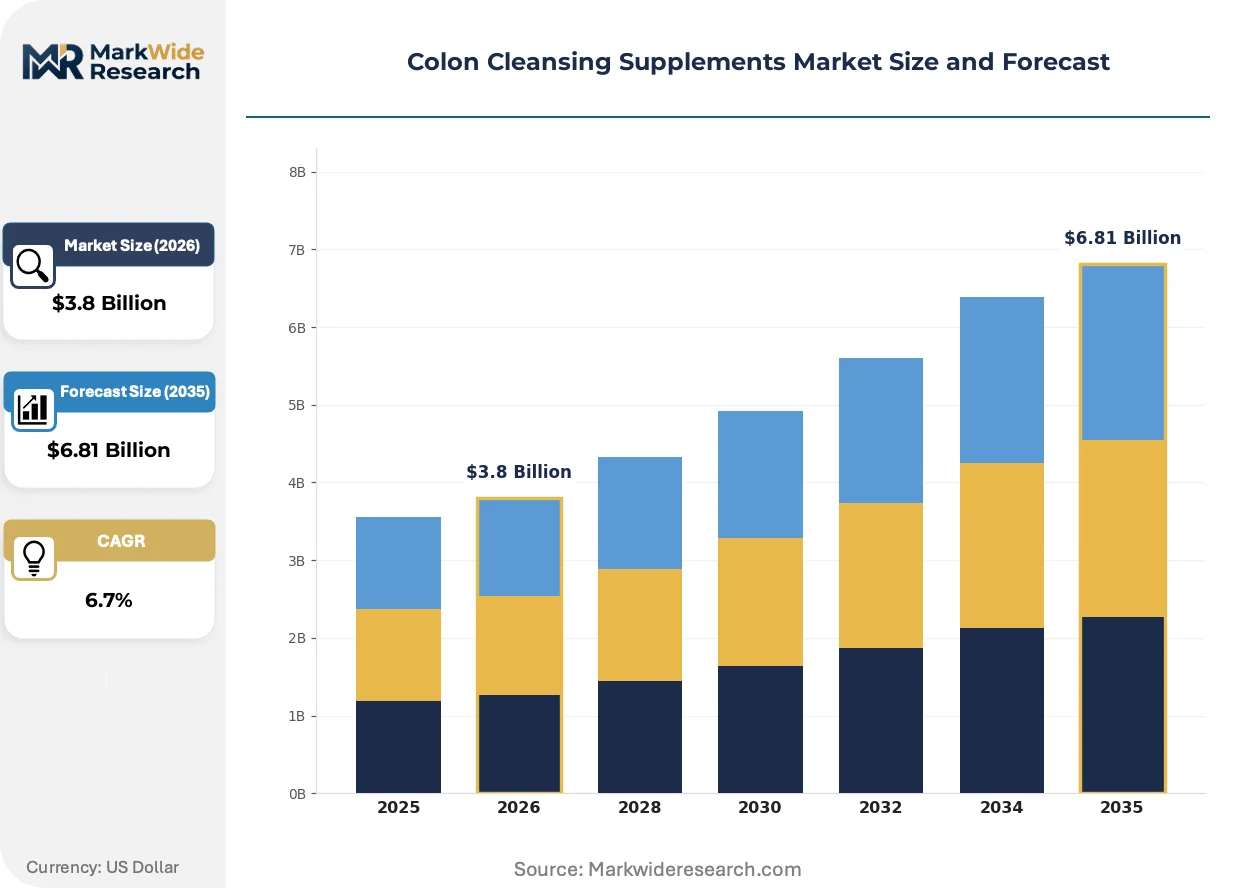
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powders, Liquids, Gummies Active Ingredient: Fiber, Probiotics, Herbal Extracts, Enzymes Application: Detoxification, Digestive Health, Weight Management, Constipation Relief Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Health Plus Inc, Irwin Naturals, Vita Balance Inc, Dr. Tobias Colon, Nature’s Secret, Renew Life, Garden of Life, Nature’s Bounty Inc, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colon Cleansing Supplements Market Evolving Landscape
Formulation science and distribution infrastructure are undergoing parallel transformation as live-culture viability, clean label verification, and subscription retention mechanics become competitive battlegrounds.
Enteric-coated delivery systems utilizing pH-responsive polymers are rendering obsolete standard gelatin capsules that degrade in stomach acid before reaching intestinal target sites. Functional medicine practitioners and biohacker communities are accelerating adoption of these advanced delivery formats. The technology is compressing efficacy differentiation timelines between pharmaceutical-grade and conventional supplement positioning.
REACH regulation amendments targeting microplastic contamination in ingestible products are forcing reformulation of synthetic excipients and coating materials across European supply chains. Manufacturers serving EU markets are accelerating migration toward plant-based capsule alternatives ahead of enforcement phase-ins. Fiber-matrix products with certified plastic-free packaging are commanding shelf preference at German and French pharmacy chains.
Wellness influencers are shifting audience monetization from affiliate commission models toward owned supplement brands with vertically integrated fulfillment. This creator-to-commerce pipeline is disintermediating legacy wholesale relationships that historically gated market access. Southern California and Austin metro clusters demonstrate the highest concentration of these influencer-operated direct-to-consumer launches.
Colon Cleansing Supplements Market Segmentation
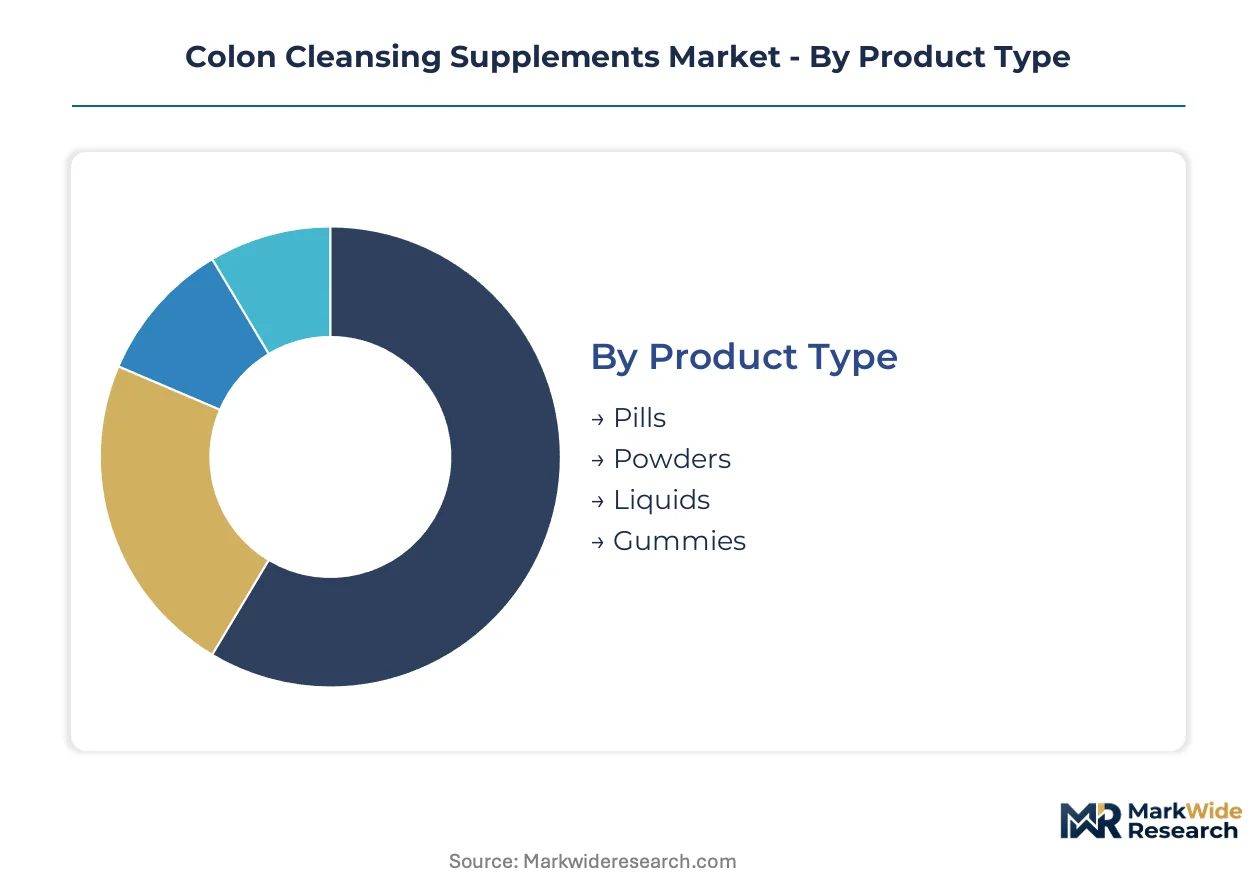
Segmentation in colon cleansing supplements reveals divergent margin profiles and channel requirements across delivery formats and active ingredient technologies. Formulation stability, temperature sensitivity, and dosing convenience create distinct operational footprints that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across delivery formats, with probiotic liquids requiring cold-chain troubleshooting and powder formats demanding mixing guidance that elevates customer support costs.
- Pills:Encapsulated formulations deliver standardized psyllium husk or senna sennoside doses in gelatin or vegetable-based shells. United States pharmacy chains favor blister-pack pills for shelf stability and theft deterrence, though enteric-coated variants command manufacturing complexity premiums.
- Powders:Bulk fiber matrices allow dose customization and rapid dissolution in beverages. Direct-to-consumer subscription models concentrate demand here, as automated replenishment offsets the format's bulk shipping cost disadvantage.
- Liquids:Pre-mixed solutions with aloe vera or magnesium citrate offer immediate bioavailability. Temperature-controlled logistics constrain distribution to urban corridors with viable cold-chain infrastructure.
- Gummies:Pectin-based chewables mask botanical bitterness with flavor masking. Children's formulations and travel convenience segments drive adoption despite higher per-dose manufacturing costs.
By volume, Pills leads. By growth pace, Gummies is ahead.
Active Ingredient:
Cost tier stratification separates commodity fiber from precision probiotic cultures, with certification requirements amplifying price spreads between basic and premium ingredient grades.
- Fiber:Psyllium husk and methylcellulose matrices provide mechanical bulk that accelerates intestinal transit. Indian export volatility and USDA Organic certification premiums shape procurement strategies for brands competing on clean label positioning.
- Probiotics:Live Lactobacillus and Bifidobacterium cultures require refrigerated supply chains from fermentation through last-mile delivery. Cold chain maturation is unlocking viability for strains previously limited to clinical settings.
- Herbal Extracts:Standardized senna sennosides, cascara sagrada, and aloe latex deliver stimulant laxative effects. California Proposition 65 enforcement and FDA warning letter patterns constrain permissible marketing language.
- Enzymes:Protease, lipase, and cellulase blends target macronutrient breakdown rather than mechanical cleansing. Functional medicine practitioner channels concentrate demand for these premium-positioned formulations.
Fiber dominates installed base. Probiotics climbs the fastest.
Application:
Customer type divergence separates acute intervention seekers from routine wellness maintainers, with subscription retention mechanics favoring chronic-use positioning over episodic detox marketing.
- Detoxification:Marketing emphasizes toxin elimination and metabolic reset claims. State attorney general actions against unsubstantiated language are forcing wholesale creative revisions and channel strategy overhauls.
- Digestive Health:Routine microbiome maintenance drives recurring revenue through automated replenishment. Millennial wellness prioritization concentrates demand in direct-to-consumer platforms with personalized recommendation engines.
- Weight Management:Satiety and bloating reduction claims position fiber matrices as adjuncts to caloric restriction. Telehealth-integrated brands leverage virtual gut health consultations for prescription-adjacent recommendations.
- Constipation Relief:Acute stimulant laxative use targets episodic need with rapid onset requirements. Gastroenterology professional society skepticism limits physician recommendation channels for chronic use.
Digestive Health leads by volume. Detoxification faces regulatory compression.
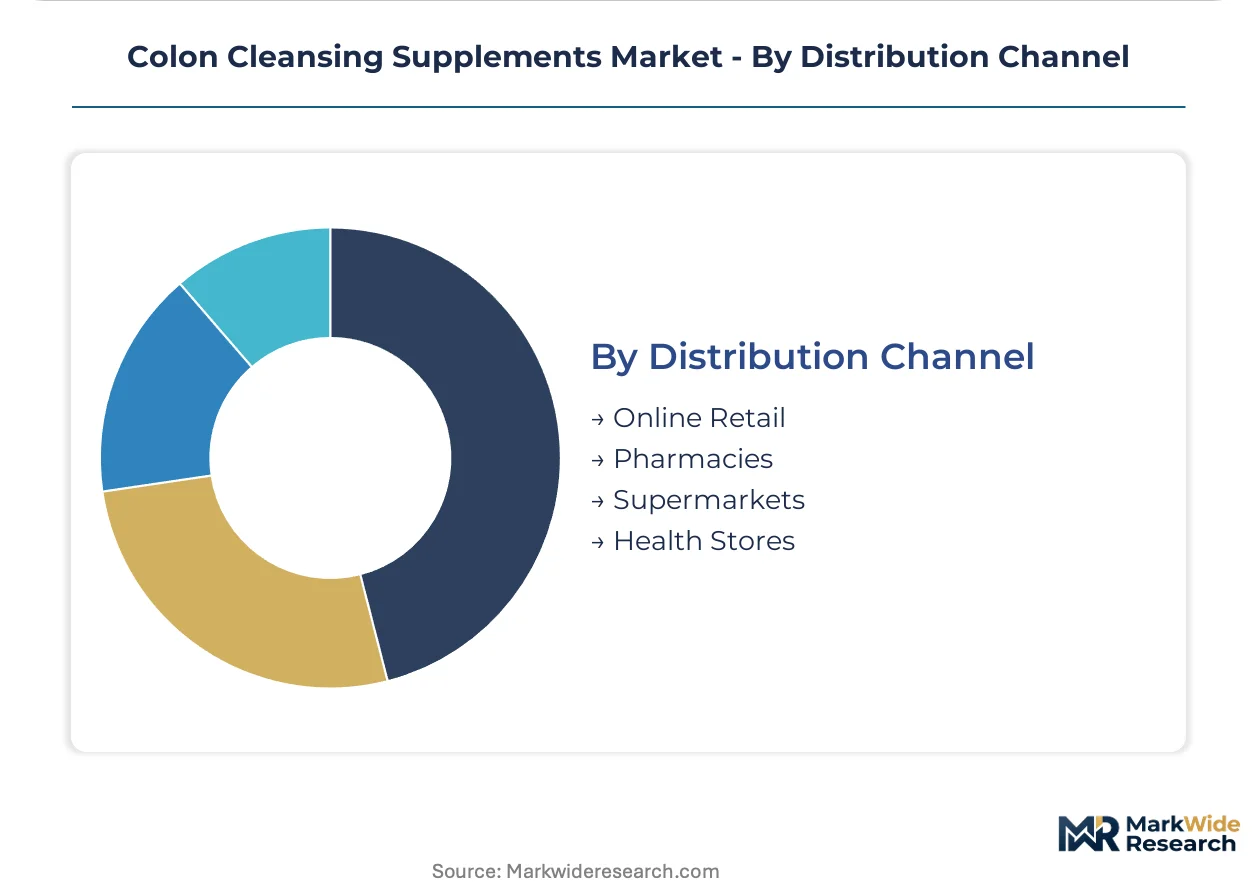
Distribution Channel:
Supply concentration in United States retail pharmacy chains contrasts with fragmented online fulfillment, where influencer-operated brands bypass legacy wholesale gatekeeping.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription-based replenishment with personalized microbiome test integration. Southern California and Austin metro clusters demonstrate highest influencer brand launch concentration.
- Pharmacies:CVS, Walgreens, and Rite Aid chains demand NSF International certification and slotting fees that disadvantage emerging entrants. Health Plus Inc leverages established relationships for premium shelf placement.
- Supermarkets:Mass-market fiber products compete on unit economics in high-velocity grocery environments. NOW Foods competes through manufacturing scale and vertically integrated production cost control.
- Health Stores:Whole Foods and independent natural retailers prioritize USDA Organic and plastic-free packaging credentials. REACH regulation amendments on microplastic contamination shape European supply chain migration.
Pharmacies lead by volume. Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement priorities and state-level attorney general actions are tightening quality verification requirements across North American markets. European REACH amendments on microplastic contamination are accelerating plant-based packaging migration. Cold-chain infrastructure investments in Asia-Pacific urban corridors are unlocking probiotic viability previously constrained by temperature stability limitations.
United States
Wellness-focused millennials aged 25-40 drive recurring revenue through subscription-based direct-to-consumer platforms with automated replenishment models. California Proposition 65 enforcement and state attorney general actions against unsubstantiated detox claims are reshaping permissible marketing language. Southern California and Austin metro clusters demonstrate the highest concentration of influencer-operated direct-to-consumer supplement launches.
Germany
REACH regulation amendments targeting microplastic contamination in ingestible products are forcing reformulation of synthetic excipients and coating materials across European supply chains. ECHA enforcement timelines are accelerating manufacturer migration toward plant-based capsule alternatives ahead of phase-in deadlines. Fiber-matrix products with certified plastic-free packaging command shelf preference at pharmacy chains in Berlin and Munich.
India
Psyllium husk export volatility from Indian subcontinent weather patterns creates raw material cost instability for fiber-based formulation manufacturers worldwide. FSSAI dietary supplement regulations and BIS quality standards are elevating compliance thresholds for domestic and export-oriented producers. Processing facilities in Gujarat and Rajasthan concentrate psyllium cultivation and primary fiber extraction operations.
Japan
Functional food regulatory frameworks under PMDA and Ministry of Health, Labour and Welfare oversight enable specific health claim approvals that differentiate premium-positioned gut health products. METI-supported cold-chain logistics investments are expanding refrigerated last-mile delivery coverage in Greater Tokyo and Osaka metropolitan areas. Probiotic culture viability standards exceed regional benchmarks, concentrating high-margin live-culture formulation demand.
Australia
TGA complementary medicine regulations enforce manufacturing quality standards that align with FDA CGMP frameworks, facilitating dual-market certification strategies for export-oriented brands. At-home microbiome testing kit adoption is converging with customized probiotic services in Sydney and Melbourne wellness markets. Clean label positioning and transparent supply chain documentation reward brands seeking pharmacy retail access.
Colon Cleansing Supplements Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Established retail pharmacy relationships and direct-to-consumer subscription platforms represent distinct control points. Three archetypes dominate: vertically integrated manufacturers with captive fiber sourcing, formulation specialists leveraging herbal expertise for premium positioning, and scale-driven operators competing on unit economics. Strategic moves concentrate on backward integration into raw material supply and cold-chain infrastructure partnerships for live-culture viability.
Within the scale-driven tier, NOW Foods exemplifies manufacturing footprint consolidation through in-house production control from fiber sourcing through finished packaging. Health Plus Inc and Irwin Naturals occupy positions at opposite ends of the channel spectrum—one anchoring conventional pharmacy shelf presence, the other commanding premium positioning through specialized formulation expertise. These three represent the competitive tension between access, scale, and specialization that defines current market structure.
| Leading Market Players |
|---|
| Health Plus Inc |
| Irwin Naturals |
| Vita Balance Inc |
| Dr. Tobias Colon |
| Nature's Secret |
| Renew Life |
| Garden of Life |
| Nature's Bounty Inc |
| NOW Foods |
| Others |
Value Network & Pricing Analysis
Indian psyllium husk export volatility determines both pricing tier spreads and supply chain shape, as fiber-based formulations anchor economy positioning while probiotic cold-chain investments push premium tiers toward refrigerated logistics infrastructure.
Pricing Analysis
Certification level creates the primary spread between economy fiber matrices and premium live-culture formulations. Three-tier pricing structure across premium, standard, and economy levels separates NSF-verified probiotic subscriptions from conventional pharmacy pills and bulk powder generics. Cost compression in standard-tier fiber products intensifies because Indian export restrictions and weather-driven crop variability squeeze raw material margins. Direct-to-consumer subscription buyers show lowest price sensitivity, while supermarket mass-market purchasers drive volume through unit economics discipline.
Supply Chain Analysis
Extended payment terms from Indian psyllium processors and supply-chain finance facilities at major distributors shape working capital structures for mid-tier brands. Raw material sourcing draws from India, China, and domestic fermentation facilities for probiotic cultures. Formulations rest on psyllium husk, standardized senna extracts, and live Lactobacillus strains as core inputs. Single-source vulnerability concentrates in Gujarat and Rajasthan processing clusters for fiber matrices. Distribution runs through direct-to-consumer cold-chain platforms, pharmacy chain slotting agreements, and mass-market retail wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colon cleansing supplements sit in early-cycle expansion as refrigerated probiotic viability unlocks precision wellness spending previously constrained by temperature stability limitations.
For Market Incumbents: Pre-empt influencer-operated direct-to-consumer launches by securing exclusive cold-chain partnerships in Southern California and Austin metro clusters. Invest in USDA Organic certification and NSF International verification to defend pharmacy shelf positioning against emerging clean-label entrants. Backward integration into captive psyllium sourcing mitigates Indian export volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in personalized microbiome testing convergence with customized probiotic services, the most penetrable white-space segment. Target telehealth-integrated recommendation pathways for clinically positioned digestive health formulations. Deploy subscription-first go-to-market mechanics with automated replenishment to lock lifetime value before incumbents adapt retention infrastructure. For Investors and Strategic Acquirers: FDA evolving dietary supplement enforcement priorities reshape the acquisition landscape by elevating compliance costs that filter substandard operators. Long-term viability favors vertically integrated manufacturers with in-house fermentation capacity and certified organic fiber sourcing. Watch state attorney general action patterns against unsubstantiated detox claims as the signal indicating regulatory compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Refrigerated last-mile networks unlock probiotic viability in dense urban corridors. |
| USDA Organic Certification Investment | Clean label positioning commands shelf preference at Whole Foods and natural retailers. |
| Telehealth Platform Integration | Virtual gut health consultations create prescription-adjacent recommendation pathways. |
| Backward Integration into Fiber Sourcing | Captive psyllium supply mitigates Indian export volatility and cost instability. |
| Subscription Retention Technology | Automated replenishment mechanics lock lifetime value in millennial wellness segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA warning letter databases, NSF International certification registries, and customs trade data for psyllium husk imports. Conversations with dietary supplement brand managers, pharmacy category buyers, cold-chain logistics operators, and functional medicine practitioners informed demand-side dynamics. Secondary sources included USDA Organic certification records, state attorney general enforcement actions, and refrigerated logistics capacity disclosures. Bottom-up segment sizing triangulated against top-down market value estimates.
Forecast inputs span product type segmentation across pills, powders, liquids, and gummies; active ingredient technology tiers from commodity fiber to live-culture probiotics; application positioning from acute constipation relief to routine digestive maintenance; and distribution channel evolution between direct-to-consumer platforms and conventional pharmacy chains. CAGRs were derived from trend extrapolation with cross-validation against adoption curve modeling. Industry-specific inputs incorporated cold-chain infrastructure buildout timelines and probiotic viability standards.
Stress conditions across Indian monsoon variability, FDA enforcement intensity, and refrigerated logistics cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about millennial wellness prioritization persistence and subscription retention mechanics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Japan Probiotics Market