
 Probiotics Market | 2026-2036
Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotics Market Analysis
Functional beverage formulation is pivoting toward clinically validated strains as consumers demand proof-backed wellness claims. Novonesis A/S leverages its microbial science platform to supply precision strains for dairy and non-dairy applications. Yakult Honsha Co., Ltd. anchors its position through dedicated Lactobacillus casei Shirota research and direct-to-consumer distribution infrastructure in Asia. Nestlé S.A. competes by extending probiotic integration across infant nutrition and senior care portfolios.
Probiotics comprise live microorganisms, predominantly Lactobacillus and Bifidobacterium species, that confer health benefits when administered in adequate doses, typically measured in colony-forming units. These organisms colonize the gastrointestinal tract to modulate microbiome composition, enhance nutrient absorption, and support mucosal immune function. Bacterial Strains command the largest value share due to pharmaceutical-grade manufacturing requirements and patent-protected formulations, while Dietary Supplements exhibit the fastest trajectory as direct-to-consumer brands bypass traditional retail gatekeepers. Fermented Foods retain volume leadership in emerging economies where traditional consumption patterns align with lower price points.
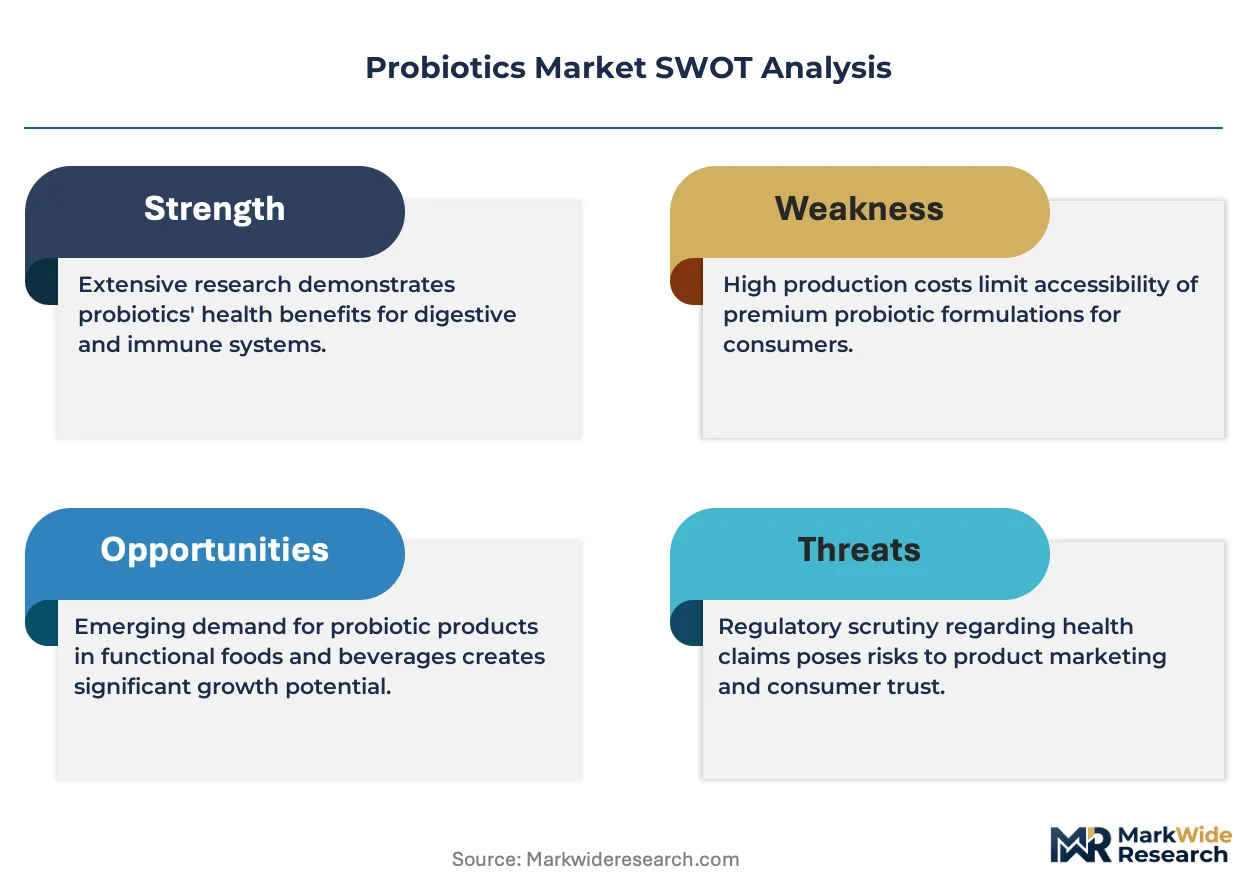
FDA oversight of dietary supplement health claims and EFSA's strict substantiation requirements under the Nutrition and Health Claims Regulation constrain marketing language and mandate clinical validation. Health Canada and Japan's Consumer Affairs Agency impose additional strain-specific approval pathways that fragment product registration timelines. Stakeholders must monitor evolving microbiome research standards and preempt regulatory divergence between major jurisdictions to sustain cross-border product portfolios.
Market Dynamics
Strain-specific substantiation requirements under EFSA and FDA frameworks are compressing marketing timelines and forcing manufacturers to front-load clinical investment before product launch. This regulatory tightening is reshaping competitive positioning toward vertically integrated players with captive research infrastructure.
Growth Catalysts
- EFSA Health Claims Regulation:Harmonized approval pathways across EU member states reduce fragmentation for compliant entrants, accelerating cross-border scale for validated products.
- Gut-brain axis research:Expanding clinical evidence linking microbiome modulation to cognitive function is electrifying demand from nutraceutical formulators seeking differentiation.
- Direct-to-consumer channels:Subscription-based delivery models bypass traditional pharmacy retail, capturing margin and consumer data simultaneously.
Market Restraints
- Live culture stability:Cold chain requirements and shelf-life degradation constrain distribution radius and inflate logistics costs for ambient retail placement.
- Strain patent cliffs:Expiring intellectual property on foundational Lactobacillus and Bifidobacterium varieties erodes exclusivity premiums and invites commoditization.
- FDA substantiation timelines:New dietary ingredient notification pathways extend time-to-market by 18-24 months, freezing capital in pre-revenue development phases.
Strategic Opportunities
- Personalized nutrition convergence:Microbiome testing kits paired with strain-matched supplements create recurring revenue architectures and defensible consumer lock-in.
- Senior care integration:Immune-senescence applications in aged-care facilities present white-space demand with limited incumbent competition.
- India FSSAI strain registration:Streamlined approval processes under 2022 framework amendments reduce entry barriers for documented probiotic cultures.
Industry Challenges
- Clinical trial recruitment:Strain-specific endpoint validation requires large cohort sizes for statistical power, inflating study costs and extending development cycles.
- Cross-jurisdiction label compliance:Divergent colony-forming unit disclosure requirements between Health Canada and Japan's Consumer Affairs Agency force SKU proliferation or conservative lowest-common-denominator formulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotics Market |
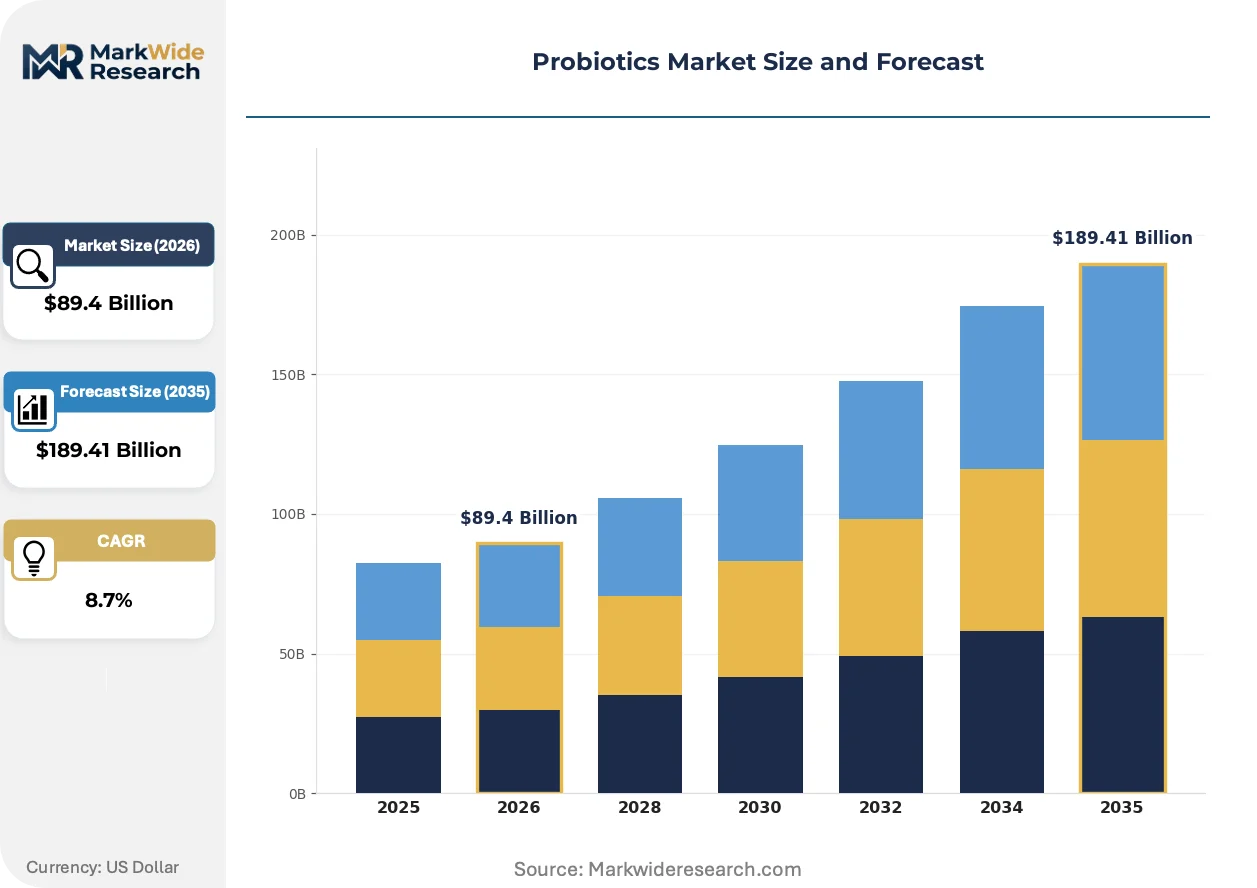
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $189.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Strains, Prebiotics, Fermented Foods, Dietary Supplements End User: Healthcare Providers, Nutritional Professionals, Fitness Enthusiasts, General Consumers Application: Digestive Health, Immune Support, Mental Wellbeing, Skin Health Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Novonesis A/S, Yakult Honsha Co., Ltd., Nestlé S.A., Groupe Danone, Archer Daniels Midland Company (ADM), International Flavors & Fragrances Inc., Chr. Hansen Holding A/S, Lallemand Inc., Kerry Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotics Market Emerging Trajectories
Live biotherapeutic products are migrating from wellness positioning toward regulated therapeutic categories, compressing the historical boundary between supplements and pharmaceuticals. This reclassification pressure is forcing infrastructure investments that favor scaled manufacturers.
Next-generation sequencing of fecal microbiota is electrifying strain discovery pipelines, enabling isolation of novel taxa with targeted metabolic functions. Pharmaceutical-grade manufacturers are adopting these platforms to build proprietary strain banks. The technology is compressing development timelines from environmental sampling to commercial production.
EFSA's 2023 updated guidance on beneficial physiological effect substantiation tightens clinical endpoint requirements for gut health claims. Manufacturers must now demonstrate statistically significant improvements in validated biomarkers rather than general well-being measures. Infant nutrition applications face the steepest compliance burden given vulnerable population protections.
Consumer purchasing of probiotics through telehealth platforms and wellness app ecosystems is displacing pharmacy-centric discovery. Digital-native brands capture first-mover advantage through microbiome test integration and algorithmic strain matching. China and Germany exhibit the fastest channel migration as mobile health adoption accelerates.
Probiotics Market Segmentation
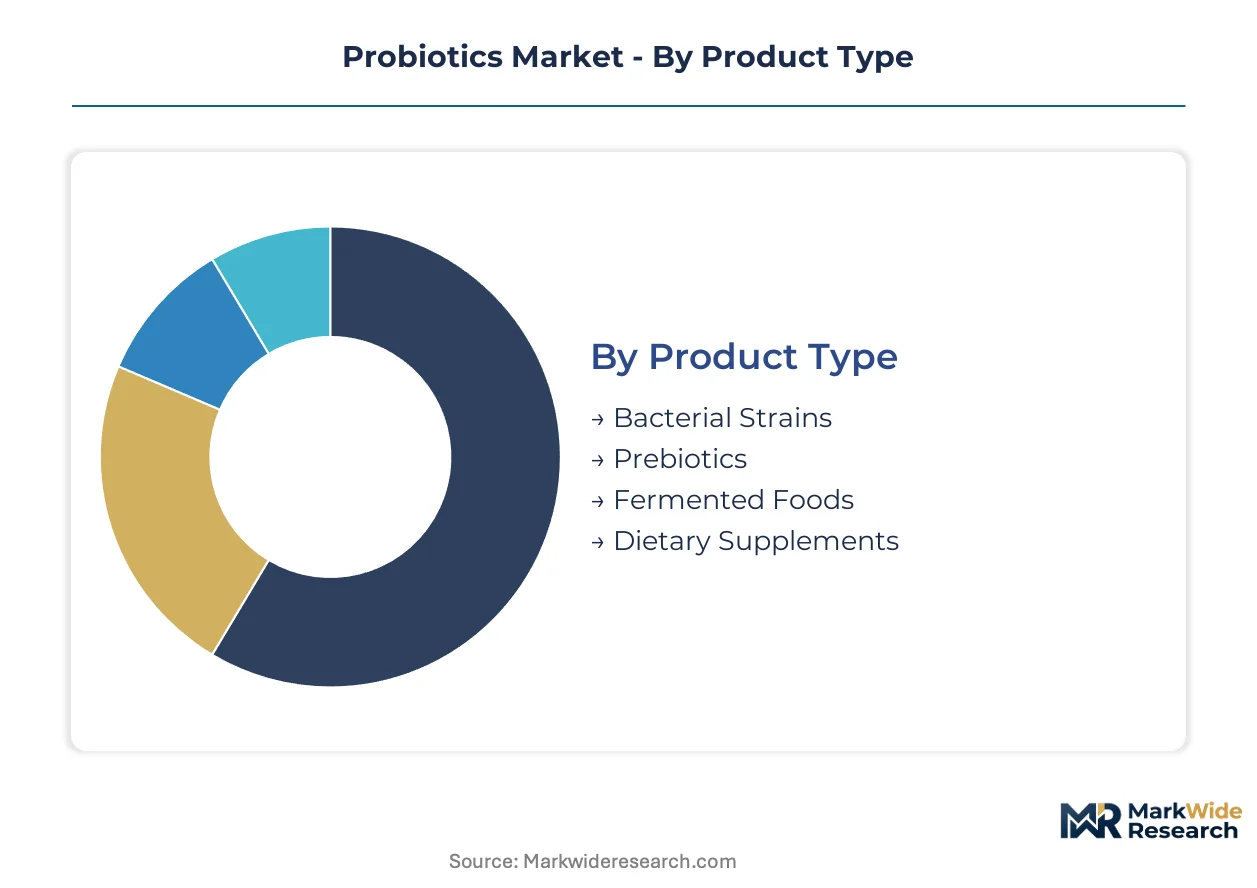
Probiotic buyers exhibit sharply divergent technical sophistication and substantiation requirements across use cases. Healthcare gatekeepers demand strain-specific clinical documentation, while mass-market consumers respond to wellness positioning and convenience formats. These splits determine pricing architecture, regulatory pathway selection, and channel investment priorities for manufacturers.
Product Type:
Cost tier separates pharmaceutical-grade purchasers from commodity buyers in this category.
- Bacterial Strains:Live microorganisms, predominantly Lactobacillus and Bifidobacterium species, cultivated under GMP conditions with CFU counts typically exceeding 10 billion per dose. Pharmaceutical manufacturers in Germany and the United States anchor demand here, driven by patent-protected formulations and FDA new dietary ingredient notification requirements that freeze out undercapitalized competitors.
- Dietary Supplements:Encapsulated or tableted probiotic preparations combining multiple strains with prebiotic fibers. Direct-to-consumer brands in China bypass traditional pharmacy retail through subscription models, capturing margin and consumer data simultaneously as telehealth platforms displace brick-and-mortar discovery.
- Prebiotics:Non-digestible oligosaccharides that selectively nourish beneficial gut bacteria. Functional food formulators in Japan integrate these into synbiotic products.
- Fermented Foods:Traditional preparations including yogurt, kefir, and kimchi containing live cultures. Volume concentrates in India and Southeast Asia where price sensitivity favors established consumption patterns over premium supplement formats.
Bacterial Strains leads volumes today; Dietary Supplements is gaining share fastest.
End User:
Application maturity determines whether buyers accept wellness claims or demand therapeutic-grade evidence.
- Healthcare Providers:Hospitals, clinics, and physician networks prescribing probiotics for antibiotic-associated diarrhea or Clostridioides difficile prevention. Reimbursement pathways in France and the Netherlands require EFSA-compliant health claim substantiation, compressing vendor pools to vertically integrated manufacturers with captive clinical infrastructure.
- Nutritional Professionals:Registered dietitians and sports nutritionists recommending strain-specific protocols for athletic performance or metabolic conditioning. Demand clusters in Australia and the United Kingdom where professional certification bodies mandate continuing education on microbiome science.
- Fitness Enthusiasts:Amateur and competitive athletes seeking gut integrity for nutrient absorption and immune resilience during training loads.
- General Consumers:Mass-market purchasers motivated by wellness trends and preventive health positioning. Price elasticity varies sharply by geography.
General Consumers dominates transaction volumes; Healthcare Providers commands the steepest price premiums.
Application:
Regulatory scrutiny intensity fragments this category between approved health claims and speculative wellness positioning.
- Digestive Health:Established indications including irritable bowel syndrome management, constipation relief, and traveler's diarrhea prevention. EFSA's 2023 updated guidance on beneficial physiological effect substantiation tightens biomarker requirements here, forcing manufacturers to demonstrate statistically significant improvements rather than general well-being measures.
- Immune Support:Strain-specific formulations targeting respiratory infection reduction and vaccine adjuvant effects. Senior care facilities in Japan and Germany present white-space demand with limited incumbent competition as immune-senescence applications gain clinical validation.
- Mental Wellbeing:Gut-brain axis applications addressing anxiety, depression, and cognitive function. Emerging clinical evidence is electrifying nutraceutical formulator interest despite regulatory uncertainty.
- Skin Health:Topical and oral probiotics for atopic dermatitis and acne modulation. Cosmetic-grade manufacturing requirements in South Korea shape competitive entry.
Digestive Health retains the largest installed base; Mental Wellbeing is climbing the fastest as microbiome-neuroscience research accelerates.
Distribution Channel:
Customer acquisition cost and margin retention split this category between high-touch and scalable formats.
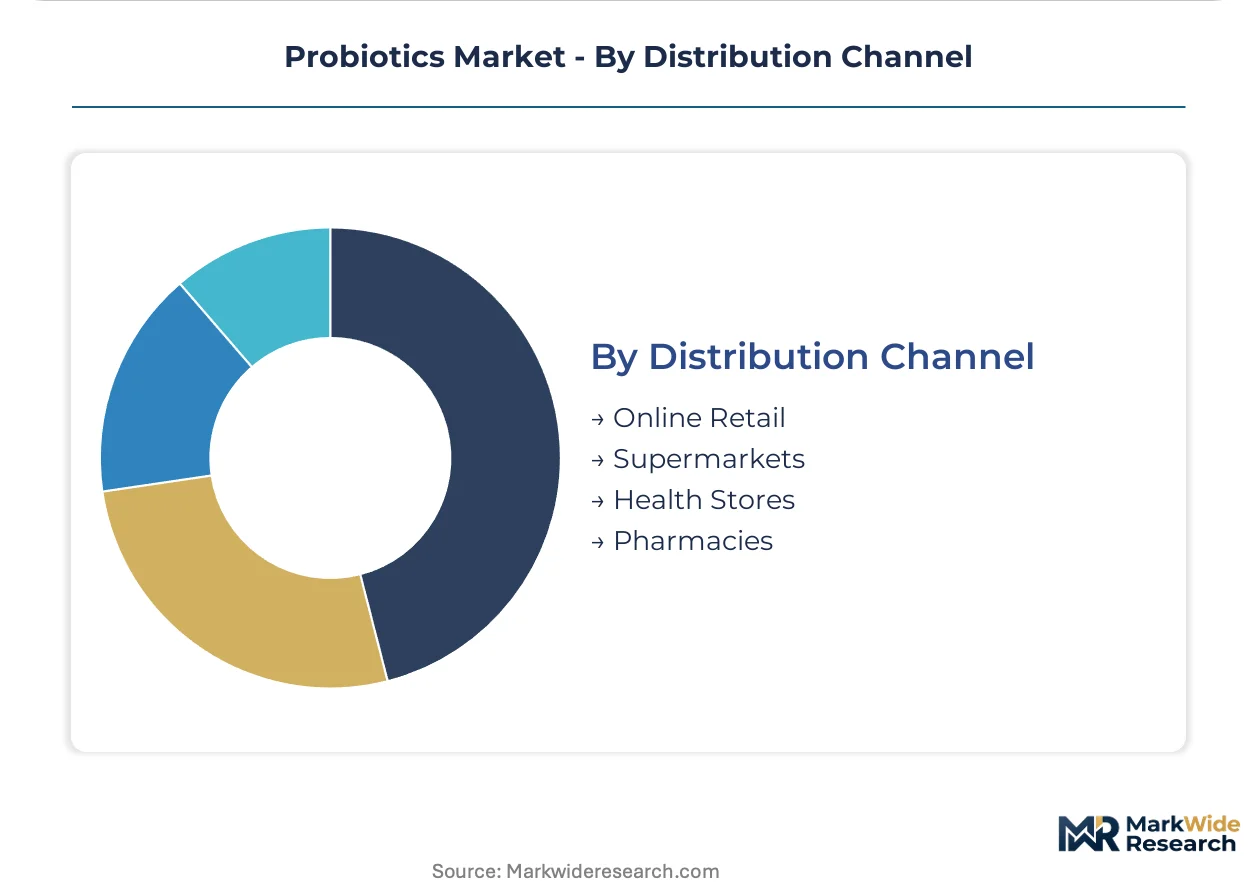
- Online Retail:Direct-to-consumer platforms, subscription services, and marketplace listings. Digital-native brands in China and Germany capture first-mover advantage through microbiome test integration and algorithmic strain matching as mobile health adoption accelerates.
- Supermarkets:Mass-market retail placement for fermented foods and entry-level supplements. Shelf-space negotiations in the United States favor manufacturers with national advertising budgets and slotting fee capacity.
- Health Stores:Specialty retailers emphasizing organic certification and strain transparency. Staff training requirements in Canada filter for technically sophisticated vendors.
- Pharmacies:Professional recommendation environments for clinically validated products. Cold chain capabilities constrain ambient retail placement for live culture stability.
Supermarkets moves the highest unit volumes; Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping probiotic manufacturing footprints as companies relocate production to jurisdictions with streamlined strain approval pathways. Cost-of-compliance gaps between the FDA's extended notification timelines and India's accelerated FSSAI framework are driving facility investment decisions. This migration concentrates capacity in countries offering faster time-to-market without sacrificing quality benchmarks.
United States
Healthcare provider demand for clinically validated strains anchors the premium segment, with hospital procurement networks requiring extensive documentation. FDA new dietary ingredient notifications stretch pre-market timelines to 18-24 months, freezing capital in development phases. The Greater Boston biotech corridor hosts multiple precision fermentation facilities expanding GMP capacity for live culture production.
Germany
EFSA-compliant manufacturers capture cross-border EU scale through harmonized health claim substantiation requirements. The country's national pharmaceutical regulator enforces strict GMP standards for bacterial strain cultivation. Bavaria's industrial biotech cluster around Munich anchors pharmaceutical-grade probiotic production serving continental healthcare networks.
China
Direct-to-consumer subscription models bypass traditional pharmacy retail, capturing margin and consumer data through mobile health platforms. SAMR oversight of functional food claims tightens marketing language while permitting faster domestic strain registration than import pathways. Yangtze River Delta manufacturing hubs around Shanghai scale precision fermentation for both domestic consumption and export markets.
India
Traditional fermented food consumption patterns sustain volume leadership in mass-market segments where price sensitivity favors established formats over premium supplements. FSSAI's 2022 framework amendments streamlined strain registration processes, reducing entry barriers for documented probiotic cultures. Maharashtra's dairy processing belt around Pune integrates live culture production into existing cold chain infrastructure.
Japan
Senior care facility demand for immune-senescence applications presents white-space growth with limited incumbent competition. The Consumer Affairs Agency imposes strain-specific approval pathways that fragment product registration timelines but reward compliant entrants with durable market positions. Tokyo-Osaka metropolitan corridors concentrate distribution infrastructure for direct-to-consumer delivery models.
Probiotics Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to front-load clinical investment through shared research infrastructure. The vendor base stratifies into three tiers: multinational conglomerates with captive fermentation capacity, mid-scale specialists with strain-specific patent portfolios, and regional formulators serving price-sensitive emerging markets. Two archetypes define competitive positioning: vertically integrated players controlling research-to-retail value chains, and platform suppliers licensing validated strains to third-party brands. M&A activity and capacity expansion constitute the dominant competitive moves, with acquisition targets selected for proprietary strain banks and geographic regulatory approvals.
Within the multinational tier, Novonesis A/S and Nestlé S.A. occupy positions exemplifying divergent strategic approaches to microbiome commercialization. Yakult Honsha Co., Ltd. anchors the specialist archetype through dedicated single-strain research infrastructure. These three entities represent distinct competitive vectors: precision fermentation platforms, diversified nutrition portfolios, and focused direct-to-consumer distribution systems respectively.
| Leading Market Players |
|---|
| Novonesis A/S |
| Yakult Honsha Co., Ltd. |
| Nestlé S.A. |
| Groupe Danone |
| Archer Daniels Midland Company (ADM) |
| International Flavors & Fragrances Inc. |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| Kerry Group PLC |
| Others |
Supply Flow & Price Mechanics
Hospital procurement networks demanding EFSA-compliant strain documentation compress vendor pools to vertically integrated manufacturers, forcing supply consolidation around captive GMP fermentation facilities and inflating price premiums for clinically validated products.
Pricing Analysis
Retailer markup layers separate pharmaceutical-grade purchasers from mass-market consumers in this category. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and cold chain capability. Pricing pressure stems from direct-to-consumer subscription models capturing margin and consumer data simultaneously. General consumers exhibit highest price sensitivity while healthcare providers accept therapeutic-grade premiums.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement networks mandate multi-supplier qualification for live culture stability. Supply concentrates in Germany, China, and India for precision fermentation capacity and traditional dairy processing infrastructure. Raw material dependencies include pharmaceutical-grade culture media, specialized packaging for ambient shelf-life, and cold chain logistics equipment. Single-source vulnerability runs through patent-protected strain banks. Distribution runs through direct-to-consumer platforms and pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: India's streamlined FSSAI strain registration offers faster time-to-market than FDA notification timelines, compressing capital freeze periods for entrants with documented cultures.
For Market Incumbents: Anchor market position through backward integration into proprietary strain banks and captive clinical infrastructure. Patent cliff erosion on foundational Lactobacillus varieties demands accelerated next-generation sequencing pipelines. Certification investment in EFSA-compliant health claim substantiation defends margin against commodity formulators.
For New Entrants and Emerging Players: Capture white-space demand in senior care immune-senescence applications and personalized nutrition microbiome testing convergence. India's FSSAI framework presents the most penetrable regulatory pathway for documented cultures. Go-to-market through telehealth platform integration bypasses pharmacy-centric discovery friction.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing proprietary strain portfolios and geographic regulatory approvals. Long-term viability hinges on live biotherapeutic product reclassification toward therapeutic categories. Acquisition target archetype: precision fermentation platforms with GMP capacity. Signal to watch: EFSA guidance evolution on gut-brain axis claim substantiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Strain-specific endpoint validation satisfies EFSA biomarker requirements for digestive health claims. |
| Regulatory Approval Pathway | FDA new dietary ingredient notification and FSSAI strain registration expand cross-border product portfolios. |
| Backward Integration | Captive GMP fermentation capacity insulates against live culture stability constraints and cold chain cost inflation. |
| Strategic Partnership | Microbiome testing kit integration creates recurring revenue architectures and algorithmic strain matching. |
| Geographic Expansion | India's dairy processing belt leverages existing cold chain infrastructure for mass-market fermented food distribution. |
Methodological Framework
Multiple input streams — regulatory affairs specialists at EFSA and FDA, hospital procurement managers, and direct-to-consumer brand executives — were reconciled against secondary validation from ClinicalTrials.gov strain registration databases, FSSAI framework amendments, and SEC filings from publicly traded nutrition conglomerates. Bottom-up strain volume estimates and top-down market sizing triangulated through cross-reference with customs records and pharmaceutical-grade manufacturing capacity disclosures.
Data-stream reconciliation across product type, end user archetype, application indication, and distribution channel segmentation generated volume and value outputs over the projection horizon. CAGRs derived from historical trajectory analysis and regulatory pathway velocity modeling. Industry-specific forecast inputs incorporated microbiome research publication velocity and strain patent expiration schedules.
Regulatory divergence between FDA and EFSA, clinical trial recruitment bottlenecks, and live culture stability technology breakthroughs are the dominant revision risks across the analysis window. Deviation in EFSA guidance evolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Global Enteric Softgel Capsules Market