
 South America Microbial Food Culture Market | 2026-2036
South America Microbial Food Culture Market Size, Share, and Industry Trends Forecast 2026-2036
South America Microbial Food Culture Market Analytics
The capital-intensity divergence between freeze-drying capabilities and basic fermentation capacity is unwinding competitive tiers across the region. Chr. Hansen Holding A/S leverages its proprietary strain banks to dominate premium starter culture supply for artisanal cheese producers. Lallemand Inc. anchors its position through distributed fermentation facilities in Argentina and southern Brazil. Corbion NV competes via specialized bio-preservative formulations tailored to clean-label meat processing demands.
Microbial food cultures comprise defined, live bacterial, yeast, or mold preparations cultivated under controlled conditions to inoculate, ferment, or preserve food matrices, typically standardized to colony-forming units per gram and maintained through lyophilization or frozen concentrate formats. Starter cultures within the product type category command the deepest margin pools due to strain exclusivity and long-term supply contracts with dairy cooperatives. The application dimension tilts heavily toward dairy products, where yogurt and cheese production absorb the bulk of volume, while beverages represent the fastest-expanding segment as kombucha and fermented juice formats gain shelf space in Brazilian retail channels.
ANVISA governs strain safety approvals and novel food ingredient registrations, while the Mercosur Food Code harmonizes cross-border standards for culture-containing products among member states. Brazil's national health surveillance agency recently tightened documentation requirements for probiotic strain identity, forcing importers to verify genomic sequencing data prior to market entry. Stakeholders must monitor pending regulatory alignment between Mercosur and Chilean standards, as divergence would fragment sourcing strategies for suppliers operating across Andean and Southern Cone markets.
Market Dynamics
ANVISA's tightened genomic documentation requirements for probiotic strain identity are forcing importers to restructure supply chains around verified sequencing data, compressing margins for distributors lacking in-house validation capabilities.
Growth Catalysts
- Starter culture adoption:Dairy cooperatives in Brazil's southeastern belt are locking in long-term supply contracts with culture suppliers to secure strain exclusivity for artisanal cheese production.
- ANVISA regulatory clarity:Updated food additive regulations, despite their stringency, are eliminating ambiguous approval pathways that previously delayed novel strain market entry.
- Fermented beverage expansion:Kombucha and fermented juice formats are capturing shelf space in Brazilian retail channels, pulling volume from traditional dairy applications.
Market Restraints
- Freeze-drying capital intensity:The equipment and energy costs for lyophilization capacity create a barrier separating integrated producers from basic fermentation operators.
- Strain bank concentration:Proprietary culture collections remain concentrated among a handful of European and North American suppliers, limiting regional sourcing alternatives.
- Mercosur regulatory fragmentation:Pending divergence between Mercosur Food Code standards and Chilean requirements threatens to complicate cross-border product registration.
Strategic Opportunities
- Argentine distributed fermentation:Underutilized biotechnology infrastructure in Córdoba and Buenos Aires provinces offers hub potential for serving Southern Cone markets.
- Clean-label meat bio-preservatives:Specialized culture formulations replacing synthetic preservatives are penetrating Brazilian processed meat channels ahead of regulatory mandates.
- Andean market penetration:Peru and Colombia maintain minimal domestic culture production, creating import-dependent demand for suppliers with Mercosur-registered strains.
Industry Challenges
- Genomic sequencing verification:The technical capability to conduct and document strain-level identification is scarce among regional distributors, forcing reliance on external laboratories.
- Cold chain integrity:Frozen concentrate formats require uninterrupted temperature control through last-mile distribution networks that remain underdeveloped in interior Brazil.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Microbial Food Culture Market |
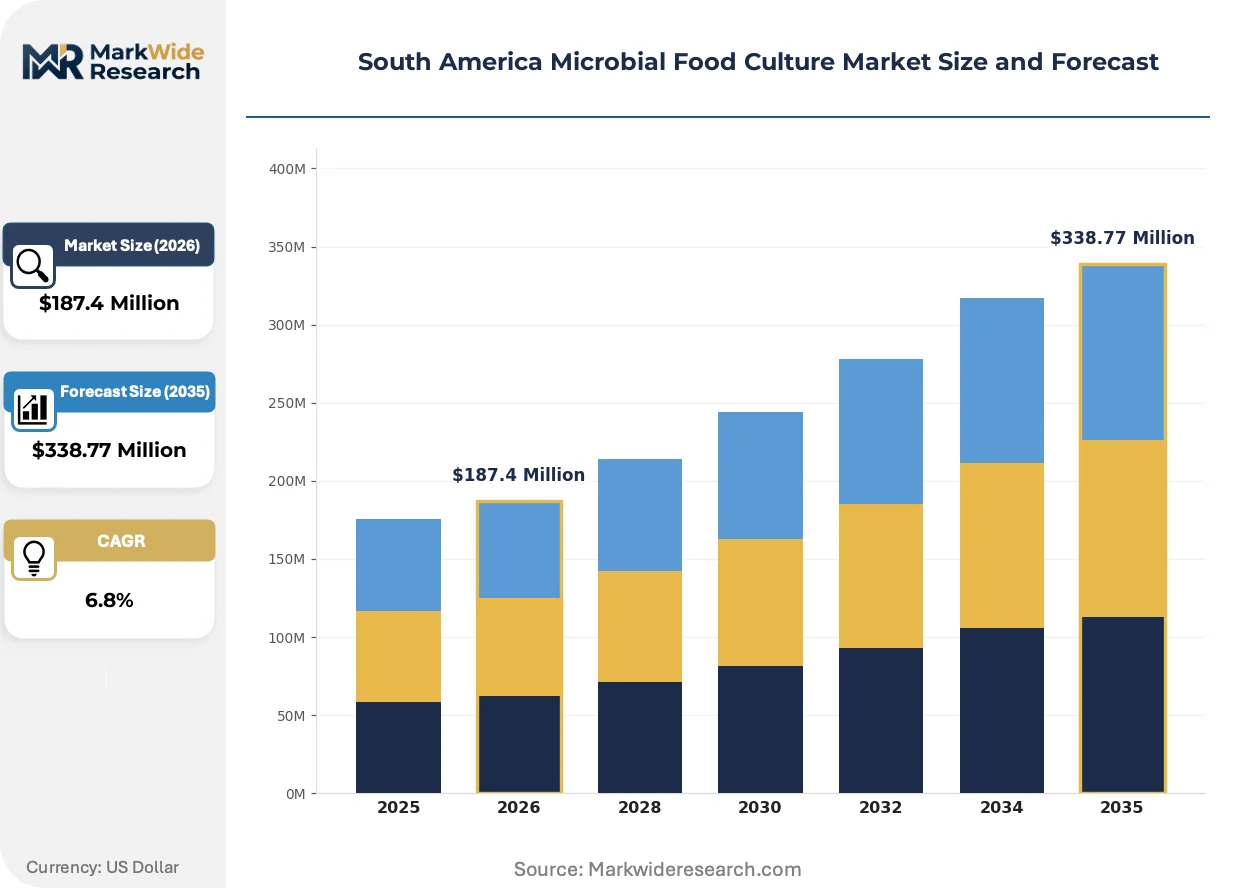
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
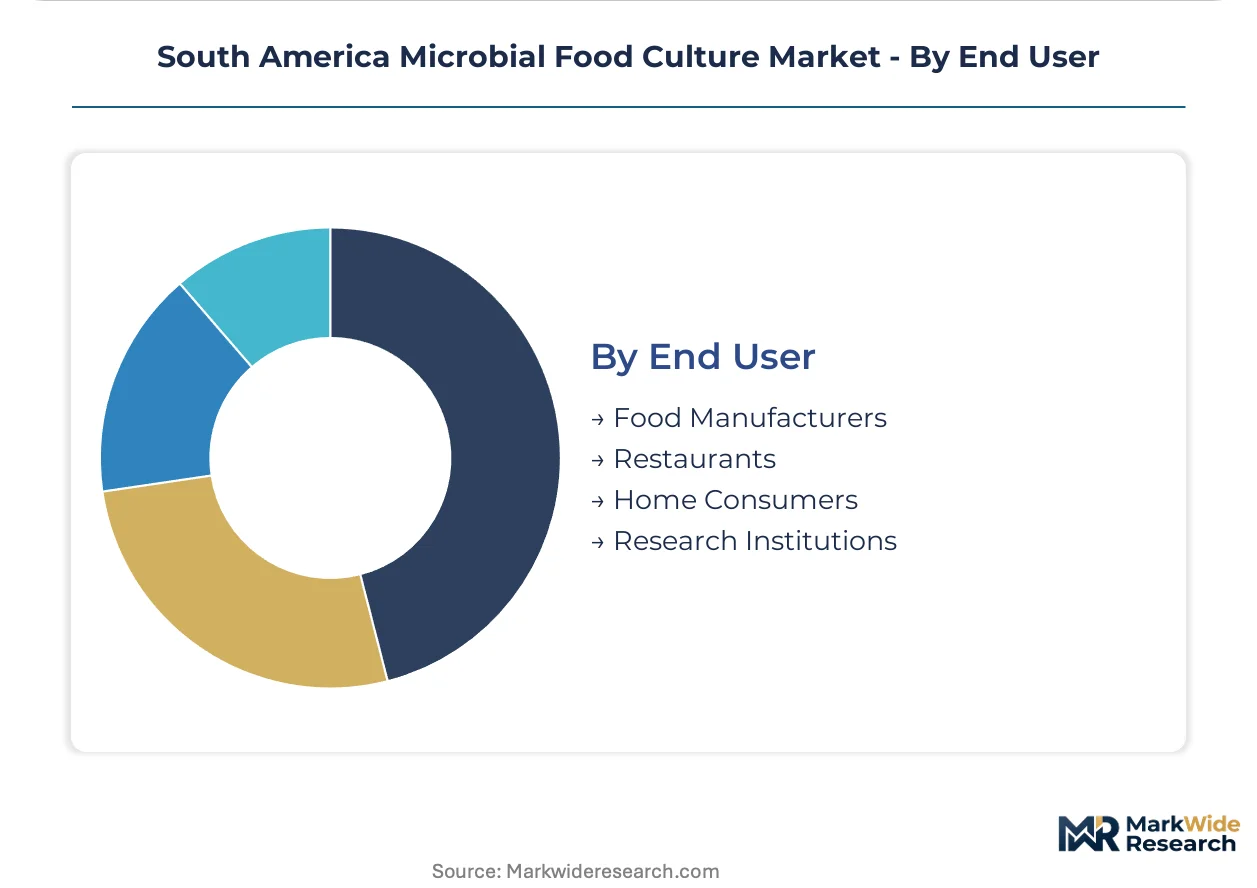
| Segmentation | Product Type: Probiotics, Fermented Products, Starter Cultures, Bio-Preservatives Application: Dairy Products, Bakery, Meat, Beverages Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Restaurants, Home Consumers, Research Institutions |
| Companies Covered | Chr. Hansen Holding A/S, Koninklijke DSM NV, Corbion NV, Lallemand Inc., IGEA S.r.l., Kerry Group plc, DuPont de Nemours, Inc., Novozymes A/S, CSK Food Enrichment, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Microbial Food Culture Market Evolving Landscape
Lyophilization technology advances and regulatory data requirements are converging to reshape how microbial cultures are standardized, documented, and delivered across South American food manufacturing networks.
Single-use bioreactor systems are supplanting stainless-steel fermentation infrastructure among mid-scale dairy culture producers. Argentine and southern Brazilian processors are adopting disposable vessel technology to reduce cross-contamination risk between strain batches. This shift is compressing the minimum efficient scale for viable culture production, enabling smaller cooperatives to bring formulation in-house.
ANVISA's probiotic strain identity verification mandate is forcing genomic sequencing documentation into standard import procedures. Industrial consequence includes extended pre-market approval timelines and elevated compliance costs for distributors without captive laboratory capabilities. Dairy and supplement segments are responding by consolidating supplier relationships around those with pre-validated strain portfolios.
Direct procurement from culture developers is displacing layered distributor networks among large Brazilian dairy cooperatives. Volume buyers are negotiating master service agreements that bundle technical support with supply commitments, bypassing traditional import intermediaries. This pattern is most visible in São Paulo and Minas Gerais states, where processor concentration enables sufficient order scale to justify direct relationships.
South America Microbial Food Culture Market Segmentation
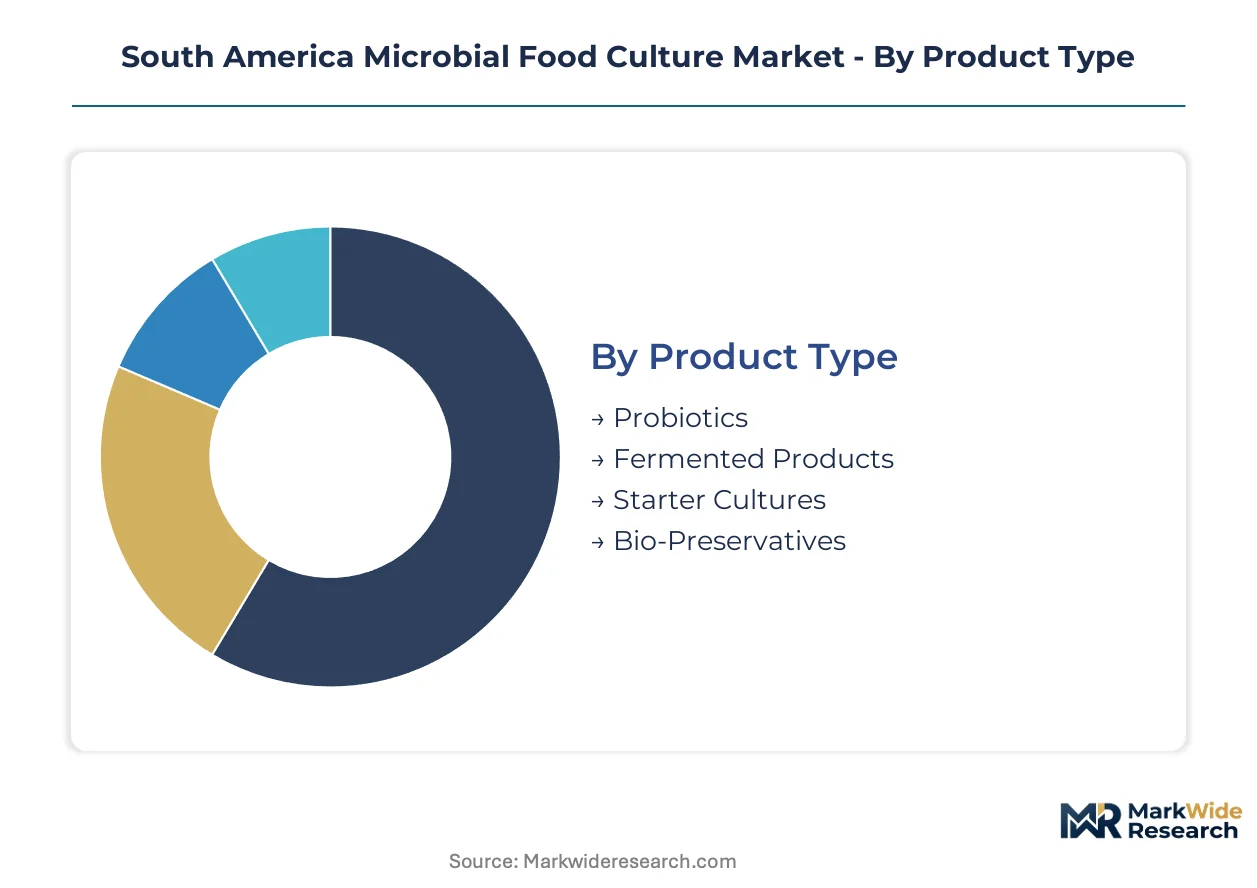
Microbial food culture procurement in South America fragments across distinct channel configurations. Each segment category carries divergent margin profiles and regulatory exposure, demanding tailored sourcing strategies from suppliers and end-users.
Product Type:
Freeze-dried concentrates and frozen formats reach dairy processors through diverging logistics networks, with lyophilized products tolerating longer distribution legs.
- Starter Cultures:Defined, live bacterial preparations standardized to colony-forming units per gram, typically maintained through lyophilization or frozen concentrate formats. Brazilian dairy cooperatives in São Paulo and Minas Gerais states are locking in long-term supply contracts to secure strain exclusivity for artisanal cheese production, though ANVISA's tightened genomic documentation requirements are compressing margins for distributors lacking in-house validation capabilities.
- Probiotics:Live microorganisms administered in adequate amounts to confer health benefits, requiring precise strain-level identification and stability documentation. Demand concentrates in Brazilian retail supplement channels and functional dairy applications, where ANVISA's probiotic strain identity verification mandate is forcing genomic sequencing documentation into standard import procedures.
- Fermented Products:Pre-fermented food matrices incorporating active cultures as processing inputs rather than standalone inoculants.
- Bio-Preservatives:Culture-derived antimicrobial formulations replacing synthetic preservatives in clean-label meat processing.
Starter cultures dominate installed base. Bio-preservatives are where expansion concentrates.
Application:
End-use concentration determines technical support intensity and contract structure, with dairy commanding dedicated strain development programs.
- Dairy Products:Yogurt and cheese production absorb the bulk of culture volume across the region. Argentine and Brazilian processors in the southeastern dairy belt are adopting single-use bioreactor systems to reduce cross-contamination risk between strain batches.
- Beverages:Kombucha and fermented juice formats are capturing shelf space in Brazilian retail channels, pulling volume from traditional dairy applications with shorter production cycles and lower cold-chain requirements.
- Meat:Processed meat channels are absorbing specialized culture formulations ahead of anticipated regulatory mandates on synthetic preservative reduction.
- Bakery:Sourdough and fermented dough applications utilizing yeast and bacterial consortia for flavor development and shelf-life extension.
Dairy products anchor current procurement volumes. Beverages are climbing the fastest.
Distribution Channel:
Channel selection correlates with buyer scale and technical sophistication, fragmenting supplier engagement models.
- Direct Sales:Volume buyers negotiate master service agreements bundling technical support with supply commitments, bypassing traditional import intermediaries. This pattern is most visible in São Paulo and Minas Gerais states, where processor concentration enables sufficient order scale.
- Supermarkets:Mass retail channels for consumer-facing probiotic supplements and fermented food products, requiring branded positioning and shelf-stable packaging formats.
- Specialty Stores:Artisanal cheese supply shops and professional kitchen distributors serving small-scale food manufacturers.
- Online Retail:Emerging channel for home fermentation kits and direct-to-consumer probiotic supplements, constrained by cold-chain integrity requirements for live culture delivery.
Direct sales command the deepest margin pools. Online retail is gaining share fastest.
End User:
Customer type dictates formulation complexity, documentation burden, and price sensitivity thresholds.
- Food Manufacturers:Industrial-scale processors requiring standardized culture concentrates with batch-to-batch consistency and full regulatory documentation for ANVISA compliance.
- Restaurants:Foodservice operators utilizing bulk fermented bases and specialized starter cultures for menu differentiation in urban centers.
- Research Institutions:Universities and biotechnology centers in Córdoba and Buenos Aires provinces developing novel strain applications with potential commercial licensing pathways.
- Home Consumers:Hobbyist fermentation practitioners purchasing retail-format cultures for domestic cheese, yogurt, and kombucha production.
Food manufacturers dominate technical service relationships. Research institutions are where innovation partnerships concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence defines the regional landscape, with European and North American suppliers capturing premium starter culture volumes while local fermentation capacity concentrates in Brazil and Argentina's dairy belts.
Brazil
Dairy cooperatives in São Paulo and Minas Gerais states are locking in long-term supply contracts with culture suppliers to secure strain exclusivity for artisanal cheese production. ANVISA's updated food additive regulations are tightening genomic documentation requirements for probiotic strain identity verification. The southeastern dairy belt anchors domestic demand, though cold-chain gaps in interior distribution networks constrain frozen concentrate penetration.
Argentina
Underutilized biotechnology infrastructure in Córdoba and Buenos Aires provinces offers hub potential for serving Southern Cone markets with distributed fermentation capacity. The Mercosur Food Code harmonizes cross-border standards for culture-containing products among member states, though pending divergence with Chilean requirements threatens sourcing fragmentation. Research institutions in these provinces are developing novel strain applications with potential commercial licensing pathways.
Chile
Regulatory alignment negotiations with Mercosur standards are creating uncertainty for suppliers operating across Andean and Southern Cone markets. The country's national health surveillance agency maintains distinct probiotic registration pathways that complicate regional product portfolios. Santiago-based processed food manufacturers are absorbing specialized bio-preservative formulations ahead of anticipated synthetic preservative reduction mandates.
Colombia
Minimal domestic culture production creates import-dependent demand for suppliers with Mercosur-registered strains, particularly in Bogotá's dairy processing corridor. The country's food safety regulator is evaluating alignment with Brazilian ANVISA protocols for strain documentation. Beverage manufacturers in the capital region are experimenting with kombucha and fermented juice formats that pull volume from traditional dairy applications.
Peru
Lima's food manufacturing base relies entirely on imported starter cultures for yogurt and cheese production, with distributors lacking in-house genomic validation capabilities facing margin compression. The national health authority is developing novel food ingredient registration frameworks that may ease market entry for validated strain suppliers. Andean dairy cooperatives are exploring direct procurement relationships to bypass layered distributor networks.
South America Microbial Food Culture Market Competitive Landscape
Concentration sits with European culture houses that leverage proprietary strain banks and freeze-drying capabilities to command premium pricing tiers. The supplier base stratifies across integrated fermentation operators, specialized bio-preservative formulators, and regional distribution intermediaries. Three archetypes dominate: strain-ownership players with captive genomic libraries, toll-manufacturing specialists with distributed fermentation assets, and compliance-heavy distributors bridging regulatory gaps. Capacity expansion and direct procurement relationships represent the dominant competitive moves as large dairy cooperatives bypass traditional import channels.
Within the strain-ownership tier, Chr. Hansen Holding A/S and Koninklijke DSM NV exemplify the European culture house model that anchors premium supply relationships. Lallemand Inc. occupies a position among North American specialists with distributed fermentation infrastructure in the Southern Cone. Corbion NV represents the bio-preservative formulation archetype targeting clean-label meat processing channels. Kerry Group plc and DuPont de Nemours, Inc. sit within the diversified ingredient supplier category that bundles microbial cultures with broader technical service portfolios.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Koninklijke DSM NV |
| Corbion NV |
| Lallemand Inc. |
| IGEA S.r.l. |
| Kerry Group plc |
| DuPont de Nemours, Inc. |
| Novozymes A/S |
| CSK Food Enrichment |
| Others |
Value Network & Pricing Analysis
Long-term supply contracts with strain exclusivity clauses lock in both supply access and price visibility for Brazilian dairy cooperatives, insulating premium starter culture volumes from spot-market volatility while compressing distributor margins on generic probiotic strains. ANVISA's genomic documentation mandates add validation cost layers that concentrate pricing power among integrated producers with captive laboratory capabilities.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure, with three-tier pricing stratifying across premium proprietary strains, standard validated cultures, and economy generic formulations. Price differentiation rests on certification grade against ANVISA's identity verification protocols and volume scale commitments from southeastern Brazilian cooperatives. Cost compression in the economy tier is intensifying as distributors without in-house sequencing capabilities face margin erosion. Small-scale artisanal producers exhibit highest price sensitivity, while integrated dairy processors with direct supplier relationships show lowest.
Supply Chain Analysis
Denmark and the Netherlands anchor proprietary strain bank production, while Argentina and Brazil host distributed fermentation capacity for regional formulation. Raw material dependencies center on cryoprotectant formulations, specialized growth media, and genomic sequencing reagents. Single-source vulnerability concentrates in European culture houses controlling exclusive strain collections. Distribution runs through direct procurement relationships displacing layered import intermediaries among large Brazilian cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as ANVISA's regulatory clarity eliminates ambiguous approval pathways and pulls volume toward pre-validated strain portfolios. Direct procurement trends among dairy cooperatives are splintering traditional distributor strongholds.
For Market Incumbents: Shield proprietary strain portfolios through accelerated genomic documentation investments that preempt ANVISA compliance deadlines, while consolidating technical service relationships with São Paulo and Minas Gais dairy cooperatives to lock out toll-manufacturing competitors. Capacity addition in Argentine distributed fermentation facilities defends against Southern Cone market encroachment by North American specialists. For New Entrants and Emerging Players: Lead with clean-label bio-preservative formulations targeting Brazilian processed meat channels ahead of synthetic preservative reduction mandates, where regulatory tailwinds outpace incumbent repositioning speed. Peruvian and Colombian import-dependent markets offer the most penetrable geography for Mercosur-registered strains, with direct technical support bundling as the go-to-market angle to bypass established distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward Argentine biotechnology infrastructure with underutilized fermentation capacity and research institution licensing pathways, where capability scarcity in regional genomic validation creates acquisition scarcity value. The signal to watch is ANVISA-Mercosur-Chilean regulatory alignment negotiations, as divergence would fragment sourcing strategies and elevate compliance-heavy distributor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Bank Acquisition | Captures proprietary genomic libraries that ANVISA documentation requirements render non-replicable. |
| Direct Procurement Relationship | Bypasses distributor intermediaries for São Paulo dairy cooperatives with sufficient order scale. |
| Argentine Fermentation Hub Expansion | Leverages Córdoba biotechnology infrastructure to serve Southern Cone markets with reduced logistics costs. |
| Genomic Validation Laboratory Buildout | Insulates margin compression from ANVISA's sequencing documentation mandates for probiotic imports. |
| Clean-Label Bio-Preservative Launch | Anticipates Brazilian processed meat regulatory mandates on synthetic preservative reduction. |
Research Methodology
Initial hypotheses were tested against primary input from dairy cooperative procurement directors, ANVISA regulatory affairs specialists, culture supplier technical service managers, and Argentine biotechnology researchers, and refined through secondary validation against customs import records, ANVISA strain registration databases, Mercosur Food Code harmonization documents, and SEC filings from publicly traded culture houses. Bottom-up volume estimates from individual processor consumption patterns were triangulated with top-down market sizing from trade flow analysis.
Variance decomposition across product type, application, distribution channel, and end-user segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate differentials applied to base-year installed capacity estimates, with inputs including ANVISA approval timeline distributions, dairy cooperative contract renewal cycles, and fermented beverage retail shelf-space expansion rates.
Forecasts assume regulatory continuity in Brazilian ANVISA protocols and Mercosur Food Code standards; material policy shifts toward Chilean divergence or Colombian alignment would require re-modeling. Strain safety approval delays, cold-chain infrastructure gaps in interior Brazil, and genomic validation capability bottlenecks represent specific revision triggers. Recalibration cycles align with material shifts in regulatory harmonization negotiations and direct procurement adoption rates among large dairy processors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market