
 Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market | 2026-2036
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market Insights
Premium clinically validated synbiotic formulations is decoupling from commodity probiotic supplements on the basis of polyphenol sourcing transparency and strain-specific clinical dossiers. Novonesis leverages its microbial platform to anchor high-potency strain development for Mediterranean polyphenol matrices. ADM competes through backward integration into olive and grape polyphenol extraction networks across Spain and Italy. Kerry Group differentiates by controlling flavor-masked delivery systems that sustain viability through gastric transit.
Mediterranean probiotic-polyphenol synbiotic concepts combine live microbial cultures with olive, grape, or citrus-derived polyphenols in co-stabilized matrices, typically requiring gastric-resistance coating to achieve colon-targeted release above 10^8 CFU. These compositions serve nutraceutical and functional food manufacturers seeking dual-mechanism gastrointestinal and antioxidant claims. Synbiotic Blends command margin pools due to formulation complexity and patent-protected strain-polyphenol pairings, while Functional Beverages represent the fastest-expanding delivery vector as liquid stability technologies mature. Digestive Health occupies the largest application share, though Cognitive Enhancement is gaining traction through gut-brain axis positioning.
EFSA novel food approval pathways and EU Health Claims Regulation govern substantiation requirements for polyphenol-probiotic synergy claims across Mediterranean member states. EMA pharmacovigilance frameworks and national food safety authorities in Italy and Spain enforce strain identity verification and polyphenol standardization thresholds. Stakeholders must monitor evolving EFSA opinions on polyphenol bioavailability markers and pre-submission consultation outcomes to calibrate R&D investment timing.
Market Dynamics
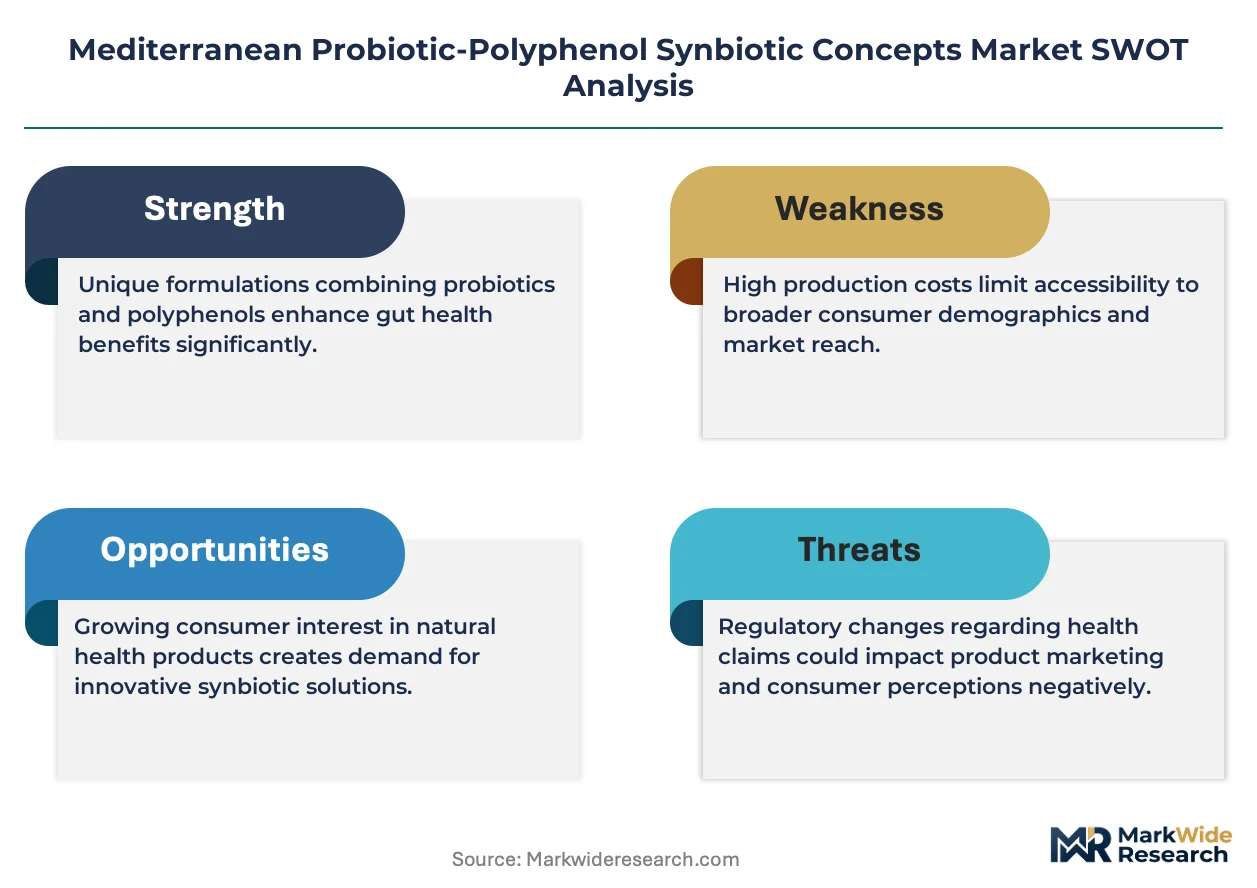
EFSA novel food guidance and EU Health Claims Regulation are compressing product development timelines while simultaneously elevating the barrier to entry for substantiated polyphenol-probiotic synergy claims across Southern European markets.
Growth Catalysts
- EFSA Health Claims substantiation:Clinically validated strain-polyphenol pairings now unlock premium positioning for digestive health applications in Spain and Italy.
- Olive polyphenol sourcing networks:Backward integration into Spanish and Italian extraction infrastructure secures supply chain control for high-potency formulations.
- Gastric-resistance coating advances:Colon-targeted delivery technologies achieving 10^8 CFU viability are expanding addressable applications for functional beverages.
Market Restraints
- Polyphenol standardization costs:Batch-to-batch variability in olive and grape extracts demands expensive HPLC verification protocols.
- Strain identity verification mandates:EMA pharmacovigilance frameworks in Italy and Spain require whole-genome sequencing for novel probiotic submissions.
- Clinical dossier development timelines:EFSA pre-submission consultations for synbiotic synergy claims extend R&D cycles by 18-24 months.
Strategic Opportunities
- Cognitive Enhancement positioning:Gut-brain axis claims represent underexploited white space as Southern European wellness clinics seek differentiated protocols.
- Liquid stability technology maturation:Functional beverages are capturing volume expansion as manufacturers solve polyphenol-probiotic co-stability in aqueous matrices.
- Flavor-masked delivery systems:Kerry Group's controlled-release technologies suggest partnership pathways for palatability-constrained pediatric and geriatric segments.
Industry Challenges
- Cross-functional formulation expertise:Synbiotic development requires simultaneous mastery of microbial strain selection, polyphenol bioavailability engineering, and gastric-resistance coating design.
- EFSA opinion tracking complexity:Evolving guidance on polyphenol bioavailability markers demands dedicated regulatory intelligence functions to calibrate investment timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market |
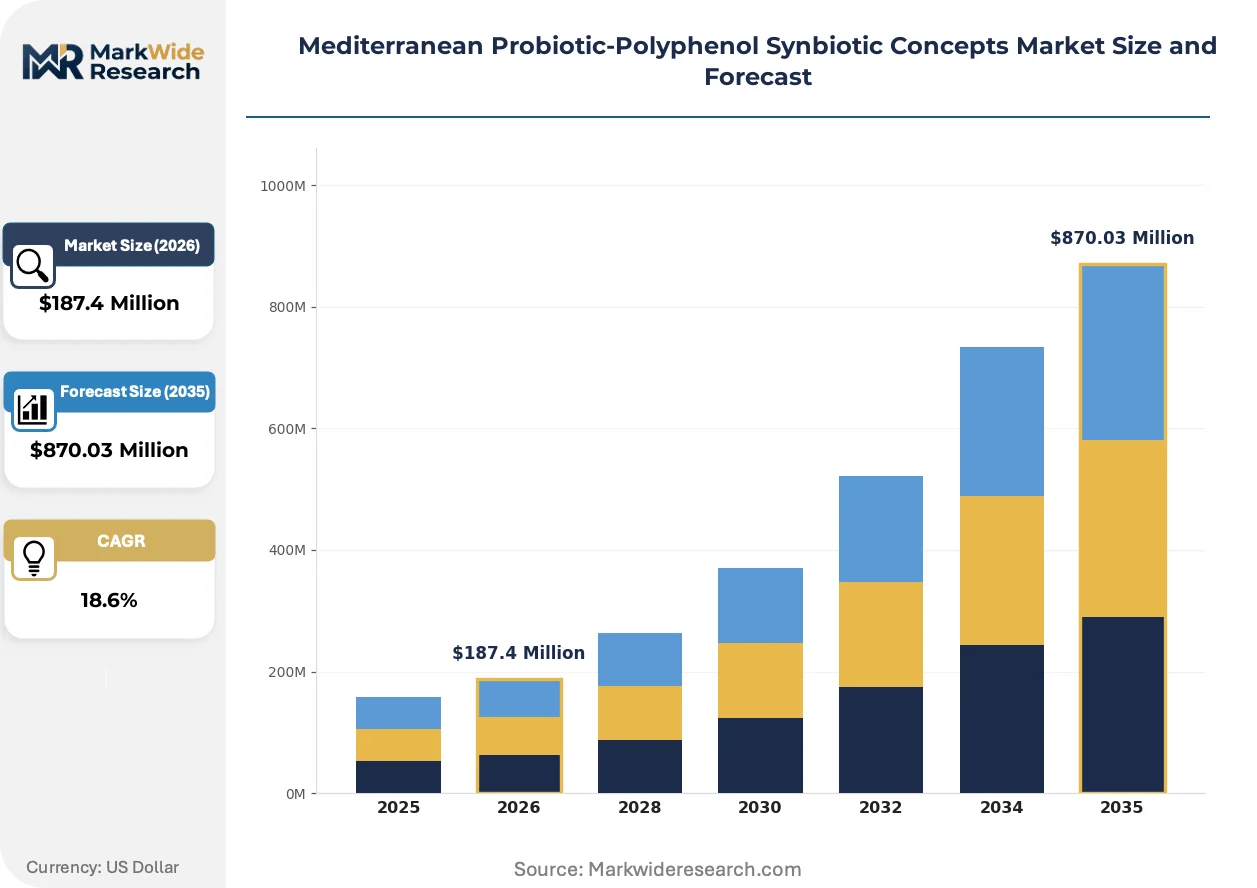
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Supplements, Polyphenol Extracts, Synbiotic Blends, Functional Beverages, Dietary Powders Application: Digestive Health, Immune Support, Cardiovascular Wellness, Skin Health, Cognitive Enhancement End User: Health-Conscious Consumers, Sports Nutritionists, Nutraceutical Manufacturers, Holistic Practitioners, Wellness Clinics Delivery Format: Capsules, Sachets, Liquid Shots, Gummies, Tablets |
| Companies Covered | Novonesis, ADM, IFF, dsm-firmenich, Kerry Group, Probi, Danone, Yakult Honsha, Sabinsa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market Trends and Innovations
Delivery technology convergence and regulatory substantiation requirements are redrawing competitive boundaries between commodity probiotic suppliers and clinically validated synbiotic specialists.
Microencapsulation technologies employing pH-responsive polymers are unifying gastric protection with controlled intestinal release in single-matrix systems. Spanish functional food manufacturers are adopting these platforms at accelerated pace to meet wellness clinic procurement standards. The technology is unifying previously separate coating and encapsulation steps, compressing production costs for colon-targeted synbiotic formats.
EU Health Claims Regulation Article 13.5 is forcing manufacturers to generate proprietary human intervention studies for polyphenol-probiotic synergy claims. This regulatory pressure is diverting R&D budgets from formulation innovation toward clinical trial infrastructure. Digestive health applications in Italy face the steepest compliance burden as national food safety authorities enforce strain-specific dossier requirements.
Wellness clinic procurement is consolidating around suppliers offering transparent polyphenol sourcing documentation and strain-specific clinical data packages. Southern European nutraceutical distributors are displacing traditional ingredient brokers with direct manufacturer relationships that provide batch-level traceability. This channel restructuring is most visible in Barcelona and Milan, where premium clinic networks now mandate supplier audit rights as standard contract terms.
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market Segmentation
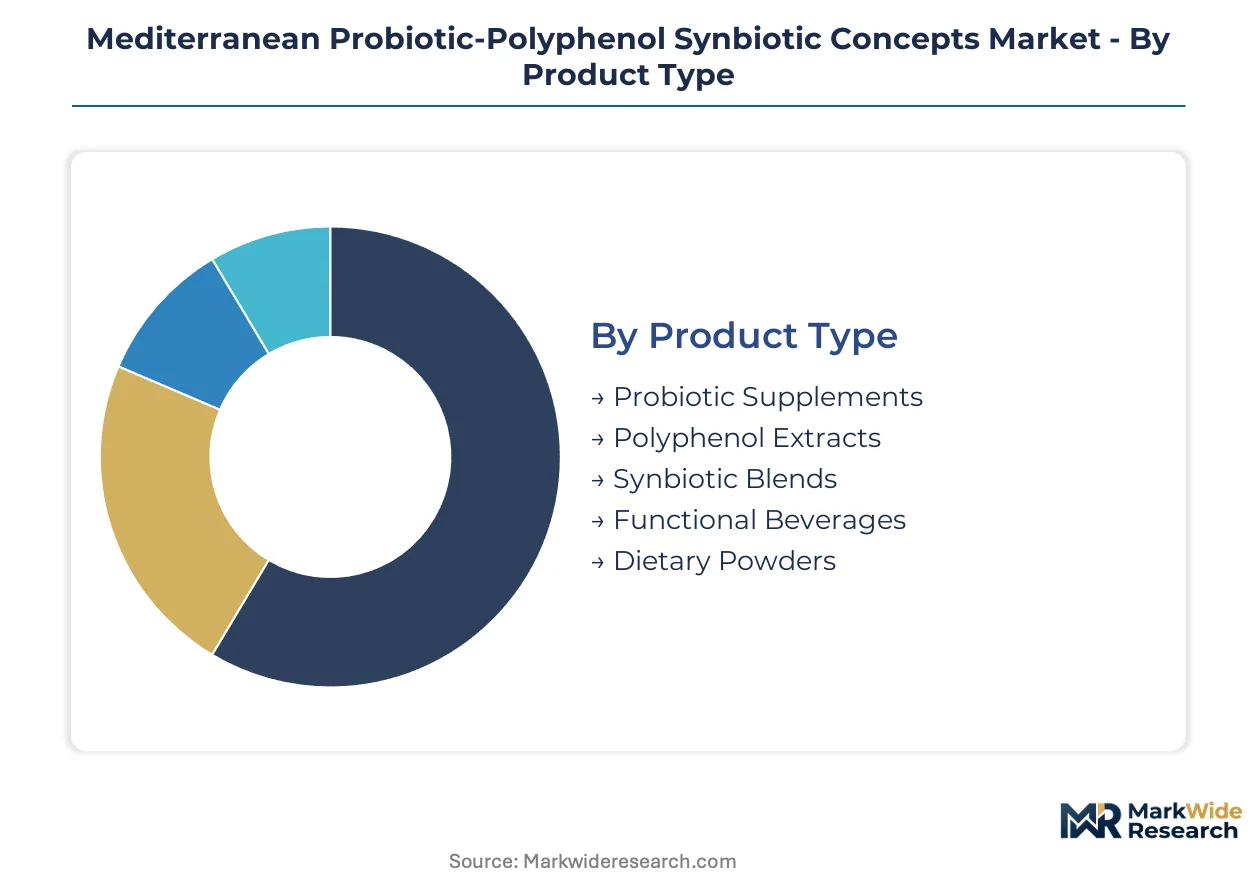
Polyphenol-probiotic synergy claims require precise formulation architecture across product matrices. Segmentation clarity determines which delivery technologies warrant R&D investment versus commodity positioning.
Product Type:
Gastric-resistance coating specifications and polyphenol bioavailability engineering define competitive differentiation across product architectures.
- Synbiotic Blends:Co-stabilized matrices combining live microbial cultures with olive, grape, or citrus polyphenols in colon-targeted formats. Spanish and Italian nutraceutical manufacturers concentrate procurement here for dual-mechanism gastrointestinal and antioxidant claims, though EFSA synergy substantiation demands extend development cycles substantially.
- Functional Beverages:Liquid delivery systems requiring advanced polyphenol-probiotic co-stability in aqueous matrices. Southern European wellness clinics in Barcelona and Milan are expanding volume commitments as stability technologies mature, capturing the steepest expansion trajectory among all product categories.
- Probiotic Supplements:Single-strain or multi-strain formats without integrated polyphenol matrices, facing margin compression from clinically validated synbiotic alternatives.
- Polyphenol Extracts:Standalone olive, grape, or citrus concentrates supplying downstream formulation partners, subject to batch-to-batch HPLC verification costs.
- Dietary Powders:Bulk formats targeting sports nutrition blending applications with lower barrier-to-entry for new market participants.
Synbiotic Blends lead on scale; Functional Beverages lead on momentum.
Application:
Clinical dossier requirements and wellness clinic procurement standards reshape application-level investment prioritization.
- Digestive Health:Largest volume segment anchored by gut microbiome modulation claims with established EFSA Article 13.1 generic health claim pathways. Italian national food safety authorities enforce the most stringent strain-specific dossier requirements here, compressing competitive margins for unsubstantiated entrants.
- Cognitive Enhancement:Gut-brain axis positioning through vagus nerve and neurotransmitter modulation pathways. Southern European wellness clinics seek differentiated protocols in Barcelona, Milan, and Rome, driving premium pricing for clinically validated polyphenol-strain pairings targeting this white space.
- Immune Support:Claims requiring demonstration of polyphenol-probiotic synergy on mucosal immunity markers, with moderate substantiation burden relative to cognitive positioning.
- Cardiovascular Wellness:Olive polyphenol matrices targeting endothelial function, constrained by bioavailability marker standardization costs.
- Skin Health:Emerging gut-skin axis applications with limited clinical precedent in Mediterranean regulatory frameworks.
Digestive Health commands volume concentration; Cognitive Enhancement gains share fastest through wellness clinic channel restructuring.
End User:
Procurement sophistication and transparency requirements segment addressable demand across customer archetypes.
- Wellness Clinics:Premium segment demanding transparent polyphenol sourcing documentation, strain-specific clinical data packages, and supplier audit rights as standard contract terms. Barcelona and Milan clinic networks are displacing traditional ingredient brokers with direct manufacturer relationships.
- Nutraceutical Manufacturers:Formulation partners seeking backward-integrated polyphenol supply and gastric-resistance coating capabilities for private-label development.
- Holistic Practitioners:Individual practitioners prescribing personalized synbiotic protocols with limited scale but high margin capture.
- Sports Nutritionists:Performance-oriented applications favoring rapid absorption liquid formats over colon-targeted delivery systems.
- Health-Conscious Consumers:Mass-market retail purchasers with lowest transparency requirements and highest price sensitivity.
Wellness Clinics anchor premium tier economics; Nutraceutical Manufacturers drive volume manufacturing scale.
Delivery Format:
Physicochemical stability requirements and patient compliance factors determine format-level technology investment.
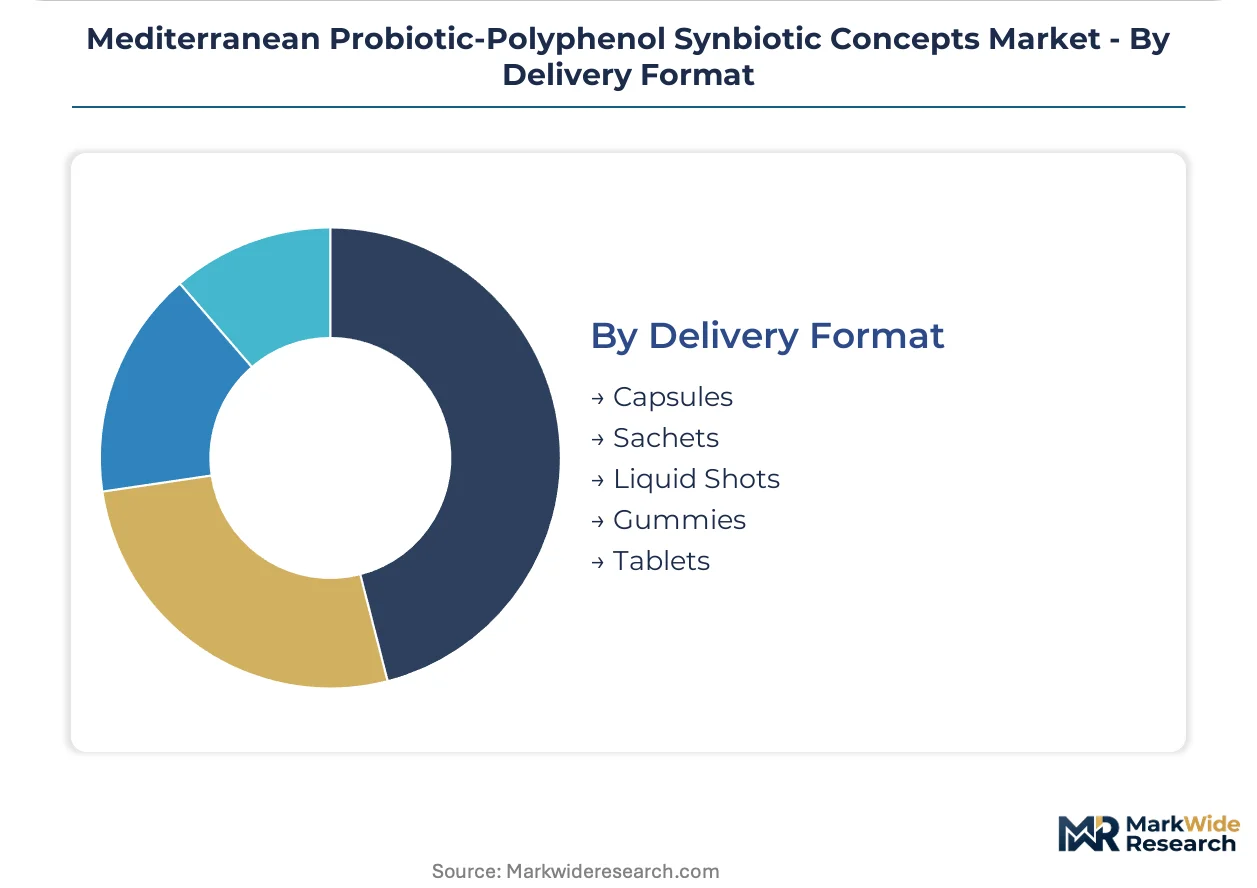
- Liquid Shots:Fastest-expanding format as pH-responsive microencapsulation solves polyphenol-probiotic co-stability in aqueous matrices. Spanish functional food manufacturers adopt these platforms at accelerated pace to meet wellness clinic procurement standards for single-dose convenience.
- Capsules:Established gastric-resistance coating infrastructure with proven colon-targeted release above 10^8 CFU, retaining largest installed manufacturing base across Italy and Spain.
- Sachets:Powder-in-sachet formats for reconstitution, balancing stability with dosing flexibility for clinical settings.
- Gummies:Palatability-driven pediatric and geriatric positioning constrained by thermal processing viability losses.
- Tablets:Compression formats with limited adoption for live culture applications due to shear stress during manufacturing.
Capsules dominate current manufacturing capacity; Liquid Shots climb fastest on stability technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain concentrates manufacturing scale for olive polyphenol extraction, while Italy dominates wellness clinic procurement networks demanding clinical validation. Southern European regulatory frameworks create divergent compliance burdens across national boundaries.
Spain
Spanish nutraceutical manufacturers drive procurement of polyphenol-rich synbiotic formulations for digestive health applications. EFSA novel food guidance governs substantiation requirements for polyphenol-probiotic synergy claims across Castile-La Mancha and Andalusia extraction zones. Barcelona wellness clinic networks mandate supplier audit rights and transparent sourcing documentation as standard contract terms.
Italy
Italian national food safety authorities enforce stringent strain-specific dossier requirements for digestive health positioning. EU Health Claims Regulation Article 13.5 demands proprietary human intervention studies for synbiotic synergy substantiation. Milan clinic networks displace traditional ingredient brokers with direct manufacturer relationships requiring batch-level traceability.
France
French ANSM pharmacovigilance frameworks impose whole-genome sequencing mandates for novel probiotic submissions entering the market. EMA oversight extends to polyphenol standardization thresholds for grape-derived matrices sourced from Languedoc-Roussillon vineyards. Lyon-based formulation partners seek backward-integrated supply chains for private-label development.
Greece
Greek functional food manufacturers adopt pH-responsive microencapsulation platforms to meet wellness clinic procurement standards for single-dose convenience. National food safety authorities align with EFSA opinions on polyphenol bioavailability markers. Athens and Thessaloniki clusters concentrate demand for liquid shot formats as stability technologies mature.
Portugal
Portuguese extraction infrastructure supplies high-potency olive polyphenol matrices to downstream Spanish and Italian formulation partners. The country's national pharmaceutical regulator enforces strain identity verification protocols aligned with EU-wide harmonization. Alentejo region agricultural cooperatives expand polyphenol sourcing networks for captive nutraceutical supply.
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market Competitive Landscape
Top-tier vendors anchor clinically validated synbiotic development, while mid-scale specialists compete on polyphenol sourcing transparency and gastric-resistance coating capabilities. The vendor base stratifies across microbial platform holders, backward-integrated extractors, and delivery technology specialists. Three archetypes dominate: strain developers leveraging microbial platforms, polyphenol extractors controlling Mediterranean sourcing networks, and formulation partners mastering flavor-masked delivery systems. Competitive moves concentrate on strategic partnerships for clinical dossier development and capacity expansion into Spanish and Italian extraction infrastructure.
Within the microbial platform tier, Novonesis represents high-potency strain development capabilities for Mediterranean polyphenol matrices. ADM exemplifies backward integration into olive and grape polyphenol extraction networks across Spain and Italy. Kerry Group occupies a position among delivery technology specialists controlling flavor-masked systems that sustain viability through gastric transit. These three entities anchor distinct competitive vectors rather than direct substitution.
| Leading Market Players |
|---|
| Novonesis |
| ADM |
| IFF |
| dsm-firmenich |
| Kerry Group |
| Probi |
| Danone |
| Yakult Honsha |
| Sabinsa |
| Others |
Pricing and Supply Chain Analysis
Olive polyphenol spot indices in Castile-La Mancha and Andalusia extraction zones cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins for non-integrated formulators while rewarding backward-integrated suppliers with captive sourcing networks.
Pricing Analysis
Capacity additions in Spanish extraction infrastructure are reshaping price floors for high-potency olive polyphenol matrices. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA synergy substantiation status and strain-specific clinical dossier completeness. Pricing pressure stems from batch-to-batch HPLC verification costs that non-integrated manufacturers cannot absorb. Wellness clinics demonstrate lowest price sensitivity due to procurement mandates for transparent sourcing documentation, while health-conscious retail purchasers concentrate price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Portuguese Alentejo agricultural cooperatives supplying high-potency olive polyphenol matrices to downstream Spanish and Italian formulation partners. Manufacturing gravity centers on Spain and Italy, with Greek pH-responsive microencapsulation technology providers feeding liquid stability advances. Raw material dependencies encompass olive pomace, grape seed extract, and citrus bioflavonoid concentrates. Tariff exposure on polyphenol extract imports from non-EU Mediterranean sources represents the dominant structural risk. Distribution runs through direct manufacturer relationships displacing traditional ingredient brokers in Barcelona and Milan clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Southern European wellness clinics consolidate procurement around clinically validated polyphenol-strain pairings with transparent sourcing documentation.
For Market Incumbents: Lock in backward integration into Spanish and Italian olive polyphenol extraction networks before capacity scarcity intensifies. Prioritize EFSA pre-submission consultations for synbiotic synergy claims to extend regulatory moats against emerging entrants lacking clinical trial infrastructure. Defensive patent filings on strain-polyphenol pairings anchor premium positioning against commodity probiotic suppliers. For New Entrants and Emerging Players: Capture cognitive enhancement positioning through gut-brain axis claims as the most penetrable white space in Barcelona, Milan, and Rome wellness clinic networks. Liquid shot formats offer lower barrier-to-entry than colon-targeted capsule infrastructure. Partner with Kerry Group flavor-masked delivery technologies to solve palatability constraints in pediatric and geriatric segments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists controlling pH-responsive microencapsulation platforms and gastric-resistance coating capabilities. Long-term viability hinges on regulatory intelligence functions tracking evolving EFSA opinions on polyphenol bioavailability markers. Watch EMA pharmacovigilance framework harmonization across Italy, Spain, and France as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Pre-Submission Consultation | Secures regulatory pathway for polyphenol-probiotic synergy claims before competitor dossier submissions. |
| Backward Integration into Extraction | Captures olive polyphenol supply chain control in Castile-La Mancha and Andalusia zones. |
| pH-Responsive Microencapsulation Partnership | Unlocks liquid stability for functional beverage expansion into Greek and Portuguese markets. |
| Wellness Clinic Direct Sourcing Agreement | Displaces ingredient brokers through supplier audit rights mandated by Milan and Barcelona networks. |
| Strain-Specific Clinical Dossier Development | Builds proprietary data packages for gut-brain axis cognitive enhancement positioning. |
Research Methodology
Multiple input streams — regulatory affairs directors at EFSA-notified bodies, procurement leads at Barcelona and Milan wellness clinic networks, and technical R&D heads at Spanish nutraceutical manufacturers — were reconciled against EFSA novel food submission databases, EU Health Claims Regulation Article 13.5 opinion trackers, and olive polyphenol trade flow records from Castile-La Mancha extraction zones. Secondary validation drew from EMA pharmacovigilance framework documents, Italian national food safety authority strain verification protocols, and Portuguese agricultural cooperative supply disclosures. Bottom-up volume modeling and top-down value reconciliation anchored forecast triangulation.
Historical pricing trajectories for olive and grape polyphenol extracts were cross-referenced against panel input from procurement officers at Southern European nutraceutical manufacturers across the analysis window. Segmentation modeling incorporated product type, application, end user, and delivery format dimensions with gastric-resistance coating technology maturity as an industry-specific forecast input. CAGRs were derived from reconciled growth assumptions rather than single-source projections, with EFSA opinion timeline uncertainty explicitly modeled as a scenario variable.
EFSA guidance revision on polyphenol bioavailability markers, EMA pharmacovigilance framework harmonization delays, and olive harvest yield volatility in Mediterranean climate zones are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market