
 Lactobacillus Acidophilus Market | 2026-2036
Lactobacillus Acidophilus Market Size, Share, and Industry Trends Forecast 2026-2036
Lactobacillus Acidophilus Market Insights
Pharmaceutical-grade strain certification is redrawing competitive boundaries in probiotic manufacturing. Chr. Hansen Holding A/S leverages its culture collection depth to dominate high-potency therapeutic segments. Danone S.A. anchors mass-market dairy probiotic distribution through refrigerated supply chain control. Nestlé S.A. extends its infant nutrition expertise into specialized L. acidophilus formulations for early-life gut colonization.
Lactobacillus acidophilus denotes a homofermentative, gram-positive lactic acid bacterium that metabolizes lactose to produce lactic acid, typically requiring a pH range of 4.0–4.6 for optimal viability during fermentation and storage. Industrial applications span live culture preservation in functional foods, freeze-dried probiotic supplements, and direct-fed microbials for animal nutrition. Capsule delivery formats now lead value capture due to shelf-stability demands and precise CFU dosing, while powder formulations sustain growth in infant formula and bulk ingredient channels. Gut health applications occupy the largest demand share, though immune support positioning is accelerating fastest among sports nutrition and senior wellness segments.
FDA dietary supplement Current Good Manufacturing Practices constrain raw material sourcing and label claim substantiation for US market participants. EFSA health claim authorization processes in Europe limit permitted strain-specific marketing, while China's NMPA and SAMR jointly regulate probiotic food ingredients through strain-level safety assessments and functional food registration requirements. Stakeholders must monitor evolving strain patent landscapes and jurisdiction-specific stability testing protocols to secure market access without reformulation delays.
Market Dynamics
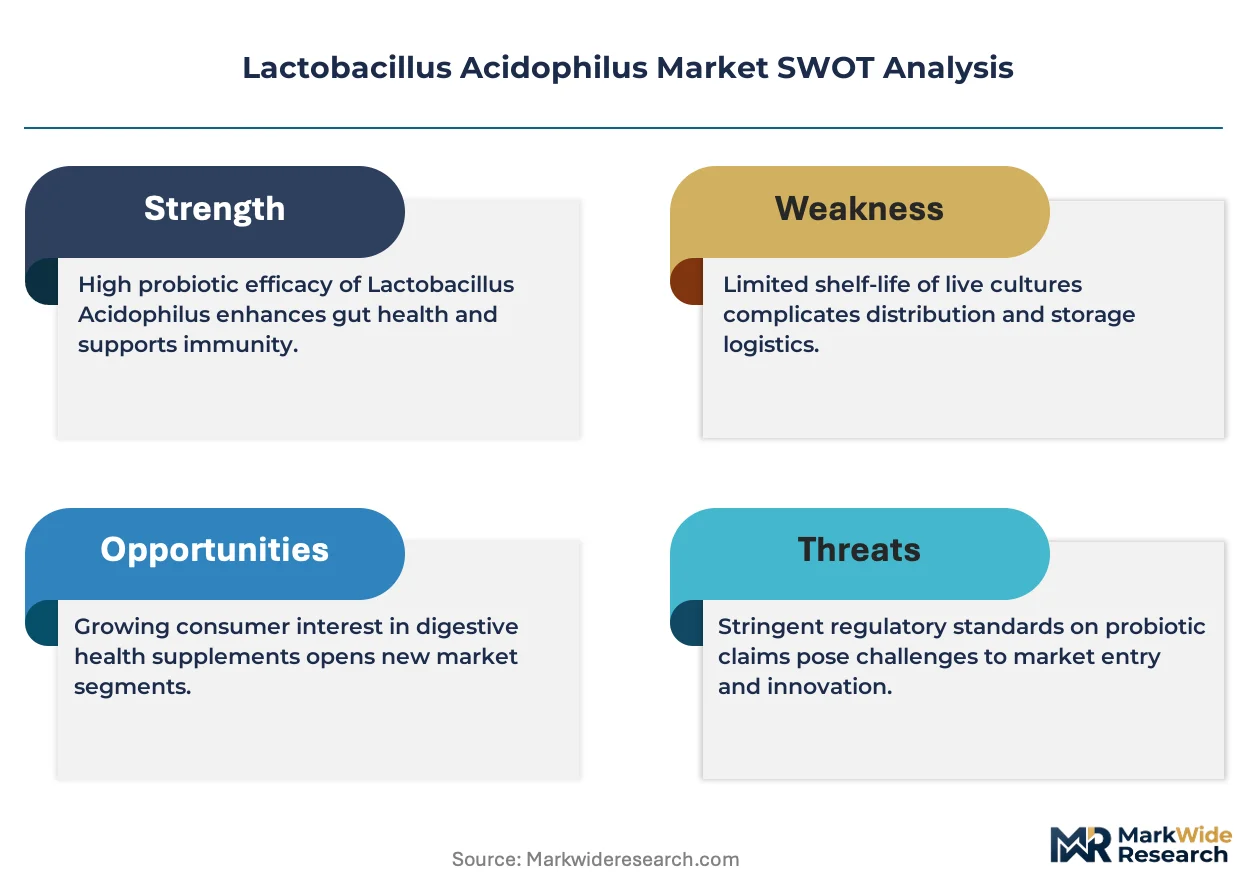
Strain-specific pharmaceutical certification is bifurcating the competitive landscape between mass-market dairy applications and high-potency therapeutic segments. This regulatory stratification forces manufacturers to choose between commodity volume plays and premium clinical-grade positioning.
Growth Catalysts
- FDA Dietary Supplement CGMP Enforcement:Tightening manufacturing standards for live culture stability and label claim substantiation is elevating barrier-to-entry for new entrants while rewarding incumbent quality investments.
- Sports Nutrition Formulation Demand:Athletes and fitness consumers are integrating L. acidophilus into recovery protocols, expanding application beyond traditional digestive positioning into immune modulation and protein absorption optimization.
- Freeze-Drying Process Advances:Industrial lyophilization equipment upgrades are extending shelf-stable CFU viability from 18 to 36 months, unlocking direct-to-consumer e-commerce channels previously constrained by cold-chain requirements.
Market Restraints
- Raw Material Concentration Risk:High-purity lactose and specialized growth media supply concentrates in German and Dutch fermentation ingredient specialists, exposing formulators to input cost volatility.
- EFSA Health Claim Authorization Bottleneck:Strain-specific probiotic claims face 18-24 month evaluation timelines with high rejection rates, constraining European marketing flexibility and forcing generic positioning.
- Live Culture Logistics Complexity:Refrigerated distribution infrastructure gaps in emerging markets limit viable geographic expansion for non-shelf-stable formats.
Strategic Opportunities
- China NMPA Strain Registration Pathway:New functional food ingredient safety assessment frameworks are opening previously restricted probiotic food categories to imported L. acidophilus strains meeting SAMR documentation standards.
- Infant Formula Premiumization:Early-life gut colonization science is driving HMO-probiotic synergistic formulations, creating white space for specialized strain development beyond commodity dairy applications.
- Direct-Fed Microbial Animal Nutrition:Antibiotic growth promoter bans in poultry and swine production across Brazil and Southeast Asia are accelerating probiotic feed additive substitution demand.
Industry Challenges
- Strain Patent Navigation Complexity:Overlapping intellectual property claims on specific L. acidophilus genomes require costly freedom-to-operate analyses before commercial launch.
- CFU Enumeration Standardization Delays:Inconsistent viability testing methodologies across ISO, FDA BAM, and AOAC protocols create cross-border shipment rejections and reformulation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactobacillus Acidophilus Market |
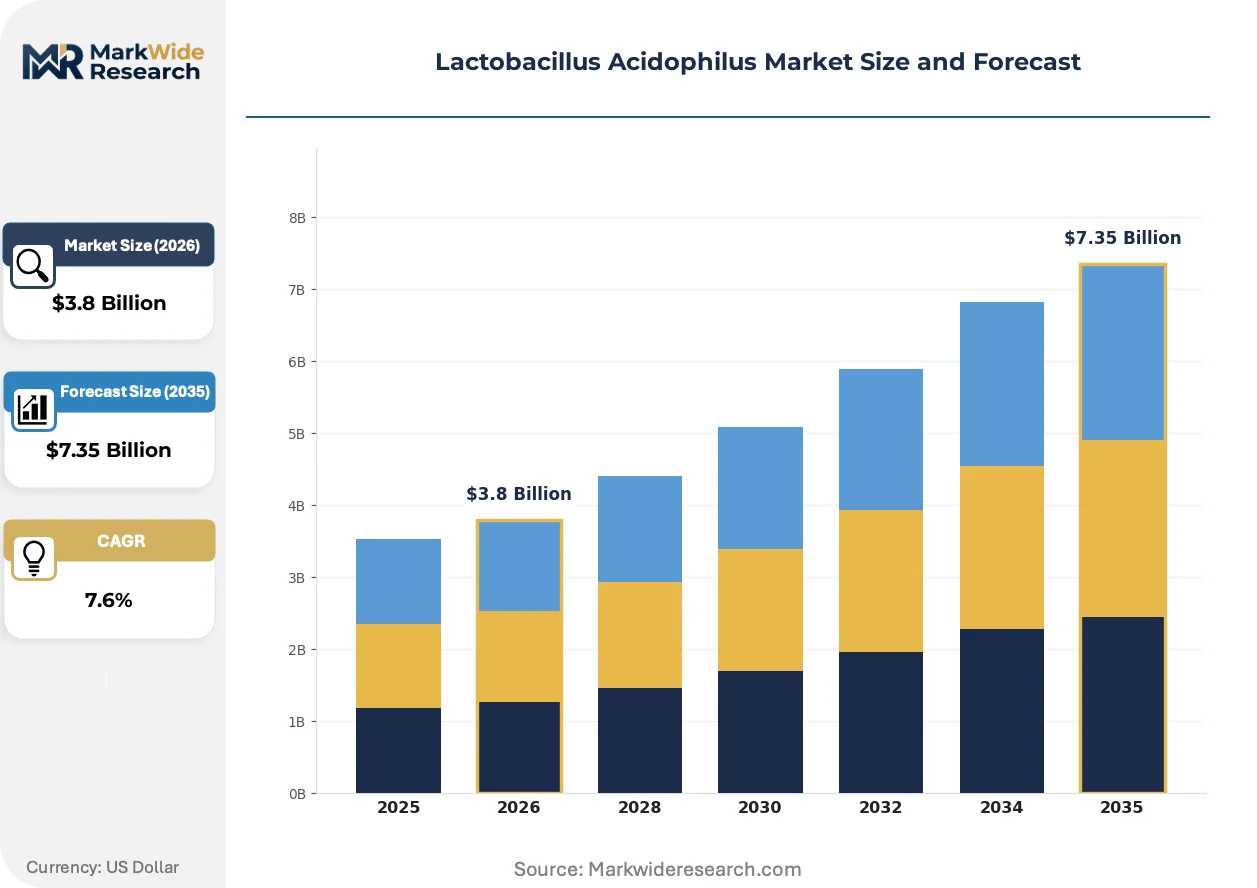
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Dietary Supplements, Functional Foods, Infant Formula Application: Gut Health, Immune Support, Nutritional Enhancement, Vaginal Health Delivery Mode: Capsules, Powders, Liquid, Chewables End User: Healthcare Professionals, Nutritionists, General Consumers, Athletes |
| Companies Covered | Danone S.A., Nestlé S.A., Chr. Hansen Holding A/S, Yakult Honsha Co., Ltd., DuPont de Nemours, Inc., Lallemand Inc., Kerry Group plc, Probi AB, BioGaia AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactobacillus Acidophilus Market Trends and Innovations
Encapsulation technology convergence with precision fermentation is redefining product format viability and dosing accuracy across consumer segments. These advances are compressing the performance gap between clinical-grade and commercial probiotic offerings.
Microencapsulation via alginate-chitosan matrix coating is miniaturizing protective shell structures to sub-100 micron diameters while maintaining gastric acid resistance above 90 percent. Pharmaceutical compounders are adopting these systems for enteric delivery of high-potency therapeutic doses. This miniaturization is enabling tablet and sachet formats previously impossible with traditional bulk freeze-dried powders, expanding pharmacy channel penetration.
EFSA's 2023 updated guidance on Article 13.1 health claims for gut microbiota modulation is forcing reformulation toward multi-strain cocktails with documented synergistic effects. Manufacturers must now submit human intervention studies with predefined primary endpoints rather than relying on mechanistic plausibility arguments. Dairy and supplement brands with existing strain-specific clinical portfolios are accelerating dossier submissions ahead of competitor compliance timelines.
Certification-driven procurement is displacing price-first supplier selection among institutional buyers including hospital formulary committees and sports team nutrition programs. Third-party USP verification and NSF Certified for Sport designations now gate access to these channels. This preference shift concentrates contract volumes with manufacturers maintaining dedicated quality assurance infrastructure, compressing margins for undifferentiated commodity suppliers.
Lactobacillus Acidophilus Market Segmentation
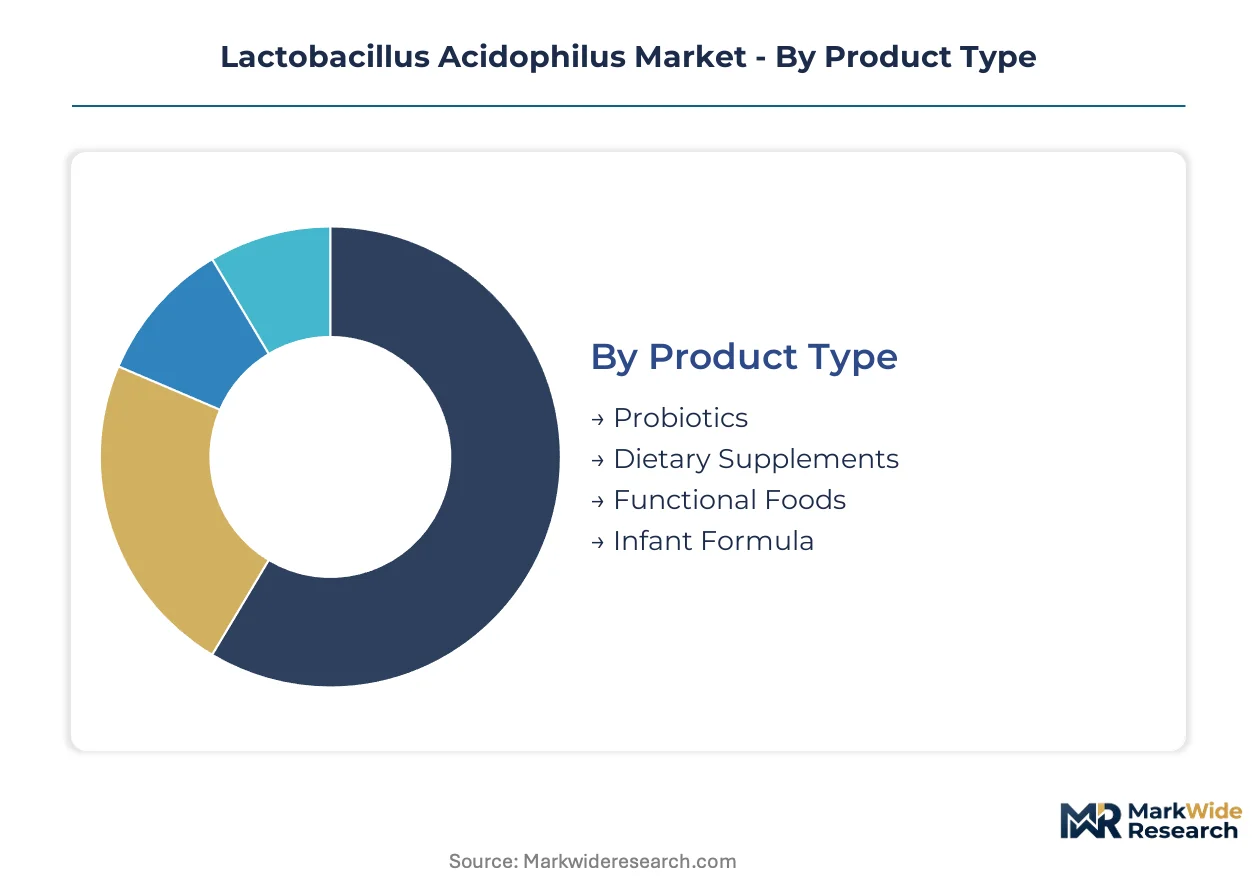
Segmentation in the Lactobacillus acidophilus market reveals distinct vulnerability profiles to substitute technologies and competing bacterial strains. Each category demands tailored positioning strategies to defend against functional ingredient substitution and format switching.
Product Type:
Probiotics face the most acute substitution pressure from multi-strain synbiotic formulations and postbiotic metabolite extracts that bypass live culture stability requirements entirely.
- Probiotics:Live culture preparations containing viable L. acidophilus colonies, typically standardized at 1-10 billion CFU per serving. Demand concentrates in refrigerated dairy applications across Germany and the United States, constrained by cold-chain infrastructure gaps in warmer climates that shelf-stable alternatives exploit.
- Dietary Supplements:Freeze-dried or encapsulated formulations designed for ambient distribution, with USP verification increasingly gating hospital formulary access. Sports nutrition procurement in North America and senior wellness programs in Japan drive premium positioning away from commodity dairy channels.
- Functional Foods:Fortified yogurts, kefirs, and fermented beverages integrating live cultures during manufacturing. Danone S.A. and Nestlé S.A. anchor mass-market penetration through controlled refrigerated distribution networks.
- Infant Formula:Specialized early-life gut colonization products combining L. acidophilus with human milk oligosaccharides. China's SAMR strain registration requirements create documentation barriers for imported formulations.
Probiotics anchors the volume base while dietary supplements gains share at the steepest rate.
Application:
Cost tier stratification separates clinical-grade therapeutic positioning from mass-market wellness claims, with reimbursement eligibility determining pricing power.
- Gut Health:Digestive wellness applications including diarrhea prevention, irritable bowel syndrome management, and antibiotic-associated dysbiosis recovery. EFSA Article 13.1 health claim authorization bottlenecks in Europe force generic positioning unless strain-specific clinical dossiers are submitted.
- Immune Support:Respiratory infection prevention and immune modulation targeting athletes, frequent travelers, and elderly populations. Sports team nutrition programs and hospital formulary committees now require NSF Certified for Sport or equivalent third-party verification.
- Nutritional Enhancement:Protein absorption optimization and micronutrient bioavailability improvement in fitness and clinical nutrition contexts. Powder formulations dominate bulk ingredient channels for institutional food service.
- Vaginal Health:Urogenital probiotic applications addressing bacterial vaginosis and yeast infection recurrence prevention. Capsule and suppository delivery formats predominate due to targeted colonization requirements.
Gut health retains the largest demand share while immune support climbs the fastest among premium-positioned segments.
Delivery Mode:
Volume concentration in e-commerce direct-to-consumer channels favors formats with extended ambient shelf stability and precise dosing transparency.
- Capsules:Enteric-coated gelatin or vegetable cellulose shells protecting cultures from gastric acid degradation. Alginate-chitosan microencapsulation advances enable sub-100 micron protective matrices with above 90 percent acid resistance.
- Powders:Bulk freeze-dried preparations for infant formula integration, bulk ingredient supply, and sachet retail formats. Industrial lyophilization equipment upgrades extend shelf-stable CFU viability from 18 to 36 months.
- Liquid:Ready-to-drink fermented beverages and culture suspensions requiring continuous cold-chain maintenance. Refrigerated distribution infrastructure gaps in Brazil and Southeast Asia constrain geographic expansion.
- Chewables:Flavored tablet formats targeting pediatric and geriatric populations with swallowing difficulties. Moisture sensitivity during manufacturing demands specialized humidity-controlled production environments.
Capsules anchors the value capture while powders sustains growth in bulk ingredient channels.
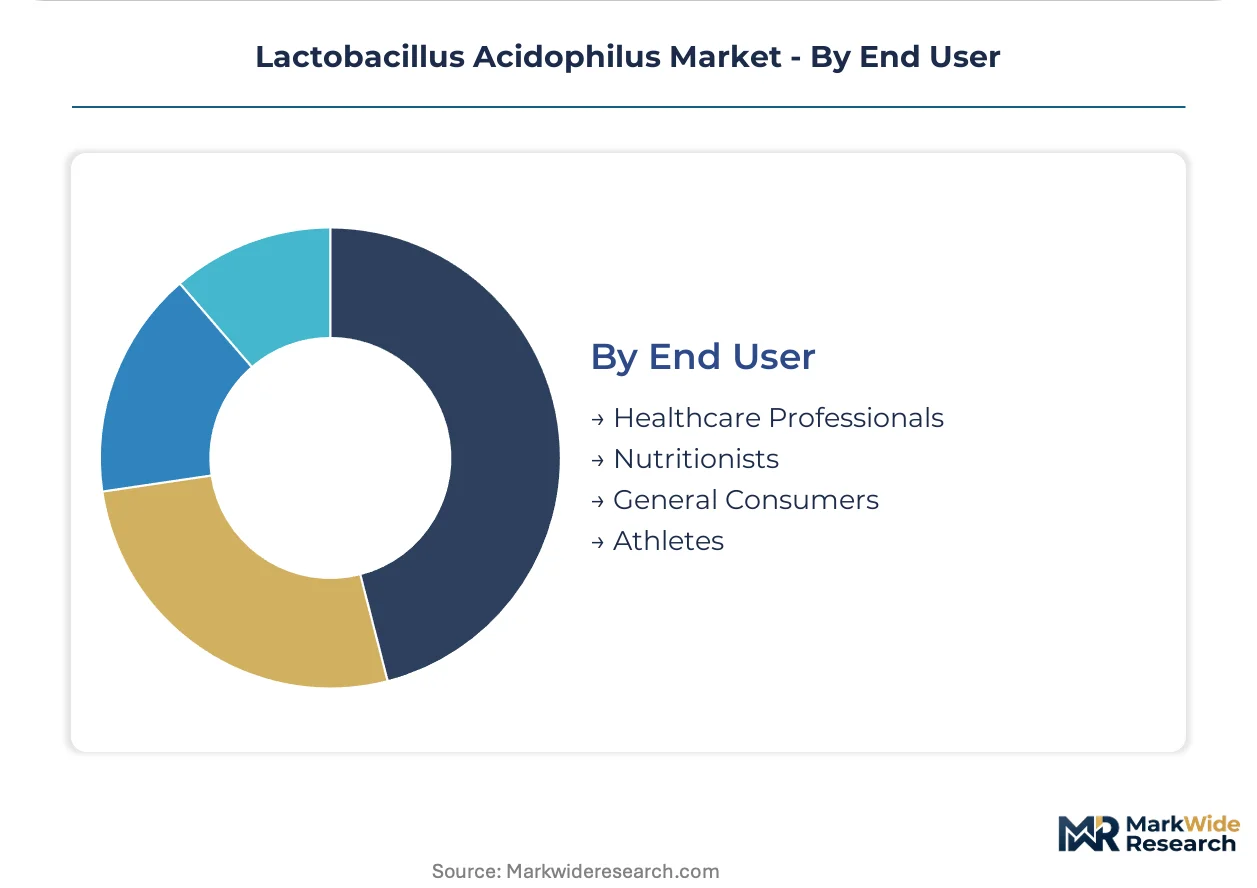
End User:
Customer type fragmentation demands distinct clinical evidence packages, with healthcare gatekeepers requiring pharmaceutical-grade strain certification unavailable to commodity suppliers.
- Healthcare Professionals:Physicians, pharmacists, and hospital formulary committees prescribing therapeutic-grade probiotics. FDA dietary supplement CGMP enforcement elevates documentation requirements for live culture stability and label claim substantiation.
- Nutritionists:Registered dietitians and sports nutrition specialists integrating probiotics into personalized protocols. Certification-driven procurement displaces price-first supplier selection among institutional buyers.
- General Consumers:Self-directed purchasers through retail and e-commerce channels. Direct-to-consumer brands leverage 36-month shelf stability advances to bypass traditional pharmacy distribution.
- Athletes:Professional and amateur competitors prioritizing immune modulation and recovery optimization. NSF Certified for Sport designation gates access to sports team nutrition programs and Olympic training facilities.
General consumers anchors the volume base while healthcare professionals commands the steepest pricing premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fermentation ingredient specialists export high-purity lactose and specialized growth media to US and Chinese probiotic formulators, creating a trade-flow corridor that concentrates raw material supply in Northwestern Europe while downstream manufacturing disperses across North America and Asia-Pacific.
United States
Sports nutrition procurement and hospital formulary access drive demand for USP-verified and NSF Certified for Sport probiotic supplements. FDA dietary supplement Current Good Manufacturing Practices enforcement elevates documentation requirements for live culture stability. Greater Boston anchors pharmaceutical-grade strain development, with contract manufacturers serving therapeutic-grade segments.
Germany
Refrigerated dairy applications and pharmaceutical-grade fermentation supply concentrate demand in Bavaria and North Rhine-Westphalia. EFSA health claim authorization processes constrain strain-specific marketing, forcing generic positioning unless clinical dossiers are submitted. Cologne-Düsseldorf corridor houses industrial lyophilization equipment specialists serving pan-European freeze-dried supplement production.
China
Infant formula premiumization and functional food ingredient registration accelerate demand for SAMR-compliant L. acidophilus strains. NMPA and SAMR jointly regulate probiotic food ingredients through strain-level safety assessments. Yangtze River Delta clusters domestic fermentation capacity while imported strains penetrate premium early-life nutrition segments.
Japan
Senior wellness programs and personalized nutrition protocols sustain demand for high-CFU shelf-stable formulations. PMDA and METI oversight maintains stringent stability testing standards for functional food claims. Kansai region, particularly Osaka-Kobe corridor, concentrates dairy probiotic manufacturing with controlled refrigerated distribution networks.
Brazil
Antibiotic growth promoter bans in poultry and swine production accelerate direct-fed microbial demand for animal nutrition applications. ANVISA regulates probiotic feed additives through safety assessment frameworks. São Paulo state anchors compound feed manufacturing, with probiotic premix integration expanding across Southeast Brazil's integrated protein production systems.
Lactobacillus Acidophilus Market Competitive Landscape
Listed leaders compete with private specialists across strain certification depth and refrigerated supply chain control. The market structures around three tiers: multinational dairy conglomerates with captive distribution, dedicated culture collection houses with pharmaceutical-grade certification, and regional fermentation ingredient suppliers serving bulk ingredient channels. Two competitive moves dominate: M&A targeting strain patent portfolios and backward integration into high-purity lactose supply.
Within the culture collection tier, Chr. Hansen Holding A/S and BioGaia AB exemplify pharmaceutical-grade positioning through proprietary strain banks. Danone S.A. and Nestlé S.A. anchor mass-market dairy applications with refrigerated distribution scale. Among Nordic specialists, Probi AB occupies a position bridging clinical evidence development and commercial supplement supply.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| Chr. Hansen Holding A/S |
| Yakult Honsha Co., Ltd. |
| DuPont de Nemours, Inc. |
| Lallemand Inc. |
| Kerry Group plc |
| Probi AB |
| BioGaia AB |
| Others |
Pricing and Supply Chain Analysis
Industrial lyophilization scale economies concentrate high-CFU probiotic manufacturing among German and Dutch equipment operators, compressing price floors for commodity-grade powders while elevating premiums for pharmaceutical-certified strains. This capacity concentration forces smaller formulators into toll-manufacturing arrangements that cede margin control to culture collection houses with captive freeze-drying infrastructure.
Pricing Analysis
Freeze-drying generation gaps separate first-generation bulk powders from second-generation microencapsulated capsules and emerging third-generation precision-fermentation isolates. Three-tier pricing structure across pharmaceutical-grade, USP-verified, and commodity dairy tiers reflects certification depth and clinical dossier investment. Price differentiation hinges on strain-specific FDA master file documentation and NSF Certified for Sport verification, with commodity dairy cultures facing cost compression from multi-strain synbiotic substitutes. Hospital formulary committees exhibit lowest price sensitivity, while mass-market retail channels absorb margin pressure from private-label entrants.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade lactose and specialized yeast extracts stretch 12-16 weeks due to fermentation ingredient concentration in Germany and the Netherlands. High-purity lactose supply draws from Bavarian dairy processors, while growth media production centers on Dutch biotechnology specialists, creating dual-source dependency for US and Chinese formulators. Single-source vulnerability concentrates in alginate-chitosan encapsulation polymers, where Japanese chemical suppliers dominate sub-100 micron matrix production. Distribution runs through temperature-controlled logistics networks for refrigerated dairy applications, with ambient-stable capsules bypassing cold-chain infrastructure through direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain patent platform economics are approaching an inflection as interoperability standards for CFU enumeration and stability testing consolidate around ISO and AOAC harmonization, favoring ecosystem orchestrators over isolated technology holders.
For Market Incumbents: Compound defensive moats by securing backward integration into high-purity lactose supply and accelerating USP verification infrastructure for hospital formulary access. Postbiotic metabolite extracts threaten live culture margins; counter through exclusive strain licensing agreements that lock sports nutrition and infant formula channels against generic substitution. For New Entrants and Emerging Players: SAMR strain registration fast-tracks in China offer the most penetrable regulatory pathway for imported L. acidophilus certifications, bypassing EFSA's 18-24 month authorization bottlenecks. Target direct-fed microbial animal nutrition in Brazil and Southeast Asia, where antibiotic growth promoter bans create immediate substitution demand without pharmaceutical-grade certification barriers. Lead with powder formulations for bulk feed premix integration rather than competing in refrigerated dairy logistics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors culture collection houses with proprietary strain banks and existing pharmaceutical-grade fermentation infrastructure over commodity dairy probiotic suppliers. Long-term viability rests on patent estate breadth and regulatory dossier depth rather than brand equity. Watch EFSA Article 13.1 health claim authorization velocity as the inflection signal—accelerated approvals for multi-strain synergistic claims would revalue clinical evidence portfolios against generic positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Patent Portfolio Acquisition | Freedom-to-operate clearance on specific L. acidophilus genomes gates commercial launch in therapeutic segments. |
| SAMR Registration Dossier Investment | China's functional food ingredient safety assessments open previously restricted probiotic categories to imported strains. |
| Microencapsulation Technology Licensing | Alginate-chitosan matrix patents enable sub-100 micron enteric delivery with above 90 percent gastric acid resistance. |
| USP Verification Infrastructure Buildout | Third-party certification gates hospital formulary access and sports team nutrition program procurement. |
| Direct-Fed Microbial Feed Additive Expansion | Antibiotic growth promoter bans in Brazil and Southeast Asia accelerate probiotic substitution demand in poultry and swine production. |
Research Methodology
The analysis maps probiotic strain certification tiers, delivery format technologies, and end-user application segments, each validated through fermentation scientists, regulatory affairs specialists at NMPA and SAMR, hospital formulary directors, and sports nutrition procurement managers. Primary fieldwork combined structured interviews with secondary validation against FDA master file databases, EFSA health claim authorization registers, SAMR functional food ingredient filings, and ISO stability testing protocol documentation. Bottom-up strain-level demand modeling triangulated against top-down category spend estimates from customs trade flows and pharmaceutical ingredient import records.
Consistency checks validated volume and value outputs against external benchmarks including fermentation capacity utilization reports from German industrial equipment specialists and probiotic supplement retail audit data from North American pharmacy channels. The analytical framework segmented by product type, application, delivery mode, and end-user archetype across the projection horizon. CAGRs derived from strain-specific adoption curves weighted by regulatory approval timelines and cold-chain infrastructure penetration. Industry-specific forecast inputs incorporated EFSA authorization pipeline velocity and SAMR registration backlog clearance rates.
Underlying assumptions cover strain viability stability under ambient storage conditions, regulatory harmonization progress between ISO and AOAC protocols, and cold-chain infrastructure expansion in emerging markets, with deviation risk concentrated in EFSA health claim rejection rates and raw material concentration disruptions from German lactose supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market