
 Japan Probiotics Market | 2026-2036
Japan Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Probiotics Market Outlook
Market Context
Japan's probiotic consumption is rebalancing toward functional foods and senior-targeted formulations as traditional dairy-centric demand diversifies. Yakult Honsha Co., Ltd. anchors the market through its unparalleled home delivery network and daily consumption ritual embedded in Japanese households. Morinaga Milk Industry Co., Ltd. leverages its long-standing bifidobacterium research to dominate premium infant and senior gut health segments. Asahi Group Holdings, Ltd. competes aggressively in the functional beverage space, extending probiotic offerings beyond traditional yogurt formats into ready-to-drink positioning.
Technical Definition and Structural Segments
Probiotics comprise live microorganisms, primarily Lactobacillus and Bifidobacterium strains, that confer measurable health benefits when administered in adequate colony-forming units, typically requiring refrigerated or shelf-stable stabilization processes to maintain viability through gastric transit. Their primary commercial purpose centers on modulating intestinal microbiota to support digestive efficiency, immune modulation, and nutrient absorption in human hosts. Functional Foods leads product type demand due to Japan's mature FFC regulatory pathway and consumer familiarity with disease-risk reduction claims, while Digestive Health anchors application volume though Immune Support exhibits the fastest trajectory as post-pandemic wellness priorities persist. Online Retail captures expanding share among younger demographics, yet Supermarkets and convenience channels sustain the bulk of recurring purchases through habitual restocking behaviors.
Regulatory Framework and Outlook
Japan's national probiotic landscape operates under the Consumer Affairs Agency's FFC notification system, METI's broader functional food industrial policy, and PMDA oversight for strains advancing toward pharmaceutical-grade claims, collectively creating a tiered compliance architecture that rewards substantiated science while filtering unsubstantiated entrants. These frameworks shape demand by permitting specific disease-risk reduction language unavailable in standard food labeling, directly elevating product premiums and channel placement. Stakeholders must monitor strain-specific claim approvals and evolving FFC evidentiary standards to determine which microbiome targets warrant sustained R&D commitment versus near-term commercialization.
Market Dynamics
METI's Foods with Function Claims system is compressing product development cycles by allowing specific disease-risk reduction language without full pharmaceutical approval, reshaping how Japanese manufacturers prioritize strain research and commercialization timelines.
Growth Catalysts
- Aging Demographics:Japan's super-aged society drives concentrated demand for digestive and immune-targeted formulations among seniors seeking longevity-focused nutrition solutions.
- METI FFC Streamlining:The notification-based approval pathway reduces time-to-market for substantiated health claims, incentivizing domestic R&D investment in clinically validated strains.
- Home Delivery Infrastructure:Embedded daily consumption rituals through established distribution networks reinforce habitual purchasing and reduce customer acquisition costs for functional food providers.
Market Restraints
- Raw Strain Supply Concentration:Viable Bifidobacterium and Lactobacillus culture supply concentrates among a limited set of specialized biotech suppliers, creating input vulnerability.
- Refrigeration Dependency:Cold-chain requirements for maintaining colony-forming unit viability elevate logistics costs and limit rural penetration where infrastructure gaps persist.
- Evidentiary Burden:PMDA's escalating standards for pharmaceutical-grade probiotic claims force manufacturers to sustain costly clinical trials without guaranteed approval outcomes.
Strategic Opportunities
- Kansai Underpenetration:Osaka and Kyoto metropolitan areas show lower functional food adoption rates than Kanto, presenting whitespace for targeted distribution expansion.
- Shelf-Stable Technology Convergence:Advances in microencapsulation and desiccation processes enable ambient-temperature probiotic formats, unlocking convenience store and export channels previously inaccessible.
- Online Subscription Models:Direct-to-consumer platforms bypass traditional retail gatekeepers while capturing younger demographics less anchored to habitual supermarket purchasing.
Industry Challenges
- Strain Differentiation Complexity:Patent thickets around specific Bifidobacterium substrains complicate licensing negotiations and freedom-to-operate assessments for new entrants.
- Clinical Validation Timelines:FFC notification requirements for human intervention studies extend product development cycles, straining R&D budgets and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Probiotics Market |
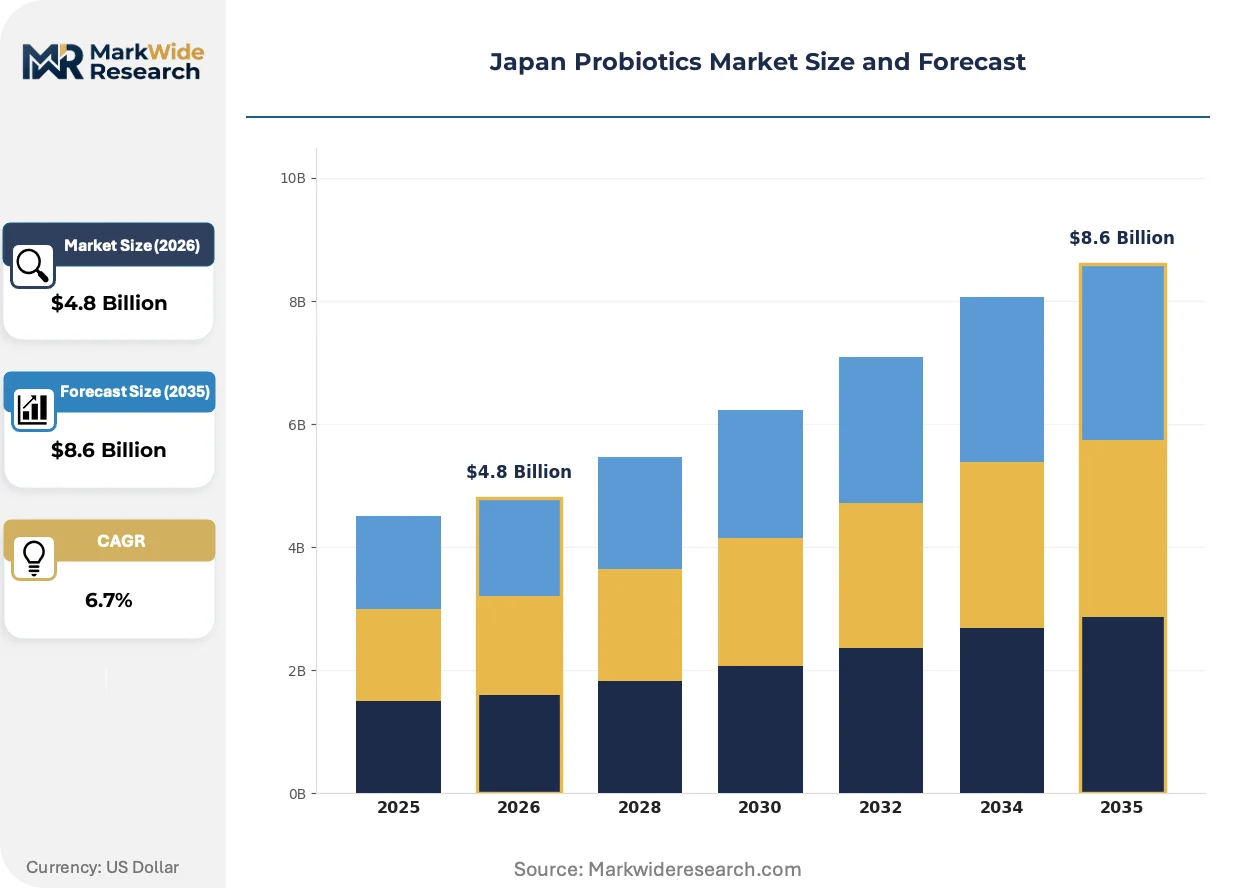
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Supplements, Dairy Products, Beverages, Functional Foods Application: Digestive Health, Immune Support, Nutritional Supplements, Weight Management Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Consumer Demographics: Adults, Children, Seniors, Athletes |
| Companies Covered | Asahi Group Holdings, Ltd., Nestlé Japan Ltd., Yakult Honsha Co., Ltd., Kewpie Corporation, Calpis Co., Ltd., Morinaga Milk Industry Co., Ltd., Danone, Biofermin Pharmaceutical Co., Ltd., Meiji Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Probiotics Market Strategic Shifts
Japanese probiotic innovation is pivoting from dairy-centric formats toward functional beverages and ambient-stable delivery systems, driven by shifting consumption occasions and channel expansion imperatives.
Microencapsulation technology is modularizing strain protection and gastric transit survival. Food technologists at domestic manufacturers are adopting multi-layer coating systems at accelerating rates. This engineering approach is modularizing the separation between production and distribution constraints, enabling shelf-stable products that bypass refrigeration infrastructure entirely.
METI's 2023 FFC evidentiary guideline revisions tightened requirements for gut microbiome modulation claims. Manufacturers must now submit larger sample sizes and longer intervention periods to secure disease-risk reduction language. Premium infant nutrition and senior digestive health segments are responding by consolidating clinical trial partnerships with university medical centers to share validation costs.
Younger consumers in Tokyo and Yokohama are abandoning habitual supermarket restocking in favor of personalized subscription services delivering monthly probiotic assortments. Digital-native brands are capturing this cohort through algorithmic strain matching based on self-reported digestive symptoms. Channel disruption is most visible among professionals aged 25-40 who prioritize convenience over established brand loyalty.
Japan Probiotics Market Segmentation
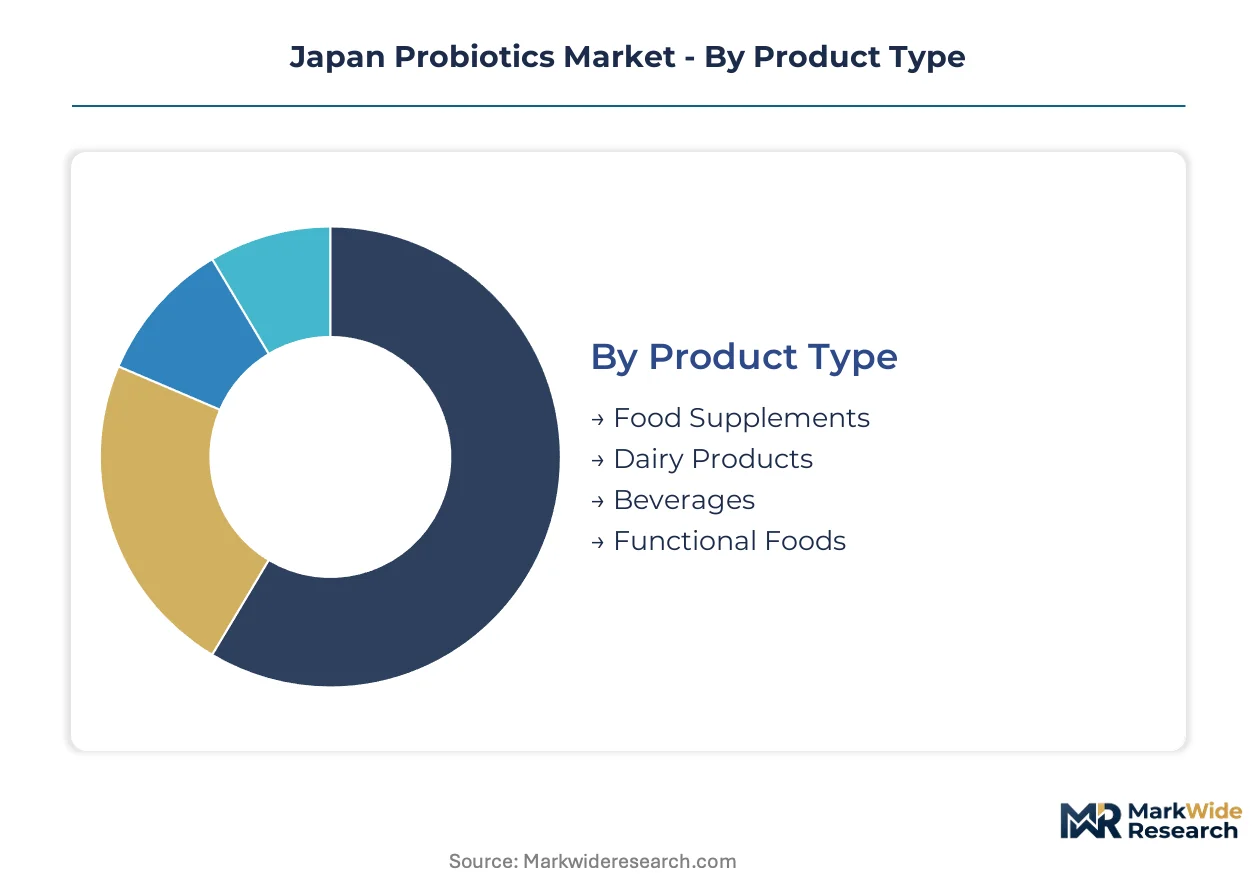
Japan's probiotic market segments reveal a structural divide between habitual consumption channels anchored in traditional retail and emerging formats targeting convenience-seeking demographics. Understanding these fault lines illuminates where METI's FFC regulatory streamlining creates the most pronounced commercial advantages.
Product Type:
Volume leadership concentrates in dairy-based formats, while premium positioning and regulatory flexibility concentrate in functional foods.
- Functional Foods:Products carrying METI's Foods with Function Claims designation permit specific disease-risk reduction language unavailable to standard foods. Tokyo's aging population drives concentrated demand for bifidobacterium-fortified yogurts targeting digestive efficiency. Mature deployment sits with Functional Foods.
- Dairy Products:Traditional fermented milk formats dominate household penetration through Yakult's embedded home delivery infrastructure. Kanto region purchasing power sustains premium pricing for daily consumption rituals. Newer deployment is concentrated in Dairy Products.
- Food Supplements:Capsule and tablet formats bypass refrigeration constraints through desiccation stabilization processes.
- Beverages:Ready-to-drink probiotic positioning extends consumption occasions beyond breakfast into afternoon refreshment.
Functional Foods command premium shelf placement in Tokyo's dense retail corridors, while Dairy Products sustain volume through habitual restocking behaviors.
Application:
Digestive Health anchors commercial volume, yet Immune Support exhibits the steepest expansion trajectory as post-pandemic wellness priorities persist.
- Digestive Health:Intestinal microbiota modulation represents the foundational probiotic value proposition with longest consumer familiarity. Seniors across Kanto and Kansai regions prioritize regularity and nutrient absorption in longevity-focused diets. Mature deployment sits with Digestive Health.
- Immune Support:Gut-associated lymphoid tissue targeting has gained regulatory traction under tightened FFC evidentiary guidelines requiring larger intervention studies. Younger demographics in Yokohama and Osaka metropolitan areas drive adoption of clinically validated strains. Newer deployment is concentrated in Immune Support.
- Nutritional Supplements:General wellness positioning captures occasional users seeking insurance against dietary gaps.
- Weight Management:Satiety signaling and metabolic modulation claims remain under PMDA scrutiny for pharmaceutical crossover risk.
Digestive Health claims face commoditization pressure as strain differentiation narrows, while Immune Support commands escalating R&D investment.
Distribution Channel:
Supermarkets sustain recurring revenue through habitual purchasing, yet Online Retail captures generational transition among digital-native consumers.
- Supermarkets:Refrigerated case placement in Tokyo's premium retail density reinforces brand visibility and impulse purchasing. Cold-chain infrastructure requirements align with existing dairy distribution networks. Mature deployment sits with Supermarkets.
- Online Retail:Subscription models bypass traditional retail gatekeepers while enabling algorithmic strain matching based on self-reported symptoms. Professionals aged 25-40 in Yokohama and Nagoya prioritize convenience over established loyalty. Newer deployment is concentrated in Online Retail.
- Health Stores:Specialized retail channels cater to informed consumers seeking pharmacist consultation on strain-specific benefits.
- Pharmacies:PMDA oversight proximity positions these outlets for pharmaceutical-grade probiotic transitions.
Supermarkets and convenience channels retain bulk purchasing frequency, while Online Retail expands fastest among younger cohorts abandoning habitual restocking.
Consumer Demographics:
Seniors concentrate absolute spending power, yet Adults represent the most contested demographic as brand loyalty fragments.
- Seniors:Japan's super-aged society drives concentrated demand for bifidobacterium formulations targeting digestive efficiency and immune resilience. Kanto region's aging population density creates pronounced geographic clustering of premium purchasing. Mature deployment sits with Seniors.
- Adults:Workplace professionals aged 25-40 exhibit channel fluidity, migrating between subscription services and convenience store impulse purchasing. Tokyo and Osaka metropolitan areas show divergent format preferences. Newer deployment is concentrated in Adults.
- Children:Infant nutrition segments leverage Morinaga's long-standing research partnerships with university medical centers.
- Athletes:Exercise recovery and gut permeability modulation remains niche relative to mainstream wellness positioning.
Seniors sustain manufacturer margins through premium tolerance and habitual consumption, while Adults drive channel experimentation and format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kanto Special Ward Zone tax incentives concentrate functional food manufacturing in Tokyo's dense urban corridor, accelerating probiotic R&D clustering around metropolitan research universities.
Kanto/Tokyo
Tokyo's super-aged demographic drives concentrated demand for bifidobacterium-fortified yogurts targeting digestive efficiency. METI's FFC notification system permits disease-risk reduction claims that elevate product premiums in this region. The Shibuya and Shinjuku retail corridors host the densest placement of functional food SKUs nationwide.
Kansai/Osaka
Osaka metropolitan area shows lower functional food adoption than Kanto, creating whitespace for targeted distribution expansion. PMDA's proximity in Osaka city influences pharmaceutical-grade probiotic development pipelines. Kyoto's university medical centers partner with manufacturers on clinical validation for senior-targeted formulations.
Chubu/Nagoya
Nagoya's manufacturing base supports probiotic beverage production for convenience store channels. Aichi prefecture's logistics infrastructure enables cold-chain distribution across central Japan. Toyota City's corporate wellness programs incorporate employer-subsidized probiotic subscriptions.
Kyushu
Fukuoka's startup ecosystem incubates digital-native probiotic brands targeting subscription models. The city's younger demographic profile favors online retail over habitual supermarket purchasing. Saga prefecture's dairy cooperatives supply raw fermented milk bases to national processors.
Hokkaido
Hokkaido's dairy farming concentration anchors raw material supply for traditional yogurt formats. Sapporo's harsh winters elevate refrigeration infrastructure quality, supporting viable cold-chain logistics. Local processors face margin pressure from Kanto-based competitors with superior METI FFC claim portfolios.
Japan Probiotics Market Competitive Environment
Top-tier vendors anchor shelf-stable innovation, while mid-tier domestic specialists compete on strain differentiation and regional distribution density. The market structure rewards established players with embedded home delivery networks and long-standing university research partnerships. Three archetypes dominate: legacy dairy conglomerates with FFC claim portfolios, pharmaceutical-origin entrants pursuing PMDA-grade transitions, and digital-native subscription brands. Competitive moves concentrate on microencapsulation technology licensing and backward integration into specialized culture supply.
Among Japan-based Co., Ltd. structures, Yakult Honsha Co., Ltd. and Morinaga Milk Industry Co., Ltd. exemplify the legacy tier with embedded distribution infrastructure, while Asahi Group Holdings, Ltd. occupies a position representing beverage-format diversification. These three anchors illustrate how patent-protected bifidobacterium substrains and METI regulatory fluency create defensive moats against multinational entrants.
| Leading Market Players |
|---|
| Asahi Group Holdings, Ltd. |
| Nestlé Japan Ltd. |
| Yakult Honsha Co., Ltd. |
| Kewpie Corporation |
| Calpis Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| Danone |
| Biofermin Pharmaceutical Co., Ltd. |
| Meiji Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
FFC-certified bifurcation separates premium functional foods from commodity dairy formats, compressing margins in the latter while rewarding METI-compliant players with pricing power anchored in clinical validation investments and refrigerated distribution infrastructure.
Pricing Analysis
Short lead-time premiums concentrate in home delivery subscriptions where Yakult's daily distribution network commands loyalty-based pricing, while spot inventory in convenience channels trades at discounts reflecting cold-chain spoilage risk. Three-tier pricing structure across premium, standard, and economy levels tracks METI FFC certification status, with disease-risk reduction claims justifying substantial markups. Cost compression in commodity yogurt segments is intensifying because raw culture supply concentrates among limited biotech suppliers. Workplace professionals aged 25-40 exhibit highest price sensitivity, migrating to algorithmic subscription models, while seniors show lowest sensitivity due to habitual consumption patterns.
Supply Chain Analysis
Workforce availability constraints in Hokkaido's dairy farming regions and Tokyo's metropolitan manufacturing zones elevate labor costs for raw milk collection and probiotic beverage processing. Geographic supply concentration centers on Japan for finished functional foods, with raw Bifidobacterium and Lactidobacillus cultures drawing from specialized domestic biotech suppliers and select European culture houses. Single-source vulnerability pervades the viable strain tier, where patent-protected substrain licensing creates captive supplier relationships. Distribution runs through embedded home delivery networks for recurring revenue, supplemented by convenience store cold-chain placement for impulse occasions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's probiotic sector functions as a cost-of-compliance market where METI's FFC evidentiary requirements erect substantial barrier-to-entry moats favoring incumbents with sustained clinical trial budgets and university research partnerships.
For Market Incumbents: To counter digital-native subscription brands capturing Tokyo's professional cohort, legacy manufacturers should deepen backward integration into specialized culture supply and expand shelf-stable microencapsulation capacity for convenience channel penetration. Channel control through employer-subsidized corporate wellness programs offers defensive positioning against algorithmic strain-matching platforms. For New Entrants and Emerging Players: Kansai's underpenetrated functional food adoption presents whitespace for Osaka-Kyoto metropolitan expansion, particularly among seniors seeking longevity-focused nutrition outside Kanto's premium retail density. Direct-to-consumer platforms with personalized microbiome assessments offer the most penetrable go-to-market angle for professionals aged 25-40 abandoning habitual supermarket purchasing. For Investors and Strategic Acquirers: Re-rating potential sits with shelf-stable technology specialists given METI's tightening FFC guidelines favoring clinically validated ambient formats over refrigeration-dependent legacy products. Long-term viability over the coming decade hinges on microencapsulation IP portfolios and university medical center partnerships. The signal to watch is PMDA pharmaceutical-grade probiotic claim approvals, which would validate premium valuation multiples for compliant players.| Strategic Initiative | Industry Significance |
|---|---|
| METI FFC Notification Expansion | Disease-risk reduction claims elevate product premiums in Tokyo's dense retail corridors. |
| Shelf-Stable Technology Licensing | Microencapsulation IP unlocks convenience store channels previously inaccessible to refrigerated formats. |
| University Medical Center Partnerships | Shared clinical validation costs address escalating evidentiary burdens for gut microbiome modulation claims. |
| Corporate Wellness Program Integration | Employer-subsidized subscriptions reduce customer acquisition costs among workplace professionals. |
| Backward Integration into Culture Supply | Captive Bifidobacterium strain production mitigates raw material concentration risk among limited biotech suppliers. |
Study Parameters
Document review covered METI regulatory filings, PMDA strain approval databases, and Consumer Affairs Agency FFC notification records, complemented by interviews with R&D directors at functional food manufacturers, regulatory affairs specialists, and category buyers at Tokyo metropolitan retailers. Primary fieldwork included discussions with university medical center research partners and cold-chain logistics operators. Secondary validation drew from trade customs data, dairy cooperative production reports, and retail audit databases. Bottom-up strain-level demand modeling and top-down market sizing were cross-referenced for triangulation.
Historical consumption patterns were cross-referenced against panel input from distribution channel partners to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, application target, distribution channel, and regional demographic cluster. CAGRs were derived from slope analysis of validated data points. Industry-specific forecast inputs incorporated METI FFC approval velocity and PMDA pharmaceutical-grade claim progression timelines.
Revisions become necessary when METI evidentiary guideline shifts, PMDA approval reversals, or raw culture supply disruptions materialize. Forecasts reflect assumptions about regulatory stability and cold-chain infrastructure continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
South America Probiotics Market