
 Europe Probiotic Supplements Market | 2026-2036
Europe Probiotic Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Probiotic Supplements Market Intelligence
Microbiome science expertise is redrawing competitive boundaries in the European probiotic sector. Novonesis leverages deep strain-banking capabilities to anchor its position in clinically validated formulations. Danone S.A. competes through extensive dairy-based distribution networks spanning Western Europe. Winclove Probiotics specializes in multi-strain custom blends for pharmaceutical partners.
Probiotic supplements contain live microorganisms, typically Lactobacillus and Bifidobacterium species at minimum viable counts of 10^6 to 10^11 CFU per serving, delivered in stabilized matrices to ensure gastric survival and intestinal colonization for digestive and immune modulation. Capsules dominate volume due to shelf-stability and precise dosing, while synbiotics represent the fastest-expanding formulation category as prebiotic fiber pairing enhances colonization efficacy. Online Retail channels are capturing disproportionate growth among athlete and senior segments seeking subscription-based replenishment models.
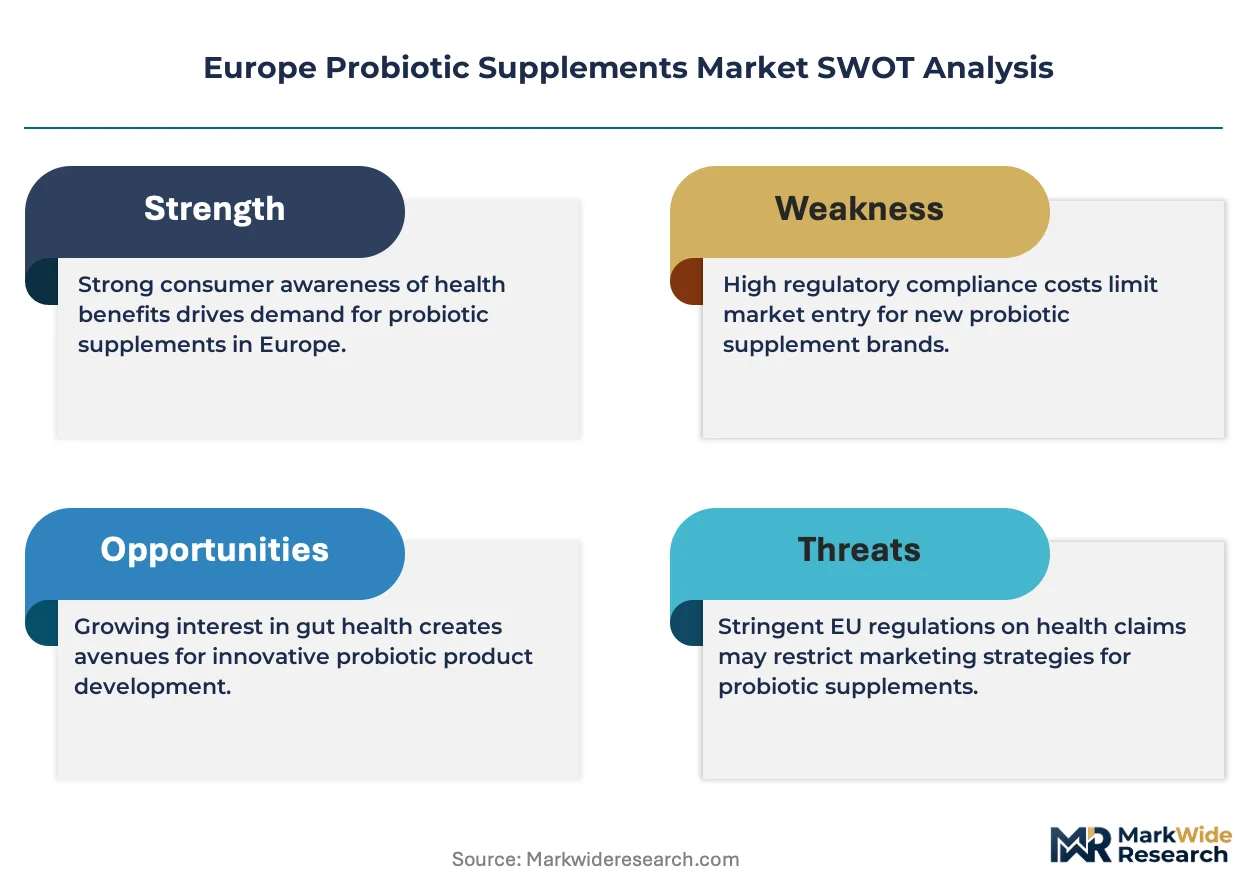
EFSA maintains stringent health claim authorization under EU Regulation 1924/2006, requiring human intervention studies for any implied disease-risk reduction, while national regulators in France and Germany enforce additional pharmacovigilance for products exceeding defined CFU thresholds. The EU Green Deal's sustainable packaging mandates are pressuring manufacturers to reformulate encapsulation materials away from petroleum-derived polymers. Stakeholders must monitor evolving Novel Food classifications for next-generation genetically characterized strains.
Market Dynamics
EFSA's tightening substantiation requirements under EU Regulation 1924/2006 are forcing manufacturers to rebuild clinical validation pipelines, while Germany's pharmacovigilance thresholds for high-CFU products are compressing formulation strategies across the continent.
Growth Catalysts
- EFSA Health Claim Pathways:Manufacturers investing in human intervention studies gain durable competitive moats as unauthorized claims face enforcement action.
- Germany's Clinical Recommendation Networks:Digestive health protocols from Berlin and Munich clinicians drive pharmacy channel penetration for validated strains.
- Synbiotic Formulation Science:Prebiotic fiber pairing with live cultures improves colonization metrics, expanding addressable populations beyond traditional supplement users.
Market Restraints
- Petroleum-Derived Encapsulation Dependencies:The EU Green Deal's sustainable packaging mandates threaten supply continuity for conventional gelatin and HPMC shell materials.
- Strain Banking Concentration:Deep microbial libraries reside with a limited set of Dutch and Danish biobanks, creating licensing bottlenecks for new entrants.
- Novel Food Classification Uncertainty:Genetically characterized next-generation strains face protracted safety assessments, delaying commercialization timelines.
Strategic Opportunities
- France's Aging Demographics:Gut microbiome maintenance protocols among retirees over 65 present untapped subscription revenue potential.
- Athlete Segment Digital Capture:Direct-to-consumer platforms with personalized replenishment algorithms bypass traditional pharmacy markups.
- CSRD-Aligned Sustainability Narratives:Carbon-footprint labeling and regenerative agriculture sourcing create differentiation vectors for premium positioning.
Industry Challenges
- Microbiome Research Talent Scarcity:Strain characterization and clinical trial design expertise concentrates within academic institutions in Leiden and Copenhagen.
- Legacy Distribution Integration:Pharmacy chains demand real-time inventory visibility that conflicts with live culture shelf-stability requirements.
Report Scope
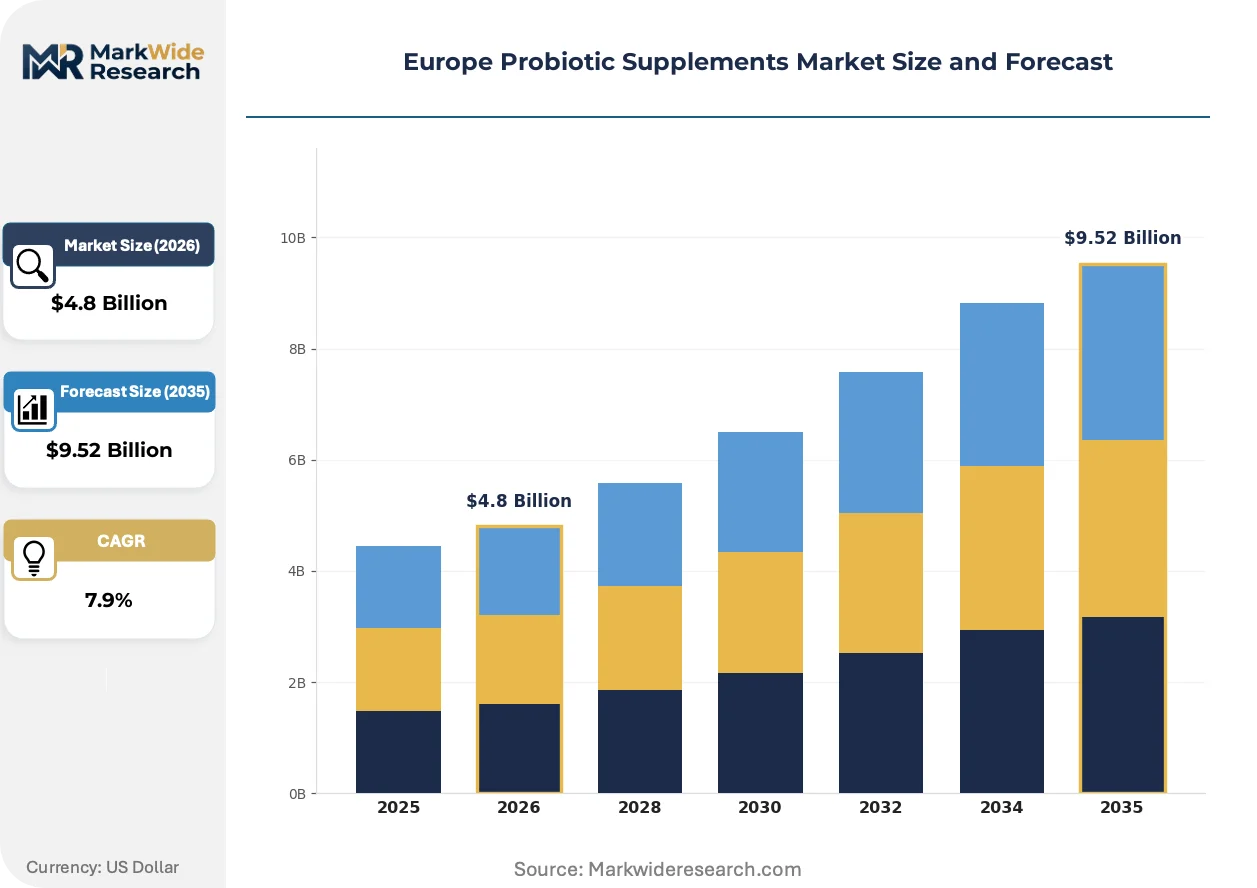
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Probiotic Supplements Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquids, Gummies Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores End User: Adults, Children, Seniors, Athletes Formulation: Multi-Strain, Single-Strain, Synbiotics, Dairy-Based |
| Companies Covered | Probi, Nestlé S.A., Novonesis, Winclove Probiotics, Yakult Honsha Co., Ltd., DSM-Firmenich, Danone S.A., OptiBac, BioGaia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Probiotic Supplements Market Strategic Shifts & Innovations
Live culture stabilization technologies and digital health integration are redrawing how European consumers access and sustain probiotic regimens, with regulatory science increasingly determining which innovations reach commercial scale.
Microencapsulation via alginate-chitosan matrices is fragmenting the dominance of traditional freeze-dried powders. Sports nutrition brands in the United Kingdom are adopting these systems at accelerated procurement cycles. The technology is fragmenting shelf-life assumptions, enabling ambient distribution models that bypass cold chain infrastructure.
EFSA's 2023 guidance on quantified disease-risk reduction claims has tightened human study requirements for implied cardiovascular and metabolic benefits. Manufacturers now face expanded clinical trial budgets to maintain existing label language. French and German regulators are enforcing additional pharmacovigilance reporting for products exceeding 10^10 CFU per serving, compressing formulation ceilings.
Subscription-based replenishment models are displacing single-unit pharmacy purchases among performance-oriented consumers. Digital health platforms in the United Kingdom and Netherlands bundle microbiome testing with personalized strain recommendations. Senior populations in France show strongest adoption of auto-ship programs for digestive maintenance protocols.
Europe Probiotic Supplements Market Segmentation
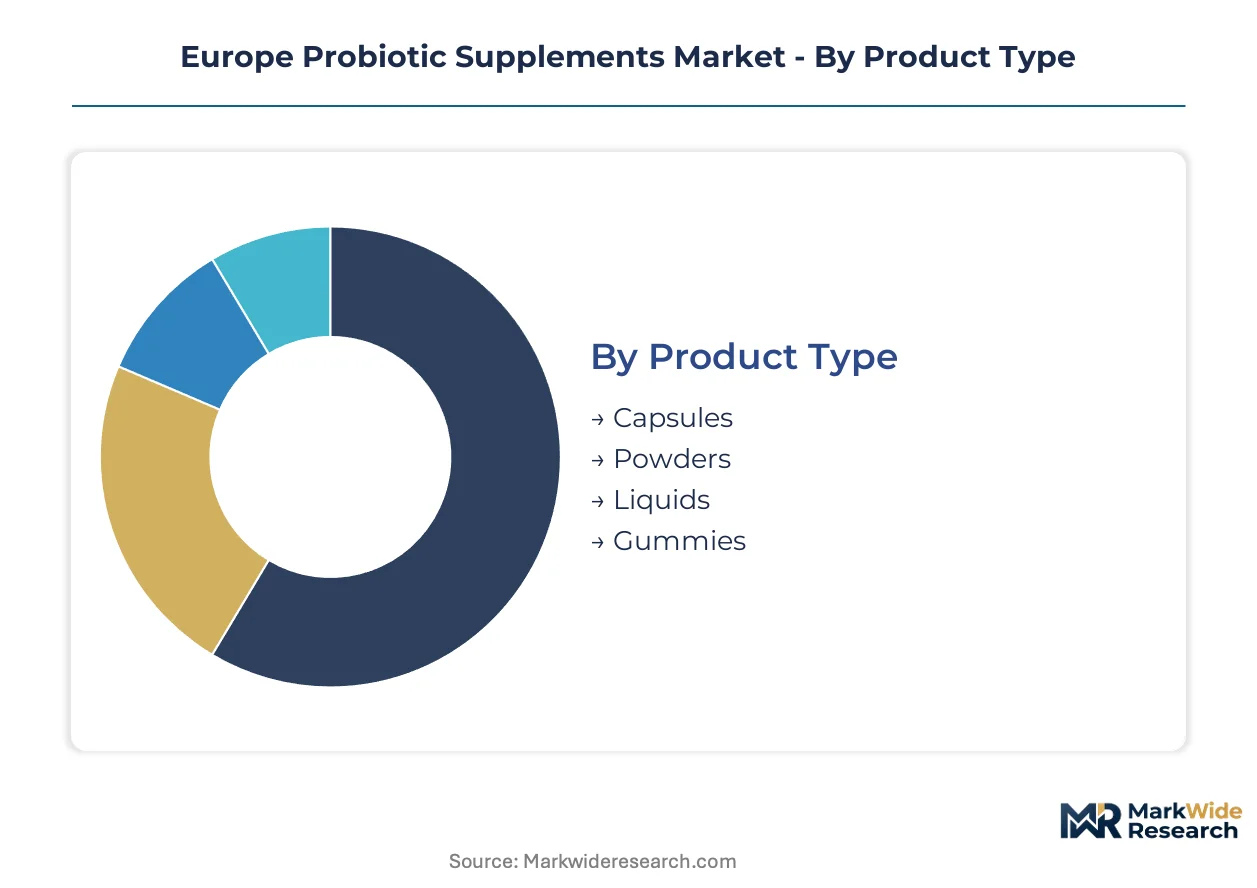
Probiotic supplement manufacturers in Europe calibrate portfolio depth against divergent margin structures across delivery formats and purchasing occasions. Strain specificity, shelf-stability requirements, and regulatory substantiation costs fragment profitability pools unevenly across segment boundaries.
Product Type:
Margin concentration in this category tracks directly to encapsulation complexity and cold-chain independence.
- Capsules:Gelatin and hydroxypropyl methylcellulose shells stabilize Lactobacillus and Bifidobacterium counts through 24-month shelf lives without refrigeration. German pharmacy chains prioritize capsule formats for their inventory predictability and precise unit dosing aligned with EFSA substantiation protocols.
- Powders:Sachet and bulk powder formats carry lower per-unit production costs but sacrifice margin to flavor masking and moisture barrier requirements. Demand clusters in France among senior populations mixing powders into yogurts and beverages for flexible dosing regimens.
- Liquids:Dropper bottles and ready-to-drink formulations require refrigerated distribution, compressing addressable retail footprints to health stores with cold storage.
- Gummies:Confectionery-based delivery appeals to pediatric and compliance-sensitive segments but faces sugar content scrutiny under EU nutrition claims.
The dominant share belongs to Capsules, while Gummies is closing the gap fastest through pharmacy channel expansion in the United Kingdom.
Distribution Channel:
Channel selection in Europe increasingly determines which customer segments manufacturers can economically reach and retain.
- Online Retail:Direct-to-consumer platforms capture subscription revenue from athletes and seniors seeking strain-specific replenishment with microbiome testing integration. Netherlands-based digital health bundlers are displacing single-unit pharmacy purchases through personalized recommendation algorithms.
- Pharmacies:German and French pharmacy networks enforce pharmacovigilance documentation for products exceeding 10^10 CFU thresholds, creating credential barriers that validated strain suppliers exploit. Berlin and Munich clinician recommendations drive protocol-based purchasing through this channel.
- Supermarkets:Mass retail placement prioritizes shelf-stable capsules with simplified health claims, limiting strain diversity to EFSA-approved generic language.
- Health Stores:Specialized retailers stock refrigerated liquids and practitioner-exclusive multi-strain blends for educated consumers seeking colonization efficacy over convenience.
Pharmacies retain the largest transaction volume, though Online Retail is climbing the fastest among under-45 demographics.
End User:
User segmentation in this market reflects physiological life stages and performance demands that reshape formulation priorities.
- Adults:Working-age consumers between 25 and 55 drive baseline digestive maintenance demand, with French and United Kingdom buyers showing strongest adoption of daily supplementation routines.
- Seniors:Adults over 65 in France represent concentrated demand for gut microbiome maintenance protocols addressing antibiotic recovery and immune modulation, with auto-ship subscription models gaining traction.
- Children:Pediatric formulations face stricter Novel Food classification scrutiny in the EU, delaying strain approvals and compressing commercial timelines for dedicated SKUs.
- Athletes:Performance-oriented consumers in the United Kingdom prioritize synbiotic formulations with protein co-delivery, procuring through specialized sports nutrition platforms that bypass traditional retail markups.
Adults command the broadest installed base, yet Seniors is gaining share fastest through France's aging demographic tailwind.
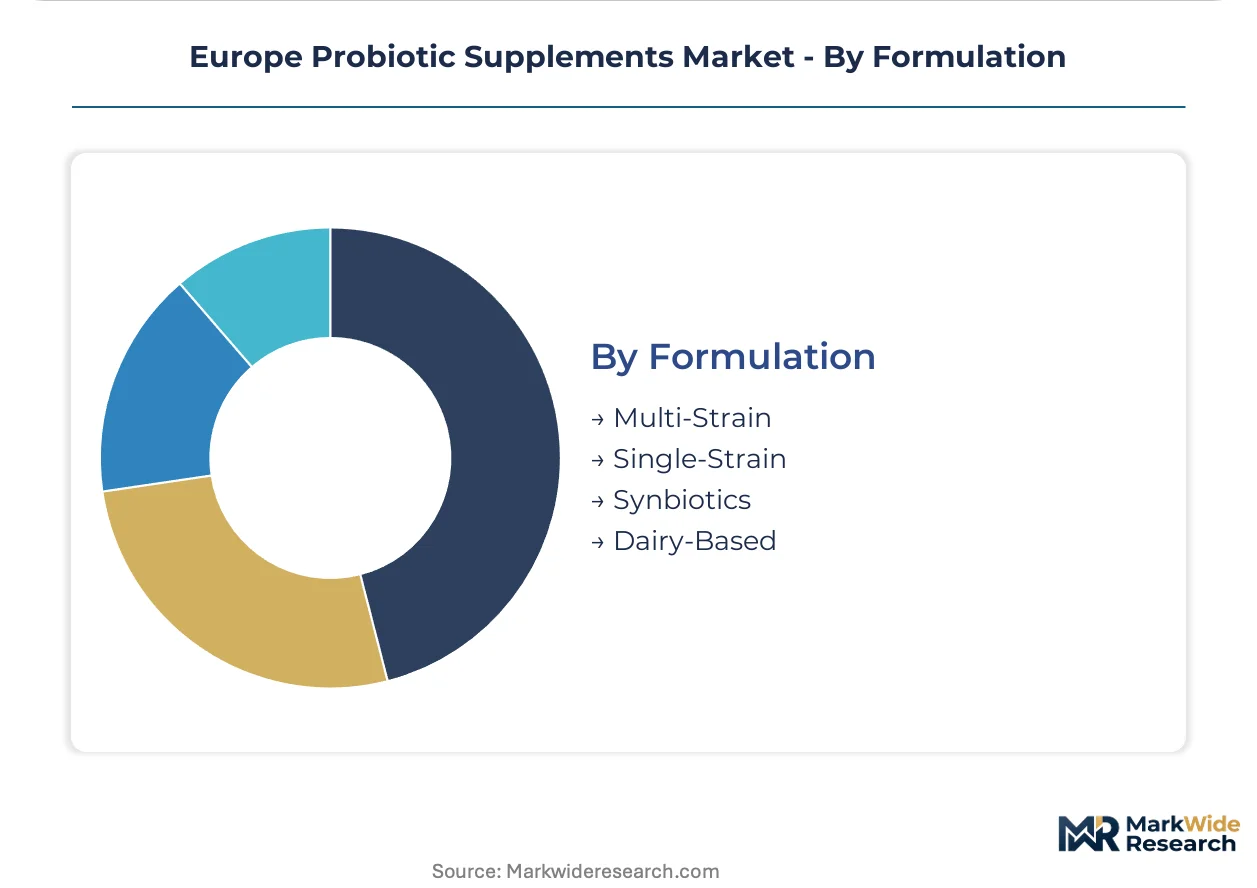
Formulation:
Formulation architecture separates commodity suppliers from clinically differentiated competitors in European probiotic markets.
- Synbiotics:Prebiotic fiber pairing with live cultures—typically inulin or galactooligosaccharides with Lactobacillus rhamnosus or Bifidobacterium lactis—demonstrates superior colonization metrics in human intervention studies. United Kingdom sports nutrition brands have accelerated procurement of alginate-chitosan microencapsulated synbiotics for ambient distribution.
- Multi-Strain:Custom blends of 5-12 characterized strains require deep microbial libraries and clinical validation budgets that concentrate supply among Dutch and Danish biobank licensees. Winclove Probiotics anchors this segment through pharmaceutical partnership models.
- Single-Strain:Isolated Lactobacillus or Bifidobacterium offerings simplify EFSA substantiation pathways but sacrifice differentiation in crowded pharmacy shelves.
- Dairy-Based:Traditional fermented delivery vehicles retain presence in Southern European markets but face compression from plant-based and ambient-stable alternatives.
Multi-Strain formulations hold established revenue leadership, while Synbiotics is expanding most quickly through colonization efficacy claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Germany diverge sharply in consumption patterns, with French seniors favoring powder formats mixed into daily foods while German clinicians drive pharmacy-based capsule protocols through formal digestive health recommendations.
Germany
Clinicians in Berlin and Munich actively prescribe multi-strain formulations through pharmacy networks, creating protocol-driven demand distinct from self-directed purchasing elsewhere. ANSM-aligned pharmacovigilance thresholds for products exceeding 10^10 CFU compress formulation ceilings and elevate documentation requirements. The Baden-Württemberg cluster hosts strain characterization facilities supplying validated cultures to pharmaceutical partners across Central Europe.
France
Adults over 65 constitute the fastest-expanding user segment, with retirees in Île-de-France adopting subscription-based auto-ship programs for gut microbiome maintenance. EFSA health claim regulations under EU Regulation 1924/2006 enforce strict substantiation for any implied disease-risk reduction on packaging. The Lyon biotech corridor concentrates microencapsulation R&D facilities developing alginate-chitosan matrices for ambient-stable delivery.
United Kingdom
Athletes and performance-oriented consumers drive disproportionate growth through direct-to-consumer platforms bundling microbiome testing with personalized strain recommendations. The UK regulator enforces additional scrutiny on novel synbiotic combinations seeking market authorization. Sports nutrition brands in Greater Manchester and London accelerate procurement cycles for ambient-distribution formulations.
Netherlands
Digital health platforms based in Amsterdam and Rotterdam displace traditional pharmacy purchases through algorithm-driven replenishment models. The Dutch national food safety authority aligns with EFSA guidance while maintaining streamlined Novel Food assessment pathways for characterized strains. Leiden anchors academic microbiome research partnerships that feed into commercial strain development pipelines.
Italy
Southern European markets retain stronger dairy-based probiotic consumption patterns, though plant-based alternatives gain traction in Milan and Rome metro areas. Italian regulators enforce EU Green Deal packaging mandates with particular attention to petroleum-derived encapsulation materials. The Emilia-Romagna food technology cluster experiments with fermented delivery vehicles bridging traditional and supplement formats.
Europe Probiotic Supplements Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding strain-banking assets and clinical validation pipelines that smaller entrants cannot replicate. The mid-tier fragments across formulation specialists, dairy-based distributors, and digital-native challengers. Two archetypes dominate: vertically integrated biobank operators with captive strain libraries, and pharmaceutical partnership specialists delivering custom multi-strain blends. Competitive moves concentrate on M&A for microbial library access and technology licensing for microencapsulation capabilities.
Among Danish and Dutch integrated leaders, Novonesis anchors the strain-banking archetype through deep microbial libraries, while DSM-Firmenich occupies a position spanning ingredient supply and finished formulation. Winclove Probiotics exemplifies the pharmaceutical partnership specialist model, delivering custom multi-strain blends to licensed manufacturers. These three represent distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Probi |
| Nestlé S.A. |
| Novonesis |
| Winclove Probiotics |
| Yakult Honsha Co., Ltd. |
| DSM-Firmenich |
| Danone S.A. |
| OptiBac |
| BioGaia |
| Others |
Cost & Logistics Intelligence
Alginate-chitosan microencapsulation replacing traditional freeze-dried matrices is redrawing supply geography toward Lyon and Rotterdam R&D clusters while compressing per-unit production economics for ambient-stable formulations. This substitution simultaneously elevates ingredient costs and extends distribution reach beyond cold-chain-dependent retail footprints.
Pricing Analysis
Long-term offtake contracts between Dutch biobanks and pharmaceutical partners anchor pricing stability for validated multi-strain libraries, while spot procurement dominates commodity single-strain offerings. Three-tier pricing structure across premium clinically-validated, standard pharmacy-grade, and economy mass-retail tiers tracks certification depth and EFSA substantiation status. Pricing pressure stems from petroleum-derived encapsulation cost volatility under EU Green Deal mandates. Athlete segments through UK direct-to-consumer platforms show lowest price sensitivity, while French senior powder buyers prioritize per-dose economy over brand premium.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain margin recovery for refrigerated liquid formulations dependent on containerized cold-chain capacity. Deep microbial libraries concentrate in Denmark and the Netherlands, with strain characterization expertise anchored in Leiden and Copenhagen academic partnerships. Raw material dependencies span pharmaceutical-grade gelatin, prebiotic inulin from chicory root, and alginate from North Atlantic seaweed harvests. Single-source vulnerability runs through Dutch biobank licensing bottlenecks for next-generation genetically characterized strains. Distribution runs through German pharmacy networks for clinician-prescribed protocols and Netherlands-based digital platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain characterization expertise and clinical validation infrastructure are consolidating within a handful of academic-corporate partnerships, creating durable capability moats that reshape competitive entry economics across the continent.
For Market Incumbents: Compound defensive positioning through captive strain-banking acquisitions and expanded EFSA substantiation pipelines for cardiovascular and metabolic health claims. Deepen backward integration into alginate-chitosan microencapsulation production to offset petroleum-derived shell material cost volatility. Priority lever rests on locking multi-year offtake agreements with Rotterdam and Hamburg logistics providers before ambient-stable formulation proliferation intensifies port capacity competition. For New Entrants and Emerging Players: EFSA Novel Food fast-track pathways for characterized Lactobacillus and Bifidobacterium strains present the most penetrable regulatory entry point, particularly for single-strain offerings below 10^10 CFU thresholds avoiding German pharmacovigilance documentation. Target France's aging demographic auto-ship segment through powder format subscription models bypassing pharmacy credential barriers. Go-to-market angle centers on bundling microbiome testing with personalized strain recommendations through algorithm-driven digital platforms displacing traditional retail markups. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated strain-banking operators with captive microbial libraries and established pharmaceutical partnership networks. Long-term viability across the analysis window hinges on regulatory science capabilities enabling EFSA health claim authorization. Acquisition target archetype encompasses Dutch and Danish biobank licensees with multi-strain custom blend expertise. Signal to watch is EFSA guidance expansion on quantified disease-risk reduction claims, which would recalibrate clinical validation investment thresholds industry-wide.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Acquisition | Captive microbial libraries from Leiden and Copenhagen biobanks secure multi-strain formulation pipelines. |
| EFSA Substantiation Investment | Human intervention studies for cardiovascular claims create durable competitive moats against unauthorized competitors. |
| Ambient Distribution Expansion | Alginate-chitosan microencapsulation bypasses cold-chain infrastructure constraints across UK sports nutrition channels. |
| Subscription Platform Development | Auto-ship algorithms for French senior segments displace single-unit pharmacy purchases with predictable recurring revenue. |
| Sustainable Encapsulation Transition | EU Green Deal compliance for petroleum-derived shell alternatives protects supply continuity for German pharmacy networks. |
Research Approach
The analysis maps capsule, powder, liquid, and gummy delivery formats, each validated through interviews with strain characterization scientists, pharmacy procurement managers, regulatory affairs leads at EFSA-notified bodies, and digital health platform operators. Primary fieldwork combined with secondary validation from EFSA health claim registers, EU Novel Food catalogs, ANSM pharmacovigilance documentation, and customs trade data for alginate and prebiotic fiber imports. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass product type, distribution channel, end-user life stage, and formulation architecture. CAGRs derived from fitted growth curves incorporating EFSA regulatory timeline assumptions, French demographic aging trajectories, and UK athlete segment digital adoption rates. Industry-specific inputs included strain characterization facility capacity utilization and microencapsulation technology procurement cycles.
Underlying assumptions cover EFSA authorization pathway timelines, EU Green Deal packaging mandate implementation, and German pharmacovigilance threshold stability, with deviation risk concentrated in Novel Food reclassification for genetically characterized strains and geopolitical disruption to North Atlantic seaweed supply. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Shelf Stable Probiotics Market