
 Probiotic Confectionery Market | 2026-2036
Probiotic Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Confectionery Market Analytics
Japan is tilting toward expanded probiotic confectionery capacity as domestic fermentation expertise meets rising export interest. Meiji Holdings Co., Ltd. leverages its century-long dairy culture heritage to anchor premium tablet formats across Asian pharmacy networks. Danone S.A. competes through specialized R&D pipelines that isolate shelf-stable strains for chocolate applications. Nestlé S.A. controls broad retail distribution, positioning probiotic gummies within mainstream confectionery aisles rather than segregated health sections.
Probiotic confectionery denotes sweetened edible formats incorporating live or stabilized beneficial microorganisms, typically Lactobacillus or Bifidobacterium species, at minimum viable counts of 10^6 to 10^9 CFU per serving at end of shelf life. These products deliver targeted digestive or immune health benefits through controlled-release matrices that protect cultures from gastric acid. Gummies dominate volume due to their palatability bridge between supplements and treats, while chocolates command margin pools through premium positioning and fat-based encapsulation that enhances strain survival. The adult end-user segment leads absolute consumption, though senior-targeted formulations with elevated CFU counts and vitamin co-fortification represent the fastest-growing structural pocket.
EFSA's health claims regulation and FDA's dietary supplement GMPs enforce stringent substantiation for live-count declarations, reshaping formulation investments toward stability-validated strains. Japan's FOSHU system creates a separate compliance pathway that rewards clinical evidence with permitted functional claims, diverting R&D resources toward trial-backed products. Stakeholders must monitor evolving strain-specific approval frameworks and decide whether to pursue pharmaceutical-grade positioning or remain within food-supplement regulatory corridors.
Market Dynamics
Strain stability validation under gastric conditions is forcing reformulation investments across the probiotic confectionery value chain, as regulatory bodies demand verifiable live-count retention through shelf life and digestive transit.
Growth Catalysts
- EFSA's substantiation framework:The regulation mandates clinical evidence for functional claims, elevating products with trial-backed strain documentation above commodity competitors in European pharmacy channels.
- Adult wellness segments:Health-conscious consumers aged 35-55 are integrating microbiome-supporting formats into daily routines, expanding addressable demand beyond traditional supplement users.
- Fat-based encapsulation:Chocolate matrices employing lipid shielding technology protect Bifidobacterium species from gastric acid, improving viable delivery to the intestinal tract.
Market Restraints
- Temperature sensitivity:Cold-chain requirements for live-culture gummies inflate logistics costs and limit distribution reach in emerging markets with inadequate refrigeration infrastructure.
- Strain supplier concentration:Premium clinically validated cultures originate from a concentrated base of European and Japanese fermentation specialists, creating input bottlenecks during demand surges.
- Stability-ceiling limitations:Current encapsulation technologies cannot guarantee 10^9 CFU survival beyond 18 months in ambient confectionery storage, constraining mass-market shelf placement.
Strategic Opportunities
- Senior-targeted co-fortification:Elevated CFU counts combined with vitamin D and calcium address aging digestive health needs in Japan's expanding elderly demographic.
- Direct-to-consumer subscription channels:Recurring delivery models bypass pharmacy margin compression while enabling personalized strain-matching based on consumer microbiome profiles.
- Japan's FOSHU approval pathway:The system rewards clinical investment with permitted functional claims, creating premium positioning unavailable in standard food-supplement categories.
Industry Challenges
- Strain enumeration expertise:Accurate CFU quantification at end-of-shelf-life requires specialized microbiology capabilities scarce among traditional confectionery manufacturers.
- Cross-functional integration:Combining food-grade palatability with pharmaceutical-grade stability demands coordination between R&D, quality assurance, and regulatory affairs that legacy organizational structures struggle to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Confectionery Market |
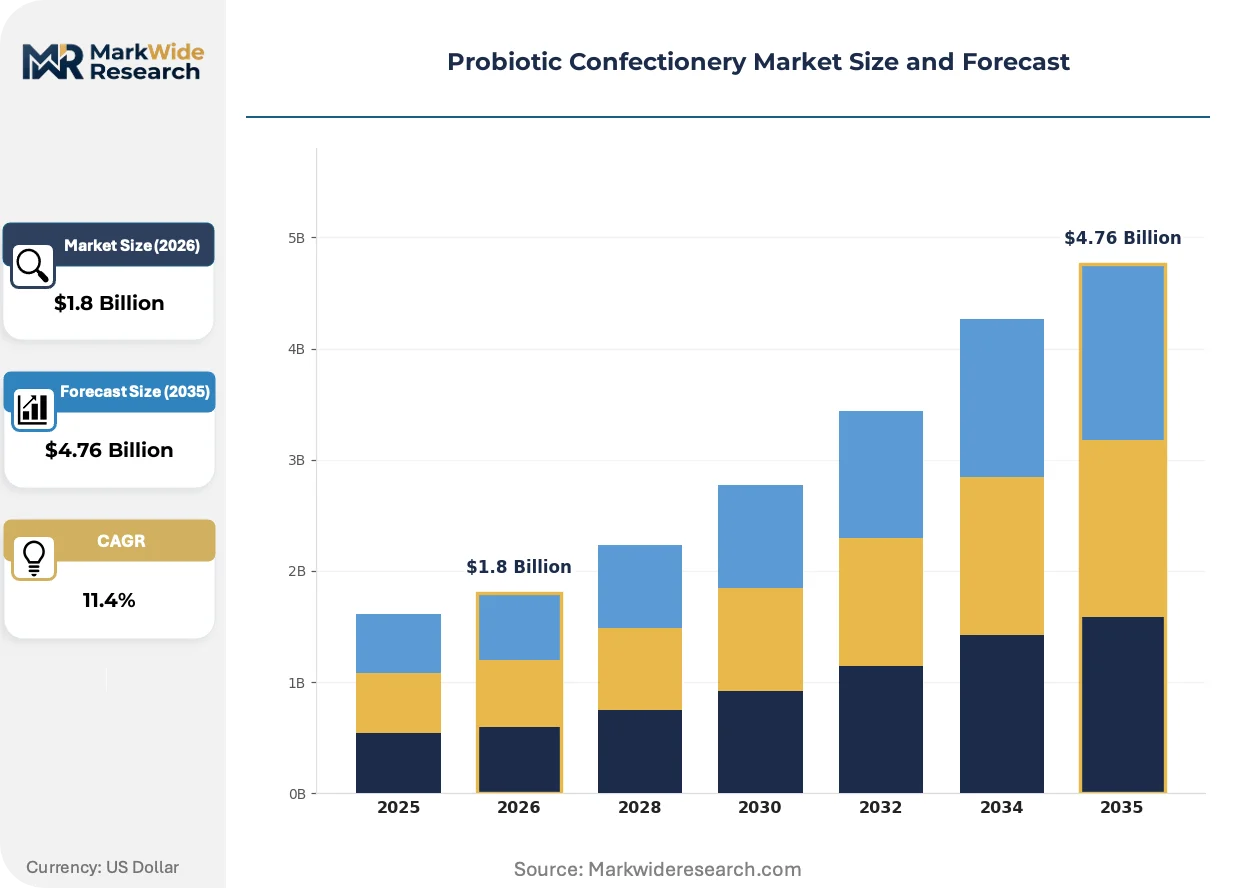
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Candies, Tablets, Gummies, Chocolates End User: Children, Adults, Seniors, Health Enthusiasts Ingredient Source: Plant-Based, Dairy-Based, Fermented, Prebiotic-Enriched Distribution Channel: Online Stores, Supermarkets, Health Food Shops, Pharmacies |
| Companies Covered | General Mills, Inc., Meiji Holdings Co., Ltd., Danone S.A., Probi AB, Chobani LLC, Nestlé S.A., Kerry Group plc, Lallemand Inc., Yakult Honsha Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Confectionery Market Evolving Landscape
Microbiome personalization and strain-specific clinical validation are compressing the gap between confectionery indulgence and therapeutic efficacy, reshaping how manufacturers balance sensory appeal with bioactive delivery.
Smart packaging incorporating time-temperature indicators and NFC-enabled traceability is digitizing supply chain transparency for probiotic confectionery. Pharmacy buyers in Germany and Japan are mandating real-time viability verification. The technology is digitizing quality assurance protocols previously reliant on batch testing alone.
Japan's FOSHU system revisions now require post-market surveillance for approved probiotic claims, tightening accountability for sustained efficacy. Manufacturers must maintain strain-specific clinical databases throughout product lifecycles. Chocolate applications with shelf-stable spore-forming cultures face heightened scrutiny under these expanded monitoring obligations.
Subscription-based microbiome testing services are redirecting purchase decisions toward strain-matched confectionery formats. Consumers in the United States receive personalized recommendations linking their gut profiles to specific Lactobacillus or Bifidobacterium SKUs. This behavior concentrates loyalty within vertically integrated brands offering both diagnostic and consumable components.
Probiotic Confectionery Market Segmentation
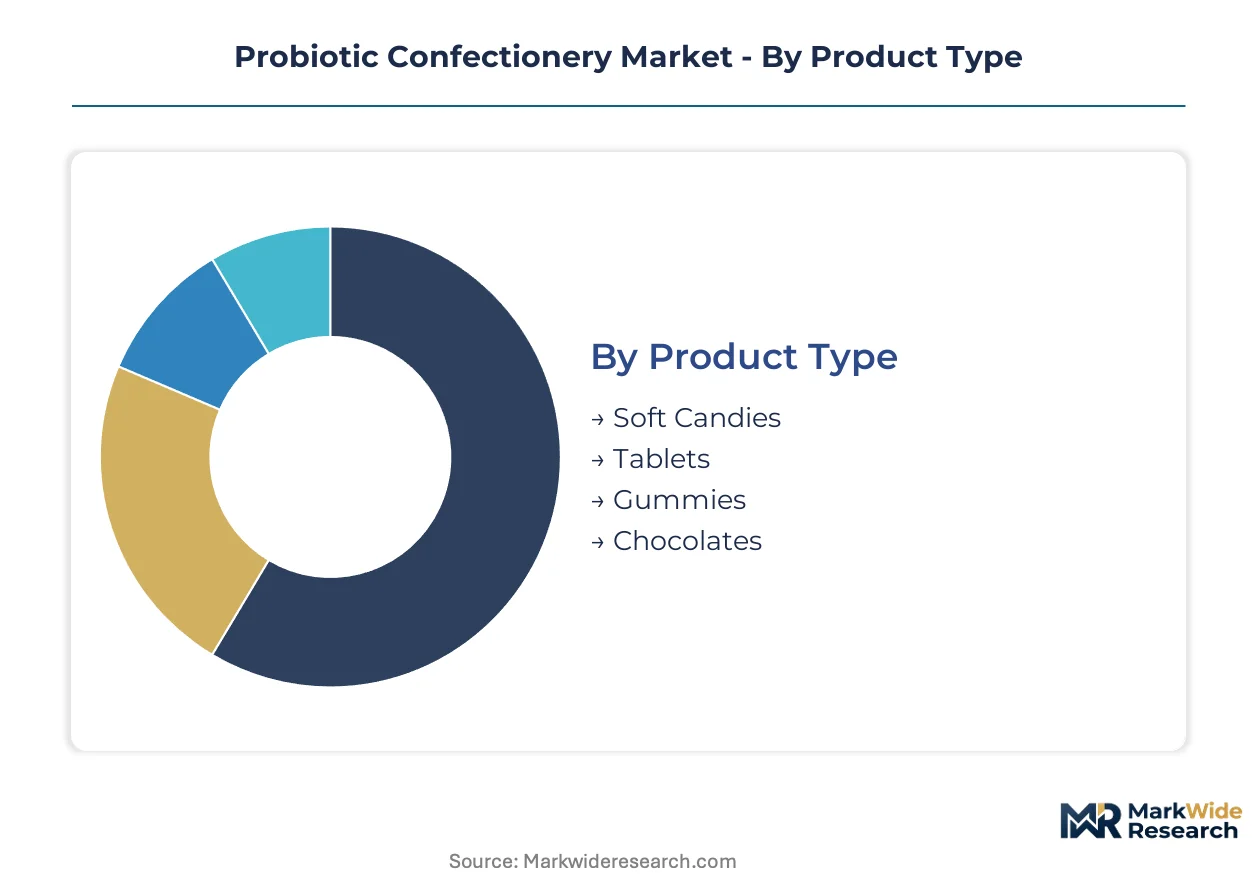
Probiotic confectionery segmentation reflects a market caught between pharmaceutical-grade efficacy demands and mass-market palatability expectations. Manufacturers must navigate strain stability requirements, regulatory corridors, and channel-specific positioning simultaneously.
Product Type:
Mature formats dominate absolute volume while emerging matrices attract reformulation investment for enhanced bioactive delivery.
- Gummies:Gelatin or pectin-based matrices carrying 10^6 to 10^9 CFU per serving, often employing microencapsulation to shield cultures from gastric acid. Adult wellness consumers aged 35-55 in the United States and Germany drive repeat purchases through pharmacy and subscription channels, though temperature sensitivity constrains ambient retail expansion.
- Chocolates:Cocoa butter matrices utilizing lipid-based encapsulation to protect Bifidobacterium species during digestive transit, commanding premium positioning through fat-phase stability advantages. Japanese health food shops and German pharmacy networks stock elevated-CFU variants targeting senior digestive health needs.
- Tablets:Compressed formats with extended shelf-life profiles through low-moisture excipient systems, favored in Asian pharmacy networks for precise dosing.
- Soft Candies:High-moisture formats requiring specialized strain selection for viability retention, limited to cold-chain distribution in developed markets.
Gummies retain volume leadership; chocolates hold the steepest expansion curve through premium margin capture and encapsulation technology advances.
End User:
Application concentration varies sharply by CFU specification, co-fortification requirements, and channel access patterns.
- Adults:Core volume segment integrating microbiome support into daily routines, typically purchasing 10^8 CFU gummies through mainstream retail. United States health food shops and German supermarkets stock the broadest SKU ranges for this cohort.
- Seniors:Fastest-climbing demand pocket requiring elevated viable counts (10^9 CFU) plus vitamin D and calcium co-fortification. Japan's expanding elderly demographic and pharmacy-centric distribution model align with FOSHU-eligible clinical positioning.
- Health Enthusiasts:Early adopters of microbiome-personalized formats linked to diagnostic services, concentrated in direct-to-consumer subscription channels.
- Children:Palatability-driven formats with lower CFU thresholds and strict safety substantiation requirements, limited by regulatory caution in European markets.
Adults anchor absolute consumption; seniors are gaining share fastest through aging demographics and targeted formulation.
Ingredient Source:
Supply concentration in European and Japanese fermentation specialists shapes availability and cost structures across source categories.
- Dairy-Based:Traditional cultures from Lactobacillus and Bifidobacterium species with extensive clinical documentation, dominating pharmacy-grade positioning. Strain supplier bottlenecks emerge during demand surges for validated cultures.
- Plant-Based:Fermented substrates from oat, coconut, or almond matrices capturing flexitarian and vegan-adjacent demand in United States health food channels.
- Fermented:Kefir-derived or kombucha-adjacent cultures with artisanal positioning, limited by standardization challenges for CFU enumeration.
- Prebiotic-Enriched:Synbiotic formats combining live cultures with inulin or oligosaccharide substrates, requiring careful moisture management in confectionery matrices.
Dairy-based formats dominate pharmacy channels; plant-based alternatives are expanding most quickly through ethical positioning and allergen avoidance.
Distribution Channel:
Channel selection determines regulatory compliance burden, margin structure, and consumer education requirements.
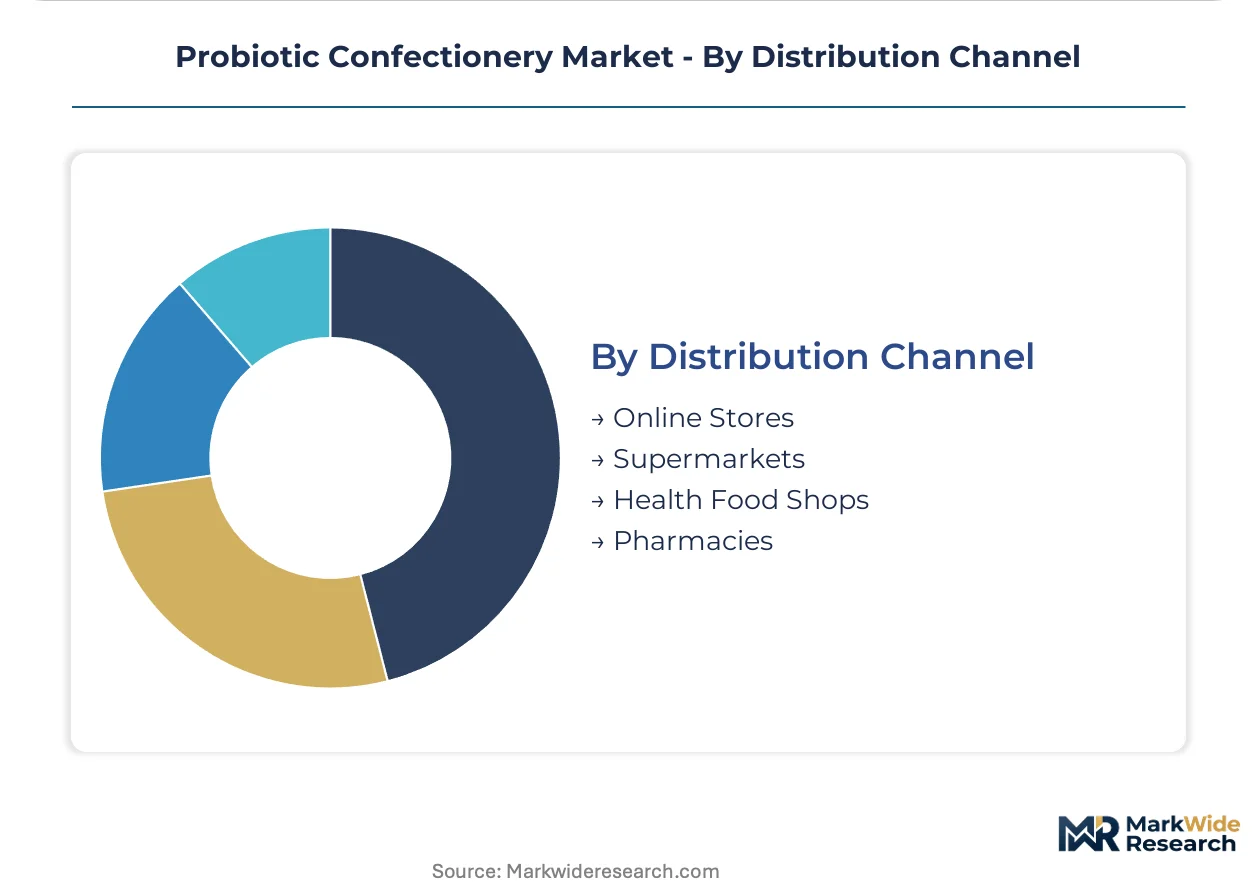
- Pharmacies:Professional recommendation environment supporting premium pricing for clinically validated strains, dominant in Germany and Japan where EFSA and FOSHU frameworks elevate substantiation standards.
- Health Food Shops:Curated assortments targeting wellness-focused consumers with transparent labeling and strain-specific information, concentrated in United States coastal cities.
- Online Stores:Direct-to-consumer and subscription models enabling personalized strain-matching and bypassing retail margin compression, with NFC-enabled traceability increasingly standard.
- Supermarkets:Mass-market placement requiring ambient stability and simplified claims, constrained by 18-month CFU survival limitations in current encapsulation technologies.
Pharmacies control premium positioning; online channels are climbing the fastest through subscription loyalty and diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: pharmacy-centric Germany and Japan favor clinically validated tablet formats, while the United States gravitates toward gummy subscriptions and mass-market retail placement.
United States
Direct-to-consumer subscription models dominate, with personalized microbiome testing services driving strain-matched gummy purchases. FDA dietary supplement GMPs enforce live-count substantiation, elevating products with stability documentation. Los Angeles and New York health food corridors concentrate demand for plant-based and vegan-adjacent formulations.
Germany
Pharmacy networks anchor distribution, with EFSA health claims regulation mandating clinical evidence for functional positioning. Consumers aged 35-55 integrate microbiome support into daily wellness routines. The Baden-Württemberg industrial cluster hosts fermentation specialists supplying validated cultures to regional confectionery manufacturers.
Japan
FOSHU system revisions now require post-market surveillance for approved probiotic claims, tightening manufacturer accountability. Tokyo and Osaka pharmacy networks stock elevated-CFU tablet formats targeting senior digestive health. Meiji Holdings leverages century-long dairy culture heritage to anchor premium positioning across Asian export markets.
Switzerland
Swissmedic oversight elevates substantiation standards for cross-border pharmacy distribution. Premium chocolate matrices with lipid-based encapsulation command margin pools through fat-phase stability advantages. The Zurich-Geneva corridor concentrates R&D investment in shelf-stable spore-forming culture applications.
United Kingdom
Health food shops in London and Manchester curate assortments with transparent strain-specific labeling. MHRA alignment with EFSA frameworks shapes import requirements for European-manufactured SKUs. Subscription channels bypass traditional retail margin compression while enabling personalized strain-matching services.
Probiotic Confectionery Market Competitive Landscape
Capability concentration sits with fermentation specialists holding validated strain libraries; scale advantage sits with multinational confectionery and dairy conglomerates with established retail distribution. The market structures around three tiers: pharmaceutical-grade formulators, mass-market confectionery integrators, and diagnostic-linked direct-to-consumer platforms. Dominant competitive moves include backward integration into strain cultivation and geographic expansion through FOSHU-eligible product registration in Japan.
Within the fermentation specialist tier, Probi AB and Lallemand Inc. represent archetypal European culture suppliers whose validated strain documentation enables pharmacy-grade positioning for downstream confectionery partners. Among Asia-Pacific heritage players, Meiji Holdings Co., Ltd. and Yakult Honsha Co., Ltd. occupy positions bridging dairy fermentation expertise with confectionery format innovation, particularly for tablet and gummy applications requiring extended shelf-life profiles. These named entities exemplify how geographic origin and corporate structure shape competitive archetype allocation without guaranteeing specific market outcomes.
| Leading Market Players |
|---|
| General Mills, Inc. |
| Meiji Holdings Co., Ltd. |
| Danone S.A. |
| Probi AB |
| Chobani LLC |
| Nestlé S.A. |
| Kerry Group plc |
| Lallemand Inc. |
| Yakult Honsha Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Undercapacity in European strain cultivation facilities is compressing supplier margins while amplifying pricing power for validated culture holders, forcing confectionery formulators to absorb input premiums or reformulate toward lower-CFU specifications.
Pricing Analysis
Long-term offtake agreements dominate between fermentation specialists and multinational confectionery manufacturers, insulating premium strain holders from spot-market volatility while locking in volume commitments that sustain R&D amortization. Three-tier pricing structure across pharmacy-grade, health food, and mass-market tiers reflects certification depth and stability documentation rigor. Cost compression in mass-market gummies is intensifying because ambient shelf-life limitations prevent viable count guarantees beyond eighteen months. Pharmacy buyers in Germany and Japan exhibit the least price sensitivity due to FOSHU and EFSA substantiation requirements, while supermarket procurement teams in the United States drive the hardest unit-cost negotiations.
Supply Chain Analysis
Upstream feedstock concentration in French, Danish, and Japanese fermentation facilities creates input bottlenecks during demand surges for clinically validated Lactobacillus and Bifidobacterium cultures. The probiotic confectionery supply chain draws from specialized cryoprotectant formulations, pharmaceutical-grade gelatin or pectin substrates, and precision encapsulation equipment. Single-source vulnerability in spore-forming strain supply threatens chocolate matrix manufacturers pursuing extended ambient stability. Distribution runs through cold-chain logistics for live-culture gummies, pharmacy networks for tablet formats, and direct-to-consumer subscription platforms for personalized microbiome-matched SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Probiotic confectionery sits at a high-growth inflection where microbiome personalization technology and FOSHU regulatory tightening are compressing the gap between functional food and therapeutic positioning.
For Market Incumbents: Insulate premium positioning through captive strain cultivation capacity in Japan or Switzerland, securing supply continuity when European fermentation specialists face allocation constraints. Deepen backward integration into shelf-stable spore-forming culture development to bypass ambient storage limitations that constrain supermarket distribution. Lock in pharmacy channel exclusivity via EFSA-compliant clinical databases that emerging competitors cannot replicate without multi-year trial investment. For New Entrants and Emerging Players: Direct-to-consumer microbiome testing integration in the United States represents the most penetrable entry point, bypassing retail slotting fees and enabling subscription-based recurring revenue before physical channel expansion. Plant-based vegan-adjacent gummy formats in Los Angeles and New York health food corridors offer white-space positioning underserved by dairy-centric incumbents. Lead with diagnostic-consumable bundling that matches strain recommendations to individual gut profiles, converting one-time buyers into platform-loyal subscribers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FOSHU-eligible product development, favoring acquisition of fermentation specialists with validated strain libraries over de novo R&D investment. Target vertically integrated platforms combining diagnostic services, strain cultivation, and confectionery manufacturing capabilities. Watch for Japan's post-market surveillance compliance costs triggering consolidation among mid-tier manufacturers unable to sustain lifecycle clinical databases.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Cultivation Backward Integration | Captive supply of validated cultures insulates against European fermentation specialist allocation constraints. |
| FOSHU Registration Pathway Investment | Japan's permitted functional claims create premium positioning unavailable in standard food-supplement corridors. |
| Microbiome Diagnostic Platform Acquisition | Vertical integration of testing services and consumables concentrates consumer loyalty through personalized matching. |
| Shelf-Stable Spore-Forming R&D Expansion | Chocolate matrix applications with ambient viability bypass cold-chain limitations constraining gummy distribution. |
| Pharmacy Channel Exclusivity Negotiation | Professional recommendation environments in Germany and Japan sustain margin premiums against supermarket compression. |
Research Methodology
Initial hypotheses were tested against primary input from R&D directors at fermentation specialists, regulatory affairs leads navigating EFSA and FOSHU frameworks, pharmacy category buyers in Germany and Japan, and supply chain managers overseeing cold-chain logistics. These perspectives were refined through secondary validation against FDA dietary supplement GMP guidance documents, EFSA health claims register entries, Japanese Consumer Affairs Agency FOSHU approval databases, and trade flow records from European customs authorities. Bottom-up strain-level demand modeling was cross-checked against top-down confectionery category value assessments across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across product type, end-user demographic, ingredient source, and distribution channel informing volume and value outputs throughout the forecast period. CAGRs were derived from growth-rate triangulation across segment-specific adoption curves and macro-category expansion patterns. Strain stability validation timelines, regulatory approval pathway durations, and encapsulation technology maturity curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, cold-chain logistics costs, or fermentation feedstock commodity prices would shift the trajectory. Cross-checking against Nielsen retail audit data and pharmacy channel sell-through reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Colon Cleansing Supplements Market