
 Asia-Pacific Drinkable Yogurt Market | 2026-2036
Asia-Pacific Drinkable Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drinkable Yogurt Market Outlook
Functional beverage adoption among health-conscious urban consumers is restructuring procurement patterns across the Asia-Pacific drinkable yogurt landscape. Yakult Honsha Co., Ltd. leverages its decades-long probiotic research heritage to dominate Japan's convenience store channel. China Mengniu Dairy Company Limited anchors its position through backward integration into raw milk supply across Inner Mongolia. Danone S.A. differentiates via specialized pediatric and senior nutrition formulations tailored to aging demographics in Southeast Asia.
Drinkable yogurt denotes a fermented dairy beverage with pourable viscosity, typically containing live Lactobacillus and Streptococcus thermophilus cultures at minimum viable counts, produced through controlled incubation followed by homogenization and aseptic filling. Its primary commercial purpose centers on delivering portable gut-health benefits and protein supplementation in single-serve formats. Probiotic variants command the deepest margin pools as consumers pay premiums for strain-specific efficacy claims, while fruit-flavored lines sustain volume leadership across supermarket and convenience store channels. Tetra Pak formats are displacing bottles in India's urban retail due to ambient distribution advantages and lower logistics costs.
China's SAMR enforces GB 19302 dairy fermentation standards that mandate live culture thresholds and restrict additive use in products labeled as yogurt. Japan's Consumer Affairs Agency administers FOSHU claims scrutiny, requiring clinical substantiation for digestive health and immune function marketing. Australia's FSANZ coordinates with New Zealand's MPI on trans-Tasman labeling harmonization for probiotic content declarations. Stakeholders must monitor evolving strain-specific approval pathways and cold-chain traceability mandates as regulatory divergence between Northeast and Southeast Asian markets intensifies competitive compliance costs.
Market Dynamics
Cold-chain infrastructure expansion across China's tier-one cities and India's metropolitan corridors is compressing distribution timelines for probiotic cultures, forcing manufacturers to reconfigure last-mile logistics around ambient-stable formulations and refrigerated fleet investments.
Growth Catalysts
- GB 19302 Standards:China's SAMR mandates for live culture thresholds and additive restrictions are elevating quality benchmarks, filtering out substandard producers and consolidating shelf space for compliant brands.
- FOSHU Labeling System:Japan's clinical substantiation requirements for digestive health claims create defensible premium positioning for strain-specific products in convenience store channels.
- Urban Health Consciousness:Metro consumers in Shanghai, Mumbai, and Jakarta are restructuring weekly purchase patterns around functional beverage aisles, prioritizing gut-health messaging over traditional flavor preferences.
Market Restraints
- Raw Milk Volatility:Inner Mongolia pasture conditions and Australian drought cycles create input cost swings that compress margin pools for non-integrated processors.
- Strain Approval Bottlenecks:Divergent regulatory pathways between China's NMPA and Japan's PMDA delay cross-border product launches by 18-24 months.
- Plant-Based Substitution:Oat and almond fermented beverages capture trial among lactose-intolerant segments in Southeast Asian urban markets.
Strategic Opportunities
- Tier-Two China Penetration:Chengdu, Wuhan, and Xi'an retail networks remain undersupplied with premium probiotic SKUs despite rising disposable incomes.
- Pediatric Formulation Gap:Specialized nutrition for ages 2-6 represents white space as Southeast Asian birth rates stabilize and parental health expenditure climbs.
- Ambient Distribution Convergence:Tetra Pak aseptic filling combined with extended-shelf-life cultures unlocks rural Indian kirana store access without refrigeration dependency.
Industry Challenges
- Microbiome R&D Talent Scarcity:Strain characterization and clinical trial design expertise concentrates in Tokyo, Shanghai, and Singapore, creating recruitment competition.
- Legacy System Integration:Traditional dairy cooperatives in India and Vietnam face friction digitizing cold-chain traceability for export compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drinkable Yogurt Market |
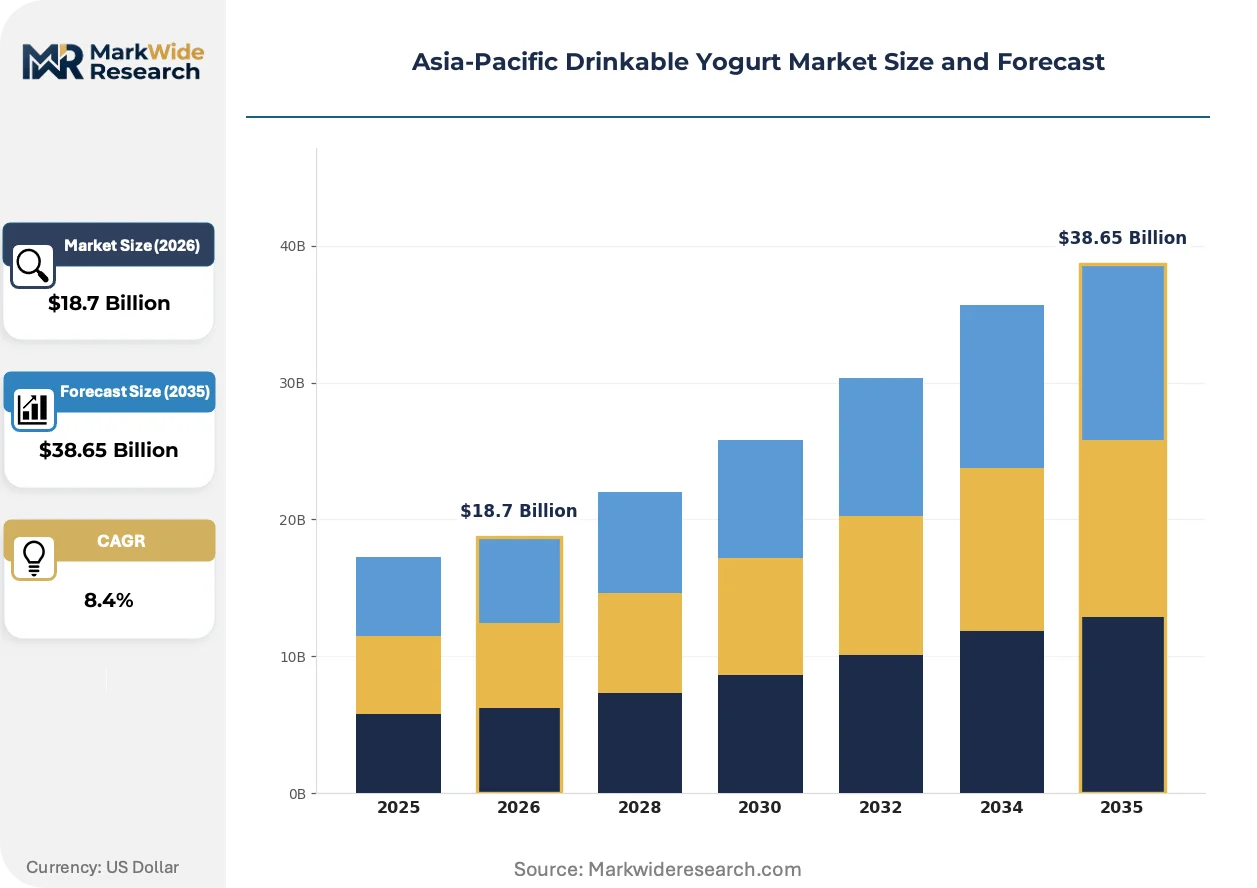
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavored, Plain, Probiotic, Organic Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores End User: Children, Adults, Seniors, Health Conscious Consumers Packaging Type: Bottles, Tetra Packs, Cups, Pouches |
| Companies Covered | Inner Mongolia Yili Industrial Group Co., Ltd., China Mengniu Dairy Company Limited, Yakult Honsha Co., Ltd., Danone S.A., Meiji Holdings Co., Ltd., Namyang Dairy Products, Nestlé, Bright Dairy & Food Co., Ltd., Epigamia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drinkable Yogurt Market Strategic Shifts
Functional beverage science is advancing beyond basic probiotic inclusion toward strain-specific efficacy demonstration and personalized nutrition targeting, compressing R&D cycles while expanding addressable consumer segments.
Extended-shelf-life probiotic stabilization technology is electrifying formulation capabilities, enabling viable Lactobacillus counts at ambient temperatures for 90+ days. Indian urban retailers are adopting these SKUs at triple-digit rates to bypass refrigeration constraints. This capability is compressing the premium gap between chilled and ambient offerings, forcing brands to differentiate on clinical substantiation rather than cold-chain exclusivity.
Australia's FSANZ coordination with New Zealand's MPI on trans-Tasman labeling harmonization is tightening probiotic content declaration standards. Manufacturers must now validate colony-forming unit counts through independent laboratory certification. Pediatric and senior nutrition lines face the steepest compliance burden as these segments trigger heightened scrutiny under ANZ food standards.
Health-conscious urban households are fragmenting their yogurt purchases across multiple channels rather than consolidating weekly supermarket trips. Convenience store single-serve formats and direct-to-subscription models are displacing traditional family-size supermarket purchases. This pattern is most visible in Tokyo and Seoul, where time-scarcity drives premium pricing for portability and portion control.
Asia-Pacific Drinkable Yogurt Market Segmentation
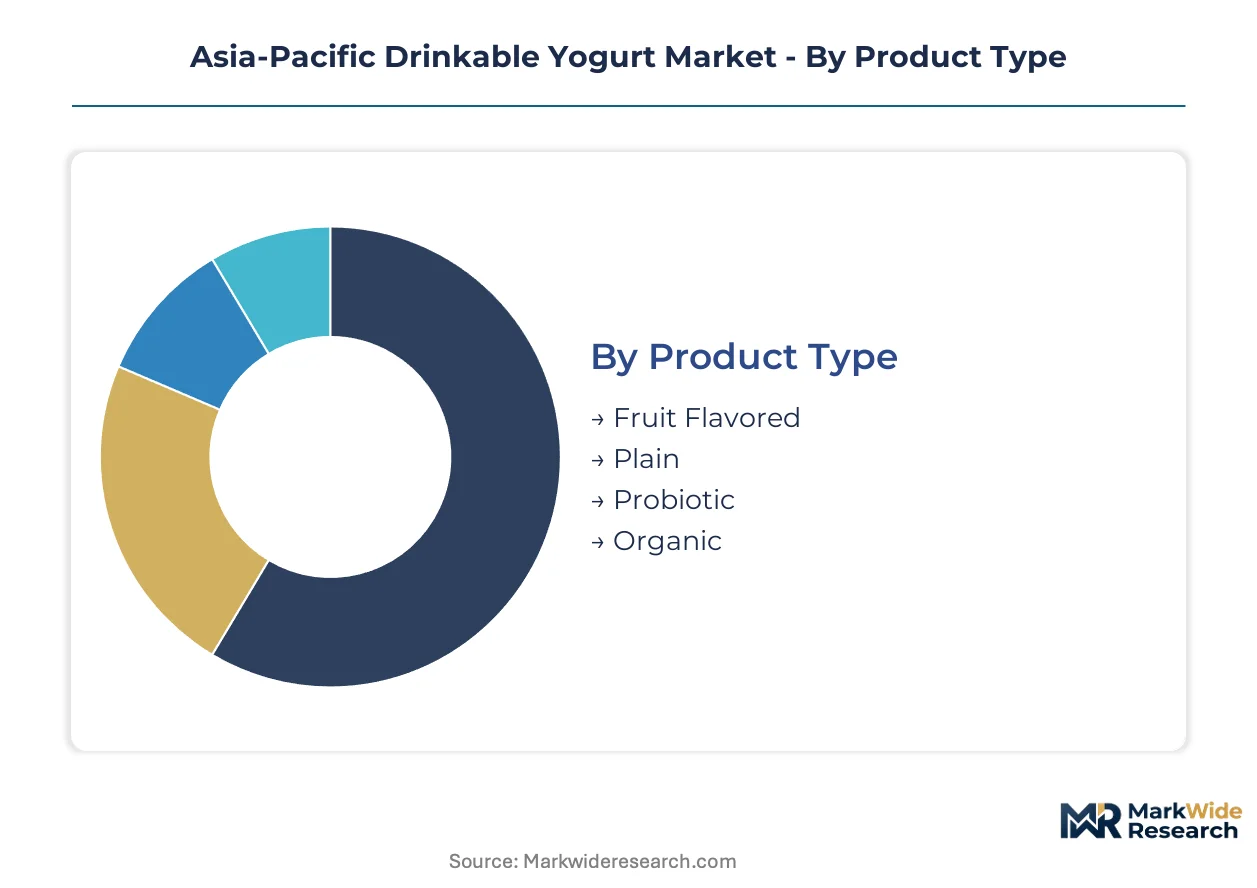
Drinkable yogurt manufacturers configure their portfolios around four distinct segmentation axes that determine margin capture and channel access. Each dimension carries different regulatory burdens, cold-chain requirements, and consumer willingness-to-pay thresholds across the Asia-Pacific region.
Product Type:
Health claims and ingredient provenance drive purchase decisions in China's tier-one cities and Japan's convenience store channels.
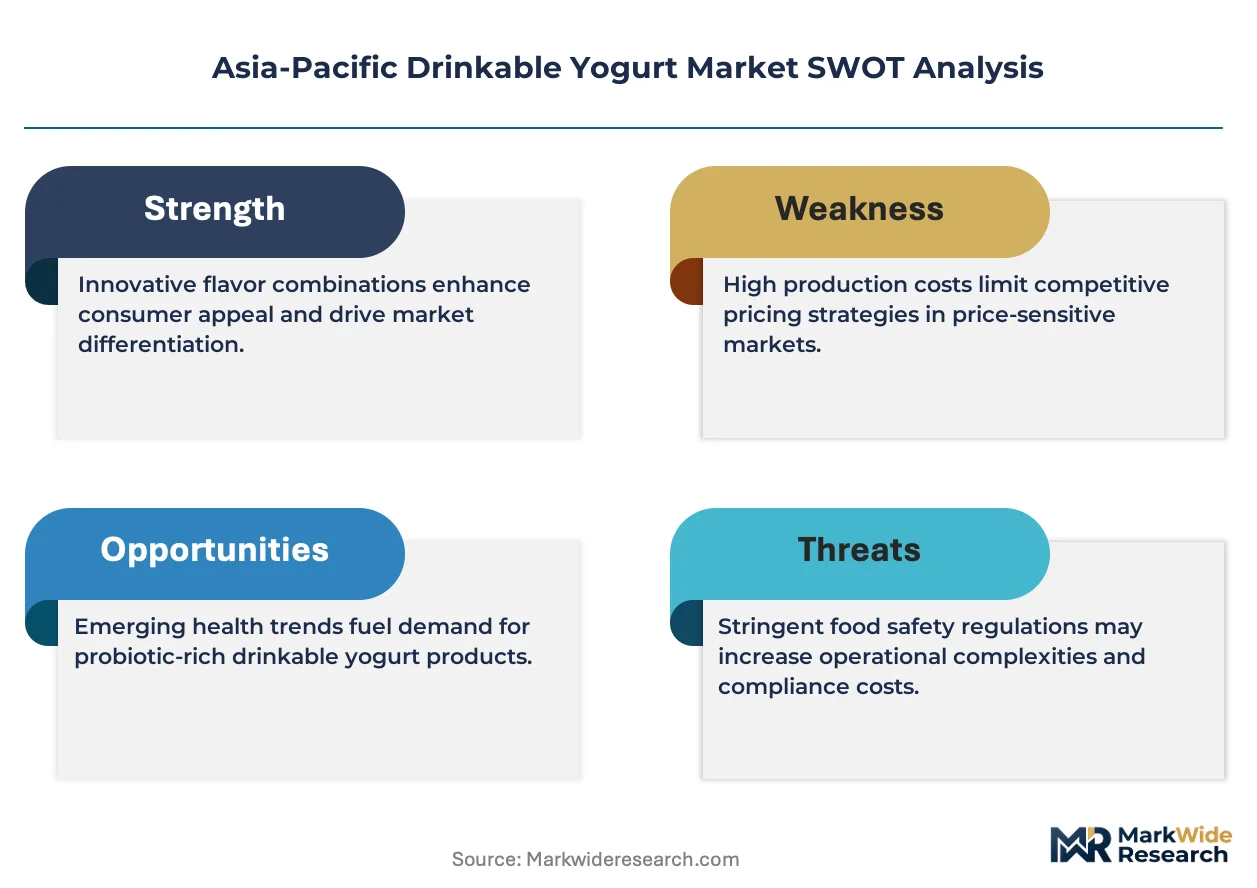
- Probiotic:Strain-specific formulations containing verified Lactobacillus and Bifidobacterium cultures at therapeutic doses command shelf space in Japanese FOSHU-compliant retail. Shanghai and Tokyo households pay premiums for clinical substantiation of digestive and immune benefits.
- Fruit Flavored:Mango, strawberry, and mixed berry variants sustain volume leadership across Indonesian and Philippine supermarket aisles where taste familiarity outweighs functional messaging. These SKUs absorb cost volatility through flexible fruit concentrate sourcing.
- Plain:Unsweetened formulations with minimal additive profiles attract diabetic and low-sugar diet adherents in Australian metropolitan markets. FSANZ labeling requirements push manufacturers toward cleaner ingredient declarations.
- Organic:Certified milk sourcing from Inner Mongolian and Victorian pasture operations targets parental segments in Seoul and Singapore concerned with antibiotic residue and hormone exposure.
Volume sits with Fruit Flavored; growth tilts toward Probiotic.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin structure for brands operating across Northeast and Southeast Asian markets.
- Convenience Stores:7-Eleven, Lawson, and FamilyMart networks in Japan and South Korea drive single-serve premium pricing through grab-and-go consumption patterns. Refrigerated display constraints favor compact bottle formats with 7-10 day turnover cycles.
- Supermarkets:Multi-pack family sizes dominate weekly purchase occasions in India's BigBasket-affiliated retail and China's Hema Fresh locations. Ambient-stable Tetra Pak variants are displacing chilled bottles in tier-two city expansion.
- Online Retail:Direct-to-subscription models through Tmall, JD.com, and Shopee capture trial-heavy urban consumers seeking strain-specific products unavailable in physical retail.
- Health Stores:Guardian, Watsons, and specialized pharmacy chains in Thailand and Malaysia stock pediatric and senior nutrition lines requiring pharmacist consultation.
Revenue concentrates in Convenience Stores; channel expansion is accelerating fastest through Online Retail.
End User:
Age-specific nutritional requirements and digestive sensitivity patterns fragment formulation strategies across the region's demographic spectrum.
- Health Conscious Consumers:Urban professionals aged 25-45 in Mumbai, Jakarta, and Bangkok prioritize gut microbiome optimization and protein supplementation over traditional dairy consumption. This segment absorbs the steepest price premiums for strain-differentiated offerings.
- Children:Calcium-fortified and reduced-sugar formulations target parental purchase decisions in Vietnam and the Philippines where stunting prevention and dental health concerns drive category entry.
- Adults:Mass-market positioning around meal replacement and digestive regularity sustains baseline volume across working-age populations in Malaysia and Taiwan.
- Seniors:Protein density and probiotic load specifications address sarcopenia and age-related gut dysbiosis in Japan's shrinking demographic and China's coastal aging belts.
Adults generate baseline volume; Health Conscious Consumers are gaining share fastest.
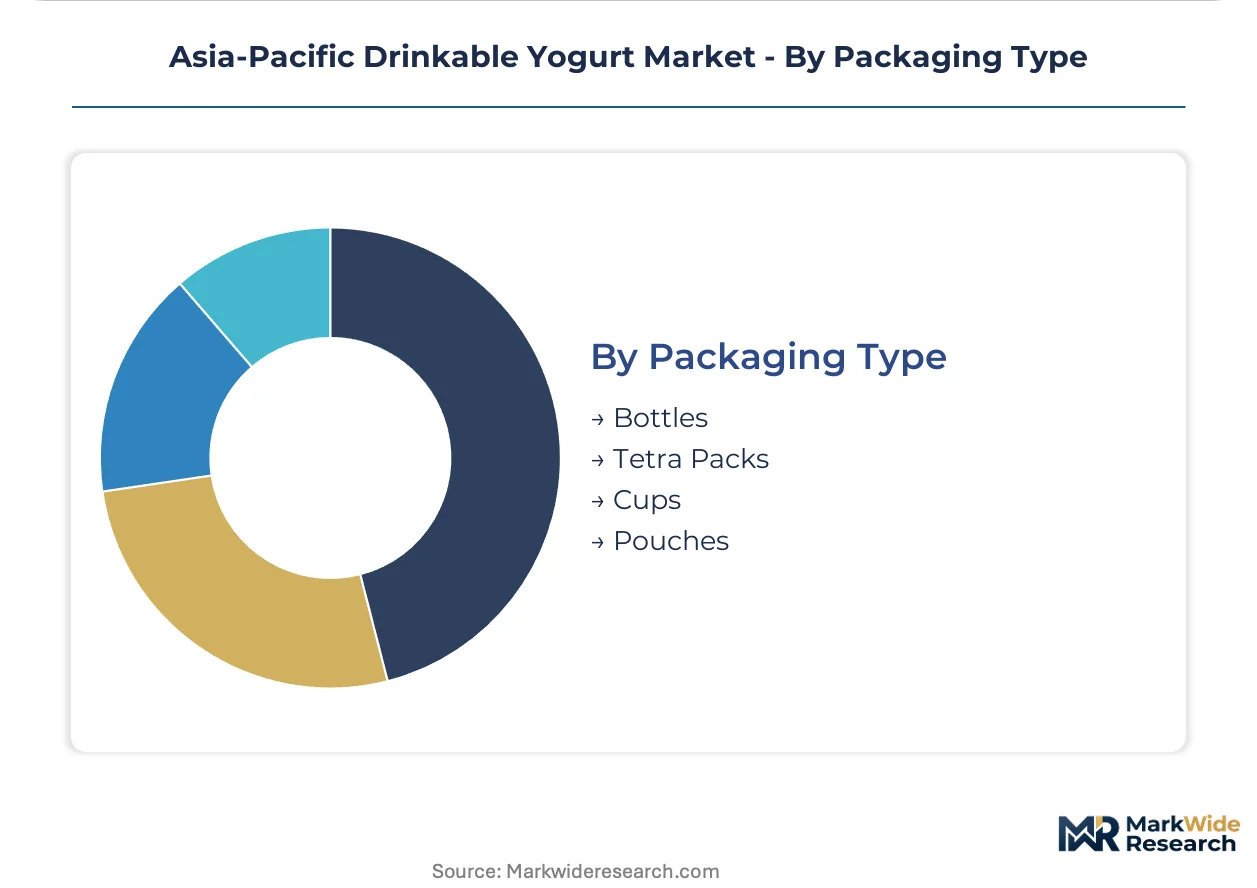
Packaging Type:
Material selection trades off shelf stability, logistics cost, and sustainability positioning against regional infrastructure constraints.
- Tetra Packs:Aseptic carton technology enables ambient distribution through India's kirana store networks and Indonesia's archipelago logistics without refrigeration dependency. Extended-shelf-life probiotic stabilization is compressing the quality gap with chilled alternatives.
- Bottles:PET and HDPE formats retain dominance in Japanese and Korean convenience channels where transparent packaging supports live culture visibility claims and premium positioning.
- Pouches:Flexible stand-up formats reduce shipping cube and damage rates for e-commerce fulfillment through Lazada and Tokopedia platforms serving scattered Indonesian and Philippine addresses.
- Cups:Spoonable-thick formulations in single-serve portions target dessert occasion substitution in Australian and New Zealand retail.
Volume sits with Bottles; Tetra Packs are climbing the fastest as ambient distribution expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port incentives and Japan's Special Zones for Structural Reform are concentrating probiotic R&D investment in coastal manufacturing clusters. Cold-chain infrastructure subsidies across metropolitan corridors are compressing distribution timelines for live-culture products.
China
Health-conscious households in Shanghai and Beijing are restructuring weekly purchases around functional beverage aisles. SAMR's GB 19302 standards mandate live culture thresholds that filter substandard producers from tier-one retail. Inner Mongolian pasture operations anchor raw milk supply for integrated processors serving northern urban corridors.
Japan
Time-scarcity drives premium pricing for single-serve formats across Tokyo and Osaka convenience networks. The Consumer Affairs Agency's FOSHU system requires clinical substantiation for digestive health claims, creating defensible positioning for strain-specific entrants. Kanto region manufacturing clusters concentrate aseptic filling capacity for export-grade production.
India
Metropolitan consumers in Mumbai and Delhi-NCR are trialing extended-shelf-life probiotic SKUs at triple-digit rates. FSSAI dairy safety protocols are tightening additive restrictions and labeling requirements for fermented beverages. Gujarat and Maharashtra dairy cooperatives face friction digitizing cold-chain traceability for premium segment compliance.
South Korea
Seoul Capital Area households fragment yogurt purchases across convenience stores and direct-to-subscription channels. MFDS regulates functional food claims with strain-specific approval pathways that delay cross-border launches. Busan-Ulsan logistics hubs enable refrigerated distribution to secondary cities with rising disposable incomes.
Australia
FSANZ labeling harmonization with New Zealand's MPI tightens probiotic count declaration standards requiring independent laboratory certification. Melbourne and Sydney health stores drive demand for pediatric and senior nutrition lines. Victorian pasture operations supply certified organic milk targeting parental segments concerned with residue exposure.
Asia-Pacific Drinkable Yogurt Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated dairy conglomerates commanding shelf space in regulated Northeast Asian markets while regional cooperatives retain volume leadership in Southeast Asian traditional trade. The competitive structure tilts toward scale-driven consolidation in China and Japan, contrasting with fragmentation across Indonesian and Philippine archipelago logistics. Three archetypes dominate: backward-integrated raw milk processors, strain-specialized probiotic research houses, and ambient-stable formulation innovators. Capacity expansion and clinical substantiation investments constitute the dominant competitive moves, as cold-chain infrastructure gaps force portfolio reconfiguration around shelf-stable alternatives.
Among Northeast Asian integrated processors, Inner Mongolia Yili Industrial Group Co., Ltd. and China Mengniu Dairy Company Limited exemplify the backward-integrated archetype with captive pasture-to-plant supply control. Yakult Honsha Co., Ltd. occupies a distinctive position as a strain-specialized research house with decades-long probiotic heritage. These three entities anchor the premium tier where clinical substantiation and regulatory compliance create defensible positioning against contract-manufactured alternatives.
| Leading Market Players |
|---|
| Inner Mongolia Yili Industrial Group Co., Ltd. |
| China Mengniu Dairy Company Limited |
| Yakult Honsha Co., Ltd. |
| Danone S.A. |
| Meiji Holdings Co., Ltd. |
| Namyang Dairy Products |
| Nestlé |
| Bright Dairy & Food Co., Ltd. |
| Epigamia |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals and Inner Mongolian grassland restoration mandates gate qualified raw milk supply for premium-tier pricing access. Processors without certified pasture partnerships face exclusion from tier-one retail channels where FOSHU-equivalent positioning commands shelf space.
Pricing Analysis
Lead-time-driven pricing stratifies across refrigerated versus ambient-stable tiers, with convenience store single-serve formats absorbing premiums for sub-48-hour cold-chain delivery. Three-tier pricing structure across FOSHU-substantiated, standard probiotic, and economy fruit-flavored levels reflects certification grade and strain specificity. Pricing pressure stems from Australian drought cycles and Inner Mongolian pasture volatility compressing margin pools for non-integrated processors. Health-conscious urban households in Tokyo and Shanghai exhibit lowest price sensitivity, while Southeast Asian traditional trade buyers prioritize volume discounts over functional claims.
Supply Chain Analysis
Single-source vulnerability sits with Australian and New Zealand pasture operations supplying certified organic milk to premium pediatric and senior nutrition lines. Raw material dependencies center on Lactobacillus strain cultures from Japanese and Danish culture houses, fruit concentrates from Thai and Philippine processors, and aseptic carton substrates from Swedish and Finnish packaging technology providers. Tariff exposure runs through trans-Tasman dairy trade protocols affecting probiotic count declaration harmonization. Distribution runs through refrigerated fleet networks in Japan and South Korea, ambient-stable Tetra Pak logistics in India and Indonesia, and direct-to-subscription cold-chain fulfillment in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific drinkable yogurt market is transitioning from chilled probiotic dependence toward ambient-stable extended-shelf-life technology, replacing legacy cold-chain infrastructure requirements with formulation-driven shelf stability.
For Market Incumbents: Lock in backward integration into Inner Mongolian and Victorian pasture operations to secure qualified supply under tightening carbon and grassland restoration mandates. Invest in extended-shelf-life culture stabilization R&D to preempt ambient distribution competitors. Control convenience store refrigerated display slots in Tokyo and Seoul against direct-to-subscription challengers.
For New Entrants and Emerging Players: Rural Indian kirana store operators represent an underserved buyer archetype with rising disposable incomes and minimal premium probiotic penetration. Target tier-two Chinese cities—Chengdu, Wuhan, Xi'an—with ambient-stable Tetra Pak SKUs bypassing refrigerated logistics requirements. Launch through Tmall and JD.com direct-to-subscription models to capture trial-heavy urban consumers seeking strain-specific products absent from physical retail.
For Investors and Strategic Acquirers: Strain-specific FOSHU approvals in Japan's Consumer Affairs Agency is the leading indicator that clinical substantiation capabilities are consolidating competitive moats around research-intensive processors. The five-to-ten-year viability window favors acquisition targets with captive culture libraries and ambient stabilization patents over pure-play distribution assets. Watch for extended-shelf-life probiotic launches achieving triple-digit adoption rates in Indian metropolitan corridors as the signal that refrigeration-independent distribution is crossing the quality perception threshold.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Shelf-Life Culture Stabilization | Ambient probiotic viability for 90+ days unlocks India's kirana store distribution without refrigeration dependency. |
| FOSHU Clinical Substantiation Investment | Japan's Consumer Affairs Agency approval creates defensible premium positioning in convenience store channels. |
| Backward Pasture Integration | Inner Mongolian and Victorian certified organic supply secures qualified raw milk access under tightening environmental mandates. |
| Direct-to-Subscription Channel Launch | Tmall and JD.com subscription models capture trial-heavy urban consumers seeking strain-specific formulations unavailable offline. |
| Pediatric Formulation Development | Specialized nutrition for ages 2-6 addresses white space as Southeast Asian parental health expenditure climbs. |
Study Parameters
Document review covered FSSAI dairy safety protocols, SAMR GB 19302 standards filings, FSANZ-MPI labeling harmonization guidelines, and Tetra Pak aseptic technology disclosures, complemented by interviews with brand managers at integrated dairy processors, category buyers at 7-Eleven and Lawson convenience networks, cold-chain logistics planners at Indian dairy cooperatives, and regulatory affairs specialists navigating FOSHU approval pathways. Secondary validation drew from Nielsen retail audit data, customs records of probiotic culture imports, and SEC filings of publicly traded dairy conglomerates. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates.
Market sizing and growth projections were developed across the analysis window using a segmented analytical framework incorporating product type stratification, distribution channel intensity, end-user age cohorts, and packaging format logistics requirements. CAGRs were derived from regression analysis of historical consumption patterns against cold-chain infrastructure investment trajectories, urban disposable income trends, and regulatory approval timelines for strain-specific health claims. Forecast inputs included ambient stabilization technology adoption curves, convenience store refrigerated display expansion rates, and direct-to-subscription penetration in Chinese tier-one cities.
Revisions become necessary when Australian pasture conditions trigger sustained raw milk cost volatility, when Japan's PMDA or China's NMPA alter strain approval pathways, or when plant-based fermented beverages accelerate substitution beyond current trial rates. Forecasts reflect documented assumptions about cold-chain infrastructure buildout timelines and consumer willingness-to-pay for clinical substantiation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Multistrain Probiotics Market