
 Brewer Yeast Powder Market | 2026-2036
Brewer Yeast Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Brewer Yeast Powder Market Outlook
Plant-based protein isolates is restructuring cost structures across the brewer yeast powder value chain as formulators blend yeast-derived fractions with pea and soy concentrates to hit amino acid targets at lower input cost. Lesaffre Group leverages its fermentation infrastructure across Europe to secure consistent feedstock supply. Angel Yeast Co., Ltd. anchors production scale in Asia through integrated brewing partnerships. Lallemand Inc. competes on strain development capabilities for specialized nutritional applications.
Brewer yeast powder consists of dried, inactive Saccharomyces cerevisiae cells harvested from beer fermentation, typically containing 40-50% protein by weight along with B-complex vitamins, minerals, and beta-glucans, produced through washing, pasteurization, and roller-drum or spray-drying processes. The powder serves primarily as a cost-effective protein and micronutrient fortifier in human food, animal nutrition, and fermentation media. Nutritional yeast within the product type category captures premium positioning as clean-label demand from dietary supplement brands intensifies. The animal feed end user segment sustains volume leadership, though dietary supplements represents the fastest-expanding margin pool as pet humanization trends accelerate.
FDA GRAS status and USDA organic certification govern human-food applications in the United States, while EFSA novel food evaluations shape market access for new yeast-derived ingredients across European markets. The EU Green Deal's circular economy mandates are pushing brewers to formalize byproduct recovery partnerships with yeast processors rather than treating spent yeast as waste. Stakeholders must monitor how tightening energy regulations around thermal drying processes will reshape cost structures for powder production.
Market Dynamics
The EU F-Gas Regulation is compressing drying technology choices across brewer yeast powder production, forcing capital reallocation toward lower-emission thermal processes while tightening supply-side cost structures.
Growth Catalysts
- Pet humanization trajectory:Pet food manufacturers are expanding brewer yeast powder inclusion rates for palatability enhancement and B-vitamin fortification in premium companion animal diets.
- Circular economy mandates:The EU Green Deal is formalizing byproduct recovery partnerships between brewers and yeast processors, converting spent yeast from waste stream to secured feedstock.
- Protein fraction blending:Formulators are combining yeast-derived fractions with pea and soy concentrates to achieve amino acid targets at reduced input cost.
Market Restraints
- Thermal drying energy intensity:Roller-drum and spray-drying processes consume substantial natural gas volumes, exposing processors to input cost volatility under tightening carbon pricing regimes.
- Feedstock geographic concentration:Brewing byproduct recovery networks concentrate in Germany, creating supply vulnerability for processors lacking diversified sourcing.
- Plant-based protein substitution:Isolated soy and pea proteins compete directly with brewer yeast powder on cost-per-protein-unit in animal nutrition applications.
Strategic Opportunities
- Dietary supplement white space:Clean-label demand from supplement brands is elevating nutritional yeast to premium positioning with expanded margin capture.
- Lower-emission drying technology:Heat pump and mechanical vapor recompression systems offer compliance pathways under the EU F-Gas Regulation while reducing operational carbon intensity.
- Integrated brewing partnerships:Direct offtake agreements with multi-site brewing groups are securing volume commitments and quality standardization.
Industry Challenges
- Specialized fermentation expertise scarcity:Strain development and process optimization for nutritional applications require rare skill sets in industrial microbiology.
- Certification timeline compression:EFSA novel food evaluations for new yeast-derived ingredients extend market access timelines, delaying revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewer Yeast Powder Market |
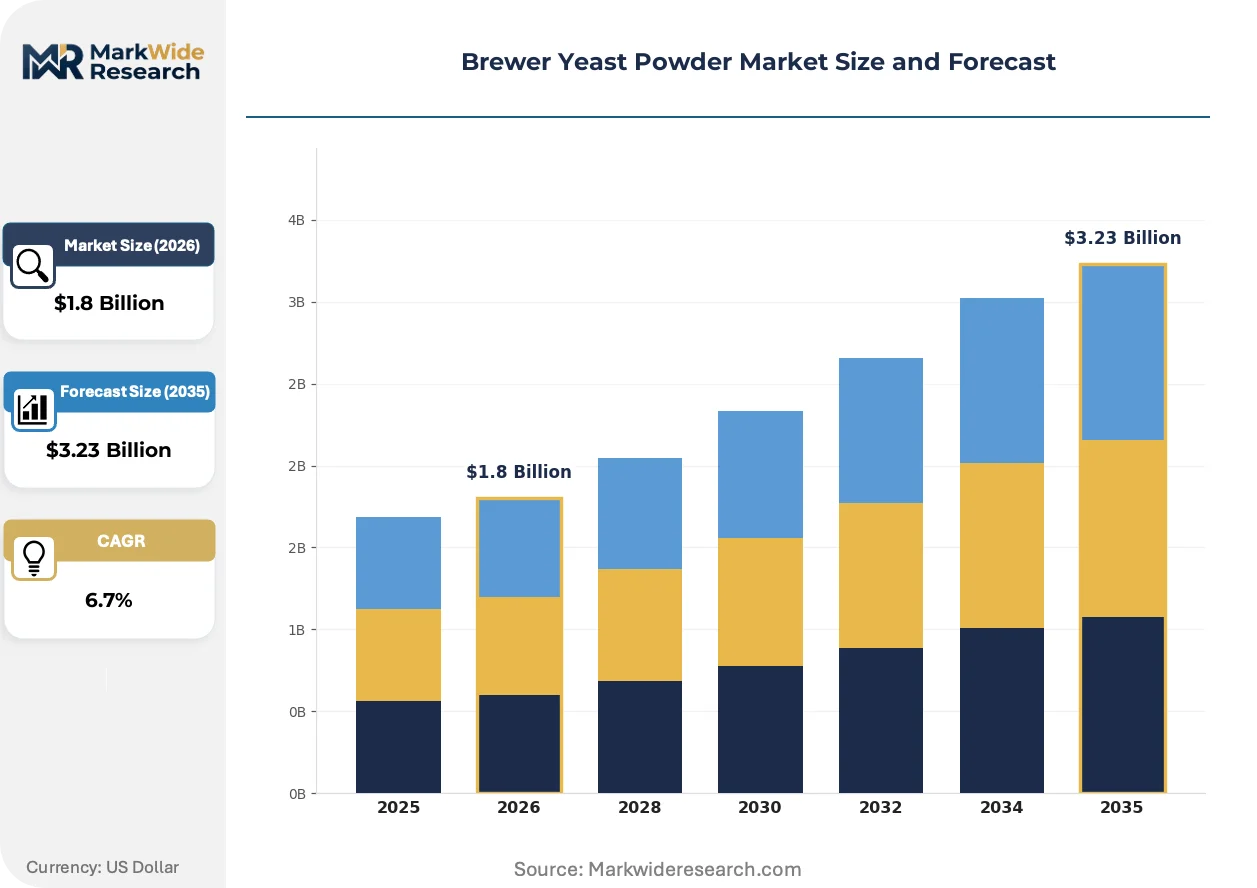
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Brewer Yeast, Active Dry Yeast, Nutritional Yeast, Liquid Yeast End User: Food Industry, Dietary Supplements, Animal Feed, Pharmaceuticals Form: Powder, Granules, Flakes, Tablets Application: Baking, Fermentation, Nutritional Enhancement, Brewing |
| Companies Covered | Lesaffre Group, Angel Yeast Co., Ltd., Lallemand Inc., Archer Daniels Midland Company, Alltech Inc., Associated British Foods plc, Leiber GmbH, Kerry Group, Ohly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewer Yeast Powder Market Strategic Shifts
Processing technology, regulatory compliance architecture, and procurement patterns are converging to reshape competitive positioning across the brewer yeast powder value chain.
Spray-drying technology is decentralizing production economics by enabling smaller-scale, distributed processing facilities co-located with regional brewing clusters. Mid-size processors in Belgium and the Netherlands are adopting modular spray-dryer configurations to reduce feedstock transport costs. This geographic diffusion is compressing the historical concentration of powder production near large-scale brewing centers.
The EU F-Gas Regulation is mandating phasedown of hydrofluorocarbon-based refrigeration in thermal drying systems, compelling equipment retrofits or replacement. Processors are responding with capital commitments to alternative drying technologies ahead of enforcement deadlines. Nutritional yeast production lines face the steepest compliance burden given their temperature sensitivity and quality requirements.
Direct contracting between yeast processors and pet food manufacturers is displacing traditional ingredient distributor channels for high-volume accounts. Large pet food groups in the United States are establishing specifications-grade partnerships with processors, unbundling technical service from commodity supply. This channel compression is most visible in the premium companion animal segment where traceability and certification documentation carry contract value.
Brewer Yeast Powder Market Segmentation
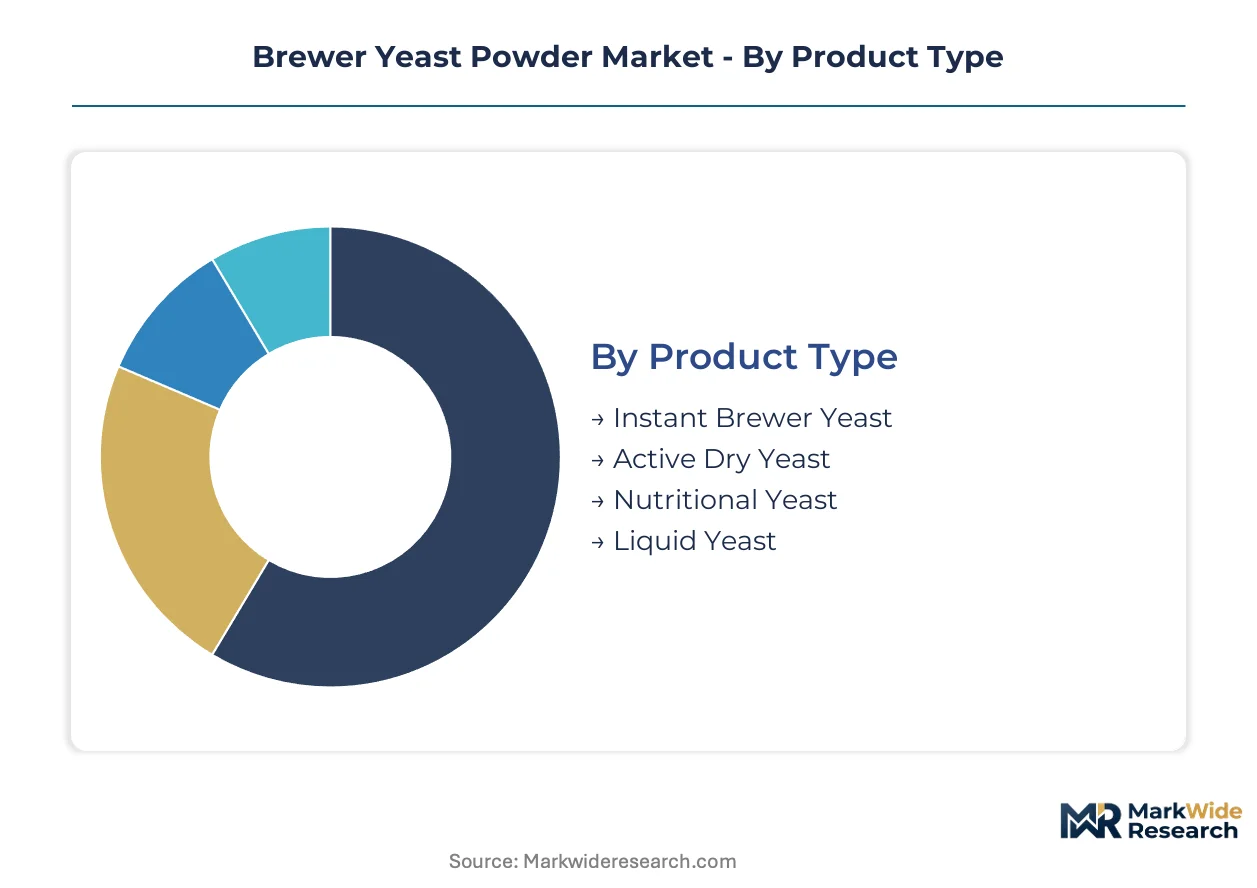
Segmentation in brewer yeast powder markets reveals how processing technology, specification intensity, and end-use certification requirements partition value capture. Product type and end user dimensions dominate strategic resource allocation decisions for processors and formulators alike.
Product Type:
Drying technology and cell viability specifications differentiate product categories across the value chain, with thermal process choices directly governing protein preservation and shelf stability outcomes.
- Instant Brewer Yeast:Rapid-rehydration formulations produced through fluidized-bed drying achieve 95%+ cell viability within 5 minutes of water contact. Pet food manufacturers in Germany favor instant formats for wet-mix applications where dispersion speed reduces production cycle times.
- Nutritional Yeast:Inactive Saccharomyces cerevisiae with enhanced B-vitamin profiles, typically fortified with additional B12 through controlled fermentation. Clean-label supplement brands in the United States command premium positioning through USDA organic certification and non-GMO verification.
- Active Dry Yeast:Vacuum-packed viable cells with 12-24 month stability, requiring reactivation protocols before use.
- Liquid Yeast:Slurry formats with 15-20% solids content, constrained by cold-chain requirements and 14-day shelf life.
Instant brewer yeast leads on scale; nutritional yeast leads on momentum.
End User:
Application-driven specification tiers separate commodity protein supply from certified nutritional ingredient markets, with regulatory complexity and margin structure diverging sharply across customer categories.
- Animal Feed:Standardized protein specifications at 40-45% crude protein with minimal processing overhead serve volume-driven compound feed operations. Poultry and swine integrators in the Netherlands negotiate annual contracts tied to soybean meal price indices.
- Dietary Supplements:β-glucan standardized extracts and mineral-chelated formats command formulation premiums. EFSA novel food evaluations and FDA GRAS self-affirmation pathways create compliance moats that specialist processors exploit.
- Food Industry:Bakeries and savory flavor houses utilize debittered powders for umami enhancement and dough conditioning.
- Pharmaceuticals:GMP-compliant production lines with endotoxin testing and pharmacopeial monograph alignment serve fermentation media and API precursor applications.
Animal feed dominates volume throughput; dietary supplements delivers steepest margin expansion.
Form:
Physical presentation formats align with handling automation, dissolution kinetics, and dosage precision requirements across manufacturing contexts.
- Powder:Free-flowing particles below 250 microns enable pneumatic conveying and homogeneous blending in extrusion systems.
- Granules:Agglomerated structures between 500-2000 microns reduce dust generation and improve flowability in high-speed packaging lines.
- Flakes:Rolled and toasted formats with enhanced surface area for rapid hydration in soup and sauce applications.
- Tablets:Compressed dosages with disintegrant binders serving direct-to-consumer supplement channels.
Powder commands production scale; tablets concentrate value per kilogram.
Application:
Functional performance requirements and regulatory exposure vary substantially across use-case categories, shaping processor specialization and customer stickiness.
- Nutritional Enhancement:B-vitamin fortification and protein supplementation in plant-based meat alternatives and sports nutrition. Formulators blend yeast fractions with pea isolates to hit PDCAAS targets while masking off-flavors.
- Fermentation:High-purity yeast extracts and autolysates serve as nitrogen sources in antibiotic and enzyme production. Biopharma contract manufacturers audit suppliers against USP <1116> microbial limits.
- Baking:Reducing sugars and glutathione-rich fractions improve dough extensibility and crust color development.
- Brewing:Recycled yeast slurry for pitch propagation in craft brewery operations with variable quality tolerance.
Nutritional enhancement scales with alternative protein demand; fermentation locks in technical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brewing byproduct recovery networks anchor continental supply chains for brewer yeast powder processors, with spent yeast collection infrastructure concentrated around Munich and Hamburg metropolitan clusters.
United States
Pet food manufacturers in Kansas and Iowa drive demand for palatability-enhancing yeast fractions in premium companion animal formulations. FDA GRAS self-affirmation pathways govern human-food applications, creating compliance differentiation between feed-grade and food-grade processors. Chicago-area ingredient distributors are consolidating procurement relationships with direct processor contracting.
Germany
Brewing conglomerates in Bavaria and North Rhine-Westphalia operate formalized spent yeast recovery partnerships with specialty processors. The EU F-Gas Regulation mandates equipment retrofits for thermal drying systems ahead of hydrofluorocarbon phase-down deadlines. Hamburg port logistics clusters facilitate export-oriented powder consolidation for Asian markets.
China
Angel Yeast Co., Ltd. anchors production scale through integrated brewing partnerships across Shandong and Guangdong provinces. SAMR food safety standards and GB quality certifications shape import substitution dynamics for domestic nutritional yeast capacity. Yangtze River Delta brewing clusters are expanding byproduct valorization infrastructure.
Belgium
Mid-size processors in Flanders are deploying modular spray-dryer configurations co-located with regional craft brewing networks. EFSA novel food evaluation timelines extend market access for β-glucan standardized extracts destined for supplement applications. Leuven biotechnology corridors concentrate strain development expertise for specialized nutritional formats.
Netherlands
Poultry and swine integrators in Gelderland negotiate annual supply contracts indexed to soybean meal price benchmarks. The EU Green Deal circular economy mandates are accelerating formal byproduct recovery agreements between Heineken-affiliated brewers and yeast processors. Rotterdam logistics hubs enable just-in-time powder delivery to compound feed operations.
Brewer Yeast Powder Market Competitive Environment
Global majors compete with regional champions across fermentation infrastructure and strain development capabilities, producing a tiered structure where scale-driven players coexist with specialized nutrition specialists. Market concentration reflects backward integration advantages in brewing byproduct access and captive supply of spent yeast feedstock. Three archetypes dominate: integrated fermentation conglomerates with multi-site brewing partnerships, specialist yeast processors focused on nutritional applications, and diversified ingredient houses with broad distribution reach. Capacity expansion and direct contracting with pet food manufacturers represent the dominant competitive vectors reshaping channel relationships.
Within the integrated fermentation tier, Lesaffre Group exemplifies European-scale infrastructure deployment, while Angel Yeast Co., Ltd. occupies a position as Asia-Pacific production anchor. Lallemand Inc. represents the specialist archetype with concentrated expertise in strain development for nutritional applications. These three entities collectively illustrate how geographic origin and organizational structure map onto competitive positioning across human food, animal nutrition, and supplement market segments.
| Leading Market Players |
|---|
| Lesaffre Group |
| Angel Yeast Co., Ltd. |
| Lallemand Inc. |
| Archer Daniels Midland Company |
| Alltech Inc. |
| Associated British Foods plc |
| Leiber GmbH |
| Kerry Group |
| Ohly |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between feed-grade commodity powder and EFSA-evaluated nutritional yeast creates parallel pricing architectures that track divergent supply chain investments. Premium tiers demand segregated production lines, specialized strain development, and pharmacopeial documentation that commodity processors bypass entirely.
Pricing Analysis
Natural gas pass-through costs dominate input-cost volatility for thermal drying operations, compressing margins on standard-grade powder while nutritional yeast commands fixed-price premiums through B-vitamin fortification contracts. Three-tier pricing structure across premium, standard, and economy levels separates GMP-compliant pharmaceutical supply from feed-grade bulk contracts. Pricing pressure stems from soybean meal substitution in compound feed applications, where amino acid cost-per-unit comparisons erode brewer yeast competitiveness. Poultry and swine integrators exhibit highest price sensitivity, while dietary supplement brands absorb premiums for clean-label certification.
Supply Chain Analysis
Direct-to-pet-food-manufacturer channels handle hyperscale buyer demand, displacing traditional ingredient distributors for volume accounts with traceability requirements. Supply concentrates in Germany, China, and Belgium, where brewing byproduct recovery infrastructure feeds regional processing clusters. Raw material dependencies center on spent yeast slurry, natural gas for thermal drying, and specialized refrigeration equipment for nutritional yeast lines. Single-source vulnerability runs through German brewing conglomerates that dominate continental feedstock availability. Distribution runs through Rotterdam and Hamburg logistics hubs for Asian export consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in brewer yeast powder hinges on clean-label premium capture and energy-cost compression through heat pump retrofits, rewarding processors who front-run EU F-Gas compliance deadlines.
For Market Incumbents: Cement backward integration into multi-site brewing partnerships to lock in feedstock security against German supply concentration risk. Expand heat pump and mechanical vapor recompression capacity ahead of hydrofluorocarbon phase-down enforcement. Prioritize EFSA novel food dossier investment for β-glucan standardized extracts to defend premium positioning against plant-protein substitution. For New Entrants and Emerging Players: Enter via modular spray-dryer deployments co-located with regional craft brewing clusters in Belgium and the Netherlands, exploiting geographic diffusion away from Munich-Hamburg supply dominance. Target pet food palatability applications where direct contracting opportunities bypass entrenched distributor relationships. Lead with USDA organic certification and non-GMO verification to capture clean-label supplement white space. For Investors and Strategic Acquirers: Consolidation pressure builds where strain development expertise scarcity meets fragmented mid-scale processing capacity across European markets. Position acquisition targets as specialist yeast processors with EFSA evaluation track records and captive brewing partnerships, viable over extended holding periods through protein diversification demand. Watch SAMR import substitution signals in China as inflection indicator for regional capacity buildout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brewing Partnerships | Secures spent yeast feedstock against German supply concentration and quality variability. |
| Heat Pump Drying Technology Deployment | Delivers EU F-Gas compliance while reducing natural gas exposure under carbon pricing regimes. |
| EFSA Novel Food Dossier Investment | Creates regulatory moats for β-glucan extracts targeting supplement premium tiers. |
| Direct-to-Pet-Food Contracting | Bypasses distributor margin capture in palatability-enhancement applications with traceability requirements. |
| USDA Organic Certification Program | Unlocks clean-label premium positioning in United States dietary supplement channels. |
Study Parameters
Direct dialogue with yeast processing plant managers, pet food manufacturer procurement leads, brewing industry byproduct recovery specialists, and EFSA regulatory affairs consultants grounded qualitative findings in operational reality. Secondary validation drew from EU F-Gas Regulation implementation guidance, SAMR food safety standards documentation, USDA organic certification databases, and brewing industry sustainability reports. Bottom-up feedstock flow modeling and top-down protein ingredient demand estimation were triangulated against trade flow data through Rotterdam and Hamburg port authorities.
Bottom-up volume builds aggregated country-level production capacity, utilization rates, and end-use consumption patterns across animal feed, dietary supplements, food industry, and pharmaceutical applications. Segmentation dimensions included product type, end user category, physical form, and functional application, with CAGRs derived from regression analysis against protein ingredient substitution elasticities and pet humanization trend indices. Forecast inputs incorporated EU Green Deal circular economy mandate implementation timelines and thermal drying technology adoption curves.
The model holds under stable natural gas pricing and sustained EU F-Gas enforcement; deviation in carbon border adjustment mechanisms or abrupt plant-protein cost breakthroughs would shift volume trajectories materially. Forecasts reflect documented assumptions regarding brewing byproduct recovery partnership formalization rates. Periodic stress-testing of base assumptions is recommended against SAMR regulatory acceleration and heat pump technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
ASEAN Probiotic Supplements Market