
 Global Probiotic Based Dietary Supplements Market | 2026-2036
Global Probiotic Based Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Probiotic Based Dietary Supplements Market Outlook
Clinical-grade strain verification is unwinding competitive dynamics across the probiotic supplements landscape. Novonesis Group leverages its fermentation science heritage to sustain leadership in specialized bacterial cultures. Danone anchors its position through extensive dairy-linked probiotic distribution networks. BioGaia AB differentiates by dominating pediatric and oral health probiotic niches with documented clinical strains.
Probiotic based dietary supplements contain live microorganisms, typically Lactobacillus and Bifidobacterium species at minimum viable counts of 10^6 to 10^11 CFU per serving, formulated to confer digestive, immune, or targeted physiological benefits when consumed in adequate quantities. Capsules command the largest share of product type revenue due to stability advantages and precise dosing, while gummies represent the fastest-expanding format as palatability drives compliance among children and reluctant adult users. Online retail channels capture expanding margin pools by bypassing traditional pharmacy markups and enabling direct-to-consumer subscription models.
FDA oversight of dietary supplement Good Manufacturing Practices and EFSA health claim authorization requirements shape product development trajectories and market access conditions across North America and Europe. India's FSSAI and China's SAMR impose additional strain registration and safety documentation mandates that filter out undercapitalized entrants. Stakeholders must monitor evolving live-cell count standardization efforts and jurisdiction-specific stability testing protocols to maintain compliant supply chains.
Market Dynamics
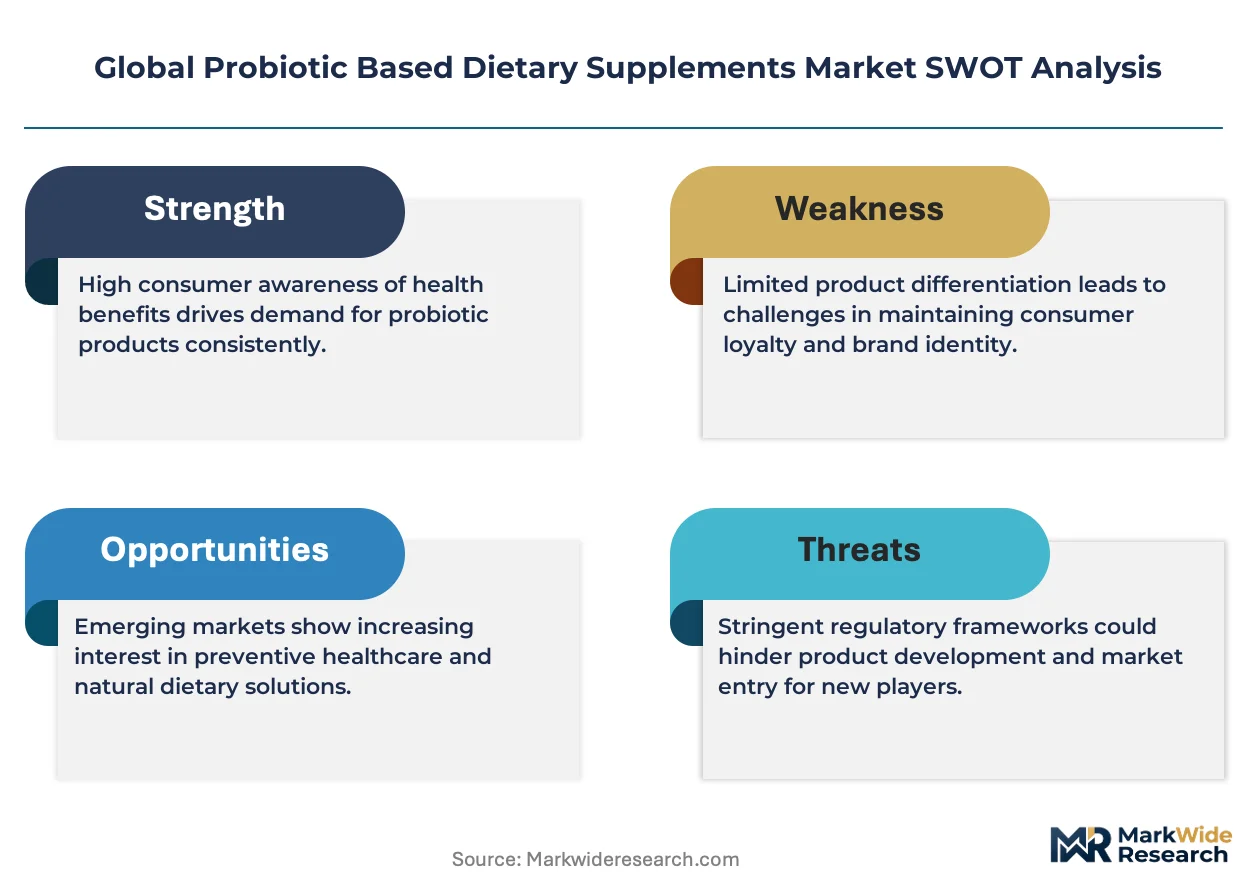
Strain-specific labeling mandates from EFSA and FDA are compressing formulation flexibility while elevating capital requirements for viable market entry. These regulatory pressures reward incumbents with established clinical documentation libraries and certified manufacturing infrastructure.
Growth Catalysts
- Digestive wellness prioritization:Adults in the United States, Germany, and China are expanding daily supplementation routines to include multi-strain probiotics with documented CFU counts at consumption.
- SAMR registration pathways:China's streamlined strain approval processes for documented probiotic species are accelerating product launches for compliant foreign manufacturers.
- Capsule stability advances:Enteric coating technologies and moisture-barrier packaging are extending shelf-life claims and reducing cold-chain dependency for retail distribution.
Market Restraints
- Live culture input volatility:Fermentation-grade glucose and yeast extract prices fluctuate with agricultural commodity cycles, squeezing margin predictability for bulk culture suppliers.
- EFSA health claim authorization backlog:The European regulator's stringent probiotic-specific claim requirements create multi-year approval timelines that freeze marketing messaging for new entrants.
- Plant-based dairy substitution:Oat and almond milk alternatives with added live cultures are capturing functional beverage demand that previously flowed to dedicated supplement formats.
Strategic Opportunities
- India's FSSAI strain registry gaps:Underpenetrated probiotic awareness in tier-2 and tier-3 Indian cities offers first-mover positioning for clinically documented pediatric and geriatric formulations.
- Subscription direct-to-consumer channels:Automated replenishment models bypass pharmacy markups and capture recurring revenue with higher lifetime value metrics than retail.
- Metabolic health applications:Emerging research linking specific Bifidobacterium strains to glucose regulation is opening prescription-adjacent positioning in prediabetes management protocols.
Industry Challenges
- CFU enumeration standardization:Inconsistent viability testing methodologies across ISO, FDA, and AOAC frameworks create compliance friction for multi-jurisdiction product lines.
- Strain banking and IP fragmentation:Proprietary culture deposits and patent thickets around specific Lactobacillus isolates complicate formulation freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Probiotic Based Dietary Supplements Market |
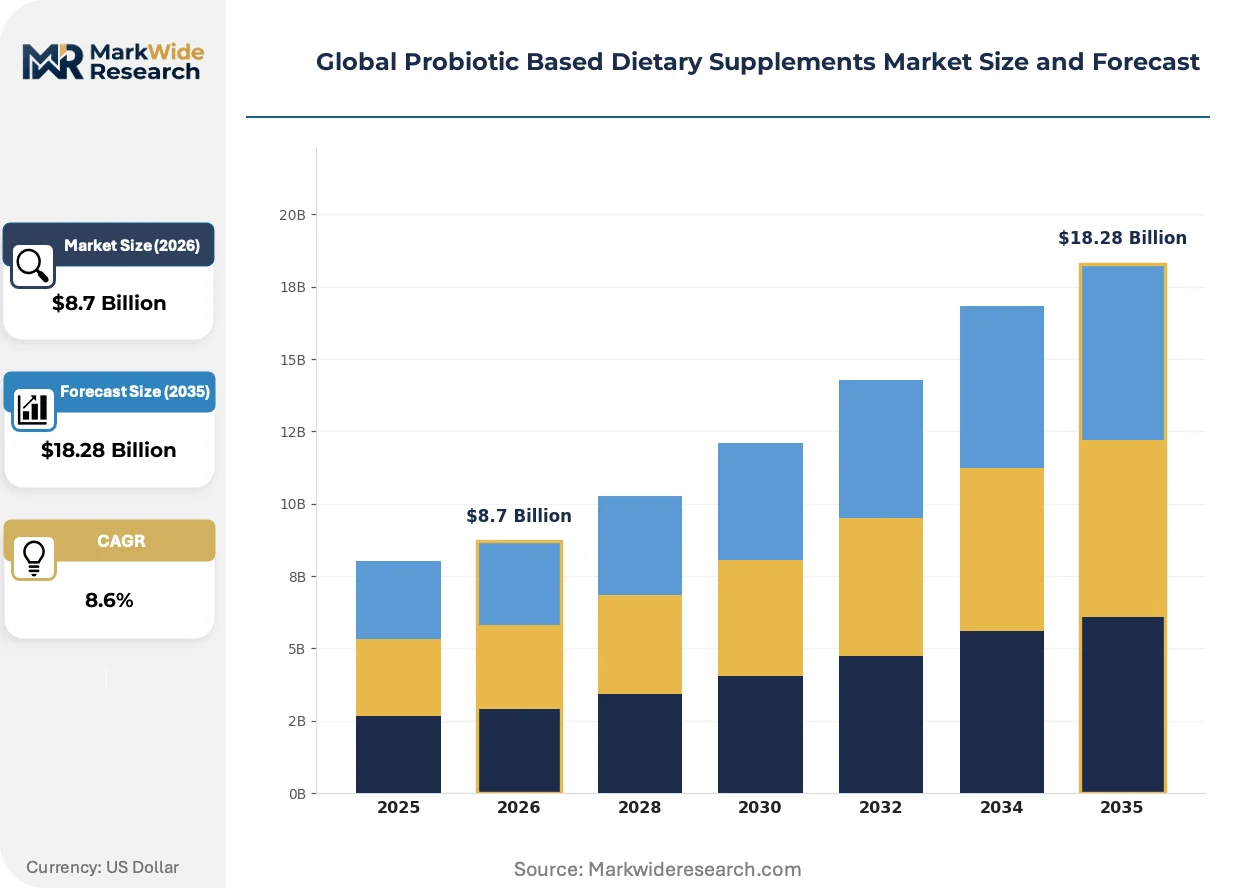
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $18.28 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Gummies, Liquids End User: Adults, Children, Seniors, Pregnant Women Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Food Stores Form: Solid, Liquid, Chewable, Effervescent |
| Companies Covered | Nestlé Health Science, Danone, Novonesis Group, DuPont de Nemours, Inc., Yakult Honsha Co., Ltd., BioGaia AB, Bayer AG, NOW Foods, Lesaffre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Probiotic Based Dietary Supplements Market Strategic Shifts
Microbiome sequencing costs and personalized nutrition platforms are converging to displace one-size-fits-all probiotic formulations. This technological inflection is rewiring competitive advantage toward data-integrated health solutions.
Microencapsulation via spray-drying and fluidized bed coating is fragmenting the stability-performance tradeoff that previously favored refrigerated liquid formats. Sports nutrition brands and travel-focused supplement lines are adopting these ambient-stable technologies at accelerating rates. The structural consequence is compressing cold-chain infrastructure requirements while enabling pharmacy and convenience retail placement previously inaccessible to live culture products.
EFSA's 2023 clarification on probiotic labeling restrictions is tightening permissible health communications across the European Union. Manufacturers must now separate strain-specific evidence from generic fermentation benefits in all consumer-facing materials. Pediatric and immune-positioned products face the steepest reformulation costs as legacy claims require systematic substantiation reviews.
Consumer purchasing patterns are rotating toward third-party certified products bearing USP, NSF, or ConsumerLab verification marks. Online retail channels amplify this preference through filterable search interfaces that prioritize certified SKUs. This certification-driven selection behavior concentrates demand among brands with documented quality investment, particularly visible in United States and German e-commerce environments.
Global Probiotic Based Dietary Supplements Market Segmentation
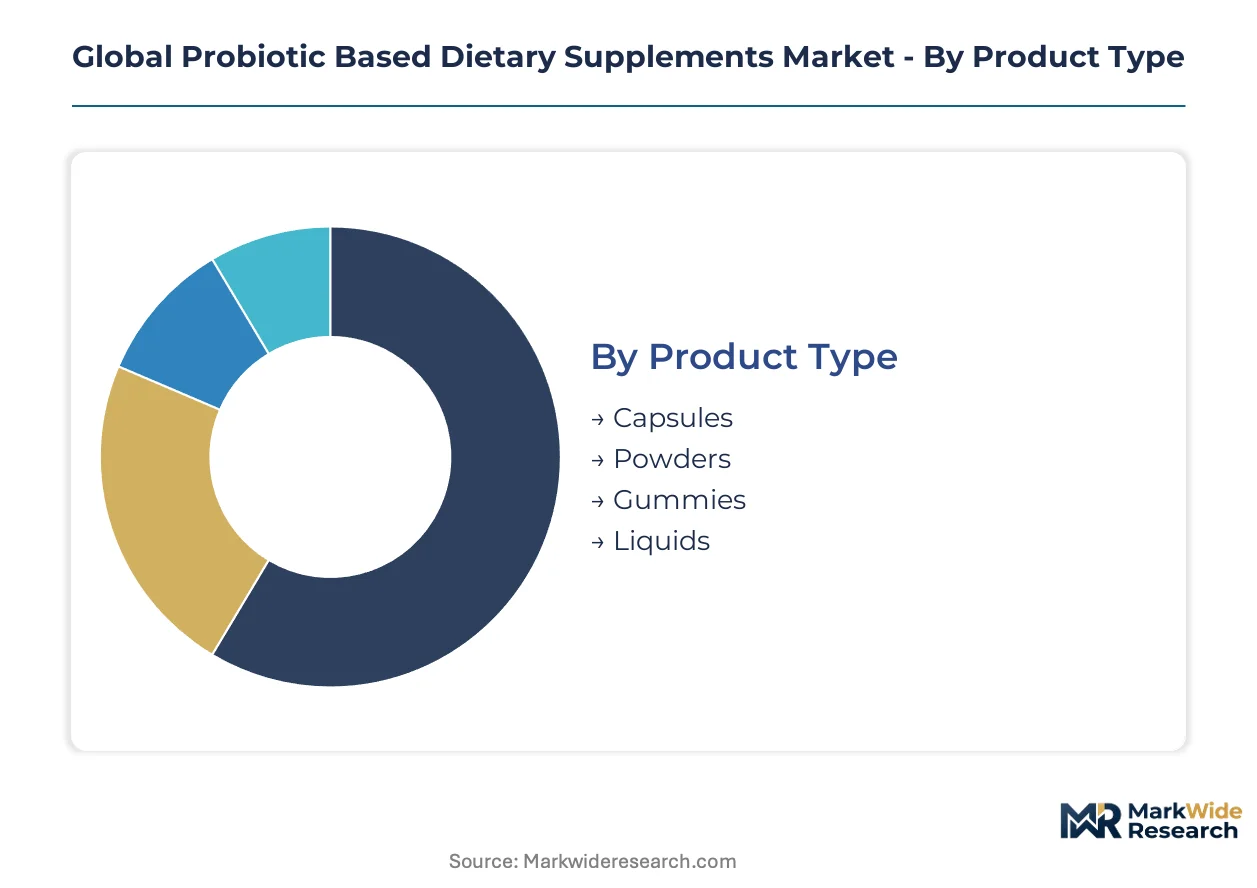
Strategic targeting in probiotic supplements demands precise alignment between formulation format and consumer compliance patterns. Segment-specific margin profiles diverge sharply based on stability requirements, channel access costs, and regulatory documentation burdens.
Product Type:
Margin pools concentrate in formats that solve the viability-stability tradeoff without cold-chain dependency.
- Capsules:Enteric-coated gelatin or vegetable cellulose shells protect Lactobacillus and Bifidobacterium strains from gastric acid degradation. Demand clusters among adults in Germany and the United States seeking precise CFU dosing with extended shelf stability. Moisture-barrier blister packs and desiccant integration reduce spoilage returns for pharmacy and e-commerce channels.
- Gummies:Pectin or gelatin matrices suspend live cultures with flavor masking for pediatric and reluctant adult users. Palatability-driven compliance expansion in China and tier-2 Indian cities is compressing the traditional capsule-dominant revenue structure. Heat-sensitive formulation constraints elevate manufacturing complexity premiums.
- Powders:Sachet or bulk formats enable flexible dosing and beverage integration for sports nutrition applications.
- Liquids:Refrigerated dropper bottles target infant and senior segments requiring swallowing ease.
The dominant share belongs to Capsules, while Gummies is closing the gap fastest.
End User:
Application-specific strain requirements and dosing protocols fragment development priorities across life-stage segments.
- Adults:Multi-strain formulations at 10^9 to 10^11 CFU target digestive wellness and immune modulation for working-age populations. Concentrated demand in the United States and China reflects preventive health prioritization and workplace productivity concerns. Subscription replenishment models capture recurring revenue with higher lifetime value than intermittent retail purchasing.
- Children:Single-strain Lactobacillus rhamnosus and Lactobacillus reuteri products with documented pediatric safety profiles address parental anxiety around antibiotic-associated diarrhea. Growth concentrates in Germany and Nordic markets with established clinical validation cultures. Dose-precision requirements elevate packaging and labeling compliance costs.
- Seniors:Bifidobacterium-dominant formulations target age-related microbiome decline and nutrient absorption efficiency.
- Pregnant Women:Strain-specific selections with gestational safety documentation support maternal metabolic and vaginal microbiome health.
Adults command the revenue base, with Children expanding most quickly on clinical validation investments.
Distribution Channel:
Channel selection determines margin capture through markup bypass or trust-transfer mechanisms.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription automation and third-party certification filtering. United States and German e-commerce environments amplify USP and NSF verification preferences through searchable product attributes. Cold-chain compression via ambient-stable formulations expands addressable logistics networks.
- Pharmacies:Pharmacist recommendation channels transfer clinical credibility for condition-specific positioning. China's SAMR registration requirements and India's FSSAI strain documentation create compliance moats for documented manufacturers. Retail markup structures compress manufacturer margins against volume access.
- Supermarkets:Mass-market placement drives impulse purchasing for established brand recognition.
- Health Food Stores:Specialty retail environments support premium positioning and educated consumer consultation.
Online Retail leads volume contribution, while Pharmacies maintains pricing power on clinical endorsement.
Form:
Physical state governs manufacturing capital requirements and consumption occasion flexibility.
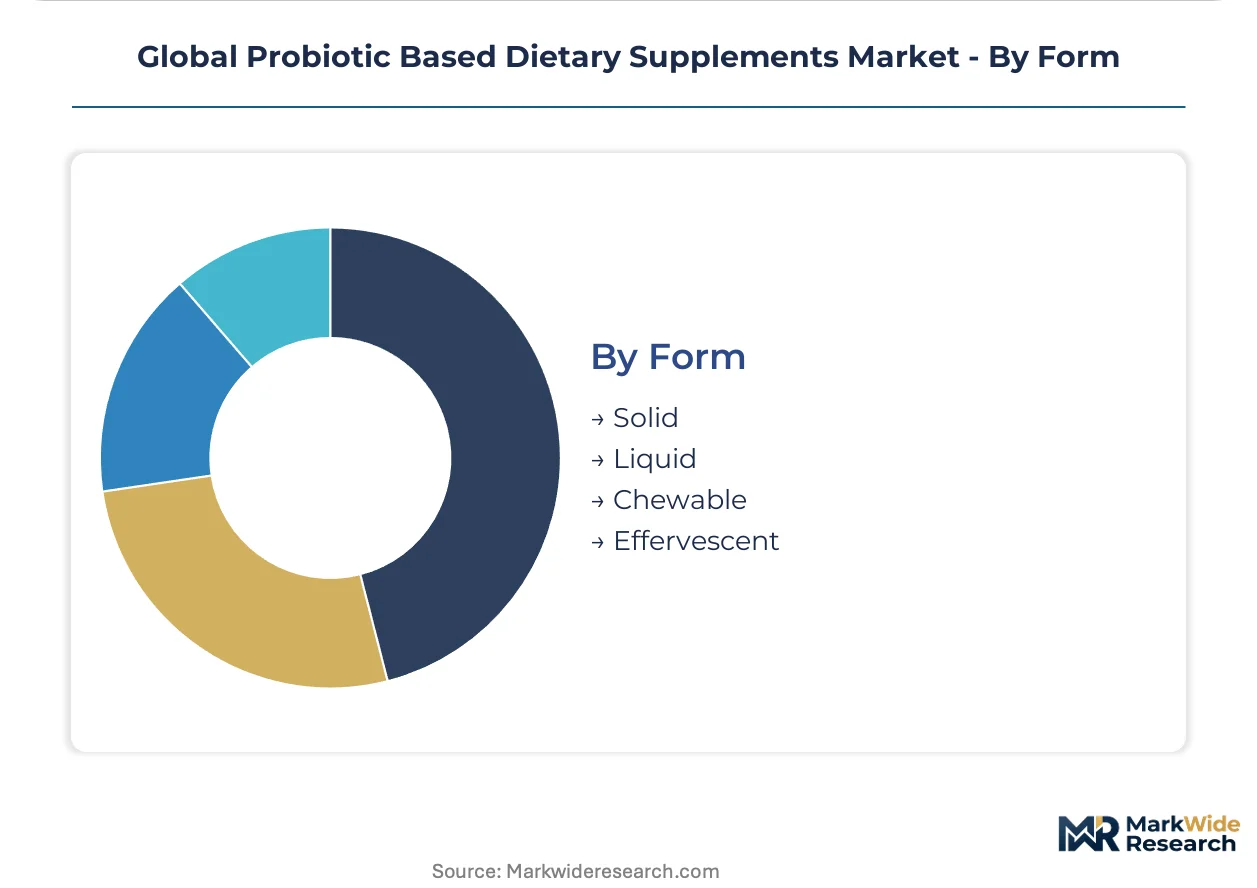
- Solid:Tablets and capsules dominate production scale economies with established compression and coating infrastructure. Shelf-stable formats reduce distribution cost burdens across United States and European retail networks. Strain viability maintenance through microencapsulation advances is elevating technical differentiation.
- Liquid:Suspension and emulsion formats require refrigerated logistics but enable rapid absorption claims. Concentrated demand in infant nutrition and senior care applications where swallowing mechanics constrain solid format adoption. Shorter shelf life compresses inventory turnover requirements.
- Chewable:Gummy and tablet formats bridge palatability and portability for travel and pediatric segments.
- Effervescent:Rapid-dissolve tablets in water create consumption ritual differentiation for wellness-positioned brands.
Solid forms anchor production volume, with Liquid formats gaining fastest on senior and pediatric targeting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bacterial culture production clusters in Denmark, France, and Japan, while finished supplement formulation concentrates in the United States, Germany, and China where health-conscious consumers drive premium uptake.
United States
FDA oversight of dietary supplement Good Manufacturing Practices shapes product development trajectories for domestic manufacturers. Subscription direct-to-consumer channels capture expanding margin pools by bypassing traditional pharmacy markups. Greater Boston and California's Bay Area host microbiome sequencing startups converging with personalized nutrition platforms.
Germany
Digestive wellness prioritization among working-age populations sustains multi-strain probiotic demand across pharmacy and e-commerce channels. EFSA health claim authorization requirements filter marketing messaging for products entering the broader European market. Bavaria anchors specialized fermentation infrastructure serving clinical-grade strain verification needs.
China
SAMR registration pathways for documented probiotic species accelerate product launches for compliant foreign manufacturers. Tier-2 and tier-3 cities present underpenetrated awareness gaps for clinically validated pediatric formulations. Yangtze River Delta manufacturing clusters specialize in ambient-stable microencapsulation technologies reducing cold-chain dependency.
India
FSSAI strain registry documentation mandates filter out undercapitalized entrants while creating compliance moats for established players. Tier-2 and tier-3 cities offer first-mover positioning for clinically documented geriatric formulations. Maharashtra and Gujarat host emerging contract manufacturing capacity for export-oriented probiotic finished goods.
Japan
Yakult Honsha's heritage in daily fermented milk consumption established precedent for routine probiotic supplementation among aging demographics. PMDA and Ministry of Health oversight maintains stringent safety documentation standards for functional food positioning. Tokyo-Osaka corridor concentrates retail pharmacy networks transferring clinical credibility for condition-specific products.
Global Probiotic Based Dietary Supplements Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the probiotic supplements landscape. Strain-specific clinical documentation libraries and certified manufacturing infrastructure reward incumbents with established regulatory compliance capabilities. Three archetypes dominate: fermentation-science heritage firms, dairy-linked distribution networks, and specialized pediatric or oral health niche players. Competitive dynamics center on M&A activity consolidating strain banking assets and strategic partnerships securing proprietary culture deposits.
Within the fermentation-science tier, Novonesis Group leverages its Danish heritage in specialized bacterial cultures. Danone anchors its position through extensive dairy-linked probiotic distribution networks. BioGaia AB occupies a distinct position dominating pediatric and oral health niches with documented clinical strains. These three exemplify how regulatory compliance capabilities and strain-specific intellectual property create defensible market positioning.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Danone |
| Novonesis Group |
| DuPont de Nemours, Inc. |
| Yakult Honsha Co., Ltd. |
| BioGaia AB |
| Bayer AG |
| NOW Foods |
| Lesaffre |
| Others |
Value Chain & Pricing Dynamics
Microencapsulation technology replacing refrigerated liquid formats is redrawing supply geography toward ambient-stable manufacturing clusters in China and India while collapsing cold-chain cost premiums that previously stratified pricing tiers across developed markets.
Pricing Analysis
EFSA health claim authorization requirements dictate the pricing tier structure across European markets, separating premium clinically validated strains from standard fermentation-derived products. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and documented CFU stability at consumption. Pricing pressure stems from plant-based dairy alternatives capturing functional beverage demand. Private-label entrants in the United States exhibit highest price sensitivity, while pharmacy-endorsed brands in Germany command lowest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for fermentation-grade glucose and yeast extract shipments. Supply concentrates in Denmark, France, and Japan for specialized bacterial cultures, with finished formulation in the United States, Germany, and China. Raw material dependencies include agricultural-grade glucose, yeast extract, and gelatin or pectin matrices. Single-source vulnerability around proprietary strain deposits creates concentration risk. Distribution runs through direct-to-consumer subscription channels bypassing traditional pharmacy markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against functional beverage substitution as oat and almond milk alternatives with added live cultures erode dedicated supplement demand across wellness-positioned consumer segments.
For Market Incumbents: Fortify strain banking assets through targeted acquisition of proprietary culture deposits to secure freedom-to-operate against patent thickets. Deepen clinical documentation libraries ahead of tightening EFSA and FDA labeling mandates. Prioritize backward integration into fermentation-grade glucose supply to buffer agricultural commodity volatility squeezing margin predictability.
For New Entrants and Emerging Players: FDA GRAS notification fast-track offers regulatory arbitrage against EFSA's multi-year authorization backlog for European market access. Target tier-2 and tier-3 Indian cities where FSSAI strain registry gaps create first-mover positioning for clinically documented pediatric formulations. Deploy subscription direct-to-consumer models capturing recurring revenue with higher lifetime value metrics than intermittent retail purchasing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation-science specialists holding Danish and French manufacturing infrastructure but lacking distribution scale. Five-to-ten year viability hinges on microbiome sequencing convergence with personalized nutrition platforms displacing generic formulations. Monitor SAMR registration acceleration for compliant foreign manufacturers as inflection signal for China market access premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Acquisition | Proprietary culture deposits secure formulation freedom-to-operate against Lactobacillus patent thickets. |
| Clinical Documentation Investment | Documented pediatric safety profiles unlock pharmacy endorsement channels in Germany and Nordic markets. |
| Microencapsulation Scale-Up | Ambient-stable technologies reduce cold-chain dependency and expand convenience retail placement access. |
| Subscription Channel Launch | Direct-to-consumer replenishment bypasses pharmacy markups and captures higher lifetime value metrics. |
| SAMR Registration Completion | Streamlined strain approval accelerates product launches for compliant foreign manufacturers in China. |
Study Parameters
A spread of perspectives from probiotic formulation scientists, regulatory affairs specialists at EFSA and FDA, pharmacy category managers, and direct-to-consumer brand operators converged on the working assumptions. Primary interviews combined with secondary validation from FDA GRAS notifications, EFSA health claim submissions, SAMR registration databases, and FSSAI strain registry records. Bottom-up strain-level demand modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product format stability requirements, end-user life-stage applications, distribution channel margin structures, and regional regulatory cluster stringency. CAGRs derived from historical trajectory analysis adjusted for documented regulatory inflection points. Forecast inputs incorporated microbiome sequencing cost curves and personalized nutrition platform adoption rates.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA and FDA labeling trajectory and stable agricultural commodity input costs; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Global Enteric Softgel Capsules Market