
 Private Narrowband IoT Market | 2026-2036
Private Narrowband IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Private Narrowband IoT Market Analysis
Market Context with Strategic Players
3GPP Release 13 certification is bifurcating the vendor landscape into qualified module suppliers and second-tier assemblers. Huawei Technologies leverages its integrated baseband-to-antenna stack to dominate private network tenders across Asian manufacturing hubs. Qualcomm Technologies anchors the chipset layer through R&D intensity in ultra-low-power narrowband modems, while Nokia competes on geographic dominance in European utility deployments.
Technical Definition and Structural Segments
Private Narrowband IoT denotes a licensed-spectrum, low-power wide-area network architecture operating in sub-GHz bands with 200 kHz channel bandwidth, designed for intermittent small-data transmission across geographically dispersed assets. By technology, NB-IoT leads in utility metering deployments where decade-long battery life and deep indoor penetration justify infrastructure investment, while LTE-M captures faster-growing share in mobile asset tracking applications requiring moderate mobility support. Application segmentation reveals smart metering as the mature revenue pool, with industrial automation representing the fastest-growing margin segment as manufacturers deploy condition monitoring on captive private networks.
Regulatory Framework and Forward Outlook
3GPP standards, the EU Cybersecurity Act, and FCC Part 15 rules collectively shape product certification timelines, spectrum allocation, and cross-border module interoperability requirements. ETSI EN 303 645 baseline security requirements in Europe and FCC equipment authorization in the United States create dual-compliance burdens that filter market access for module vendors. Stakeholders must monitor spectrum refarming decisions in key jurisdictions and assess whether hybrid deployment architectures can satisfy diverging national security mandates without fragmenting product portfolios.
Market Dynamics
The 3GPP Release 13 certification mandate is compressing the vendor base into qualified module suppliers versus second-tier assemblers, reshaping competitive positioning across utility and industrial automation deployments.
Growth Catalysts
- EU Cybersecurity Act:Baseline certification requirements for connected critical infrastructure are accelerating module procurement cycles among German utilities deploying smart metering networks.
- Industrial automation corridors:Shenzhen and Shanghai manufacturing zones are absorbing significant private network module volumes for condition monitoring applications.
- Sub-GHz spectrum allocation:Licensed 200 kHz channel bandwidth in sub-GHz bands enables decade-long battery life for geographically dispersed asset tracking.
Market Restraints
- Dual-compliance burden:ETSI EN 303 645 baseline security requirements in Europe and FCC Part 15 equipment authorization in the United States create fragmented product certification timelines.
- Chipset supply concentration:Ultra-low-power narrowband modem R&D intensity concentrates at the baseband layer, limiting second-tier module vendor access to qualified silicon.
- LTE-M substitution threat:Moderate mobility support in mobile asset tracking applications is displacing NB-IoT in faster-growing tracking segments.
Strategic Opportunities
- Underpenetrated manufacturing clusters:Captive private network deployments in Vietnam and Indonesia offer white space for module vendors outside established Chinese corridors.
- Hybrid architecture convergence:Integration of NB-IoT with 5G private network cores enables unified connectivity management for mixed-criticality industrial sites.
- Utility procurement centralization:European water and gas distributors are consolidating module sourcing through framework agreements, favoring vendors with multi-country certification portfolios.
Industry Challenges
- RF engineering talent scarcity:Deep indoor penetration optimization and antenna tuning expertise sits concentrated among legacy cellular infrastructure specialists.
- Legacy system integration friction:SCADA and AMI backhaul integration with IP-native NB-IoT cores requires protocol gateway development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Narrowband IoT Market |
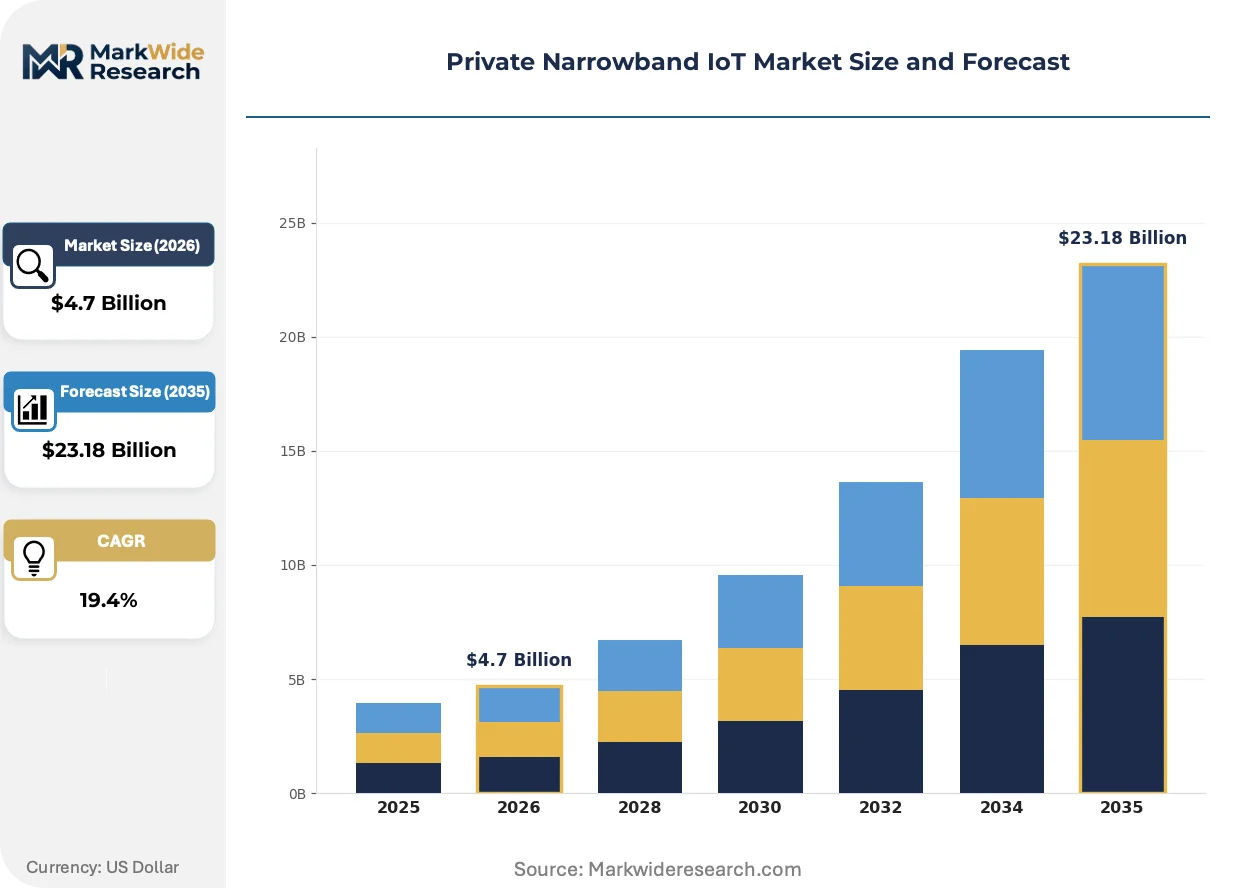
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Private Cloud, Hybrid, Virtual Private Network Technology: NB-IoT, LTE-M, GPRS, LoRa Application: Smart Metering, Asset Tracking, Industrial Automation, Smart Agriculture End User: Utilities, Manufacturing, Transportation, Retail |
| Companies Covered | Huawei Technologies, Qualcomm Technologies, AT&T, Nokia, Intel Corporation, Verizon Communications, Ericsson Corporation, Cisco Systems, China Mobile Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Narrowband IoT Market Emerging Trajectories
Module architecture is splitting between integrated baseband-to-antenna stacks and discrete component assemblies, with certification requirements determining which design philosophy captures utility tenders versus industrial automation contracts.
3GPP Release 14 and 15 enhancements are bifurcating the module landscape into positioning-capable variants for mobile asset tracking and ultra-low-power optimized designs for static metering applications. German utilities are adopting positioning-enabled modules for distribution network fault location, while Chinese manufacturers prioritize power-optimized variants for battery-constrained condition sensors. This technical segmentation is compressing margins for undifferentiated mid-tier module suppliers lacking either capability depth.
ETSI EN 303 645 baseline security requirements are mandating firmware signing and secure boot capabilities that extend module development cycles by eight to twelve months. European module vendors are absorbing these compliance costs through premium pricing to utilities, while Asian suppliers face market access barriers without certified manufacturing facilities. The regulatory friction most impacts small-scale industrial automation deployers lacking dedicated compliance teams.
Buyer concentration among European utility procurement consortia is displacing fragmented distributor networks with direct manufacturer relationships and multi-year framework agreements. Siemens and Schneider Electric are consolidating module sourcing through centralized technical qualification processes that favor vendors with pan-European service footprints. This channel restructuring is most visible in Germany and France, where distribution system operators are harmonizing technical specifications across municipal boundaries.
Private Narrowband IoT Market Segmentation
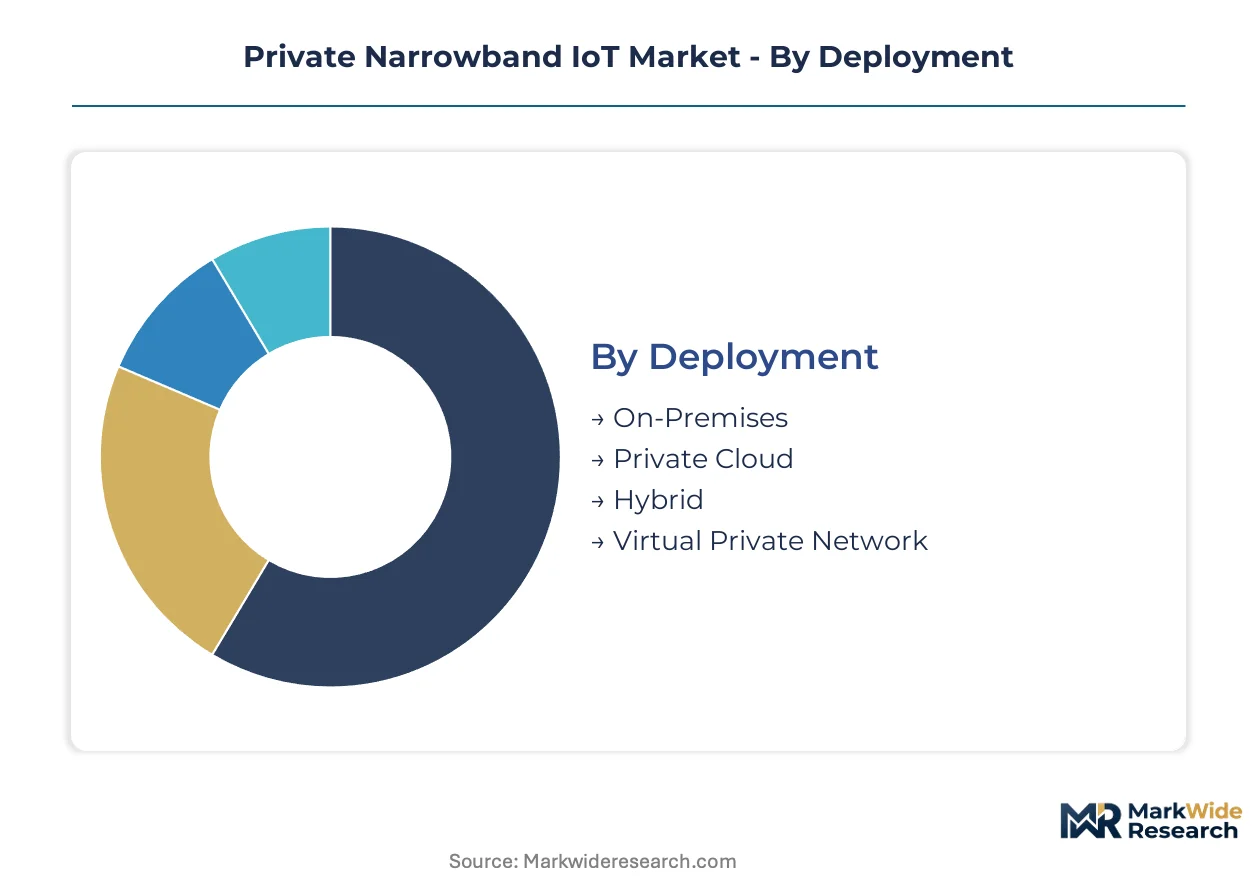
Private Narrowband IoT deployments fragment across infrastructure ownership models and spectrum technologies, with procurement channels diverging between utility framework agreements and industrial direct sourcing. Understanding how segments map to customer buying behaviors illuminates vendor positioning and margin capture opportunities.
Deployment:
Channel mix varies sharply by deployment architecture, with on-premises installations flowing through systems integrators while private cloud and hybrid models increasingly route through telecom operator marketplaces.
- On-Premises:Captive infrastructure ownership with dedicated baseband hardware deployed behind manufacturing firewalls. German utilities and Shenzhen electronics manufacturers absorb significant volumes through direct vendor relationships, driven by data sovereignty mandates under EU Cybersecurity Act and China's MIIT cybersecurity regulations.
- Private Cloud:Hosted network cores with customer-dedicated radio access network slices. European water distributors in France and Germany are consolidating procurement through Schneider Electric and Siemens framework agreements, favoring vendors with multi-country service footprints.
- Hybrid:Split architectures combining on-premises gateways with cloud-orchestrated cores. Industrial automation deployers in Vietnam and Indonesia manufacturing clusters are adopting hybrid models to balance latency-sensitive condition monitoring with centralized fleet management.
- Virtual Private Network:Logical network isolation over shared operator infrastructure. Retail asset tracking applications in transportation hubs utilize VPN deployments for rapid geographic expansion without spectrum licensing delays.
On-Premises dominates installed base among security-sensitive utilities. Private Cloud is where expansion concentrates as European procurement centralization accelerates.
Technology:
Cost tier stratification separates premium-certified modules from economy-tier alternatives, with certification depth determining access to utility tenders versus industrial spot purchasing.
- NB-IoT:Licensed-spectrum 200 kHz narrowband technology optimized for decade-long battery life and deep indoor penetration. Smart metering deployments across German utilities and Chinese industrial zones absorb the majority of module volumes, constrained by 3GPP Release 13 certification timelines that filter second-tier assemblers from qualified supplier lists.
- LTE-M:Higher-throughput cellular IoT variant supporting moderate mobility and voice channels. Asset tracking applications in transportation and mobile industrial equipment are climbing the fastest as positioning-enabled modules capture distribution network fault location contracts.
- GPRS:Legacy 2G fallback technology for transitional deployments. Remaining utility AMI backhaul integrations in regions with delayed spectrum refarming utilize GPRS modules as protocol bridge elements.
- LoRa:Unlicensed sub-GHz proprietary protocol for cost-constrained sensor networks. Smart agriculture deployments in remote monitoring applications employ LoRa where licensed spectrum economics prove prohibitive for low-data-volume endpoints.
NB-IoT anchors revenue among certified utility suppliers. LTE-M is where margin expansion concentrates as positioning capabilities command premium pricing.
Application:
Application segmentation reveals divergent maturity curves, with smart metering procurement running through centralized frameworks while industrial automation contracts fragment across direct manufacturer negotiations.
- Smart Metering:Mature revenue pool encompassing electricity, gas, and water AMI infrastructure. German distribution system operators harmonizing technical specifications across municipal boundaries are absorbing significant NB-IoT module volumes through multi-year framework agreements.
- Asset Tracking:Mobile and fixed asset location services requiring positioning capabilities. Transportation fleets and logistics operators are expanding procurement of LTE-M modules with Release 14 positioning enhancements for fleet optimization.
- Industrial Automation:Condition monitoring and predictive maintenance on captive private networks. Shenzhen and Shanghai manufacturing corridors represent concentrated demand, with Vietnam and Indonesia clusters offering white space expansion opportunities.
- Smart Agriculture:Remote soil moisture, livestock, and equipment monitoring in geographically dispersed deployments. LoRa and NB-IoT modules compete based on spectrum licensing economics and backhaul infrastructure availability.
Smart Metering dominates installed base among European utilities. Industrial Automation is where steepest expansion trajectory concentrates as manufacturers deploy condition monitoring at scale.
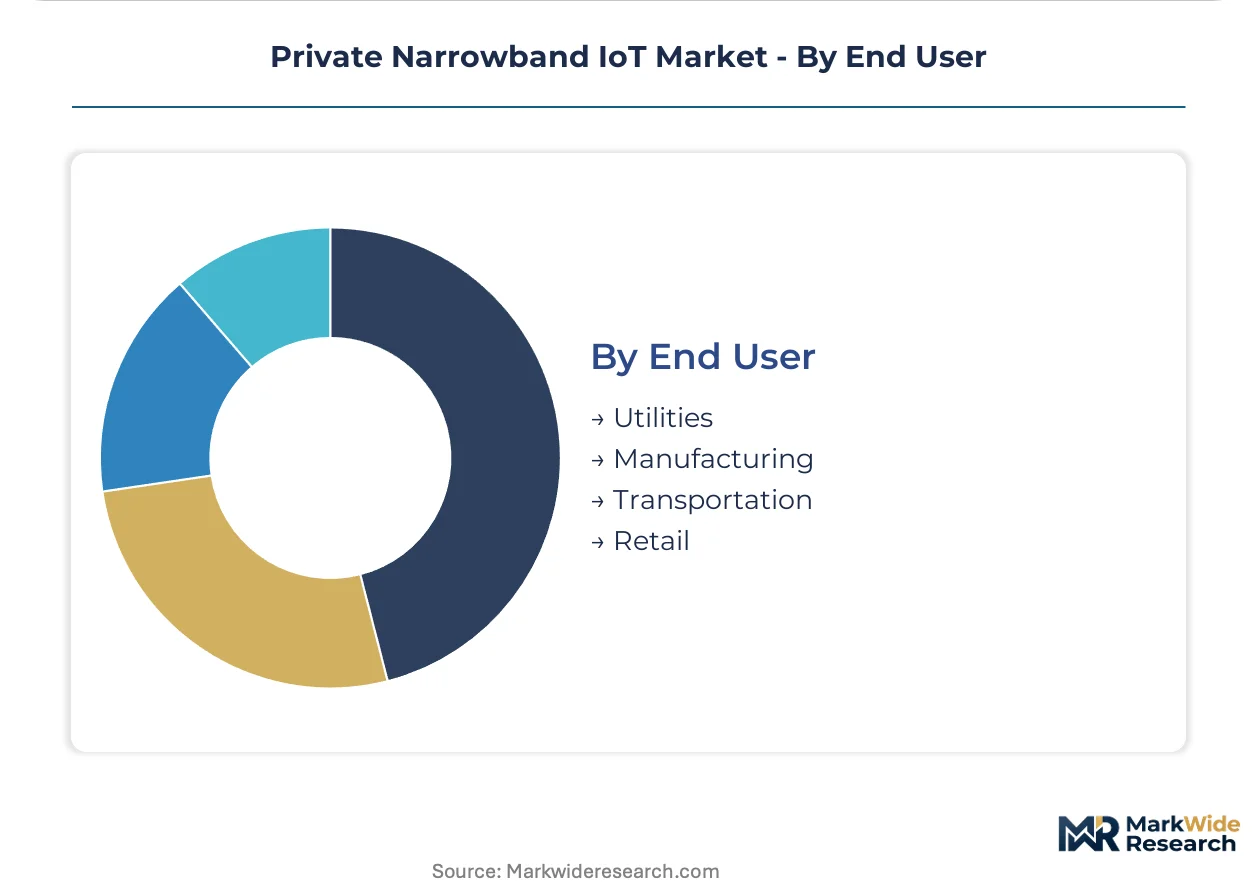
End User:
Customer type determines procurement sophistication, with utilities operating centralized technical qualification processes while manufacturing and transportation buyers emphasize rapid deployment flexibility.
- Utilities:Electricity, water, and gas distribution operators with decade-long infrastructure horizons. ETSI EN 303 645 compliance requirements and EU Cybersecurity Act mandates are extending module development cycles, favoring vendors with certified manufacturing facilities and pan-European service capabilities.
- Manufacturing:Electronics, automotive, and process industry operators deploying captive private networks. Chinese industrial automation corridors absorb significant volumes, with RF engineering talent scarcity concentrated among legacy cellular infrastructure specialists constraining rapid scaling.
- Transportation:Fleet operators and logistics providers requiring mobile asset visibility. LTE-M substitution is accelerating as moderate mobility support displaces NB-IoT in tracking applications.
- Retail:Supply chain and inventory management operators with distributed endpoint requirements. Virtual private network deployments enable rapid geographic expansion without dedicated spectrum licensing.
Utilities dominate certified module procurement through framework centralization. Manufacturing is where volume expansion concentrates as private network deployments proliferate across Asian industrial zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement consortia and industrial automation clusters concentrate demand across Germany, China, the United States, Japan, and Vietnam. Each geography presents distinct regulatory compliance requirements and deployment architectures that shape vendor access and margin capture.
Germany
Distribution system operators in Bavaria and North Rhine-Westphalia are harmonizing technical specifications across municipal boundaries for smart metering infrastructure. The EU Cybersecurity Act mandates ETSI EN 303 645 baseline certification for connected critical infrastructure, extending module development cycles. Siemens and Schneider Electric are consolidating procurement through multi-year framework agreements that favor vendors with pan-European service footprints.
China
Shenzhen and Shanghai manufacturing corridors absorb significant private network module volumes for condition monitoring applications. MIIT cybersecurity regulations require data sovereignty compliance for captive industrial deployments. The Pearl River Delta electronics manufacturing cluster is deploying battery-optimized NB-IoT variants for sensor networks across automotive and electronics assembly lines.
United States
Transportation fleets and logistics operators are expanding procurement of LTE-M modules with positioning capabilities for mobile asset tracking. FCC Part 15 equipment authorization creates compliance timelines that filter non-certified vendors from utility tenders. The Pacific Northwest utility sector is piloting hybrid deployment architectures combining on-premises gateways with cloud-orchestrated cores.
Japan
Industrial automation deployers in the Kanto region around Tokyo are adopting private NB-IoT networks for predictive maintenance on manufacturing equipment. METI standards guide spectrum allocation for licensed sub-GHz deployments in factory environments. The Chubu industrial corridor near Nagoya is integrating NB-IoT modules with legacy SCADA systems through protocol gateway development.
Vietnam
Electronics manufacturers in Ho Chi Minh City and Hanoi are deploying captive private networks as Chinese supply chain diversification accelerates. The country's national telecommunications regulator is streamlining spectrum licensing for industrial IoT applications. Northern Vietnam manufacturing clusters offer white space expansion opportunities for module vendors outside established Chinese corridors.
Private Narrowband IoT Market Vendor Landscape
Player mix skews toward integrated baseband-to-antenna stack specialists and chipset-layer technology licensors, with certification depth determining tier placement. The vendor base compresses into qualified module suppliers versus second-tier assemblers as 3GPP Release 13 mandates reshape competitive positioning. Strategic archetypes include integrated infrastructure vendors, discrete chipset specialists, and telecom operator channel partners. Dominant competitive moves center on multi-country certification portfolio expansion and hybrid architecture convergence with 5G private network cores.
Within the integrated infrastructure tier, Huawei Technologies and Nokia exemplify divergent geographic dominance patterns. Huawei leverages its Shenzhen base to anchor private network tenders across Asian manufacturing hubs, while Nokia occupies a position concentrated on European utility deployments. Qualcomm Technologies represents the chipset-layer archetype, anchoring ultra-low-power narrowband modem supply through R&D intensity at the baseband layer. These three companies illustrate how certification timelines and geographic regulatory alignment stratify competitive access across deployment verticals.
| Leading Market Players |
|---|
| Huawei Technologies |
| Qualcomm Technologies |
| AT&T |
| Nokia |
| Intel Corporation |
| Verizon Communications |
| Ericsson Corporation |
| Cisco Systems |
| China Mobile Limited |
| Others |
Supply Flow & Price Mechanics
3GPP Release 13 certification timelines gate both supplier qualification and module price stratification simultaneously, compressing vendor tiers while extending development cost amortization across premium utility contracts versus spot industrial purchases. German utilities absorb certification premiums through multi-year framework agreements, while second-tier assemblers face margin compression without qualified silicon access.
Pricing Analysis
Cost-plus contracts with semiconductor raw material indexation dominate utility procurement, with module vendors passing through baseband chipset fluctuations while capturing fixed-margin service fees. Price differentiation hinges on 3GPP certification depth and pan-European service footprint, with ETSI EN 303 645 compliance adding eight to twelve month development premiums. Cost compression in economy-tier modules is intensifying because LTE-M substitution threatens NB-IoT volume in mobile tracking applications. Transportation fleets demonstrate highest price sensitivity due to commoditized positioning capabilities, while German water distributors accept premium pricing for cybersecurity-assured supply security.
Supply Chain Analysis
TSMC advanced node allocation for ultra-low-power baseband modems creates a chokepoint that constrains second-tier module vendor access to qualified silicon. Manufacturing concentrates in China, Taiwan, and South Korea, with final assembly drawing from Shenzhen electronics corridors and Vietnamese contract manufacturers. Raw material dependencies span silicon wafers, sub-GHz RF filters, and lithium primary cells for decade-long battery life. Single-source vulnerability at the baseband layer exposes vendors to allocation priority shifts. Distribution runs through telecom operator marketplaces for private cloud deployments and direct manufacturer relationships for on-premises utility installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment architectures creates specialist niches as hybrid models displace pure on-premises or cloud-native approaches, rewarding vendors with cross-architecture integration capabilities rather than single-mode scale players.
For Market Incumbents: Secure multi-country certification portfolios ahead of EU Cybersecurity Act enforcement waves, prioritizing ETSI EN 303 645 baseline compliance as a defensive moat against Asian cost competitors. Anchor pan-European service footprints through Schneider Electric and Siemens framework qualifications to lock out second-tier assemblers from utility procurement centralization. Vertical integration into secure boot firmware development addresses the eight to twelve month compliance timeline extension threatening margin capture. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia manufacturing clusters where Chinese supply chain diversification accelerates captive private network deployment without established incumbent saturation. Target hybrid architecture integration services for industrial automation deployers balancing latency-sensitive condition monitoring with centralized fleet management, leveraging protocol gateway development capabilities as entry wedge. Pursue direct manufacturer relationships rather than fragmented distributor networks to bypass procurement consolidation barriers in European utilities. For Investors and Strategic Acquirers: 3GPP Release 14 and 15 enhancement cycles reshape the acquisition landscape toward positioning-capable module specialists and ultra-low-power optimization firms with divergent capability depth. Long-term viability favors vendors with certified manufacturing facilities and dual-technology NB-IoT/LTE-M portfolios over undifferentiated mid-tier suppliers lacking either positioning or power optimization depth. Acquisition target archetype: European module vendors with ETSI compliance infrastructure and Asian assembly partnerships. Monitor spectrum refarming decisions in Germany and China as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Country Certification Portfolio Expansion | ETSI EN 303 645 compliance unlocks German utility framework agreements through cybersecurity assurance. |
| Hybrid Architecture Convergence with 5G Cores | Unified connectivity management captures mixed-criticality industrial sites migrating from siloed networks. |
| Backward Integration into Baseband Silicon | Captive supply of ultra-low-power modems insulates against TSMC allocation priority shifts affecting competitors. |
| Positioning Capability Development | Release 14 positioning modules command premium pricing in distribution network fault location contracts. |
| Pan-European Service Footprint Buildout | Direct technical qualification with Siemens and Schneider Electric displaces distributor-dependent rivals. |
Methodological Framework
A spread of perspectives from module vendor engineering directors, utility procurement managers at German distribution system operators, industrial automation plant engineers in Shenzhen manufacturing corridors, and telecom operator IoT platform specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through 3GPP release documentation, ETSI EN 303 645 certification registries, FCC equipment authorization databases, and customs trade flow records for NB-IoT module categories. Bottom-up unit economics triangulated against top-down market sizing from infrastructure deployment announcements.
Segmentation dimensions modeled span deployment architecture, technology variant, application vertical, and end-user procurement sophistication across the projection horizon. The analytical framework disaggregates volume through smart metering framework agreements, industrial automation direct sourcing, and transportation fleet procurement channels. CAGRs derived from installed base replacement cycles, spectrum licensing velocity, and cybersecurity mandate enforcement timelines. Forecast inputs incorporate module certification backlog durations, baseband chipset allocation priorities, and hybrid architecture adoption curves in Vietnamese manufacturing clusters.
Material uncertainties — spectrum refarming acceleration, LTE-M substitution velocity in mobile tracking, and EU Cybersecurity Act enforcement variance — sit outside the modeled envelope. Forecasts reflect assumptions regarding 3GPP release cadence, ETSI certification processing capacity, and industrial automation capital commitment sustainability. Practitioners should keep alternative scenarios live as regulatory milestone timing and technology substitution thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Edge Computing in IoT Market