
 Asia-Pacific Massive IoT Market | 2026-2036
Asia-Pacific Massive IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Massive IoT Market Insights
Modular hardware-software bundling is decoupling from traditional integrated-stack contracts across the Asia-Pacific Massive IoT landscape. Huawei Technologies leverages its in-house chip design and base station manufacturing to anchor large-scale smart city deployments. Samsung Electronics competes through vertical control over sensor fabrication and device management platforms. Alibaba Cloud differentiates by occupying the public cloud deployment tier with edge-to-core data pipelines tailored for manufacturing clients.
Massive IoT denotes wide-area networks connecting ultra-low-power devices at densities exceeding thousands per square kilometer, typically operating on narrowband protocols such as NB-IoT, LTE-M, or unlicensed LoRa with sub-50 kbps data rates and ten-year battery targets. The architecture serves industrial monitoring, utility metering, and agricultural telemetry where per-node cost minimization outweighs bandwidth requirements. Platform solutions currently lead value capture because recurring software margins exceed commoditized connectivity modules. Smart metering applications are maturing fastest in Northeast Asian utilities with established AMI infrastructure, while smart agriculture represents the fastest-expanding end-use as sensor costs fall below the threshold for smallholder farm economics. Edge computing deployments are concentrating margin pools in hybrid configurations that split inference between field gateways and centralized clouds.
China's MIIT enforces GB standards for radio equipment and dual carbon monitoring protocols that mandate connected energy meters in industrial facilities. Japan's METI administers JIS certification for IoT devices deployed in critical infrastructure, creating compliance barriers for non-domestic suppliers. India's TRAI governs spectrum allocation for unlicensed LPWAN bands, directly shaping network operator economics and hardware vendor market access. Stakeholders must monitor evolving spectrum harmonization negotiations between national regulators, as diverging band plans threaten cross-border device interoperability and supplier scale economies.
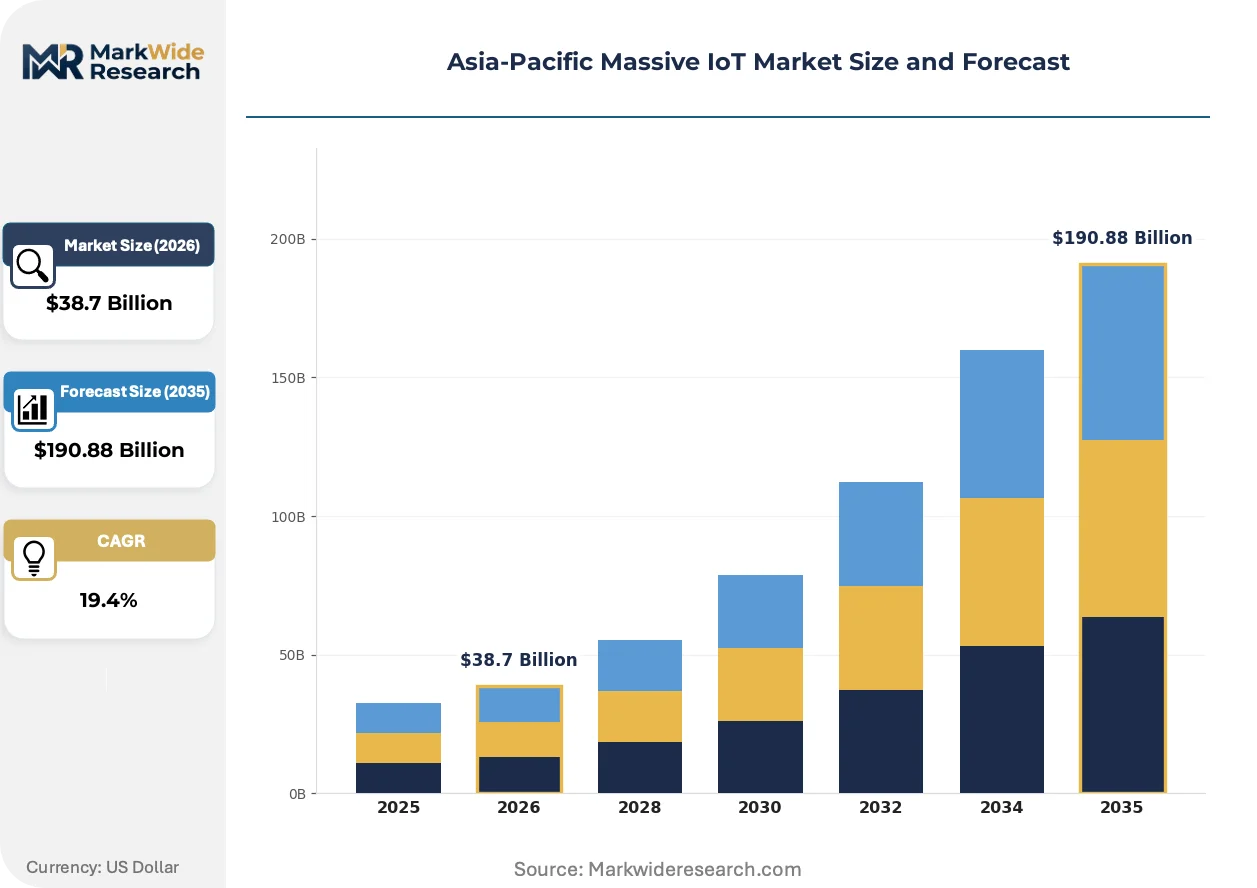
Market Dynamics
China's MIIT spectrum harmonization for NB-IoT and LoRaWAN is compressing module costs below the threshold for mass deployment, while India's factory digitization programs concentrate demand in industrial corridors across Gujarat and Tamil Nadu.
Growth Catalysts
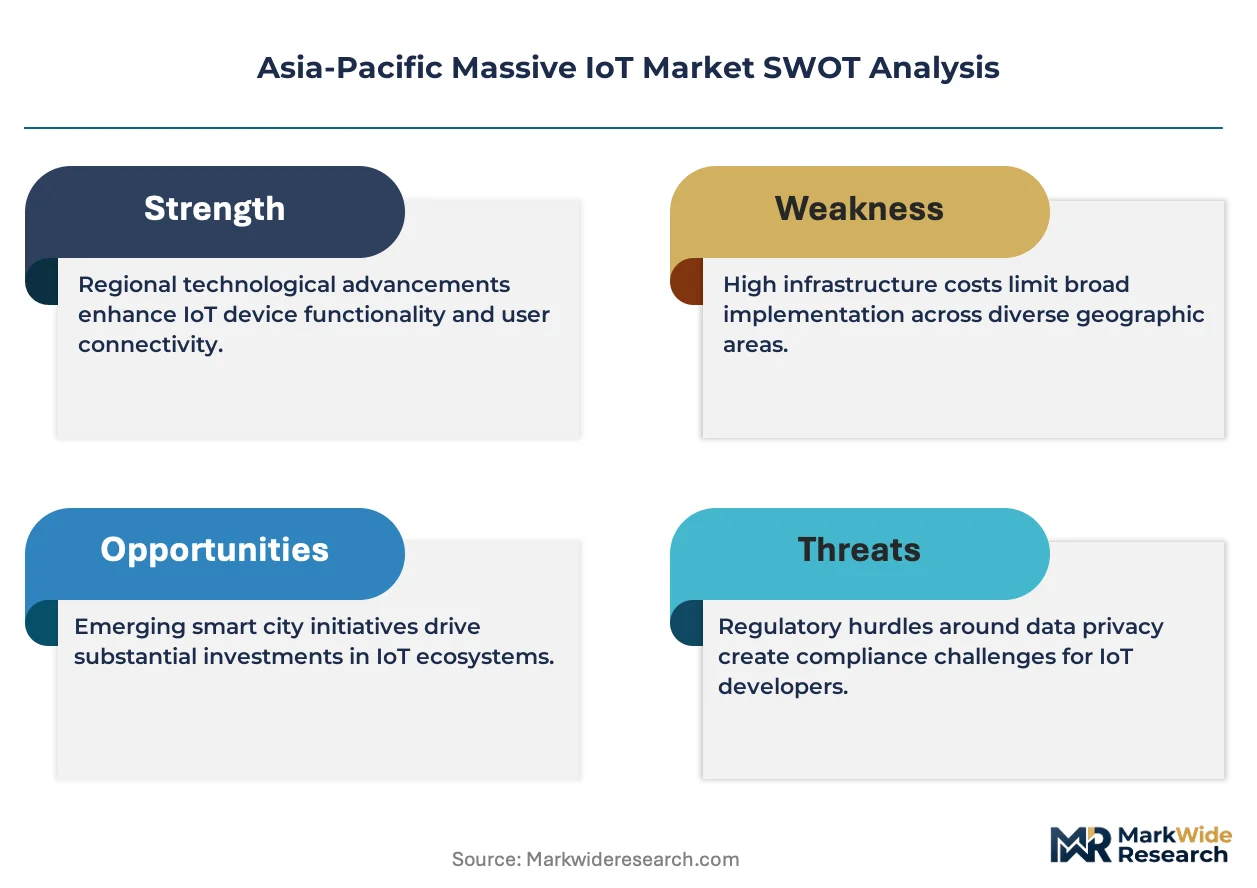
- TRAI unlicensed LPWAN allocation:India's spectrum framework for 865-867 MHz bands reduces network operator capex and accelerates rural sensor rollouts.
- Smart agriculture telemetry:Falling sensor costs below smallholder farm economics in Vietnam and Indonesia expand connected irrigation and soil monitoring deployments.
- Dual carbon monitoring mandates:China's GB standards for industrial energy meters create compulsory replacement cycles across steel and cement facilities.
Market Restraints
- NB-IoT chipset supply concentration:Three foundries control 80% of narrowband modem silicon, exposing procurement to geopolitical friction.
- LoRaWAN interference in dense urban RF environments:Unlicensed band congestion degrades packet delivery ratios in Singapore and Hong Kong high-rises.
- JIS certification timelines:Japan's METI testing protocols for critical infrastructure IoT extend product approval cycles by 8-14 months versus regional peers.
Strategic Opportunities
- Philippine archipelago connectivity gaps:Island geography and sparse fiber infrastructure create addressable white space for satellite-LPWAN hybrid networks.
- Edge-to-core pipeline bundling:Manufacturing clients in Thailand's Eastern Economic Corridor seek unified data routing from plant gateways to cloud analytics.
- Australia agricultural water rights trading:Connected flow meters enable real-time usage verification for Murray-Darling Basin allocation markets.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers proficient in ultra-low-power RTOS coding constrains product development cycles across the region.
- Legacy SCADA integration complexity:Brownfield industrial sites in South Korea and Japan require protocol translation layers that inflate deployment costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Massive IoT Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Solution Type: Platform, Connectivity, Software, Device Management End User: Manufacturing, Smart Cities, Transportation, Healthcare Application: Asset Tracking, Predictive Maintenance, Smart Metering, Smart Agriculture |
| Companies Covered | Huawei Technologies, Samsung Electronics, Hitachi, Alibaba Cloud, Cisco Systems, Tata Consultancy Services, ZTE Corporation, Tuya Inc., KDDI Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Massive IoT Market Trends and Innovations
Modular hardware-software decoupling is fragmenting traditional integrated-stack contracts, while edge inference capabilities redistribute computational loads between field gateways and centralized infrastructure.
AI-accelerated sensor fusion at the network edge is electrifying predictive maintenance applications across Asia-Pacific manufacturing. Automotive and electronics plants in Malaysia and Thailand deploy vibration-acoustic-temperature combined sensing with on-device anomaly detection. This compression of inference latency from seconds to milliseconds enables real-time equipment shutdown before catastrophic failure.
Japan's METI has tightened JIS Q 15001 requirements for IoT devices handling critical infrastructure data, mandating hardware-backed secure boot and encrypted telemetry channels. Utilities in Tokyo and Osaka face compulsory retrofit timelines for existing AMI endpoints. Domestic vendors with pre-certified module libraries capture disproportionate share in replacement procurement cycles.
Factory operators now unbundle device management from connectivity contracts, selecting specialized platform vendors independent of network operators. South Korean chaebol manufacturing subsidiaries lead this disaggregation, negotiating separate agreements for sensor hardware, connectivity, and analytics software. The practice spreads fastest in semiconductor and battery cell production facilities where vendor lock-in risks outweigh procurement convenience.
Asia-Pacific Massive IoT Market Segmentation
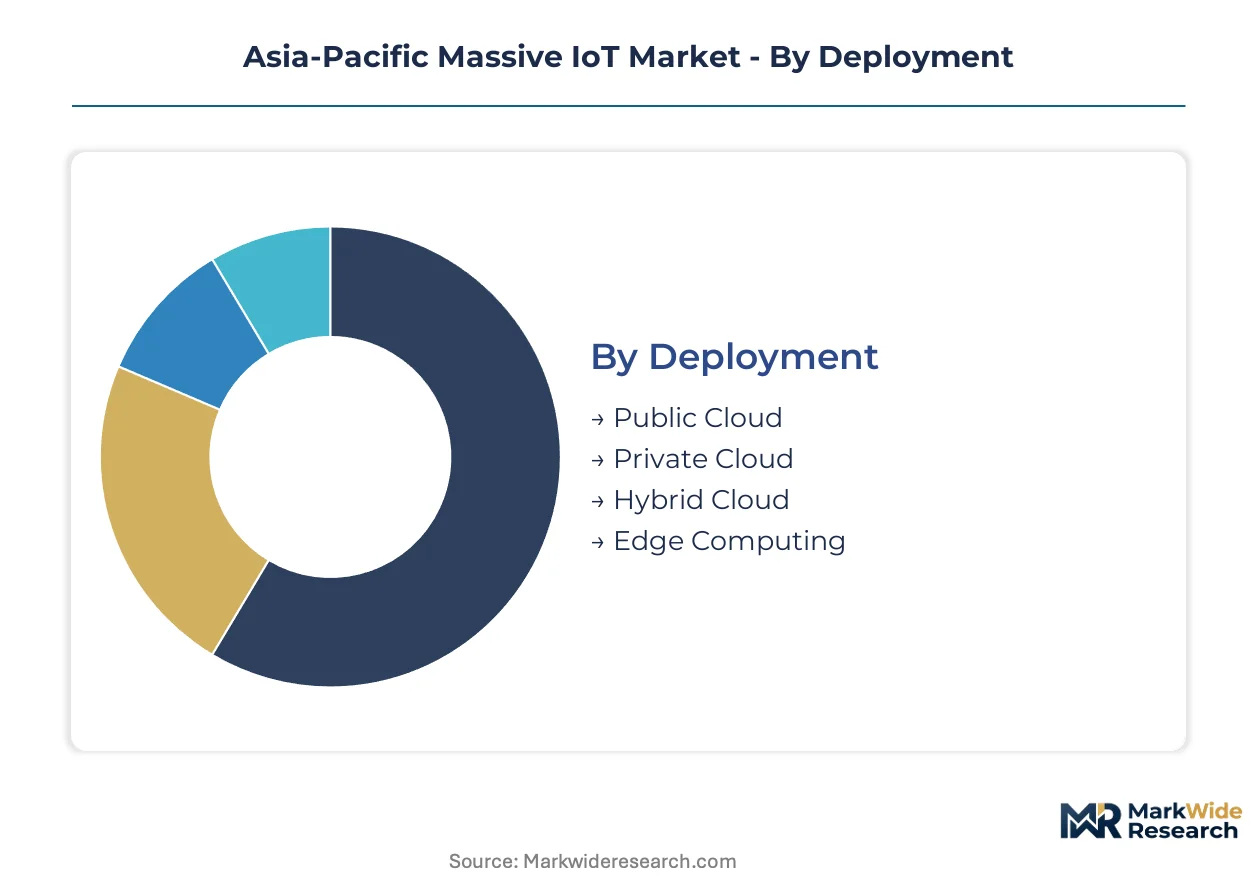
Massive IoT deployments fragment across infrastructure layers where recurring software margins diverge sharply from commoditized hardware. Segment boundaries shift as manufacturing clients unbundle integrated contracts and utilities mandate protocol-specific certifications.
Deployment:
Volume concentrates in standardized public configurations while premium workloads migrate to controlled environments.
- Public Cloud:Multi-tenant infrastructure serves smart agriculture telemetry and utility AMI backhauls where data sovereignty requirements remain permissive. Vietnam and Indonesia smallholder irrigation networks favor this tier for sub-dollar monthly per-node economics.
- Private Cloud:Dedicated infrastructure hosts semiconductor fab environmental monitoring and pharmaceutical cold chain tracking where GB standards or JIS certification mandate air-gapped telemetry. South Korean battery cell manufacturers anchor regional demand.
- Hybrid Cloud:Split architectures route non-critical telemetry to public tiers while retaining predictive inference on-premises. Thailand's Eastern Economic Corridor factories adopt this pattern for quality control video analytics.
- Edge Computing:Field gateways execute anomaly detection for Malaysia automotive press lines, compressing response latency below 50 milliseconds.
Today's leader: Public Cloud. Tomorrow's challenger: Edge Computing.
Solution Type:
Margin pools concentrate in recurring software layers that outearn one-time connectivity module sales.
- Platform:Unified device provisioning and data normalization layers capture the highest recurring margins across the stack. Alibaba Cloud and domestic Chinese vendors dominate manufacturing client procurement in the Yangtze River Delta.
- Connectivity:Narrowband modem provisioning and SIM lifecycle management face commoditization pressure as MIIT spectrum harmonization compresses hardware costs.
- Software:Analytics and visualization modules for predictive maintenance command premium pricing in Japan's METI-regulated critical infrastructure sectors.
- Device Management:Over-the-air firmware update and security patch distribution grows fastest as JIS Q 15001 mandates hardware-backed secure boot retrofits across Tokyo and Osaka utilities.
Platform solutions currently extract maximum value per connected node. Device Management is climbing the fastest as compliance-driven replacement cycles accelerate.
End User:
Demand clusters diverge between regulated utilities and price-sensitive agricultural operators.
- Manufacturing:Factory digitization programs in Gujarat and Tamil Nadu industrial corridors drive connected sensor density above 5,000 nodes per facility for vibration and acoustic monitoring.
- Smart Cities:Southeast Asian municipal deployments prioritize traffic signal optimization and waste bin fill monitoring where NB-IoT coverage reaches urban peripheries.
- Transportation:Fleet telematics and container tracking concentrate in Singapore and Hong Kong port logistics, though unlicensed band congestion degrades packet delivery in dense high-rise districts.
- Healthcare:Cold chain verification for vaccines and biologics expands fastest in Australia's regional distribution networks.
Manufacturing anchors current procurement volume. Smart Agriculture—captured under Application segmentation—expands most quickly outside formal end-user categories.
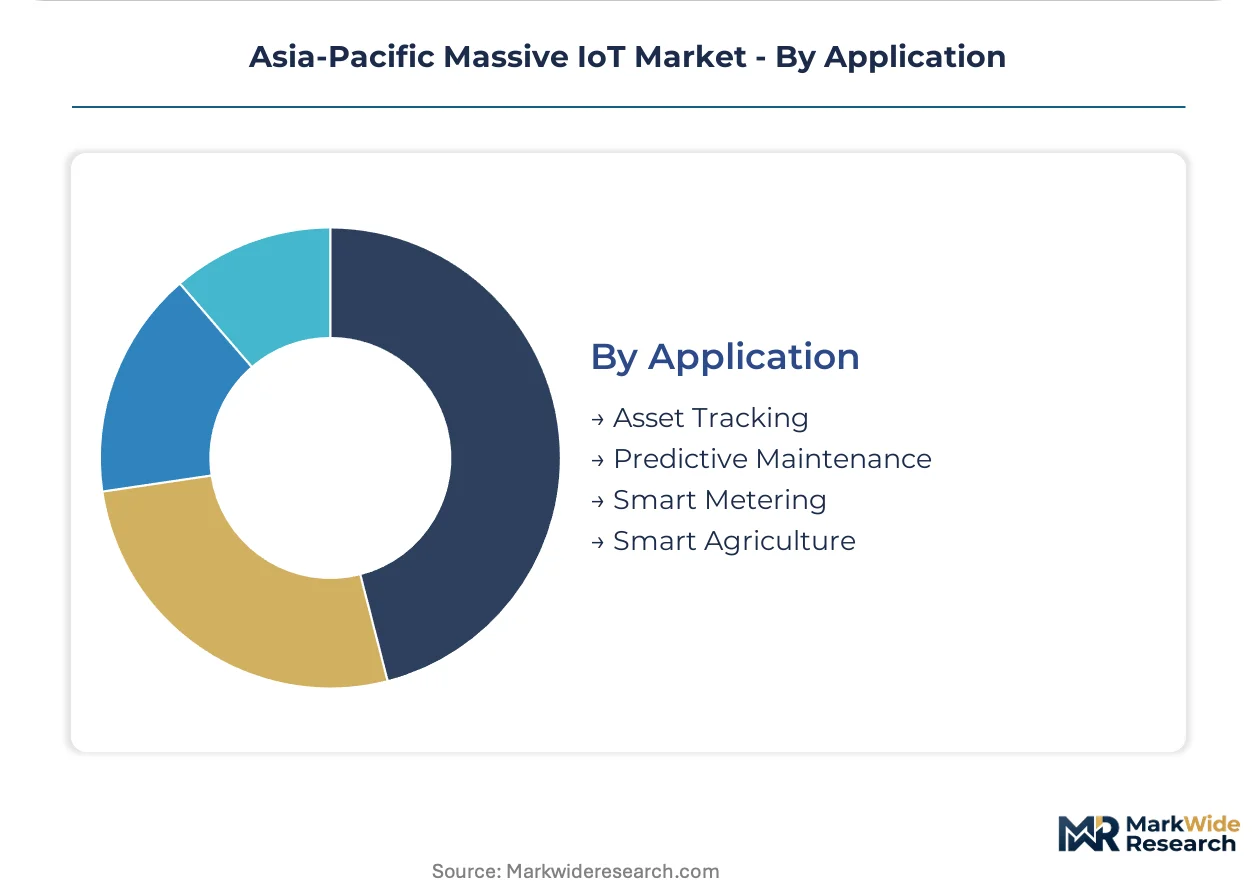
Application:
Maturity gradients separate established utility metering from nascent agricultural telemetry.
- Asset Tracking:Container and vehicle location monitoring leverages existing cellular infrastructure with minimal incremental capex. Philippine archipelago logistics operators trial satellite-LPWAN hybrids where fiber backhaul is absent.
- Predictive Maintenance:AI-accelerated sensor fusion combines vibration, acoustic, and thermal data at the network edge. Malaysia and Thailand automotive plants deploy this for real-time equipment shutdown before catastrophic failure.
- Smart Metering:AMI infrastructure in Northeast Asian utilities approaches saturation, though China's dual carbon mandates force industrial submetering retrofits across steel and cement facilities.
- Smart Agriculture:Soil moisture and connected irrigation controllers gain traction as sensor costs fall below smallholder farm economics in Vietnam and Indonesia. Murray-Darling Basin water rights trading in Australia drives flow meter deployments for real-time usage verification.
Smart Metering holds installed base dominance. Smart Agriculture follows the steepest expansion trajectory as hardware economics cross adoption thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massive IoT infrastructure first achieved commercial scale in Japan's utility sector during the 2010s, with smart metering deployments establishing the narrowband protocol templates later adopted across Asia-Pacific industrial corridors.
China
Factory digitization in the Yangtze River Delta drives sensor densities above 4,000 nodes per facility for vibration monitoring. MIIT spectrum harmonization for NB-IoT and LoRaWAN compresses module costs below mass-deployment thresholds. Shenzhen and Hangzhou anchor smart city rollouts where connected street lighting and waste management networks reach urban peripheries.
India
Industrial corridor programs in Gujarat and Tamil Nadu expand connected device footprints across automotive and textile plants. TRAI unlicensed LPWAN allocation for 865-867 MHz bands reduces network operator capex and accelerates rural sensor rollouts. Ahmedabad and Coimbatore cluster manufacturing demand where predictive maintenance contracts unbundle from integrated connectivity stacks.
Japan
Tokyo and Osaka utilities face compulsory AMI endpoint retrofits under tightened METI JIS Q 15001 requirements for hardware-backed secure boot. Domestic vendors with pre-certified module libraries capture disproportionate replacement procurement share. Nagoya automotive plants deploy edge inference for real-time equipment shutdown before catastrophic press-line failure.
South Korea
Semiconductor and battery cell production facilities lead contract unbundling, negotiating separate agreements for sensor hardware, connectivity, and analytics software. Busan-Ulsan industrial zones concentrate edge-to-core pipeline demand for quality control video analytics. National IoT certification protocols for critical infrastructure extend product approval cycles versus regional peers.
Australia
Murray-Darling Basin water rights trading drives connected flow meter deployments for real-time usage verification. Regional vaccine distribution networks expand cold chain verification for biologics. Sparse fiber infrastructure in Western Australia and Queensland creates addressable white space for satellite-LPWAN hybrid architectures.
Asia-Pacific Massive IoT Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the solution stack, with platform vendors capturing recurring software revenues while connectivity module suppliers face hardware commoditization. The vendor base organizes into three tiers: integrated infrastructure providers controlling chip-to-cloud verticals, specialized platform vendors unbundling device management from connectivity, and regional system integrators serving compliance-heavy utility procurements. Dominant competitive moves include strategic partnerships between cloud operators and national telecom carriers, plus portfolio diversification into edge computing gateways.
Within the integrated infrastructure tier, Huawei Technologies and ZTE Corporation occupy positions exemplifying captive silicon design and base station manufacturing. Samsung Electronics anchors the specialized platform segment through sensor fabrication and device management capabilities. Alibaba Cloud represents the public-cloud deployment archetype with edge-to-core data pipelines for manufacturing clients.
| Leading Market Players |
|---|
| Huawei Technologies |
| Samsung Electronics |
| Hitachi |
| Alibaba Cloud |
| Cisco Systems |
| Tata Consultancy Services |
| ZTE Corporation |
| Tuya Inc. |
| KDDI Corporation |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot indices and rare earth element benchmarks cascade through NB-IoT modem production into three distinct pricing tiers. Module vendors in Shenzhen and Seoul pass commodity volatility downstream to platform providers, while compliance-heavy Japanese utilities absorb certification premiums without volume elasticity.
Pricing Analysis
Subscription-tiered SaaS pricing stratifies across premium JIS-certified, standard METI-compliant, and economy unlicensed tiers. Price differentiation hinges on secure boot hardware mandates and volume scale across node counts. Cost compression in economy connectivity modules is intensifying because MIIT spectrum harmonization erodes hardware margins. Smallholder agricultural operators in Vietnam exhibit highest price sensitivity, whereas Tokyo utilities demonstrate lowest elasticity due to compulsory retrofit timelines.
Supply Chain Analysis
Dual-sourcing requirements from South Korean battery manufacturers and Japanese automotive OEMs mandate multi-foundry qualification for narrowband modem silicon. Concentration centers on Taiwan, South Korea, and mainland China for chipset fabrication. Raw material dependencies span silicon wafers, rare earth magnets for sensor assemblies, and lithium coin cells for decade-long battery targets. Single-source vulnerability concentrates in three foundries controlling narrowband silicon output. Distribution runs through regional telecom carriers and cloud platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where China's dual carbon mandates and Japan's JIS Q 15001 retrofits create compulsory replacement cycles independent of economic cycles.
For Market Incumbents: To counter unbundling pressure from South Korean manufacturing subsidiaries, anchor device management platforms with captive silicon design and pre-certified module libraries. Deepen backward integration into base station manufacturing to preserve margin pools as connectivity commoditizes. Prioritize certification investment in METI-regulated segments where approval timelines deter foreign entrants. For New Entrants and Emerging Players: Cloud-native platform routes offer lowest friction entry into Thailand's Eastern Economic Corridor, where factory digitization programs seek independent analytics vendors. Philippine archipelago connectivity gaps present the most penetrable white space for satellite-LPWAN hybrid architectures. Lead with edge-to-core pipeline bundling to displace integrated-stack incumbents in quality control video analytics. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized platform vendors possessing JIS pre-certified libraries and manufacturing client concentration in the Yangtze River Delta. Long-term viability favors vendors with recurring software margins exceeding hardware commoditization headwinds. Monitor spectrum harmonization negotiations between national regulators as the inflection signal for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Gateway Development | Compresses inference latency below 50 milliseconds for Malaysia automotive press lines. |
| JIS Q 15001 Certification Pre-Investment | Captures disproportionate Tokyo and Osaka utility replacement procurement share. |
| LoRaWAN-NB-IoT Dual-Mode Module Launch | Addresses unlicensed band congestion in Singapore and Hong Kong high-rises. |
| Smart Agriculture Platform Integration | Targets Vietnam and Indonesia smallholder irrigation below dollar-per-node economics. |
| Satellite-LPWAN Hybrid Partnership | Bridges Philippine archipelago fiber infrastructure gaps for logistics operators. |
Research Methodology
Bottom-up manufacturing deployment modeling reconciled against top-down chipset supply tracking forms the analytical core of this study. Primary interviews with IoT platform engineering directors, telecom carrier network planners, factory automation procurement leads, and regulatory compliance officers combined with secondary validation from MIIT spectrum filings, TRAI allocation notices, METI JIS documentation, and customs trade records. Top-down triangulation against module shipment data and cloud infrastructure capex disclosures anchored volume estimates.
Historical trendline analysis of narrowband protocol adoption curves and sensor cost depreciation trajectories informed projection parameters across the modeling period. Segmentation dimensions span deployment architecture, solution type layering, end-user industry concentration, and application maturity gradients. CAGRs derived from fitted growth curves adjusted for regulatory mandate timing and infrastructure buildout phases. Forecast inputs incorporate spectrum allocation decisions, foundry capacity expansion announcements, and utility AMI saturation thresholds.
Geopolitical friction in semiconductor supply chains, divergent national band plans, and embedded systems firmware talent scarcity are the dominant revision risks. Deviation in foundry concentration or spectrum harmonization outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
Internet of Things in Energy Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Indonesia IoT Market