
 Lora and Lorawan IoT Connectivity Market | 2026-2036
Lora and Lorawan IoT Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Lora and Lorawan IoT Connectivity Market Insights
Utility buyer concentration around smart metering rollouts is recalibrating procurement dynamics across the ecosystem. Semtech Corporation leverages its silicon dominance to anchor chipset supply for module vendors worldwide. Cisco Systems competes through enterprise gateway portfolios that extend from edge routing into managed LoRaWAN services. Orange SA controls one of Europe's largest public LoRaWAN footprints, positioning network coverage as a barrier against cellular IoT alternatives.
LoRa and LoRaWAN IoT connectivity encompasses long-range, low-power wireless communication protocols operating in sub-gigahertz unlicensed spectrum bands, typically at 868 MHz in Europe and 915 MHz in North America, with link budgets enabling 15-kilometer range in rural settings and deep indoor penetration for battery-operated sensors. This technology stack serves industrial asset monitoring, agricultural telemetry, and municipal infrastructure where cellular subscription costs and power constraints exclude conventional wide-area alternatives. Public network deployments currently dominate connectivity volumes, though private network installations for manufacturing facilities and critical infrastructure are expanding fastest as enterprises seek data sovereignty and guaranteed quality-of-service levels. Smart agriculture applications remain comparatively nascent in revenue contribution but carry outsized growth potential where cellular coverage gaps persist across remote cultivation zones.
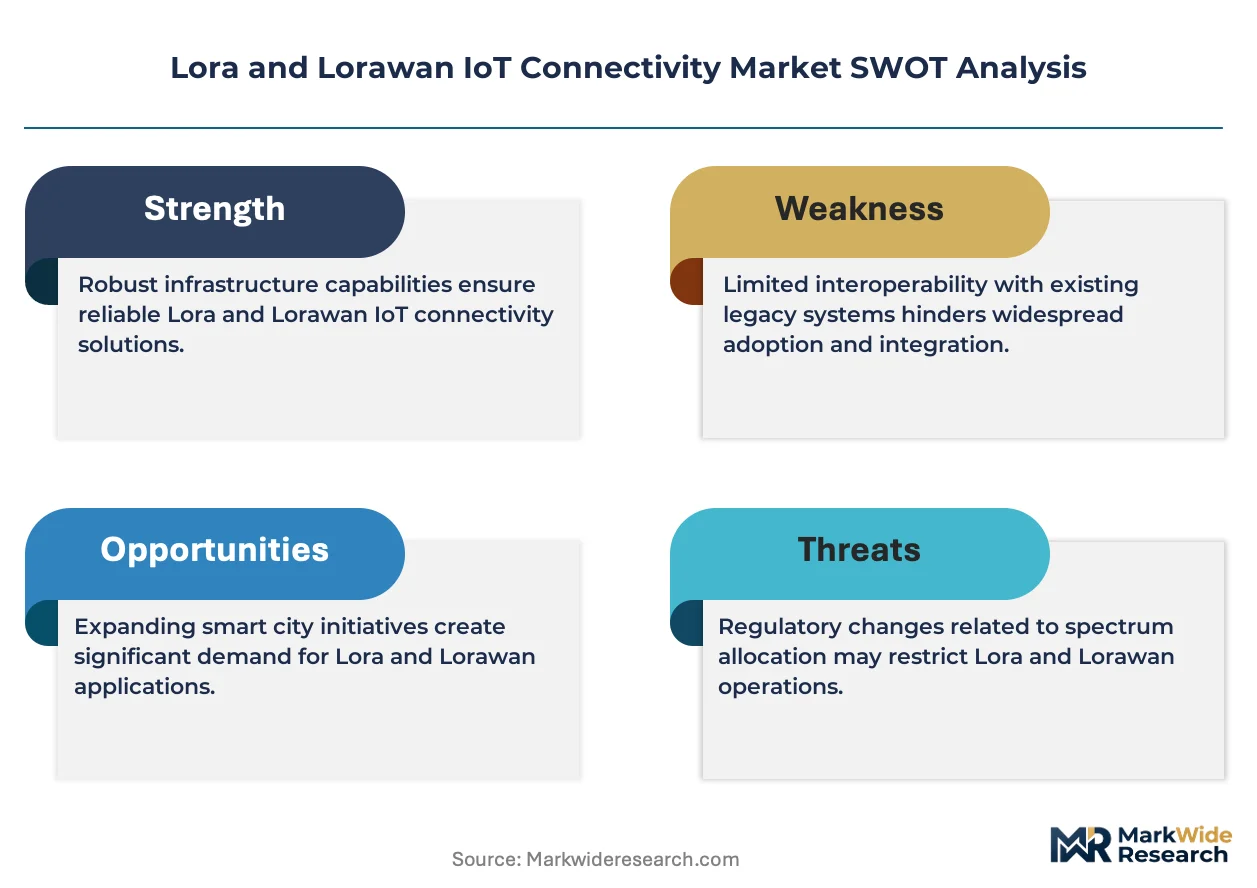
FCC Part 15 rules in the United States govern unlicensed spread-spectrum operation and directly shape permissible duty cycles and power levels for LoRa devices entering the North American market. ETSI EN 300 220 standards in Europe enforce listen-before-talk protocols and spectrum access restrictions that manufacturers must satisfy for CE marking and lawful commercialization. Stakeholders must monitor evolving national spectrum reallocations and cybersecurity certification mandates that will determine which hardware architectures achieve sustainable market access across jurisdictions.
Market Dynamics
Utility-scale smart metering deployments in Germany and France are compressing procurement cycles and forcing module vendors to pre-certify hardware against evolving cybersecurity mandates before tender participation.
Growth Catalysts
- EU Cybersecurity Act:Mandatory certification schemes for IoT devices are creating compliant-hardware shortages that favor early-certifying module manufacturers with established testing partnerships.
- Industrial predictive maintenance:German automotive and machinery plants are deploying private LoRaWAN networks for vibration monitoring, bypassing cellular latency constraints and subscription costs.
- Sub-gigahertz spectrum efficiency:LoRa's chirp spread-spectrum modulation enables 15-kilometer rural coverage and deep indoor penetration, opening agricultural telemetry applications where cellular infrastructure remains uneconomical.
Market Restraints
- Silicon supply concentration:Semtech Corporation's dominance in LoRa chipset production creates single-source vulnerability for module vendors across Europe and North America.
- ETSI EN 300 220 compliance costs:European listen-before-talk and duty-cycle restrictions extend hardware development timelines and require specialized RF engineering capabilities.
- Cellular LPWAN substitution:NB-IoT and LTE-M price compression by mobile network operators threatens public LoRaWAN network economics in urban deployments with existing cellular coverage.
Strategic Opportunities
- Private network sovereignty:French and German critical infrastructure operators are procuring standalone LoRaWAN core networks to ensure data residency and guaranteed quality-of-service for energy distribution monitoring.
- Agricultural telemetry expansion:Remote cultivation zones in Spain and Italy present white-space opportunities where cellular coverage gaps persist and solar-powered sensor networks enable irrigation optimization.
- CE marking acceleration:Module vendors with pre-certified radio equipment directive compliance are capturing municipal smart-city tenders before competitors complete notified body assessments.
Industry Challenges
- RF engineering talent scarcity:Sub-gigahertz antenna design and propagation modeling expertise concentrates among legacy telecommunications specialists, constraining vendor scaling.
- Multi-protocol integration complexity:Enterprise buyers demand seamless interoperability between LoRaWAN sensors and existing SCADA or cloud platforms, extending deployment timelines.
- Cybersecurity certification bottlenecks:EU Common Criteria evaluations for critical infrastructure applications face 12-18 month backlogs at notified bodies, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lora and Lorawan IoT Connectivity Market |
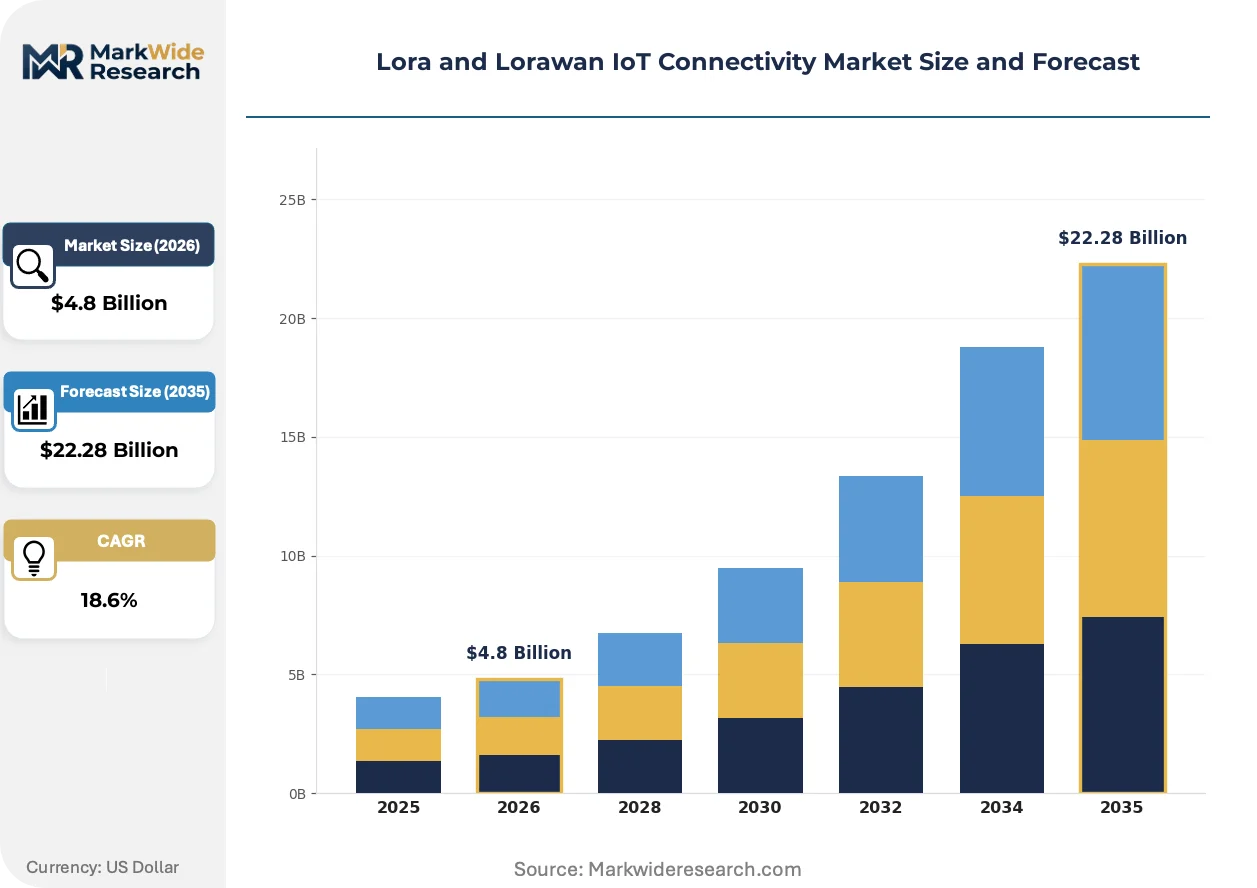
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lora, Lorawan, Sigfox, NB-IoT Deployment Model: Public Network, Private Network, Hybrid Network, On-Premises Application: Smart Agriculture, Smart Cities, Asset Tracking, Environmental Monitoring Industry Vertical: Healthcare, Transportation, Utilities, Manufacturing |
| Companies Covered | Semtech Corporation, Cisco Systems, Orange SA, Robert Bosch GmbH, Advantech Co., Ltd., NEC Corporation, Senet, MultiTech Systems, Akenza AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lora and Lorawan IoT Connectivity Market Trends and Innovations
LoRaWAN protocol evolution and edge computing integration are compressing data latency and enabling autonomous local decision-making that reduces backhaul dependency for industrial applications.
LoRaWAN 1.1 and Regional Parameters 1.0.3 are unifying end-device roaming, fragmented downlink scheduling, and standardized multicast capabilities across national network operators. Municipal utilities in France and the Netherlands are migrating to these specifications to enable cross-border asset tracking without gateway reconfiguration. This unification is compressing vendor differentiation around proprietary MAC-layer extensions and forcing module suppliers toward standardized firmware stacks.
ETSI EN 303 645 cybersecurity requirements for consumer IoT are extending into industrial equipment categories through national implementation acts in Germany and France. Hardware manufacturers must now embed secure boot, signed firmware updates, and entropy sources for cryptographic operations. Industrial sensor vendors serving energy and water utilities face the steepest compliance ramps as critical infrastructure designation triggers enhanced oversight from national cybersecurity agencies.
Buyer aggregation through utility-led consortiums is displacing fragmented municipal procurement across European smart-city deployments. French water authorities and German distribution system operators are consolidating sensor purchases into framework agreements that specify interoperability certifications and multi-year service level commitments. This concentration is visible most acutely in street lighting and waste container monitoring tenders where single-vendor network management contracts now span multiple municipalities.
Lora and Lorawan IoT Connectivity Market Segmentation
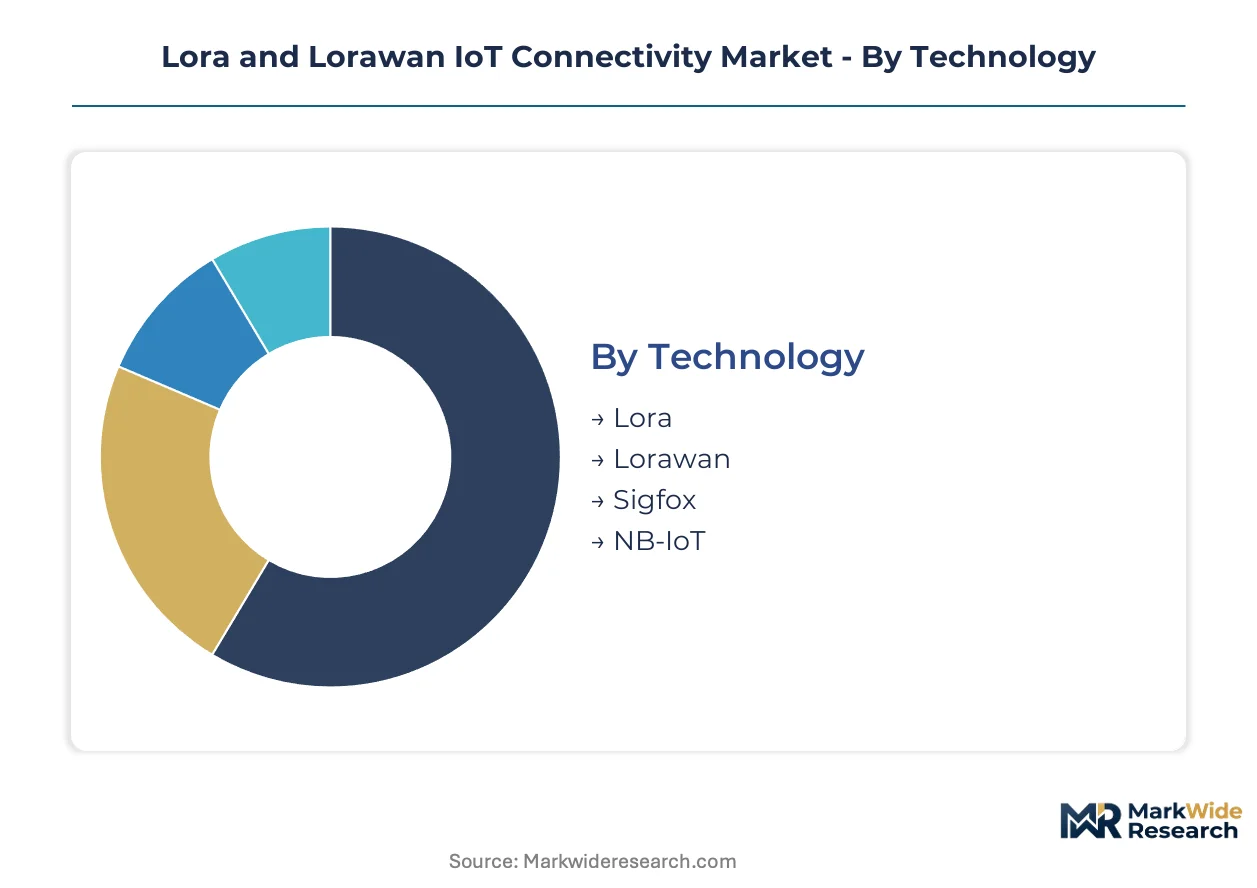
Segmentation in LoRa and LoRaWAN IoT connectivity reveals distinct procurement patterns across spectrum access methods and infrastructure ownership models. Buyers prioritize deployment flexibility against total cost of ownership when selecting between public subscription services and private network sovereignty.
Technology:
Standardization intensity varies sharply across this category, from proprietary modulation schemes to open protocol specifications governed by industry alliances.
- Lora:Chirp spread-spectrum modulation technology from Semtech Corporation enables long-range transmission at sub-gigahertz frequencies with minimal power draw. German industrial sensor manufacturers specify LoRa PHY layers for vibration monitoring equipment in automotive plants where battery life spans 10-plus years.
- Lorawan:Open network protocol stack standardizing MAC-layer operations, security frameworks, and backend interoperability across vendor ecosystems. French municipal utilities mandate LoRaWAN certification for smart street lighting tenders to ensure multi-supplier compatibility.
- Sigfox:Proprietary ultra-narrowband technology operated through subscription-based network services with simplified device requirements.
- NB-IoT:Cellular-licensed narrowband standard specified by 3GPP, deployed by mobile operators over existing LTE infrastructure with quality-of-service guarantees.
Leading the category by volume: LoRa physical layer chipsets. Expanding most quickly: LoRaWAN protocol implementations for enterprise private networks.
Deployment Model:
Infrastructure ownership economics drive segmentation here, with capital expenditure tolerance separating utility-scale buyers from commercial facility operators.
- Public Network:Subscription-based connectivity through national operators like Orange SA or regional consortiums, eliminating gateway infrastructure investment. French water authorities leverage public LoRaWAN coverage for rural meter reading where private deployment costs prove prohibitive.
- Private Network:Dedicated gateway installations with standalone core servers ensuring data residency and guaranteed service levels. German energy distribution operators procure private LoRaWAN networks for substation monitoring under BSI cybersecurity guidelines.
- Hybrid Network:Combination architectures using private gateways for critical sites with public network fallback for mobile assets.
- On-Premises:Fully air-gapped installations with no external connectivity, satisfying critical infrastructure isolation requirements.
Public networks dominate connection volumes currently. Private installations gain share fastest among manufacturing and energy verticals.
Application:
Use-case maturity determines specification rigor, with established municipal deployments contrasting against emerging agricultural implementations.
- Smart Cities:Integrated municipal systems spanning street lighting control, waste container fill-level monitoring, and parking occupancy detection. Dutch municipalities specify interoperable LoRaWAN sensors for multi-city framework agreements consolidating procurement.
- Asset Tracking:Location and condition monitoring for mobile industrial equipment, shipping containers, and vehicle fleets. German logistics operators deploy battery-powered trackers for railcar monitoring across trans-European routes.
- Smart Agriculture:Soil moisture, microclimate, and livestock monitoring in remote cultivation zones. Spanish irrigation cooperatives pilot solar-powered sensor networks where cellular coverage gaps persist.
- Environmental Monitoring:Air quality, water level, and noise pollution sensors for regulatory compliance and public health applications.
Smart city deployments lead by installed base. Agricultural telemetry climbs the fastest as sensor economics improve for distributed cultivation.
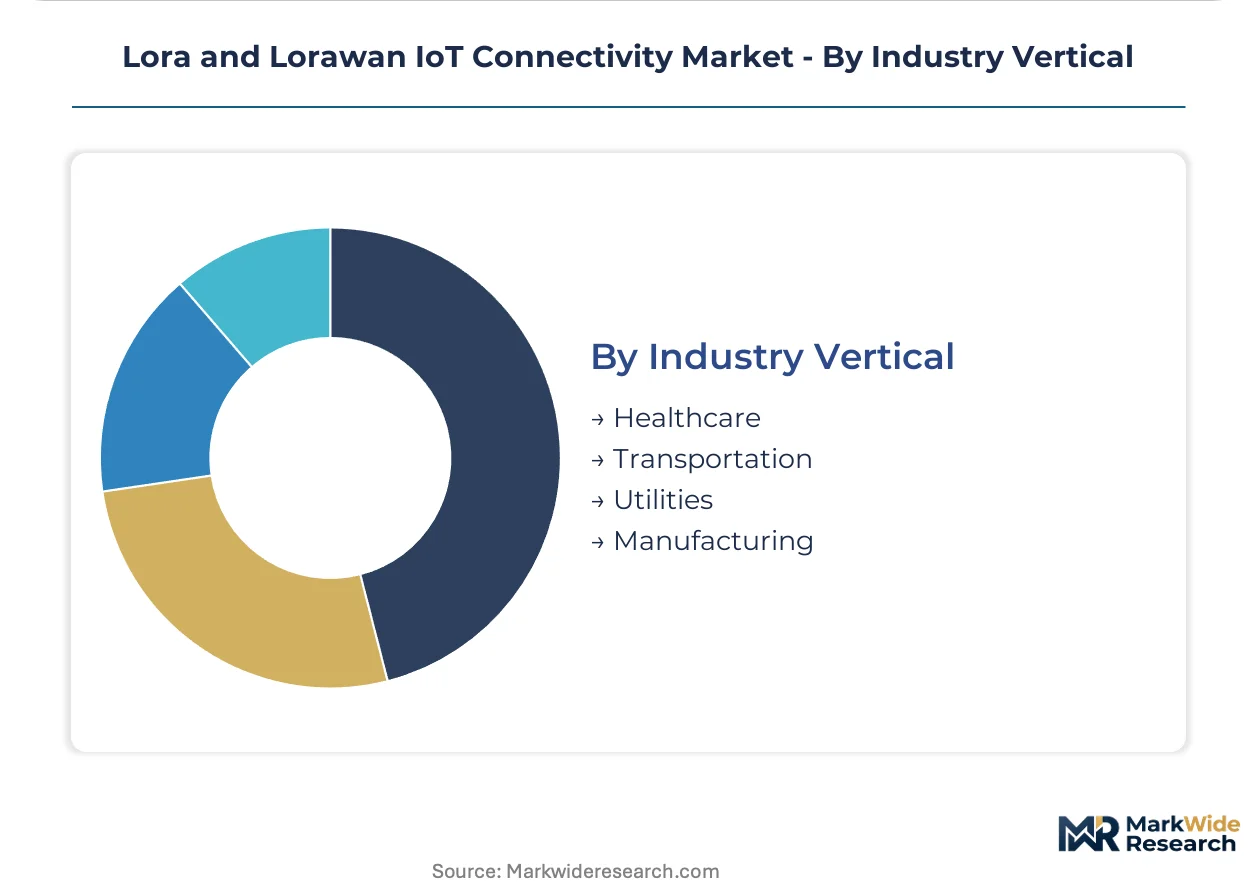
Industry Vertical:
Regulatory exposure and operational criticality shape vertical adoption patterns, with infrastructure operators outpacing consumer-facing sectors.
- Utilities:Electricity, gas, and water metering infrastructure with stringent cybersecurity certification requirements. German distribution system operators mandate Common Criteria evaluations for LoRaWAN gateways under BSI technical guidelines.
- Manufacturing:Predictive maintenance, energy submetering, and environmental condition monitoring in production facilities. Automotive plants in Bavaria deploy private LoRaWAN networks for machine vibration analysis bypassing cellular latency constraints.
- Transportation:Fleet management, cargo condition monitoring, and infrastructure condition sensing for rail and road networks.
- Healthcare:Medical device tracking, cold chain monitoring, and facility environmental control with HIPAA or GDPR compliance overlays.
Utilities vertical leads by hardware procurement value. Manufacturing segment shows steepest expansion trajectory for private network installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale deployments in Germany and France concentrate procurement volumes for LoRaWAN hardware, while industrial automation and smart city mandates across five countries reshape regional connectivity economics.
Germany
Distribution system operators and automotive manufacturers drive private network installations for predictive maintenance and substation monitoring. BSI technical guidelines mandate Common Criteria evaluations for critical infrastructure gateways. Bavarian automotive plants deploy standalone LoRaWAN cores for machine vibration analysis, bypassing cellular latency constraints entirely.
France
Municipal utilities and water authorities consolidate sensor purchases through multi-city framework agreements for street lighting and waste management. ANSM cybersecurity oversight extends into industrial IoT categories through national implementation acts. The Paris metropolitan region anchors procurement for interoperable smart city infrastructure spanning multiple municipalities.
Netherlands
Regional water boards and agricultural cooperatives pilot solar-powered sensor networks for irrigation optimization and flood monitoring. CE marking requirements under the Radio Equipment Directive govern module certification timelines. The Randstad conurbation concentrates smart city deployments with cross-border roaming specifications for trans-European asset tracking.
Spain
Irrigation cooperatives in remote cultivation zones deploy telemetry where cellular coverage gaps persist and solar economics improve sensor viability. ETSI EN 300 220 spectrum access restrictions shape hardware development for listen-before-talk compliance. Andalusian agricultural clusters lead pilot programs for soil moisture and microclimate monitoring networks.
United States
Industrial facilities and utilities deploy private networks for data sovereignty and guaranteed quality-of-service in manufacturing and energy distribution. FCC Part 15 rules govern unlicensed spread-spectrum operation and permissible duty cycles for sub-gigahertz devices. The Pacific Northwest and Texas industrial corridors concentrate gateway installations for critical infrastructure isolation requirements.
Lora and Lorawan IoT Connectivity Market Competitive Landscape
North American technology providers anchor one tier of the competitive structure; European telecommunications and industrial specialists hold differentiated positions around network operations and vertical integration. The vendor base separates into chipset suppliers, gateway manufacturers, and managed service operators with limited overlap between tiers. Three strategic archetypes dominate: silicon-anchored technology licensors, enterprise infrastructure providers, and national network operators. Competitive moves concentrate on pre-certification against evolving cybersecurity mandates and framework agreement positioning for utility consortium procurement.
Within the chipset-dominant tier, Semtech Corporation occupies a foundational position as the physical layer technology source for module vendors worldwide. Cisco Systems exemplifies the enterprise infrastructure archetype through edge gateway portfolios extending into managed connectivity services. Orange SA represents the national operator model, controlling public network coverage as a barrier against cellular IoT alternatives. These three entities anchor distinct competitive vectors without direct overlap in core competencies.
| Leading Market Players |
|---|
| Semtech Corporation |
| Cisco Systems |
| Orange SA |
| Robert Bosch GmbH |
| Advantech Co., Ltd. |
| NEC Corporation |
| Senet |
| MultiTech Systems |
| Akenza AG |
| Others |
Pricing and Supply Chain Analysis
RF engineering talent scarcity in Southern Germany widens pricing spreads between premium-certified modules and economy-tier alternatives, as labor-cost differentials for sub-gigahertz antenna design propagate through finished-goods quotations.
Pricing Analysis
Volume concentration in utility-scale smart metering compresses margins for standard-tier module suppliers while premium-certified hardware retains pricing power. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity certification grade and volume commitment scale. Cost compression in economy tiers intensifies because cellular LPWAN substitution pressures public network economics. Municipal utilities exhibit highest price sensitivity; critical infrastructure operators prioritize guaranteed quality-of-service over unit cost.
Supply Chain Analysis
End-of-life gateway refurbishment flows from German industrial facilities into secondary markets across Eastern Europe, extending asset utilization cycles and compressing replacement demand. Silicon sourcing concentrates in the United States, Taiwan, and China, with LoRa PHY layer chipsets drawing from Semtech Corporation's captive production. Supply chain risk centers on single-source vulnerability for sub-gigahertz radio front-ends. Distribution runs through module vendor direct sales for private networks and national operator channels for public subscription services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where chipset-to-module control determines margin capture, with upstream silicon access serving as the decisive lever players are pursuing.
For Market Incumbents: To counter cellular LPWAN price compression by mobile network operators, secure exclusive supply agreements with Semtech Corporation for LoRa chipset allocation and accelerate Common Criteria pre-certification at German BSI-notified bodies to lock in utility framework agreements. For New Entrants and Emerging Players: EU Cybersecurity Act implementation in France opens a window for module vendors with established testing partnerships to capture municipal smart-city tenders before competitors complete notified body assessments, targeting agricultural telemetry in Spanish irrigation cooperatives where cellular coverage gaps persist. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated gateway manufacturers given private network sovereignty demand from German energy distribution operators, with acquisition focus on firms holding pre-certified radio equipment directive compliance. Signal to watch: BSI technical guideline revisions for critical infrastructure gateway specifications.| Strategic Initiative | Industry Significance |
|---|---|
| LoRa Chipset Supply Agreement | Exclusive silicon allocation from Semtech Corporation secures module production capacity against competitor rationing. |
| CE Marking Pre-Certification | Accelerated Radio Equipment Directive compliance captures French municipal tenders before rival completion. |
| Private Network Core Deployment | Standalone LoRaWAN infrastructure satisfies German BSI cybersecurity guidelines for critical infrastructure. |
| Agricultural Telemetry Pilot | Solar-powered sensor networks exploit cellular coverage gaps in Spanish irrigation cooperatives. |
| RF Engineering Talent Acquisition | Sub-gigahertz antenna design specialists in Southern Germany constrain competitor scaling velocity. |
Research Methodology
Multi-period observation of module vendor certification timelines, utility tender award patterns, and chipset allocation dynamics anchored the trend analysis, supplemented by interviews with LoRaWAN gateway procurement officers at German distribution system operators, RF engineering directors at French module manufacturers, municipal smart-city project managers in the Netherlands, and agricultural cooperative technology leads in Spain. Secondary validation drew from ETSI EN 300 220 regulatory filings, BSI technical guideline publications, EU Cybersecurity Act implementation notices, and Semtech Corporation supply disclosure statements. Bottom-up unit shipment estimates triangulated against top-down connectivity revenue projections.
Input-output matrices mapped deployment model penetration against application vertical adoption rates across the analysis window. Segmentation dimensions modeled include technology layer, infrastructure ownership model, use-case maturity, and industry vertical regulatory exposure. CAGRs derived from logistic diffusion curves fitted to historical smart meter installation data and extrapolated using industrial automation capital expenditure intentions. Forecast inputs incorporated spectrum reallocation risk probabilities and cybersecurity certification backlog durations at notified bodies.
The model assumes a particular technology adoption path; alternative pathways for cellular LPWAN substitution would alter the outlook for public network connection volumes. Forecasts reflect assumptions regarding EU member state implementation timelines for EN 303 645 cybersecurity requirements and Semtech Corporation's foundry capacity allocation priorities. Practitioners should monitor BSI technical guideline revisions, French ANSM cybersecurity oversight extensions, and ETSI spectrum access rule amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Cellular M2M Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Industrial IoT Platform Market