
 IoT Technology Market | 2026-2036
IoT Technology Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Technology Market Outlook
Healthcare providers is recalibrating their procurement priorities toward remote patient monitoring platforms as telemedicine infrastructure matures. Qualcomm Technologies leverages its cellular modem leadership to dominate medical-grade connectivity modules. Cisco Systems anchors enterprise IoT security architectures through its networking hardware and software integration. IBM competes in predictive analytics for hospital asset management using its Watson IoT platform.
IoT technology encompasses networked sensor arrays, embedded processors, wireless communication protocols, and cloud analytics platforms that collect, transmit, and process operational data from physical environments. Industrial deployments typically operate across sub-gigahertz to 5G spectrum bands with latency requirements spanning ten milliseconds to near-real-time thresholds depending on safety-criticality. Smart Home Devices represents a mature revenue pool where margin compression has intensified amid commoditized hardware. Edge Computing deployment architectures capture the fastest structural expansion as manufacturing firms process telemetry locally to minimize cloud egress costs and latency exposure. Environmental Monitoring Systems occupies a specialized niche serving agriculture sector clients with soil, water, and atmospheric sensing arrays.
The FCC governs spectrum allocation for unlicensed IoT bands in the United States, while the EU AI Act imposes conformity requirements on autonomous decision-making systems embedded in connected infrastructure. ETSI standards for low-power wide-area networks shape interoperability and market access conditions across European deployments. Stakeholders must monitor evolving cybersecurity certification mandates and spectrum reallocation proceedings to anticipate compliance costs and connectivity optionality.
Market Dynamics
Edge computing architectures are displacing cloud-centric telemetry models as manufacturing firms prioritize latency reduction and data sovereignty compliance. This infrastructure pivot concentrates capital deployment around Stuttgart and Munich industrial corridors while reshaping vendor competitive positions.
Growth Catalysts
- EU AI Act Conformity Requirements:Mandatory algorithmic transparency for autonomous IoT systems is accelerating certified platform procurement across German automotive and French healthcare networks.
- 5G Private Network Deployment:Manufacturing facilities in Japan and South Korea are commissioning dedicated spectrum slices for deterministic machine-to-machine communication.
- Soil Sensing Arrays:Agricultural cooperatives in the Netherlands are expanding precision irrigation telemetry to comply with EU Water Framework Directive conservation mandates.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundry capacity constraints limit embedded processor availability for industrial sensor manufacturers.
- GDPR Cross-Border Data Friction:Telemetry routing restrictions complicate multi-national fleet management platform architectures.
- Sub-Gigahertz Interference Saturation:Unlicensed spectrum congestion in dense European urban deployments degrades LPWAN reliability thresholds.
Strategic Opportunities
- India Smart Grid Modernization:Rural electrification programs are creating demand for distributed grid monitoring endpoints with localized analytics.
- Brazilian AgTech Expansion:Soybean and sugarcane operations are adopting satellite-linked soil moisture networks to optimize water application.
- Digital Twin Convergence:Integration of physics-based simulation with real-time sensor feeds is opening predictive maintenance contracts in German chemical processing.
Industry Challenges
- Embedded Security Engineering Scarcity:Firmware hardening expertise for resource-constrained devices commands premium compensation and extends development timelines.
- Multi-Protocol Certification Burden:Devices must validate against ETSI, FCC, and MIC radio standards simultaneously for cross-border deployment eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Technology Market |
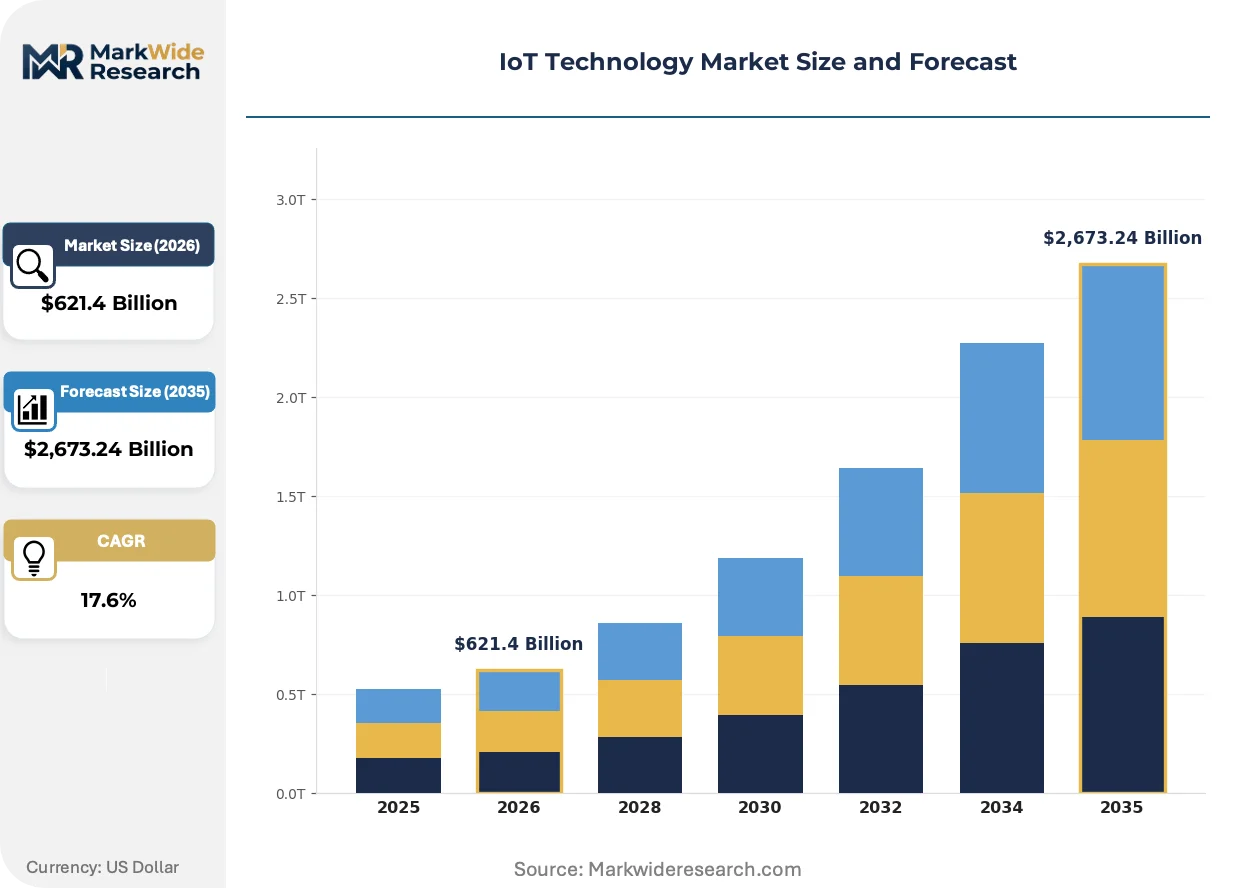
| Market Size in 2026 | $621.4 Billion |
| Market Size in 2035 | $2,673.24 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Smart Home Devices, Industrial IoT Solutions, Environmental Monitoring Systems Deployment: On-Premises, Cloud, Hybrid, Edge Computing End User: Healthcare Providers, Manufacturing Firms, Retailers, Agriculture Sector Application: Asset Tracking, Smart Lighting, Predictive Maintenance, Remote Monitoring |
| Companies Covered | Intel Corporation, Qualcomm Technologies, Inc., Texas Instruments Incorporated, Cisco Systems, Inc., Microsoft, IBM, Amazon Web Services, Huawei Technologies Co. Ltd., STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Technology Market Strategic Shifts
Telemetry processing is migrating toward network peripheries as bandwidth economics and latency requirements reshape architectural decisions. This decentralization pattern favors specialized hardware vendors while compressing margins for pure cloud analytics providers.
Digital twin software is expanding into predictive asset management across German chemical and pharmaceutical manufacturing sites. BASF and Bayer facility operators are deploying physics-based simulation layers fed by vibration and thermal sensor arrays. This convergence is compressing maintenance contract value pools toward integrated platform vendors capable of delivering both hardware and simulation licensing.
EU AI Act algorithmic transparency mandates are forcing embedded system architects to document decision pathways for autonomous industrial controllers. German automotive suppliers must now maintain conformity dossiers for quality-control vision systems. Medical device manufacturers in Ireland and the Netherlands are responding by segregating AI-enabled diagnostic functions onto separately certifiable hardware modules.
Hospital procurement departments are consolidating telemetry vendor relationships around platforms delivering remote patient monitoring and asset tracking through unified dashboards. This concentration pattern displaces point-solution specialists in favor of enterprise networking incumbents with established security credentialing. The shift is most visible in US health systems pursuing Medicare reimbursement optimization through reduced readmission rates.
IoT Technology Market Segmentation
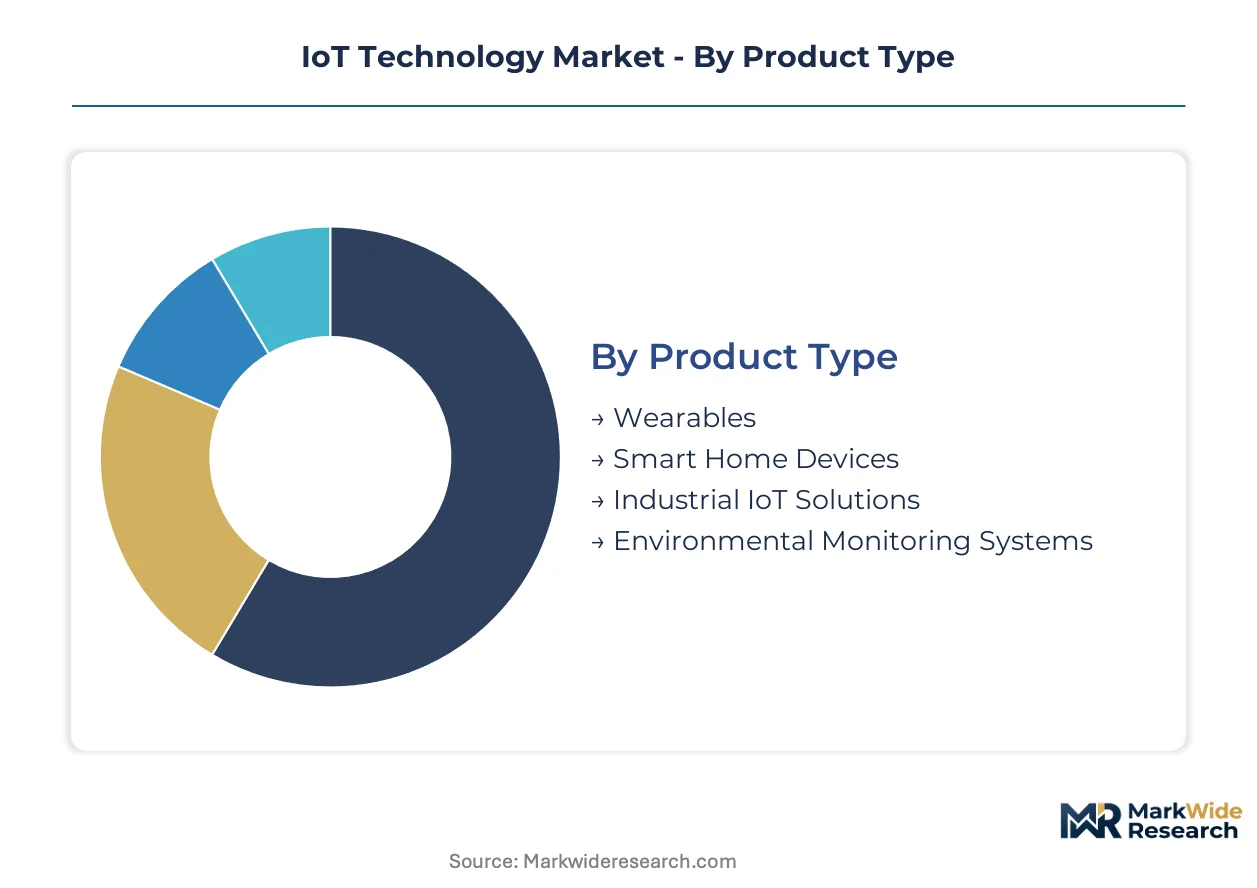
Segmentation in IoT technology reflects divergent latency requirements, security postures, and data sovereignty mandates across vertical deployments. Each axis reveals distinct vendor competitive dynamics and procurement decision criteria.
Product Type:
Hardware form factors differentiate by processing capability, power envelope, and environmental hardening specifications.
- Industrial IoT Solutions:Ruggedized sensor arrays and embedded controllers operate across sub-gigahertz to 5G spectrum bands with deterministic latency guarantees. German automotive suppliers around Stuttgart anchor procurement volume as production line digitization accelerates under EU AI Act conformity timelines.
- Smart Home Devices:Consumer-grade connected appliances and security systems leverage Wi-Fi and Thread protocols for residential automation. Margin compression has intensified amid commoditized hardware, though Matter certification is reshaping interoperability premiums.
- Wearables:Biometric-enabled wrist and body-worn devices transmit physiological telemetry through Bluetooth Low Energy. Healthcare systems in the Netherlands prioritize FDA-cleared units for remote patient monitoring reimbursement eligibility.
- Environmental Monitoring Systems:Soil, water, and atmospheric sensing arrays serve precision agriculture with satellite backhaul. Dutch agricultural cooperatives expand deployments to satisfy EU Water Framework Directive conservation mandates.
Mature deployment sits with Smart Home Devices. Newer deployment is concentrated in Industrial IoT Solutions.
Deployment:
Infrastructure topology selection hinges on bandwidth economics, regulatory data residency requirements, and safety-critical response thresholds.
- Edge Computing:Localized processing nodes execute telemetry analytics within manufacturing facility boundaries to minimize cloud egress costs and GDPR cross-border friction. German chemical processors in Ludwigshafen prioritize edge architectures for predictive maintenance latency requirements.
- Cloud:Centralized data lake architectures aggregate multi-site sensor feeds for longitudinal pattern recognition. Retail chains favor cloud deployment for inventory optimization across distributed store footprints despite recurring subscription exposure.
- Hybrid:Tiered processing splits time-sensitive control loops to edge nodes while archiving historical telemetry to cloud repositories. Hospital networks adopt hybrid models to segregate patient-identifiable data under HIPAA jurisdiction from anonymized operational analytics.
- On-Premises:Air-gapped server infrastructure maintains complete data sovereignty within facility perimeters. Defense contractors and critical infrastructure operators mandate on-premises deployment for classified or safety-critical control systems.
Established footprint dominates Cloud deployment. Steepest expansion trajectory belongs to Edge Computing.
End User:
Procurement sophistication varies by vertical maturity, regulatory exposure, and available capital expenditure pools.
- Manufacturing Firms:Discrete and process manufacturers deploy machine vision, vibration sensing, and digital twin infrastructure for quality assurance and asset optimization. Japanese automotive plants commission 5G private networks for deterministic machine-to-machine coordination.
- Healthcare Providers:Hospital systems consolidate remote patient monitoring and asset tracking platforms to optimize Medicare reimbursement through reduced readmission rates. Procurement departments favor vendors with unified security credentialing over point-solution specialists.
- Agriculture Sector:Large-scale farming operations and agricultural cooperatives adopt precision irrigation and yield monitoring telemetry. Brazilian soybean producers deploy satellite-linked soil moisture networks to optimize water application amid climate variability.
- Retailers:Omnichannel merchants instrument supply chain and customer experience touchpoints with RFID and environmental sensors. Cold chain monitoring for perishable inventory drives refrigerated logistics investment.
Capital deployment concentrates with Manufacturing Firms. Procurement velocity is climbing fastest among Healthcare Providers.
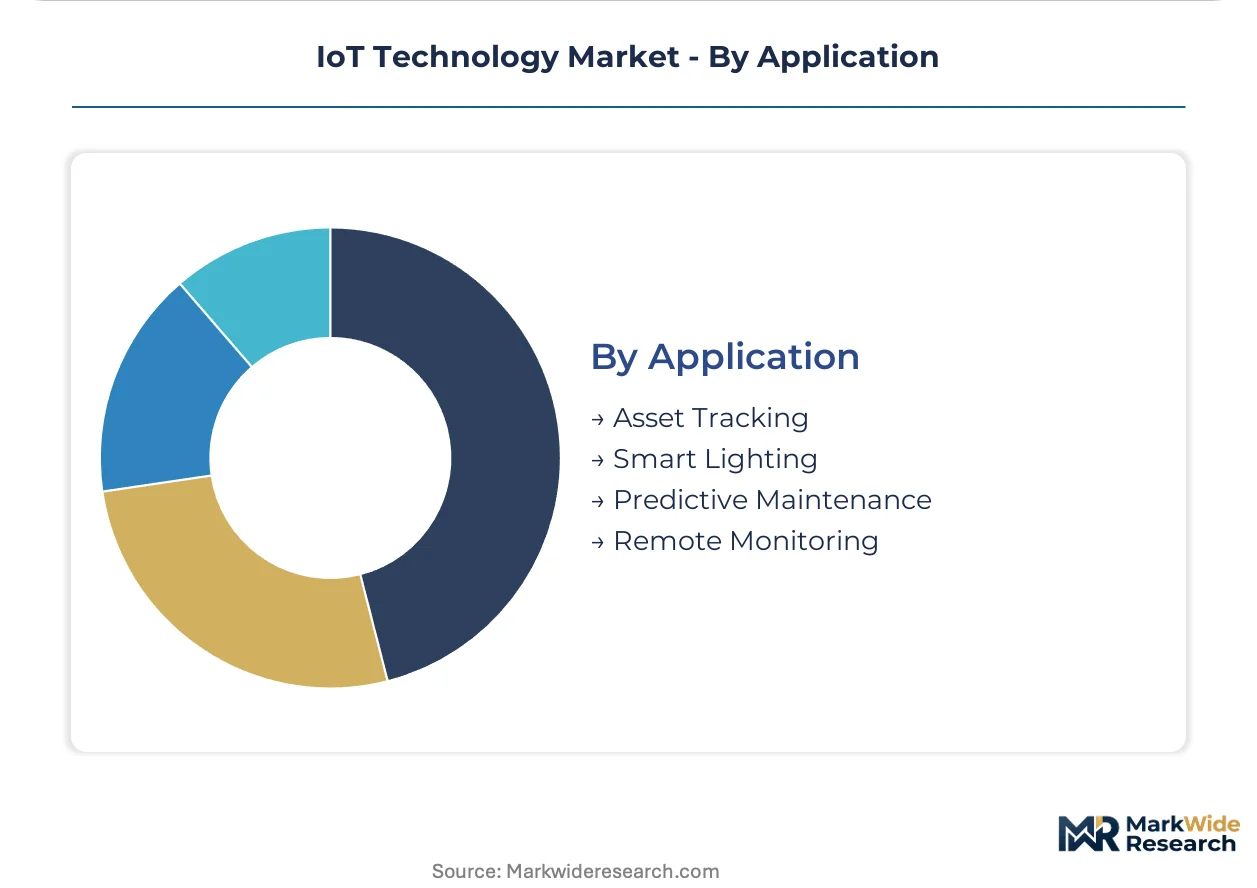
Application:
Use case prioritization reflects operational pain points, measurable ROI horizons, and integration complexity with legacy infrastructure.
- Predictive Maintenance:Vibration, thermal, and acoustic sensor fusion enables failure anticipation before catastrophic asset downtime. German chemical processors at BASF and Bayer facilities integrate physics-based simulation with real-time feeds for maintenance contract optimization.
- Remote Monitoring:Continuous telemetry from dispersed assets or patients reduces site visit frequency and enables early intervention. US health systems pursue Medicare reimbursement optimization through reduced hospital readmission rates.
- Asset Tracking:Location and condition monitoring for mobile equipment, inventory, and personnel improves utilization and security. Manufacturing firms track high-value tooling across multi-site production networks.
- Smart Lighting:Connected LED infrastructure with occupancy and daylight harvesting sensors reduces energy consumption. Commercial real estate operators deploy smart lighting as an entry point for broader building automation.
Revenue maturity sits with Asset Tracking. Application development is concentrating most heavily in Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone concentrates cellular module manufacturing for export markets. German industrial automation corridors around Stuttgart and Munich anchor European sensor deployment. Japanese automotive plants commission private 5G networks for deterministic machine coordination.
United States
Healthcare systems consolidate telemetry platforms to optimize Medicare reimbursement through reduced readmission rates. The FCC governs spectrum allocation for unlicensed IoT bands while HIPAA shapes data governance for connected medical devices. Hospital procurement departments in the Boston-Cambridge corridor favor vendors with unified security credentialing over point-solution specialists.
Germany
Automotive suppliers accelerate production line digitization under EU AI Act conformity timelines. The EU AI Act imposes mandatory algorithmic transparency for autonomous industrial controllers while REACH regulates embedded sensor material composition. BASF and Bayer facilities in Ludwigshafen deploy physics-based simulation with real-time sensor feeds for predictive maintenance optimization.
Japan
Manufacturing facilities commission dedicated spectrum slices for deterministic machine-to-machine communication. METI standards shape interoperability requirements for industrial IoT deployments across automotive and electronics sectors. Toyota and Honda production networks in the Nagoya industrial corridor prioritize 5G private network latency guarantees for safety-critical robotics.
Netherlands
Agricultural cooperatives expand precision irrigation telemetry to comply with EU Water Framework Directive conservation mandates. ETSI standards for low-power wide-area networks shape interoperability conditions across European deployments. Wageningen agtech clusters deploy satellite-linked soil moisture networks to optimize water application amid climate variability.
Brazil
Soybean and sugarcane operations adopt satellite-linked soil moisture networks to optimize water application. ANVISA regulates connected medical device data flows while the central bank shapes fintech-integrated agricultural financing platforms. Mato Grosso farming cooperatives instrument vast acreage with environmental sensing arrays for yield optimization.
IoT Technology Market Competitive Environment
Top-tier vendors anchor platform ecosystems, while specialized module suppliers occupy mid-tier positions. The competitive structure stratifies across semiconductor architects, enterprise networking incumbents, and cloud hyperscalers. Three archetypes dominate: cellular connectivity specialists, edge-to-cloud integrators, and predictive analytics platform vendors. Consolidation pressure favors M&A activity around security credentialing assets and strategic partnerships for multi-protocol certification coverage.
Within the semiconductor architect tier, Intel Corporation and Qualcomm Technologies, Inc. occupy positions defined by processor and modem leadership respectively. Texas Instruments Incorporated anchors the embedded controller segment with analog and mixed-signal integration capabilities. These three exemplify how hardware specialization maps to distinct competitive vectors—compute density, wireless connectivity, and power efficiency—across industrial and consumer deployment scenarios.
| Leading Market Players |
|---|
| Intel Corporation |
| Qualcomm Technologies, Inc. |
| Texas Instruments Incorporated |
| Cisco Systems, Inc. |
| Microsoft |
| IBM |
| Amazon Web Services |
| Huawei Technologies Co. Ltd. |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic transparency mandates gate qualified supply access and premium-tier pricing for certified IoT platforms serving German automotive and French healthcare networks. Procurement departments prioritize vendors with pre-validated conformity dossiers, compressing margin pools for uncertified alternatives while elevating pricing power for compliant module suppliers.
Pricing Analysis
Short lead-time premiums command pricing advantages as Taiwan foundry capacity constraints extend embedded processor delivery schedules. A three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EU AI Act-compliant platforms capturing premium positioning. Cost compression in consumer-grade smart home hardware intensifies because Matter interoperability requirements force firmware redevelopment. Retail chains exhibit highest price sensitivity, while defense contractors and critical infrastructure operators demonstrate lowest sensitivity due to air-gapped deployment mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries that anchor embedded processor supply for industrial sensor manufacturers. Hardware sourcing concentrates in Taiwan, China, and South Korea, with final assembly drawing from Mexico and Vietnam for North American market access. Raw material dependencies include rare earth elements for magnetics, silicon wafers for chip fabrication, and lithium compounds for battery-backed edge devices. Tariff exposure on Chinese-manufactured cellular modules threatens cost structures for connectivity vendors. Distribution runs through authorized distributor networks serving OEM procurement teams, with direct enterprise sales capturing strategic accounts in manufacturing and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge computing architectures are displacing cloud-centric telemetry models as manufacturing firms prioritize latency reduction and data sovereignty compliance. This infrastructure pivot creates distinct strategic imperatives across incumbent vendors, emerging entrants, and capital allocators.
For Market Incumbents: Lock in certification moats by accelerating EU AI Act conformity dossier completion for autonomous industrial controllers before competitor validation timelines compress. Prioritize backward integration into edge processor supply through strategic foundry partnerships in Japan and South Korea to mitigate Taiwan concentration risk. Cisco Systems and Qualcomm Technologies exemplify vendors leveraging existing security credentialing and cellular modem leadership respectively to defend platform positions against modular challengers.
For New Entrants and Emerging Players: Satellite-linked soil moisture sensing for Brazilian agribusiness represents a technology-first wedge into precision agriculture telemetry underserved by incumbent industrial IoT platforms. Target India's rural electrification programs for distributed grid monitoring endpoints where localized analytics requirements favor specialized hardware over hyperscaler cloud bundles. Pursue hospital procurement consolidation trends by offering unified remote patient monitoring and asset tracking dashboards with simplified security credentialing.
For Investors and Strategic Acquirers: 5G private network deployment acceleration in Japanese automotive plants is the leading indicator that deterministic machine-to-machine communication infrastructure will capture outsized capital allocation across manufacturing verticals. Position portfolios for five-to-ten year holding periods around edge-to-cloud integrators with multi-protocol certification coverage spanning ETSI, FCC, and MIC standards. Monitor EU cybersecurity certification mandate progression as the signal for compliance cost inflection that will reshape vendor competitive positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified dashboards combining remote patient monitoring and asset tracking displace point-solution specialists in US hospital procurement. |
| Acquisition of Specialist Firm | Security credentialing assets command premium valuations as EU AI Act mandates force embedded system hardening expertise consolidation. |
| Strategic Partnership | Foundry partnerships in Japan and South Korea reduce Taiwan concentration exposure for industrial sensor manufacturers. |
| Geographic Expansion | Brazilian agribusiness and Indian rural electrification programs create demand for satellite-linked and distributed grid monitoring endpoints. |
| Product Launch | Matter-certified smart home devices capture interoperability premiums amid commoditized hardware margin compression. |
Study Parameters
Multi-period observation of sensor deployment rates, spectrum allocation proceedings, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with embedded systems engineers, hospital procurement managers, agricultural cooperative technology officers, and automotive Tier 1 supplier executives. Secondary validation drew from FCC dockets, ETSI standardization documents, EU AI Act implementing guidance, SEC 10-K filings of semiconductor vendors, and hyperscaler IoT platform capex disclosures. Bottom-up telemetry volume estimates triangulated against top-down market sizing from trade flow data and foundry capacity announcements.
Segment-weighting approaches modeled hardware form factors, deployment topologies, end-user verticals, and application use cases across the projection horizon. CAGRs derived from installed base growth rates, replacement cycle compression, and average selling price trajectories by certification tier. Industry-specific forecast inputs included 5G private network deployment pipelines from METI filings and EU Water Framework Directive conservation mandate compliance timelines for Dutch agricultural telemetry.
Several conditions sit outside the modeled scope, including speculative quantum-secure communication protocol adoption and unannounced spectrum reallocation proceedings beyond current FCC and EU consultation dockets. Deviation in Taiwan semiconductor foundry capacity utilization or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
Cellular IoT Module Market