
 Edge Computing in IoT Market | 2026-2036
Edge Computing in IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Computing in IoT Market Foresight
Hyperscaler infrastructure buildouts in Northern Virginia is repositioning the competitive map for edge data center supply. Amazon Web Services leverages its Outposts portfolio to extend cloud services into on-premises factory floors. Microsoft Corporation anchors enterprise trust through Azure Stack Edge deployments inside regulated healthcare networks. Intel Corporation competes on silicon specialization, embedding AI accelerators directly into gateway chipsets for sub-10-millisecond inference.
Edge Computing in IoT denotes distributed computing architecture that processes data at or near the source device rather than in centralized cloud facilities, typically operating within 1-10 milliseconds latency thresholds using containerized microservices on resource-constrained hardware. Its primary purpose is to enable real-time decision autonomy for mission-critical systems while reducing backhaul bandwidth consumption. Manufacturing end users currently dominate deployment value as predictive maintenance workloads shift from cloud inference to localized edge servers. The hybrid deployment segment represents the fastest-expanding configuration, bridging on-premises control with cloud orchestration for workload portability.
The Federal Communications Commission in the United States governs spectrum allocation for private 5G networks that underpin industrial edge connectivity, while the EU AI Act imposes conformity requirements on automated decision systems processing personal data at the edge. The European Telecommunications Standards Institute publishes MEC framework specifications that shape interoperability between telecom edge and enterprise IoT platforms. Stakeholders must monitor divergence between national data localization mandates and cross-border edge federation standards as regulatory fragmentation becomes the primary barrier to multi-country IoT rollouts.
Market Dynamics
EU AI Act compliance deadlines are forcing manufacturing facilities to relocate inference workloads from centralized cloud to localized edge nodes, compressing deployment timelines and reshaping vendor selection criteria across industrial corridors.
Growth Catalysts
- Private 5G spectrum allocation:FCC rulings in the United States enable dedicated industrial wireless networks that eliminate latency variability for autonomous robotics and predictive maintenance systems.
- Smart manufacturing mandates:German automotive suppliers accelerate edge node deployment to satisfy EU AI Act requirements for localized processing of sensor data in automated quality inspection.
- Containerized microservices:Kubernetes-based orchestration at the gateway level allows workload portability between on-premises servers and cloud control planes without code rewrites.
Market Restraints
- Silicon supply concentration:AI accelerator fabrication depends on a limited foundry base in Taiwan, creating vulnerability for gateway chipset availability.
- Energy cost volatility:Edge data center operations in Germany face electricity price spikes that erode the economic case against cloud alternatives.
- Interoperability fragmentation:Divergent MEC specifications between ETSI frameworks and proprietary telecom implementations complicate multi-vendor deployments.
Strategic Opportunities
- Healthcare edge penetration:Regulated hospital networks in the United States present untapped demand for HIPAA-compliant localized inference on patient monitoring data.
- India industrial corridors:PLI scheme incentives for electronics manufacturing create openings for edge infrastructure co-location near contract assembly facilities.
- Digital twin convergence:Integration of edge analytics with physics-based simulation enables real-time process optimization in chemical processing plants.
Industry Challenges
- Embedded systems talent scarcity:Shortage of engineers proficient in real-time operating systems and constrained-resource optimization limits deployment velocity.
- Legacy OT integration friction:Brownfield manufacturing sites struggle to interface modern containerized workloads with decades-old programmable logic controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Computing in IoT Market |
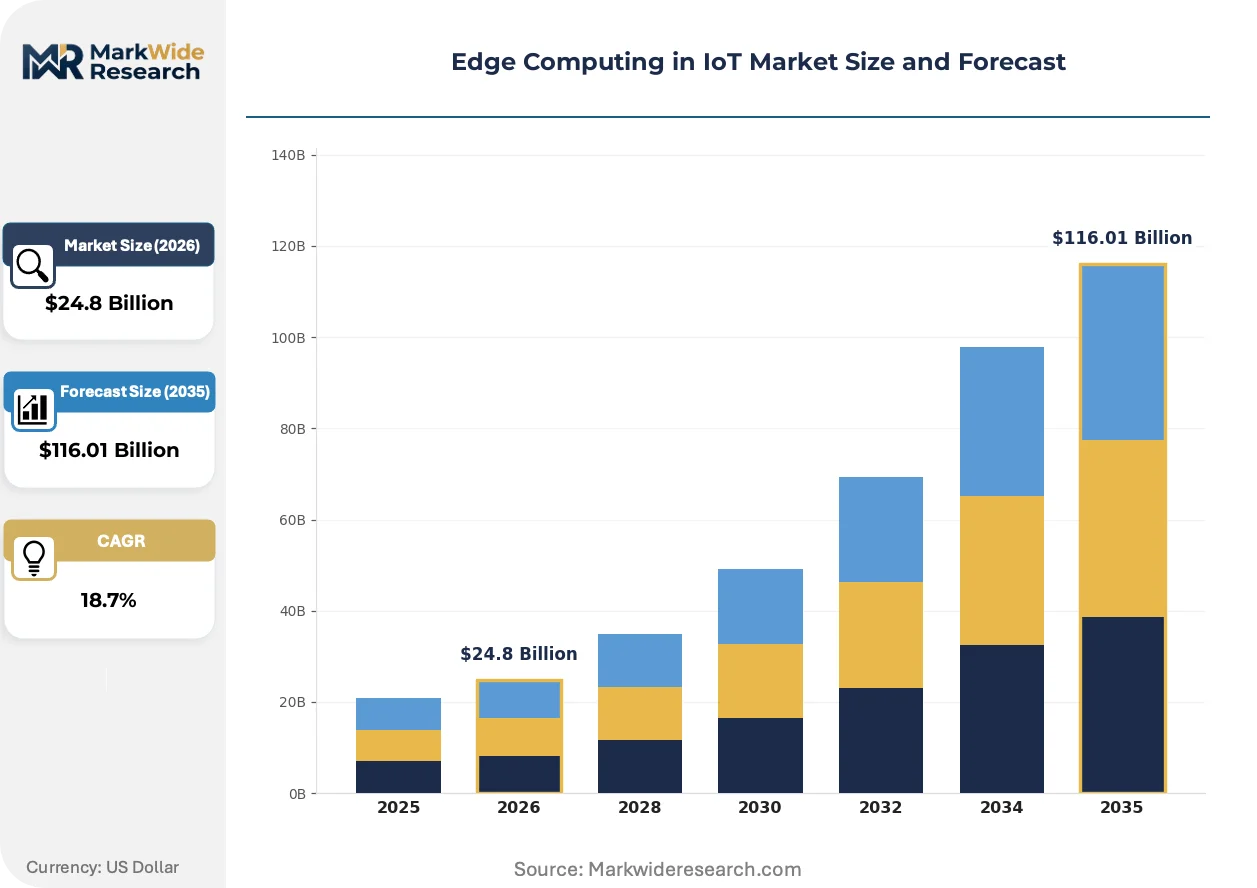
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $116.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Manufacturing, Healthcare, Transportation, Smart Cities Deployment: On-Premises, Cloud, Hybrid, Distributed Device Type: Sensors, Gateways, Routers, Edge Servers Application: Real-Time Analytics, Remote Monitoring, Predictive Maintenance, Smart Grids |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Cisco Systems, Hewlett Packard Enterprise, Intel Corporation, IBM Corporation, Dell Technologies, NVIDIA Corporation, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Computing in IoT Market Shifts & Advancements
Compute architecture is migrating toward heterogeneous processing fabrics that embed inference engines directly into sensor hubs, eliminating the gateway tier entirely for latency-critical workloads.
Neural processing units integrated into industrial cameras is overtaking traditional gateway-based inference for defect detection on automotive assembly lines. Tier-1 suppliers in Michigan and South Carolina are deploying these devices at sub-5-millisecond latencies. The shift is compressing the addressable market for standalone edge servers in quality inspection applications.
EU AI Act conformity requirements for high-risk automated decision systems are mandating algorithmic transparency documentation and human oversight interfaces at the edge node level. Medical device manufacturers processing patient data locally must now maintain audit trails that were previously cloud-resident. Healthcare networks in France and Germany are restructuring procurement specifications to prioritize vendors with pre-certified edge stacks.
Automotive OEMs are consolidating vendor relationships around integrated hardware-software stacks rather than assembling point solutions. Tier-1 suppliers now expect edge platform providers to deliver pre-validated inference pipelines for specific welding, painting, and assembly applications. This preference consolidation is most pronounced in the United States, where Ford and General Motors have established approved vendor lists with single-source accountability clauses.
Edge Computing in IoT Market Segmentation
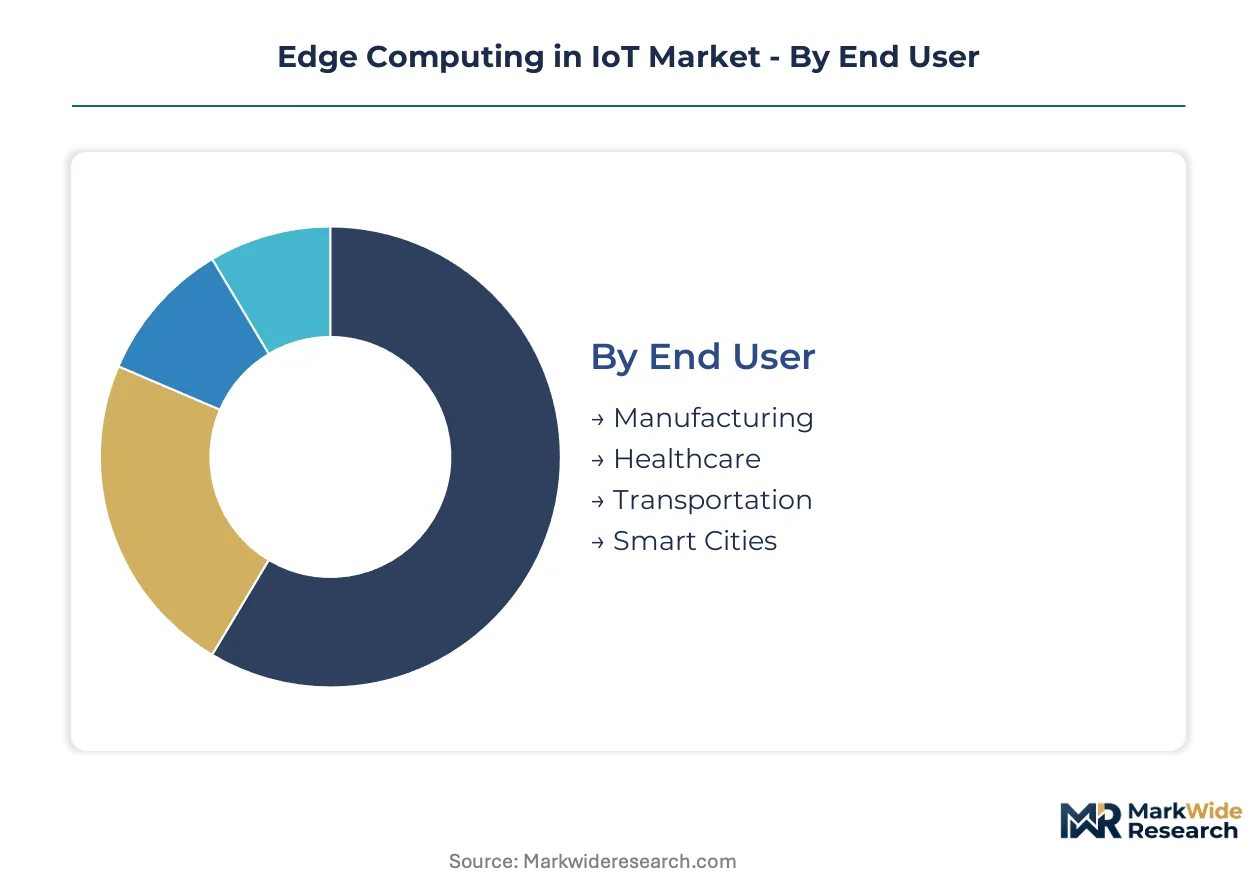
Edge Computing in IoT deployments fragment across four structural dimensions that determine latency architecture, capital intensity, and regulatory exposure. Understanding these segment boundaries clarifies where hardware specialization yields margin premiums versus where software abstraction drives volume economics.
End User:
Integration depth varies sharply: manufacturing and healthcare embed edge nodes directly into operational technology stacks, while transportation and smart cities operate more distributed gateway tiers.
- Manufacturing:Predictive maintenance workloads on localized edge servers process vibration and thermal sensor streams from CNC machines and robotic welders. German automotive suppliers under EU AI Act deadlines are accelerating node deployment for automated quality inspection systems.
- Healthcare:HIPAA-compliant localized inference on patient monitoring data requires edge stacks with audit trail capabilities that were previously cloud-resident. Hospital networks in France and Germany now prioritize pre-certified vendors for high-risk automated decision systems.
- Transportation:Fleet telematics and autonomous vehicle perception systems rely on vehicle-embedded edge processing with intermittent cloud synchronization.
- Smart Cities:Traffic management and public safety applications distribute inference across street-level gateway clusters with municipal data sovereignty constraints.
Volume placements concentrate in Manufacturing; the faster expansion belongs to Healthcare.
Deployment:
Cost tiering separates capex-heavy on-premises installations from opex-driven cloud extensions, with hybrid configurations commanding premium pricing for workload portability.
- On-Premises:Dedicated edge infrastructure inside factory floors or hospital basements delivers sub-10-millisecond latency for mission-critical control loops. United States automotive OEMs in Michigan and South Carolina favor this model for welding and painting line automation.
- Cloud:Centralized processing with edge-like latency through CDN extension and regional cloud zones serves non-critical analytics with relaxed timing requirements.
- Hybrid:Kubernetes-orchestrated workloads migrate seamlessly between local gateways and cloud control planes without code rewrites. This configuration is gaining share fastest among industrial users seeking workload portability.
- Distributed:Federated micro-data centers across multiple sites enable disaster recovery and geographic load balancing for enterprise IoT platforms.
Capital deployment favors On-Premises; Hybrid configurations show the steepest expansion trajectory.
Device Type:
Application maturity determines whether intelligence sits at the sensor hub, gateway tier, or consolidated server layer.
- Sensors:Neural processing units embedded directly into industrial cameras now handle defect detection at sub-5-millisecond latencies, displacing standalone gateway inference for automotive assembly line quality control.
- Gateways:Containerized microservices on resource-constrained hardware bridge legacy OT protocols with modern IP networks. Intel Corporation embeds AI accelerators into gateway chipsets for sub-10-millisecond inference.
- Routers:Network aggregation devices with lightweight edge compute capabilities serve branch office and retail IoT deployments.
- Edge Servers:Rack-mounted systems with GPU acceleration support multi-workload consolidation in controlled environments.
Sensor-embedded inference is climbing the fastest; Edge Servers retain volume dominance in brownfield manufacturing retrofits.
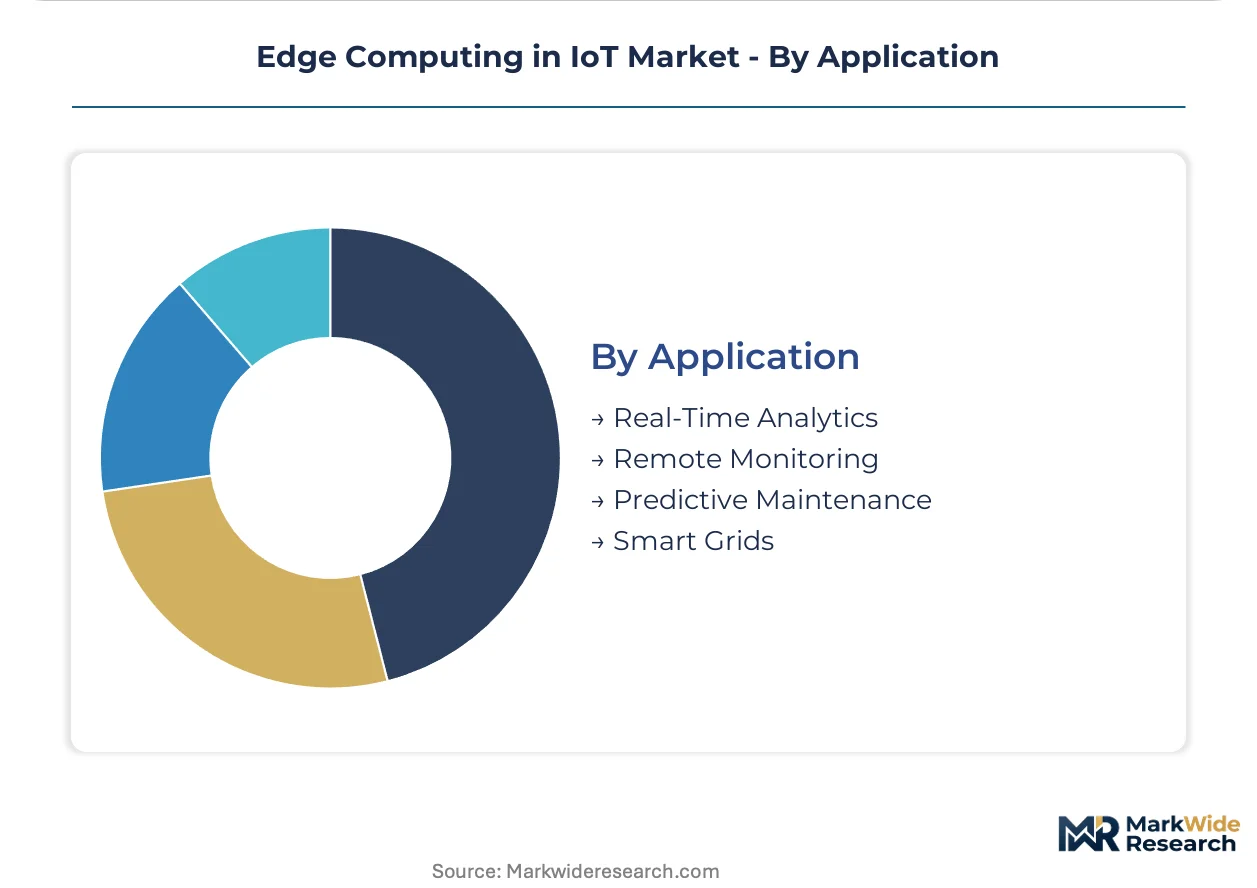
Application:
Customer type differentiation separates industrial buyers seeking operational efficiency from utility operators managing grid stability.
- Real-Time Analytics:Stream processing of manufacturing sensor data enables immediate process adjustments without cloud round-trips. German smart manufacturing facilities deploy these systems for EU AI Act compliance.
- Remote Monitoring:Intermittently connected asset tracking in transportation fleets buffers telemetry locally during network outages.
- Predictive Maintenance:Vibration and acoustic analysis on edge servers forecasts equipment failure before production disruption. This application dominates current manufacturing deployment value.
- Smart Grids:Localized load balancing and fault isolation in electrical distribution networks requires edge nodes with deterministic response guarantees.
Procurement intensity centers on Predictive Maintenance; Smart Grids are expanding most quickly under utility modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon fabrication concentration in Taiwan anchors gateway chipset supply chains, while deployment gravity shifts toward manufacturing corridors in Germany, the United States, India, and China where localized data processing mandates accelerate edge infrastructure buildouts.
United States
Automotive OEMs and cloud hyperscalers co-locate edge infrastructure near industrial corridors in Michigan and South Carolina. The Federal Communications Commission governs spectrum allocation for private 5G networks that underpin industrial edge connectivity. Hospital networks across the Midwest and Southeast prioritize HIPAA-compliant localized inference for patient monitoring systems.
Germany
Smart manufacturing facilities accelerate edge node deployments to meet EU AI Act compliance requirements for localized data processing. The European Telecommunications Standards Institute publishes MEC framework specifications shaping interoperability between telecom edge and enterprise IoT platforms. Automotive suppliers in Bavaria and Baden-Württemberg deploy automated quality inspection systems with sub-10-millisecond latency thresholds.
India
PLI scheme incentives for electronics manufacturing create openings for edge infrastructure co-location near contract assembly facilities. The Bureau of Indian Standards and Telecom Regulatory Authority of India shape equipment certification and spectrum frameworks for industrial wireless networks. Industrial corridors in Maharashtra and Tamil Nadu attract gateway chipset integration facilities serving domestic automotive and electronics demand.
China
Dual carbon goals and smart factory mandates drive edge server deployment in Yangtze River Delta manufacturing zones. The Ministry of Industry and Information Technology governs equipment standards and data localization requirements for industrial IoT platforms. Shenzhen and Shanghai cluster hardware-software integration vendors serving predictive maintenance workloads in domestic automotive and semiconductor fabs.
Japan
Precision manufacturing and robotics sectors demand deterministic edge computing for motion control and quality assurance applications. The Ministry of Economy, Trade and Industry coordinates industrial digitalization standards including edge reference architectures for smart factories. Nagoya automotive suppliers and Osaka semiconductor equipment makers embed AI accelerators directly into sensor hubs for sub-5-millisecond inference.
Edge Computing in IoT Market Competitive Landscape
Global majors compete with regional champions across cloud-to-edge integration capabilities, creating a tiered structure where hyperscalers anchor enterprise trust while semiconductor specialists capture silicon premiums. The vendor base separates into three strategic archetypes: cloud-native platform providers extending services on-premises, hardware-centric systems integrators bundling silicon with software stacks, and telecom equipment vendors leveraging MEC infrastructure relationships. Dominant competitive moves include vertical integration into AI accelerator design and strategic partnerships between automotive OEMs and edge platform providers for pre-validated inference pipelines.
Within the cloud-platform tier, Amazon Web Services and Microsoft Corporation occupy positions exemplifying the hyperscaler edge extension model, while Intel Corporation anchors the silicon specialization archetype through gateway chipset integration. These three entities represent the competitive fault lines where software abstraction meets hardware performance optimization.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Intel Corporation |
| IBM Corporation |
| Dell Technologies |
| NVIDIA Corporation |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
AI accelerator wafer fabrication costs cascade through gateway chipset pricing tiers, with foundry capacity allocation in Taiwan determining margin compression for mid-tier edge server vendors serving German automotive suppliers under EU AI Act procurement deadlines.
Pricing Analysis
Warranty bundling and field service contracts separate premium edge platform vendors from bare-metal hardware suppliers in procurement negotiations. Three-tier pricing structure across certified, validated, and unbundled configurations reflects algorithmic transparency documentation requirements under EU AI Act mandates. Pricing pressure stems from hyperscaler cloud extension offerings compressing standalone edge server margins. Healthcare networks exhibit lowest price sensitivity due to HIPAA compliance liability, while smart city municipalities drive hardest bargain on per-node economics.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting gateway assembly from China to Maharashtra and Tamil Nadu contract manufacturing facilities. AI accelerator fabrication draws from Taiwan foundry capacity, while memory and passive component sourcing rests on South Korean and Japanese suppliers. Single-source vulnerability concentrates in sub-10 nanometer logic fabrication. Distribution runs through Tier-1 automotive supplier procurement committees with approved vendor list gatekeeping authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is consolidating around captive control of AI accelerator silicon and pre-validated inference pipelines, with automotive OEMs demanding single-source accountability from edge platform providers.
For Market Incumbents: Anchor enterprise trust through pre-certified edge stacks that satisfy EU AI Act algorithmic transparency requirements for high-risk automated decision systems. Defend against hyperscaler cloud extension encroachment by deepening on-premises workload portability via Kubernetes-native orchestration layers. Prioritize backward integration into neural processing unit design to capture silicon premiums as sensor-embedded inference displaces gateway tiers.
For New Entrants and Emerging Players: Begin with HIPAA-compliant healthcare edge deployments in United States hospital networks where incumbent hardware-software bundling remains incomplete. Target brownfield manufacturing retrofit opportunities in India PLI scheme corridors where legacy OT integration friction slows established vendor deployment velocity. Lead with containerized microservices portability as the primary go-to-market wedge against proprietary integrated stacks.
For Investors and Strategic Acquirers: Automotive OEM approved vendor list consolidation is the leading indicator that single-source accountability clauses will reshape vendor economics toward integrated platform providers. Position acquisition screening around gateway chipset designers with AI accelerator roadmaps and established Tier-1 supplier relationships. Monitor EU AI Act conformity certification timelines as the signal for procurement specification inflection toward pre-validated edge stacks.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Accelerator Silicon Integration | Captures margin premiums as inference migrates from gateways to sensor hubs in automotive quality inspection. |
| EU AI Act Pre-Certification | Accelerates procurement velocity for German automotive suppliers facing automated decision system compliance deadlines. |
| Kubernetes-Native Orchestration | Enables workload portability between factory floor gateways and AWS Outposts or Azure Stack Edge control planes. |
| Private 5G Spectrum Partnership | Locks in FCC-governed industrial wireless network deployments for autonomous robotics latency guarantees. |
| Healthcare Edge Audit Trail Development | Satisfies HIPAA requirements for localized patient monitoring data processing with cloud-resident documentation. |
Research Methodology
Independent corroboration across platform engineering directors at cloud hyperscalers, procurement leads at Tier-1 automotive suppliers, and biomedical engineers at United States hospital networks underwrites the qualitative findings in this study. Secondary validation draws from FCC spectrum allocation rulings, ETSI MEC framework specifications, EU AI Act conformity documentation, and SEC capex disclosures by infrastructure deployers. Bottom-up deployment tallies by end-use segment triangulate against top-down market sizing from supply-side vendor revenue attribution.
Comparable historical reference periods spanning pre-pandemic industrial automation investment cycles anchor the projection methodology across the analysis window. Segmentation modeling incorporates deployment configuration, device type intelligence tier, end-use vertical, and regional regulatory cluster dimensions. CAGR derivation rests on deployment velocity differentials between EU AI Act compliance-driven manufacturing and HIPAA-constrained healthcare penetration. Forecast inputs include private 5G spectrum allocation timelines and PLI scheme incentive disbursement patterns.
Underlying measurement precision varies by segment; on-premises manufacturing deployments carry tighter precision than emerging healthcare edge configurations due to established vendor reporting practices. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry capacity expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Location of Things Market