
 Satellite IoT Market | 2026-2036
Satellite IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite IoT Market Outlook
Aftermarket service revenue is tilting from hardware maintenance toward subscription-based connectivity management. Iridium Communications leverages its L-band constellation to sustain pole-to-pole coverage for maritime and aviation clients. SpaceX anchors terrestrial-backhaul substitution through its Starlink IoT beta programs. ORBCOMM specializes in dual-mode cellular-satellite terminals that dominate agricultural and transportation telemetry.
Satellite IoT denotes networked sensor and communication endpoints that relay data through low Earth orbit, geostationary, or medium Earth orbit spacecraft rather than terrestrial infrastructure, typically operating across L-band through Ka-band frequencies with link budgets engineered for remote, mobile, or intermittently connected assets. The primary commercial purpose is to enable continuous monitoring, command, and data extraction from assets beyond cellular range. Communication devices command the largest installed base among product types, while tracking systems represent the fastest-expanding margin pool as fleet operators consolidate multi-modal visibility platforms. Agriculture monitoring and fleet tracking use cases are converging as equipment OEMs embed satellite modems at the factory.
The FCC governs spectrum allocation and orbital debris mitigation for U.S.-based operators, while the ITU coordinates cross-border frequency registrations and interference protocols. ESA and national space agencies in France, Germany, and Italy shape European procurement standards for sovereign IoT constellations. Stakeholders must monitor spectrum auction timelines and debris-compliance thresholds as gatekeepers for constellation deployment permits.
Market Dynamics
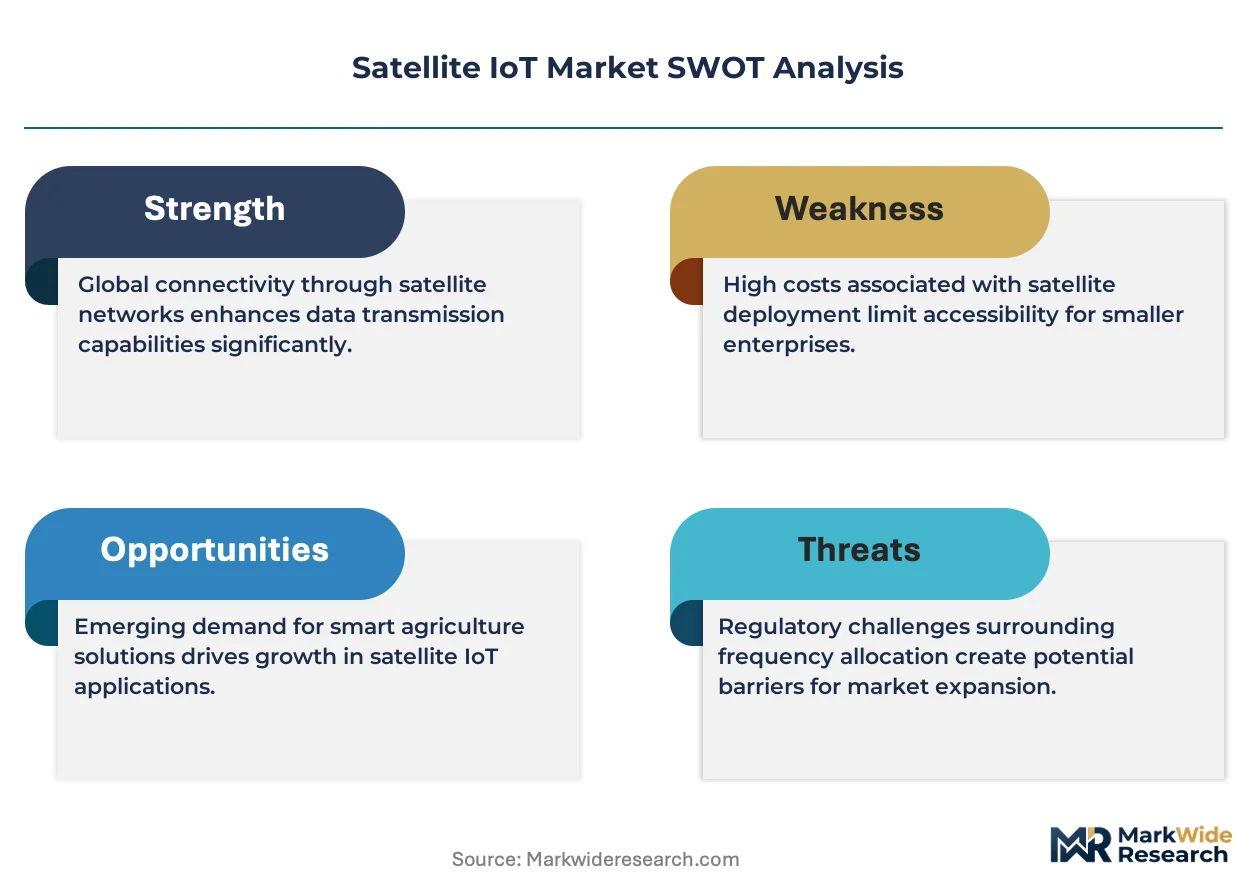
The Satellite IoT Market pivots on spectrum scarcity and constellation density economics. Operators must secure orbital slots and frequency allocations before deploying spacecraft, while terrestrial-backhaul substitution accelerates demand for low-latency links.
Growth Catalysts
- FCC Part 25 Licensing Reform:Streamlined market access rules for non-geostationary systems reduce entry barriers for constellation operators seeking U.S. coverage footprints.
- Maritime Fleet Digitization:Container shipping lines mandate real-time reefer monitoring and engine telemetry across trans-oceanic routes beyond cellular reach.
- L-band Propagation Physics:Superior foliage and weather penetration compared to Ku/Ka bands sustains connectivity for agricultural sensors in dense vegetation environments.
Market Restraints
- Launch Capacity Bottlenecks:Limited heavy-lift availability and range safety scheduling constrain constellation deployment cadence for new entrants.
- Solar Panel Supply Concentration:Photovoltaic array manufacturing clusters in Southeast Asia create single-source vulnerability for spacecraft power systems.
- ITU Coordination Timelines:Cross-border frequency registration procedures extend 18-24 months, delaying commercial service activation in contested orbital planes.
Strategic Opportunities
- Brazilian Agribusiness Expansion:Soybean and cattle operations across Mato Grosso and Pará lack terrestrial infrastructure, creating addressable white space for precision agriculture telemetry.
- Aviation Black-Box Streaming Mandates:Regulatory pressure for continuous flight data transmission opens retrofit opportunities for narrowband satellite modems in existing commercial fleets.
- Dual-Mode Terminal Convergence:Hybrid cellular-satellite chipsets eliminate radio switching latency, enabling seamless handoff for cross-border logistics tracking.
Industry Challenges
- Orbital Debris Compliance Engineering:Post-mission disposal and collision avoidance system mandates from national space agencies increase spacecraft design complexity and certification burden.
- RF Interference Mitigation:Co-channel emissions from proliferating constellations require sophisticated beam-steering algorithms and inter-operator coordination protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite IoT Market |
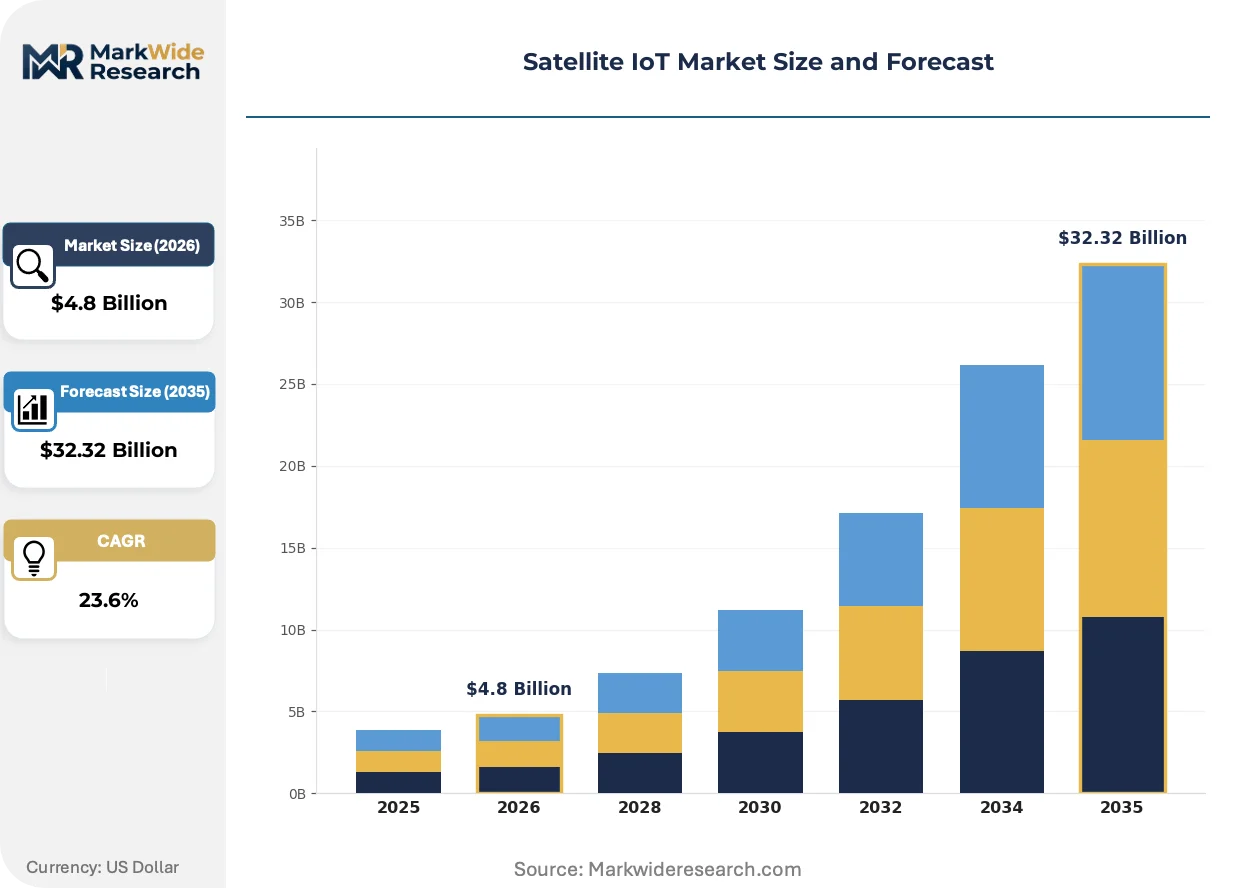
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $32.32 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Sensors, Communication Devices, Terminals, Tracking Systems Use Case: Agriculture Monitoring, Disaster Management, Fleet Tracking, Environmental Monitoring End User: Aerospace, Shipping, Agriculture, Mining Connectivity: L-band, Ku-band, Ka-band, C-band |
| Companies Covered | Globalstar, SES, SpaceX, Astrocast, Lynk Global, Viasat, ORBCOMM, Myriota, Iridium Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite IoT Market Strategic Shifts
Constellation architectures and terminal economics are compressing service delivery costs. Three forces dominate: spacecraft miniaturization, spectrum-sharing protocols, and unbundled connectivity procurement.
Flat-panel phased array antennas are rendering obsolete traditional parabolic dish terminals for mobile platforms. Maritime and aviation integrators specify electronically steered arrays for low-profile installation. The technology eliminates mechanical gimbal maintenance while enabling simultaneous multi-constellation reception, collapsing the installed cost differential between geostationary and low Earth orbit services.
REACH chemical restrictions and the EU Green Deal sustainability disclosure rules now extend to spacecraft manufacturing supply chains. European constellation procurement mandates cradle-to-grave environmental reporting for solar cells, batteries, and composite structures. Operators serving EU-flagged vessels and aircraft must document carbon intensity per data bit transmitted, favoring operators with renewable ground station power.
Enterprise buyers now unbundle hardware acquisition from connectivity subscriptions, treating satellite modems as depreciable capital assets rather than bundled lease components. Agricultural equipment OEMs embed modems at factory, shifting procurement authority from fleet operators to manufacturing procurement teams. This pattern concentrates most visibly in North American precision agriculture, where Deere and Case IH specify satellite radio modules as standard factory fitment.
Satellite IoT Market Segmentation
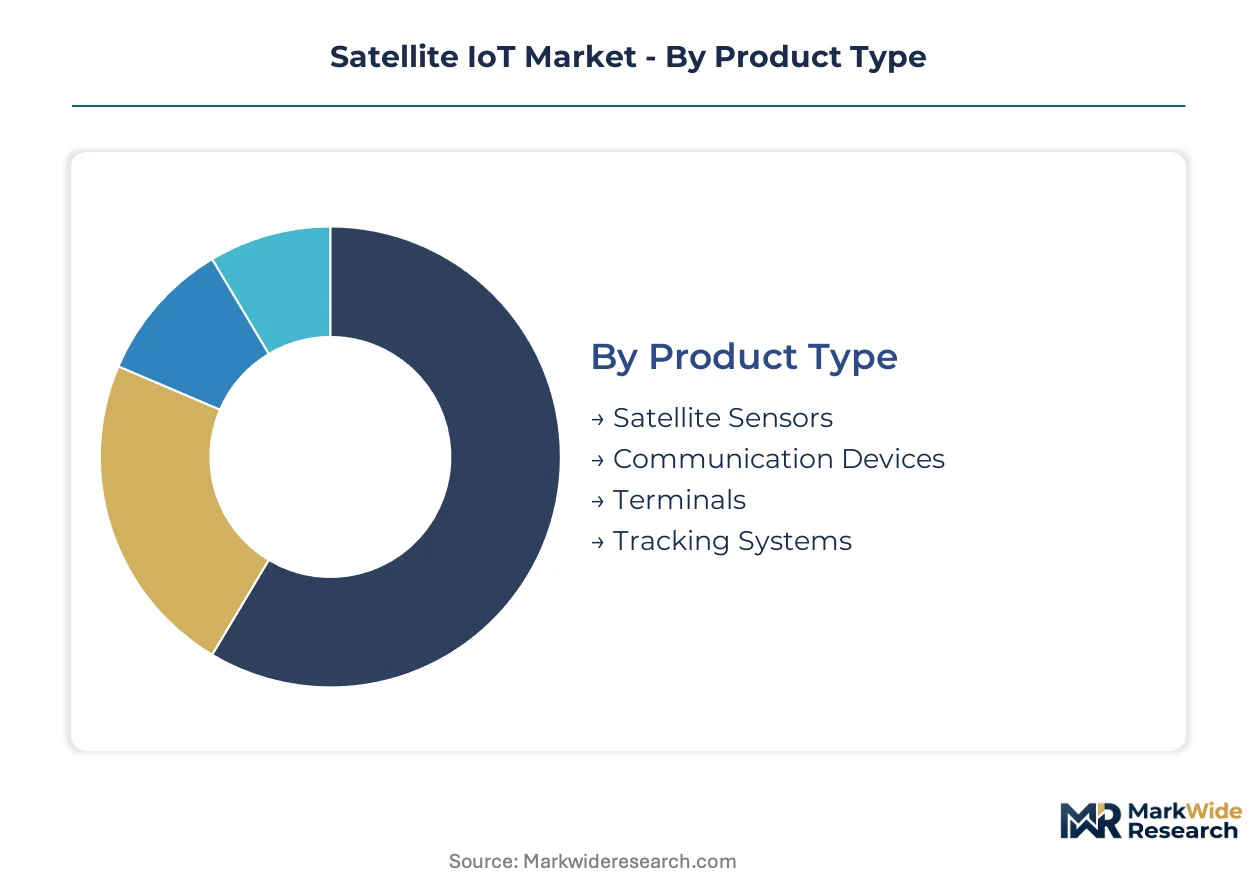
Satellite IoT segmentation reveals how constellation economics and terminal specifications map to distinct procurement authority centers. Equipment OEMs, fleet operators, and sovereign agencies each drive divergent specification requirements across frequency bands and form factors.
Product Type:
Cost tier separates capital-intensive spacecraft-integrated hardware from modular field-deployable units.
- Communication Devices:These units encode, modulate, and transmit sensor data through L-band to Ka-band links, with power amplifiers sized for maritime and aviation antenna constraints. Container shipping lines across the North Atlantic and Pacific routes deploy these for engine telemetry and reefer monitoring where cellular backhaul fails.
- Tracking Systems:GPS-integrated modules combine positioning fixes with satellite uplink capability in compact enclosures rated for vibration and temperature extremes. Brazilian agribusiness operators in Mato Grosso specify these for cattle herd and machinery fleet visibility across pastureland lacking terrestrial infrastructure.
- Satellite Sensors:Remote sensing payloads measuring soil moisture, thermal signatures, or atmospheric conditions with onboard processing for edge analytics.
- Terminals:Ground station equipment aggregating multiple sensor streams for bulk transmission, typically deployed at fixed agricultural or mining sites.
Communication devices command the established base. The steepest expansion runs through tracking systems.
Use Case:
Application maturity varies sharply between regulated mandates and discretionary operational efficiency investments.
- Fleet Tracking:Multi-modal visibility platforms consolidate maritime, aviation, and ground vehicle telemetry under unified fleet management software. European shipping operators subject to EU Green Deal disclosure rules prioritize these deployments for fuel consumption and route optimization documentation.
- Agriculture Monitoring:Precision agriculture systems integrate soil sensors, weather stations, and equipment telematics through satellite backhaul. Deere and Case IH factory-fit these modules as standard equipment for North American row-crop operations.
- Disaster Management:Rapid-deploy communication kits for first responders when terrestrial infrastructure fails during hurricanes, floods, or seismic events.
- Environmental Monitoring:Long-duration sensor networks tracking deforestation, glacier movement, or marine ecosystem parameters in remote conservation zones.
Fleet tracking commands the established base. Agriculture monitoring climbs the fastest as OEM procurement authority displaces operator decision-making.
End User:
Customer type determines specification rigor, with aerospace and maritime imposing the most demanding certification requirements.
- Shipping:Container lines and bulk carriers mandate IEC 60945 maritime electronics compliance plus FCC Part 25 licensing for U.S. port operations. Reefer monitoring and engine telemetry drive the largest volume procurement.
- Aerospace:Commercial aviation retrofit opportunities concentrate on narrowband satellite modems for black-box streaming mandates under FAA regulatory pressure.
- Agriculture:Equipment OEM procurement teams now specify satellite radio modules as factory standard, shifting buying authority from fleet operators to manufacturing supply chains.
- Mining:Open-pit and underground operations requiring personnel safety tracking and autonomous vehicle command links beyond cellular range.
Shipping commands the established base. Aerospace gains share fastest on regulatory retrofit timelines.
Connectivity:
Frequency band selection trades propagation physics against bandwidth economics and licensing availability.
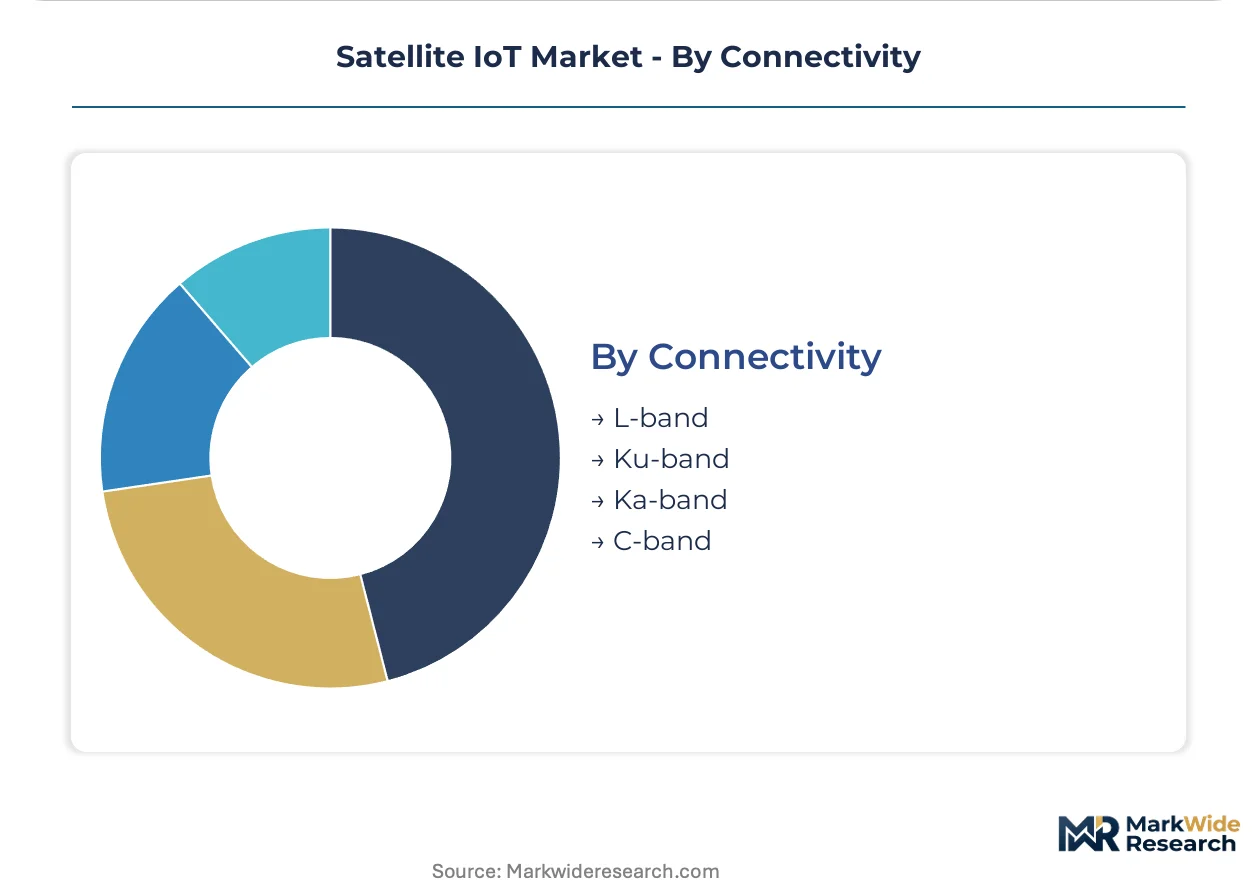
- L-band:Lower frequencies penetrate foliage, weather, and building materials with minimal attenuation. Iridium Communications leverages this spectrum for pole-to-pole maritime and aviation coverage where link reliability outweighs bandwidth requirements.
- Ka-band:Higher frequencies enable broadband throughput for data-intensive applications but require precise antenna pointing and suffer rain fade. SpaceX Starlink IoT beta programs utilize this band for terrestrial-backhaul substitution in remote U.S. locations.
- Ku-band:Mid-range frequencies balancing throughput and propagation, common in geostationary satellite services for fixed agricultural and mining terminals.
- C-band:Legacy spectrum with favorable rain margins but limited orbital slot availability, concentrated in older maritime and broadcast relay applications.
L-band commands the established base. Ka-band expands most quickly on constellation density economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by geography. Brazilian agribusiness operators prioritize low-cost L-band terminals for cattle tracking, while European shipping lines absorb premium Ka-band pricing for EU Green Deal compliance documentation.
United States
SpaceX's Starlink constellation anchors terrestrial-backhaul substitution across rural agricultural zones and remote industrial sites. FCC Part 25 licensing reforms streamline non-geostationary market access for constellation operators. California-based launch clusters and Texas ground station networks concentrate deployment infrastructure for IoT beta programs.
Brazil
Soybean and cattle operations across Mato Grosso and Pará drive demand for precision agriculture telemetry beyond cellular infrastructure. ANVISA and national telecommunications frameworks govern satellite service commercialization. São Paulo state hosts equipment distribution channels serving agribusiness procurement teams specifying factory-embedded satellite modems.
Germany
European shipping operators subject to EU Green Deal disclosure rules mandate fleet tracking for fuel consumption documentation. REACH chemical restrictions and sustainability disclosure rules extend to spacecraft manufacturing supply chains. Hamburg and Bremen harbor clusters concentrate maritime electronics integration for container line retrofits.
Japan
Commercial aviation retrofit opportunities concentrate on narrowband satellite modems for black-box streaming under regulatory pressure. METI shapes national procurement standards for sovereign IoT constellation participation. Tokyo-Osaka industrial corridors host aerospace electronics manufacturers specifying satellite radio modules for next-generation flight data systems.
Australia
Mining operations across Western Australia and Queensland require personnel safety tracking and autonomous vehicle command links beyond cellular range. TGA and national space agency frameworks coordinate spectrum allocation for remote asset monitoring. Perth and Brisbane serve as logistics hubs for satellite terminal deployment to open-pit and underground sites.
Satellite IoT Market Competitive Environment
Capability concentration sits with established constellation operators possessing orbital slots and frequency allocations; scale advantage sits with vertically integrated launch-service providers. The market structures around three tiers: legacy geostationary operators defending maritime contracts, low Earth orbit newcomers capturing terrestrial-backhaul substitution, and dual-mode terminal specialists bridging cellular gaps. Dominant competitive moves include spectrum portfolio expansion through ITU coordination filings and strategic partnerships with agricultural equipment OEMs for factory-fit modem programs.
Within the constellation operator tier, Iridium Communications and Globalstar exemplify established L-band specialists, while SpaceX occupies a position at the scale-driven end through integrated launch and service provision. ORBCOMM sits within the dual-mode terminal specialization, representing hybrid cellular-satellite integration for agricultural and transportation telemetry applications.
| Leading Market Players |
|---|
| Globalstar |
| SES |
| SpaceX |
| Astrocast |
| Lynk Global |
| Viasat |
| ORBCOMM |
| Myriota |
| Iridium Communications |
| Others |
Value Chain & Pricing Dynamics
Southeast Asian photovoltaic array manufacturing clusters determine spacecraft power system economics, with concentrated solar panel production translating directly into constellation deployment cost structures and downstream service pricing power for operators.
Pricing Analysis
Subscription-based connectivity management now drives lifetime value, displacing hardware maintenance revenue. Three-tier pricing structure across premium, standard, and economy levels differentiates by link reliability grade and after-sales service bundling. Cost compression in economy L-band terminals is intensifying because agricultural OEMs embed modems at factory scale. Brazilian agribusiness operators exhibit highest price sensitivity; European shipping lines absorbing EU Green Deal compliance costs show lowest.
Supply Chain Analysis
Extended payment terms from launch service providers now structure supplier-financing for constellation operators. Solar cell manufacturing draws from China, Vietnam, and Malaysia; launch vehicle propulsion systems rest on Russian and Ukrainian supply heritage. Single-source vulnerability concentrates in heavy-lift launch capacity. Distribution runs through equipment OEM procurement teams shifting authority from fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation density economics fragment procurement authority across equipment OEMs, fleet operators, and sovereign agencies, creating specialized vendor niches around frequency band expertise and certification jurisdiction.
For Market Incumbents: Insulate maritime contract positions through ITU coordination filings securing contested orbital planes. Deepen backward integration into flat-panel phased array manufacturing to capture terminal margin pool. Emerging LEO entrants threaten geostationary incumbents on latency metrics; defend through L-band propagation reliability certification. For New Entrants and Emerging Players: Establish a beachhead in Brazilian precision agriculture telemetry where terrestrial infrastructure gaps persist. Target aviation black-box streaming retrofit segments under regulatory mandate pressure. Partner with agricultural equipment OEMs for factory-fit modem programs as primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a spectrum-arbitrage play because orbital slot scarcity appreciates against proliferating IoT endpoint demand. Acquisition targets should display ITU filing portfolios and dual-mode terminal integration capabilities. Watch FCC Part 25 licensing reform timelines as inflection signal for new entrant capacity additions.| Strategic Initiative | Industry Significance |
|---|---|
| ITU Frequency Coordination Filing | Secures orbital plane access before constellation deployment cadence accelerates. |
| Dual-Mode Terminal Integration | Enables seamless cellular-satellite handoff for cross-border logistics tracking applications. |
| Flat-Panel Phased Array Manufacturing | Eliminates mechanical gimbal maintenance for maritime and aviation low-profile installation. |
| Agricultural OEM Factory-Fit Partnership | Shifts procurement authority from fleet operators to manufacturing supply chains. |
| EU Green Deal Compliance Documentation | Creates premium pricing tier for carbon intensity disclosure in European shipping. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across constellation operators, maritime fleet managers, agricultural equipment OEM procurement teams, and aviation electronics integrators. Secondary validation drew from FCC Part 25 licensing databases, ITU frequency registration filings, ESA procurement disclosures, and customs records for satellite terminal trade flows. Bottom-up endpoint deployment estimates triangulated against top-down spectrum allocation capacity models.
Calibration against historical constellation deployment cadence and service activation timelines anchored the analytical framework. Segmentation dimensions modeled include frequency band, terminal form factor, end-user certification tier, and regional regulatory cluster. CAGRs derived from subscriber growth curves and average revenue per endpoint trajectories. Launch cost elasticity and solar panel supply concentration served as industry-specific forecast inputs across the analysis window.
Stress conditions across launch capacity availability, ITU coordination timeline extension, and solar panel supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spectrum allocation continuity and debris compliance threshold stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
IoT Application Development Services Market