
 IoT Integration Services Market | 2026-2036
IoT Integration Services Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Integration Services Market Outlook
The IoT integration services market is recalibrating around a widening gap between premium managed-service bundles and commodity device-connectivity offerings. Microsoft Corporation leverages its Azure IoT platform and enterprise cloud footprint to anchor high-margin vertical solutions. Amazon Web Services, Inc. competes through edge-to-cloud infrastructure scale and developer ecosystem density. Cisco Systems, Inc. differentiates via networking hardware-software convergence and OT-security integration.
IoT integration services encompass the architectural design, protocol harmonization, API orchestration, and lifecycle management required to unify disparate sensors, edge nodes, and enterprise systems into coherent operational workflows. These services typically handle multi-protocol environments spanning MQTT, CoAP, and OPC-UA with latency thresholds below 50 milliseconds for real-time control applications. Implementation services now command the largest revenue pool as manufacturers retrofit legacy equipment, while edge computing deployments represent the fastest-expanding segment driven by latency-sensitive automotive and energy use cases. Consulting engagements around hybrid cloud-on-premises architectures concentrate margin in complex regulated verticals including healthcare providers and telecommunications operators.
The EU AI Act and NIS2 Directive impose mandatory conformity assessments and incident reporting on connected infrastructure across Europe, directly expanding demand for compliance-integrated deployment services. In the United States, NIST cybersecurity frameworks and FDA guidance on connected medical devices shape procurement specifications and vendor qualification pathways. Stakeholders must monitor how divergent regional certification regimes fragment platform architectures and whether edge-native security standards consolidate before hybrid deployment complexity escalates beyond manageable integration costs.
Market Dynamics
Industrial digitization mandates are compressing procurement cycles for IoT integration services, forcing service providers to embed compliance architectures directly into deployment workflows rather than retrofitting them post-installation.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting and risk management obligations for critical infrastructure operators across Europe are expanding demand for security-integrated deployment services.
- Automotive edge computing:Latency-sensitive autonomous manufacturing and predictive maintenance applications in vehicle production are accelerating sensor-to-cloud integration projects.
- Smart manufacturing clusters in Germany:Industrial digitization programs concentrated in Baden-Württemberg and Bavaria are anchoring premium service demand for protocol harmonization and legacy equipment retrofitting.
Market Restraints
- Specialized OT-IT convergence talent scarcity:Shortages of engineers certified in both operational technology protocols and enterprise cloud architectures are inflating implementation costs and extending project timelines.
- Component concentration in East Asian semiconductor supply:Dependency on concentrated sensor and edge processor manufacturing creates vulnerability to supply disruptions and tariff exposure.
- Interoperability fragmentation:Proprietary industrial IoT platforms from major cloud providers are locking customers into single-vendor ecosystems, limiting competitive pricing pressure.
Strategic Opportunities
- Japan's Society 5.0 implementation:METI-led smart factory and connected infrastructure programs are creating demand for hybrid cloud-on-premises architectures in manufacturing and energy.
- Digital twin convergence with AI analytics:Integration of real-time sensor feeds with simulation models is opening new service revenue pools in process optimization and predictive quality control.
- Outcome-based service contracting:Buyers in regulated healthcare and telecommunications verticals are shifting from capital expenditure models to performance-guaranteed subscription arrangements.
Industry Challenges
- Multi-protocol certification complexity:Engineers must maintain concurrent competencies across MQTT, CoAP, OPC-UA, and proprietary industrial standards, stretching training and retention budgets.
- Legacy brownfield integration:Retrofitting decades-old manufacturing equipment with modern connectivity layers requires custom hardware adapters and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Integration Services Market |
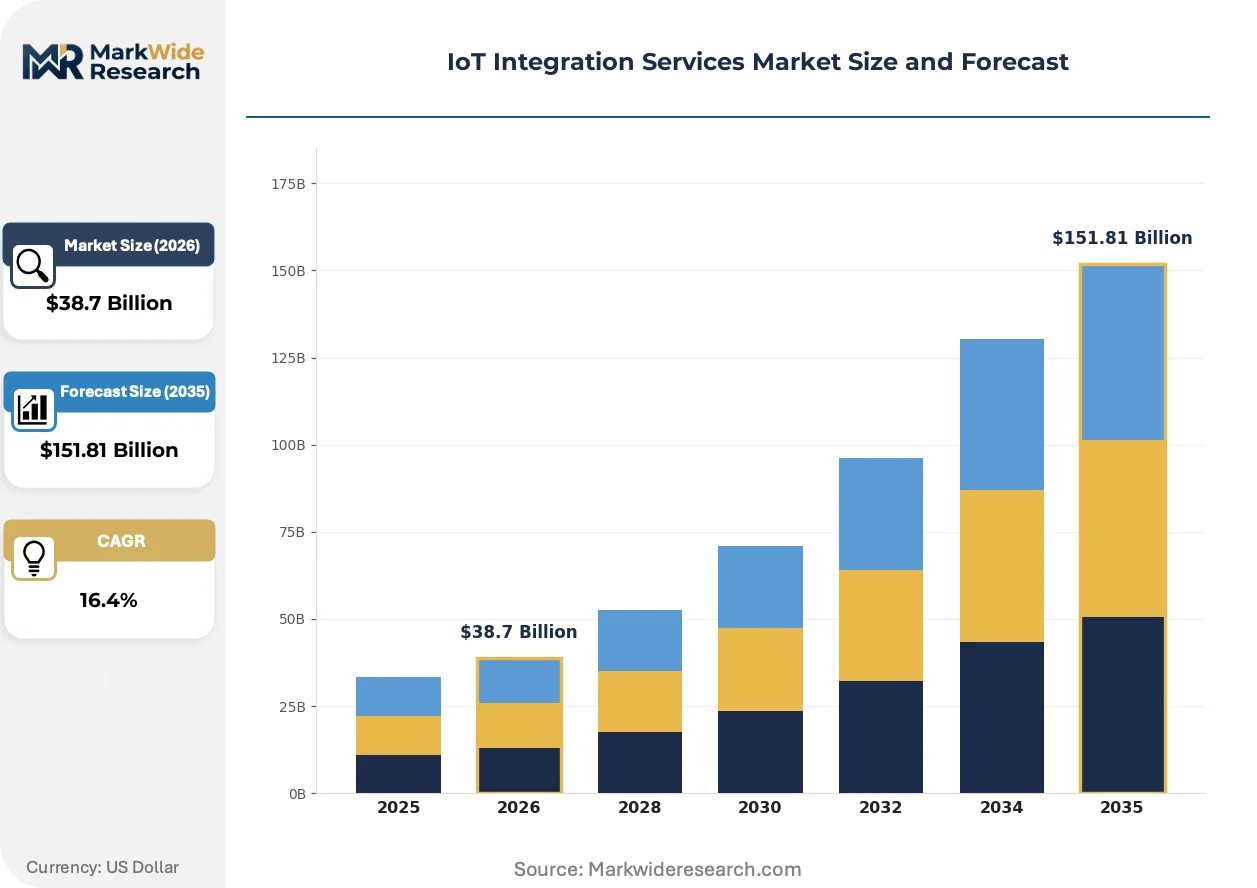
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Support, Maintenance End User: Manufacturers, Retailers, Healthcare Providers, Smart Home Consumers Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Industry Vertical: Automotive, Agriculture, Energy, Telecommunications |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Inc., Cisco Systems, Inc., Accenture, IBM, Intel Corporation, SAP SE, Tata Consultancy Services, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Integration Services Market Strategic Shifts
Edge-native computing architectures are redistributing intelligence away from centralized cloud infrastructure, creating new service categories around distributed security management and localized data governance.
Mesh networking protocols for industrial environments are decentralizing connectivity responsibility across factory floors. Automotive manufacturers in Stuttgart and Wolfsburg are deploying these self-healing topologies to eliminate single points of failure in production lines. The technology is decentralizing control system architectures and compressing dependency on proprietary gateway hardware.
The EU AI Act's risk-based classification system for connected devices is mandating conformity assessments before market deployment. Medical device manufacturers and energy grid operators must now document algorithmic transparency and bias mitigation in connected sensor networks. German industrial automation suppliers are restructuring product development cycles to embed these documentation requirements upstream.
Buyers in capital-intensive sectors are unbundling hardware procurement from integration and lifecycle management services. Energy utilities in Texas and telecommunications operators in Japan are separating device purchases from multi-year managed service agreements. This pattern is most pronounced in regulated verticals where compliance accountability must remain with specialized service providers rather than equipment vendors.
IoT Integration Services Market Segmentation
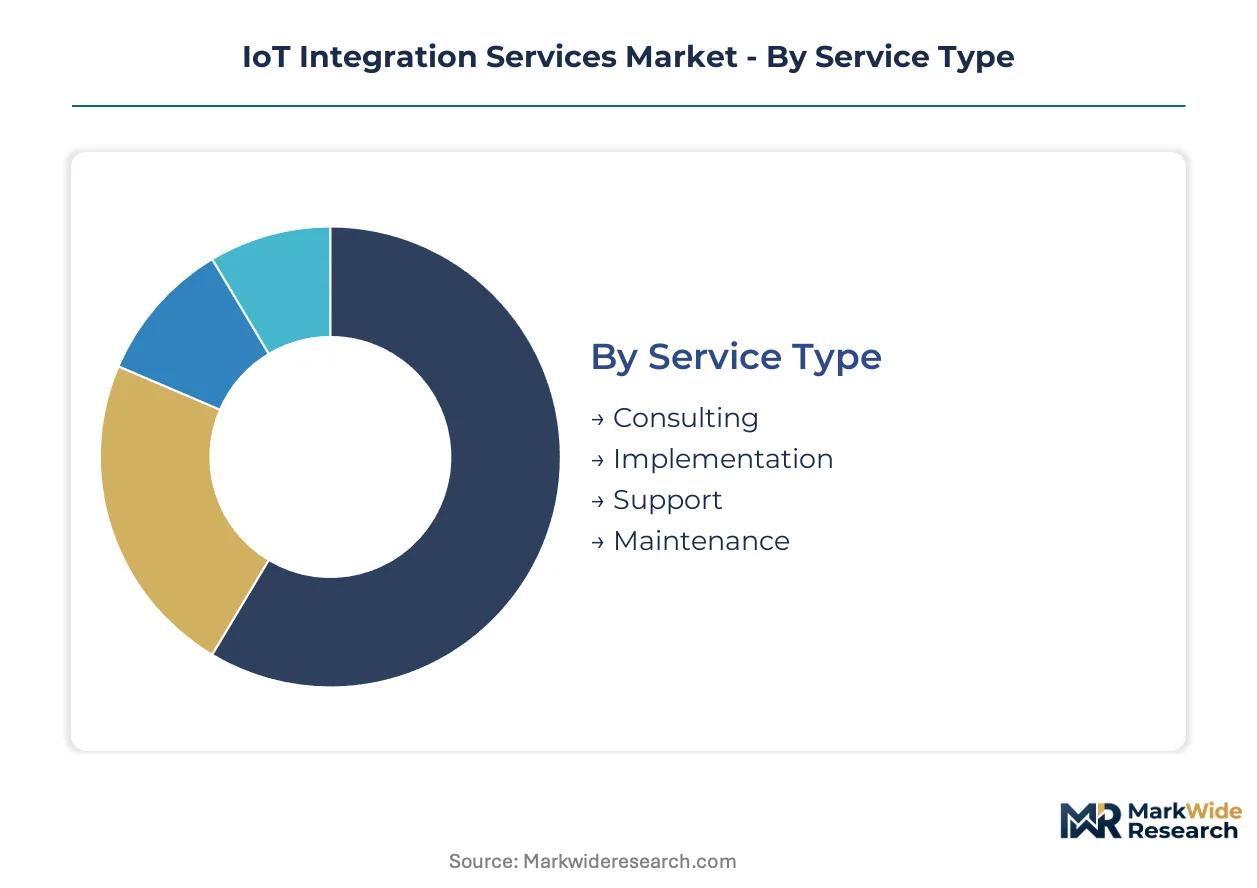
IoT integration services fragment across four critical dimensions that determine pricing architecture and delivery complexity. Service type dictates margin structure, while deployment mode governs latency performance and regulatory exposure. End user concentration and industry vertical specialization shape competitive positioning and talent requirements.
Service Type:
Upgrade and replacement cycles vary dramatically across service categories, with legacy system retrofits driving consulting and implementation demand while connected device proliferation expands recurring maintenance pools.
- Consulting:Architectural design and protocol harmonization engagements for hybrid cloud-on-premises deployments. Healthcare providers in Germany and telecommunications operators in Japan anchor premium demand as NIS2 and METI compliance requirements compress procurement cycles.
- Implementation:Physical deployment, API orchestration, and commissioning services for multi-protocol environments. Automotive manufacturers in Stuttgart and Wolfsburg retrofit decades-old production lines with MQTT and OPC-UA connectivity layers, stretching project timelines due to custom hardware adapter requirements.
- Support:Technical assistance and troubleshooting for operational IoT ecosystems.
- Maintenance:Lifecycle management and firmware update services for sensor networks and edge nodes.
Implementation sits at the top of the volume ranking, with Support climbing the fastest as outcome-based contracting shifts accountability to service providers.
End User:
Customer procurement sophistication creates three distinct cost tiers, with regulated verticals accepting premium pricing for compliance-integrated delivery and consumer segments driving standardization.
- Manufacturers:Industrial digitization programs across automotive and energy sectors. Smart factory clusters in Baden-Württemberg and Bavaria generate concentrated demand for protocol harmonization and brownfield integration expertise.
- Healthcare Providers:Connected medical device deployments requiring FDA and EU MDR conformity assessments. Documentation of algorithmic transparency and bias mitigation in sensor networks restructures product development cycles.
- Retailers:Supply chain visibility and inventory management IoT implementations.
- Smart Home Consumers:Residential automation and connected appliance integration services.
Manufacturers command the largest revenue share, while Healthcare Providers gain share fastest as regulatory complexity expands addressable spend.
Deployment:
Latency thresholds below 50 milliseconds for real-time control applications are redistributing intelligence away from centralized infrastructure toward distributed architectures.
- Cloud-Based:Centralized data processing and analytics platforms. Energy utilities in Texas unbundle hardware procurement from multi-year managed service agreements, separating device purchases from integration accountability.
- Edge Computing:Localized intelligence for latency-sensitive automotive and energy use cases. Mesh networking protocols in Stuttgart and Wolfsburg production lines eliminate single points of failure through self-healing topologies.
- Hybrid:Combined cloud-on-premises architectures for regulated verticals.
- On-Premises:Fully localized infrastructure for data sovereignty requirements.
Cloud-Based deployments retain volume leadership, though Edge Computing demonstrates the steepest expansion trajectory as autonomous manufacturing applications multiply.
Industry Vertical:
Application-specific certification requirements and OT-IT convergence complexity create divergent margin profiles across vertical markets.
- Automotive:Predictive maintenance and autonomous manufacturing sensor-to-cloud integration. Vehicle production facilities deploy edge-native architectures to compress dependency on proprietary gateway hardware.
- Energy:Grid modernization and distributed generation monitoring. NIS2 incident reporting obligations expand demand for security-integrated deployment services across European operators.
- Telecommunications:Network infrastructure monitoring and customer premise equipment management.
- Agriculture:Precision farming and livestock monitoring connectivity solutions.
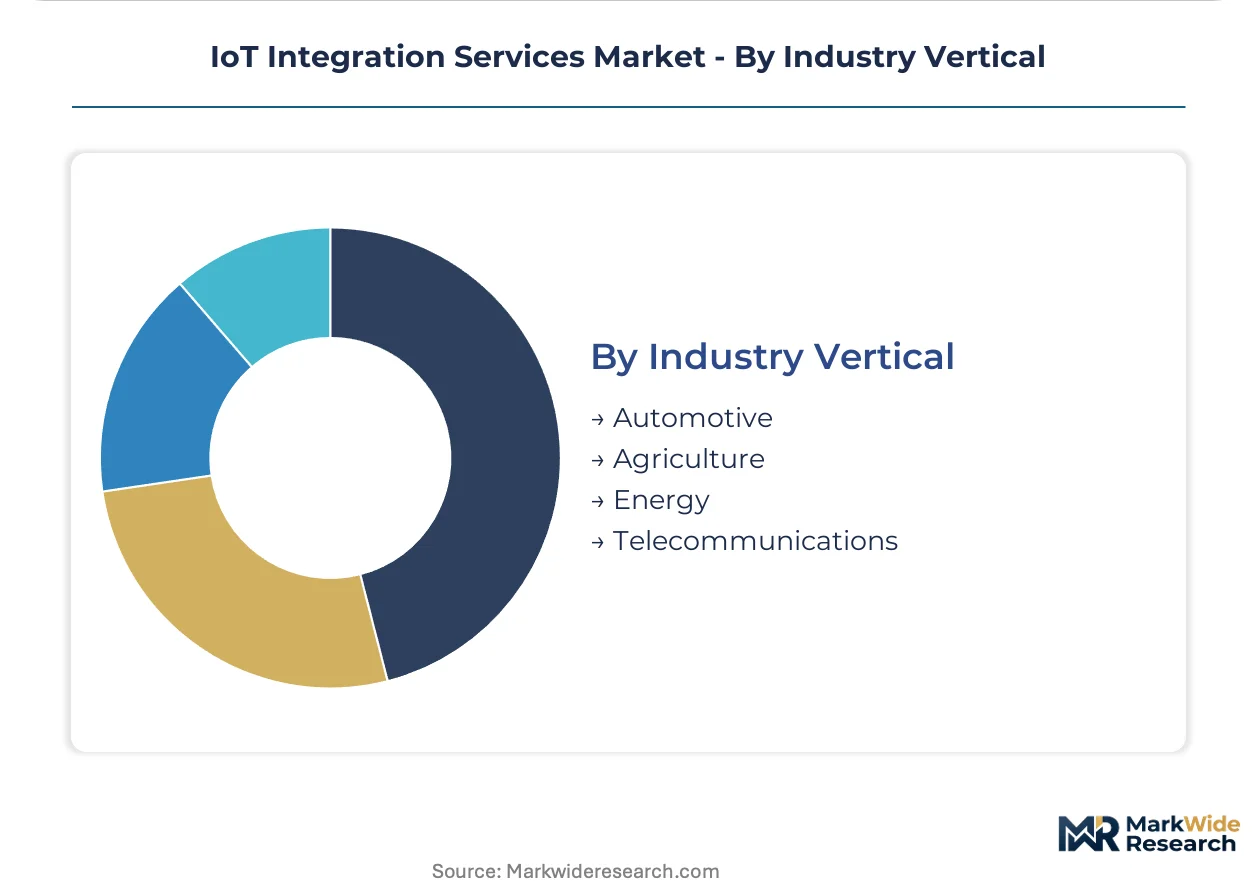
Automotive anchors vertical revenue, with Energy expanding most quickly as critical infrastructure designations broaden regulatory scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium service demand through industrial digitization mandates, while the United States concentrates cloud-to-edge deployment scale across energy and automotive verticals. Japan's Society 5.0 framework and India's manufacturing expansion create divergent growth vectors across the Asia-Pacific rim.
Germany
Smart factory clusters in Baden-Württemberg and Bavaria drive protocol harmonization demand for brownfield equipment retrofitting. The EU NIS2 Directive mandates incident reporting and risk management for critical infrastructure operators, expanding security-integrated deployment services. Stuttgart and Wolfsburg automotive facilities deploy mesh networking protocols to eliminate single points of failure in production lines.
United States
Energy utilities in Texas and telecommunications operators unbundle hardware procurement from multi-year managed service agreements. NIST cybersecurity frameworks shape procurement specifications and vendor qualification pathways for connected infrastructure. Greater Boston and Pacific Northwest technology corridors concentrate edge computing development for latency-sensitive industrial applications.
Japan
METI-led smart factory programs create demand for hybrid cloud-on-premises architectures in manufacturing and energy sectors. The country's national industrial standards regulator enforces conformity assessments for connected device ecosystems through JIS certification requirements. Kanto and Kansai industrial belts anchor sensor-to-cloud integration projects for predictive maintenance systems.
India
Domestic manufacturing expansion under the PLI scheme accelerates demand for legacy equipment connectivity and OT-IT convergence expertise. The central bank's digital infrastructure guidelines shape procurement for financial services IoT deployments. Maharashtra and Gujarat industrial corridors concentrate smart factory pilot programs for automotive component suppliers.
United Kingdom
Healthcare providers and telecommunications operators drive compliance-integrated deployment demand around data sovereignty requirements. The national data protection regulator enforces GDPR-aligned accountability for connected medical device networks. London and Southeast technology clusters concentrate consulting engagements for hybrid architecture design.
IoT Integration Services Market Competitive Environment
Top-tier vendors anchor high-margin vertical solutions, while mid-tier specialists compete on OT-IT convergence expertise and regional compliance knowledge. The market structure fragments across cloud hyperscalers, networking hardware-software convergers, and systems integration consultancies. Three archetypes dominate: platform-native service bundlers, security-integrated infrastructure providers, and outcome-based managed service operators. Competitive moves concentrate on M&A for OT talent acquisition and strategic partnerships for edge-native security certification.
Within the platform-native tier, Microsoft Corporation and Amazon Web Services, Inc. exemplify cloud-to-edge infrastructure scale. Cisco Systems, Inc. occupies a position among networking hardware-software convergers. Tata Consultancy Services represents the systems integration archetype with India-based delivery scale.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Cisco Systems, Inc. |
| Accenture |
| IBM |
| Intel Corporation |
| SAP SE |
| Tata Consultancy Services |
| Deloitte |
| Others |
Value Chain & Pricing Dynamics
OT-IT convergence engineers concentrated in Germany's Baden-Württemberg and Bavaria clusters command wage premiums that compress pricing-tier spreads between premium managed-service bundles and commodity device-connectivity offerings. Labor-cost differentials between these specialized European talent pools and emerging delivery hubs in India widen margin capture opportunities for service providers with geographic arbitrage capabilities.
Pricing Analysis
The bundled-versus-unbundled service split separates hardware procurement from multi-year managed service agreements. Three-tier pricing structure across premium compliance-integrated, standard protocol-harmonization, and economy device-connectivity levels stratifies buyer segments. Cost compression in the economy tier intensifies as cloud hyperscalers automate baseline connectivity provisioning. Healthcare providers and telecommunications operators exhibit lowest price sensitivity due to regulatory accountability requirements, while automotive component suppliers drive hardest bargain on implementation fees.
Supply Chain Analysis
Single-source vulnerability sits with East Asian semiconductor fabrication for sensor modules and edge processors. Manufacturing concentrates in Taiwan, South Korea, and mainland China. Component sourcing draws from concentrated silicon wafer suppliers, specialty memory foundries, and precision sensor fabricators. Tariff exposure on edge hardware imports into European and North American assembly facilities elevates landed cost volatility. Distribution runs through authorized distributor networks serving systems integrators and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where service delivery from India's Maharashtra and Gujarat industrial corridors captures 40-60% labor-cost savings against German engineering rates, while EU NIS2 compliance mandates preserve premium pricing power for Europe-based advisory layers.
For Market Incumbents: Deepen captive OT-IT talent development through acquisition of specialized protocol-engineering boutiques in Stuttgart and Wolfsburg automotive clusters. Cloud hyperscaler encroachment on baseline connectivity services threatens margin compression in the economy tier; defend position by embedding security-integrated deployment workflows that embed EU AI Act conformity assessments upstream in product development cycles.
For New Entrants and Emerging Players: Mid-tier automotive component suppliers in India's PLI scheme corridors represent an underserved buyer archetype with acute brownfield integration needs and limited incumbent service relationships. White-space concentration sits in legacy equipment retrofitting for German automotive suppliers expanding Indian manufacturing footprints. Penetrate through outcome-based contracting models that transfer compliance accountability from equipment vendors to specialized service providers.
For Investors and Strategic Acquirers: Cloud hyperscalers with edge-to-cloud infrastructure scale are the most active acquirer in this space, targeting OT-IT convergence boutiques for vertical solution bundling. Long-term viability favors platform-native service bundlers with embedded compliance architectures over pure-play implementation shops. Watch for consolidation signals when edge-native security standards achieve certification harmonization across European and Japanese regulatory frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of OT-IT Convergence Specialist | Microsoft and AWS target German protocol-engineering boutiques for automotive vertical bundling. |
| Edge-Native Security Certification Program | Cisco pursues JIS and EU AI Act dual certification for factory-floor mesh networking deployments. |
| Outcome-Based Service Contracting Expansion | Tata Consultancy Services structures performance-guaranteed agreements for Texas energy utility retrofits. |
| Hybrid Cloud-On-Premises Architecture Partnership | Accenture collaborates with METI-designated smart factory operators in Kanto industrial belt. |
| Legacy Equipment Retrofitting Scale-Up | IBM expands Stuttgart and Wolfsburg implementation teams for OPC-UA adapter commissioning. |
Study Parameters
Bottom-up end-user procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core. Primary interviews with IoT platform engineers, OT-IT integration specialists, hospital biomedical engineering directors, automotive plant maintenance managers, and energy utility grid modernization officers supply demand-side calibration. Secondary validation draws from SEC 10-K hyperscaler disclosures, EU NIS2 implementation guidance documents, METI smart factory program reports, and FDA connected medical device guidance filings. Triangulation between these sources anchors volume and value estimates.
Input-output matrices map service-type demand against deployment-mode supply capacity across the projection horizon. Segmentation dimensions include service type, deployment architecture, end-user sophistication tier, and industry vertical regulatory intensity. CAGRs derive from logistic adoption curves fitted to brownfield retrofitting pipelines and greenfield edge-computing deployment schedules. Forecast inputs incorporate EU AI Act risk-classification rollout timelines and NIS2 critical infrastructure designations.
Underlying measurement precision varies by segment; cloud-based deployment volumes carry tighter precision than emerging edge-native service categories. Forecasts reflect documented assumptions around regulatory enforcement intensity and semiconductor supply normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
Internet of Things in Energy Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
IoT Data Governance Market