
 IoT Development Kit Market | 2026-2036
IoT Development Kit Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Development Kit Market Foresight
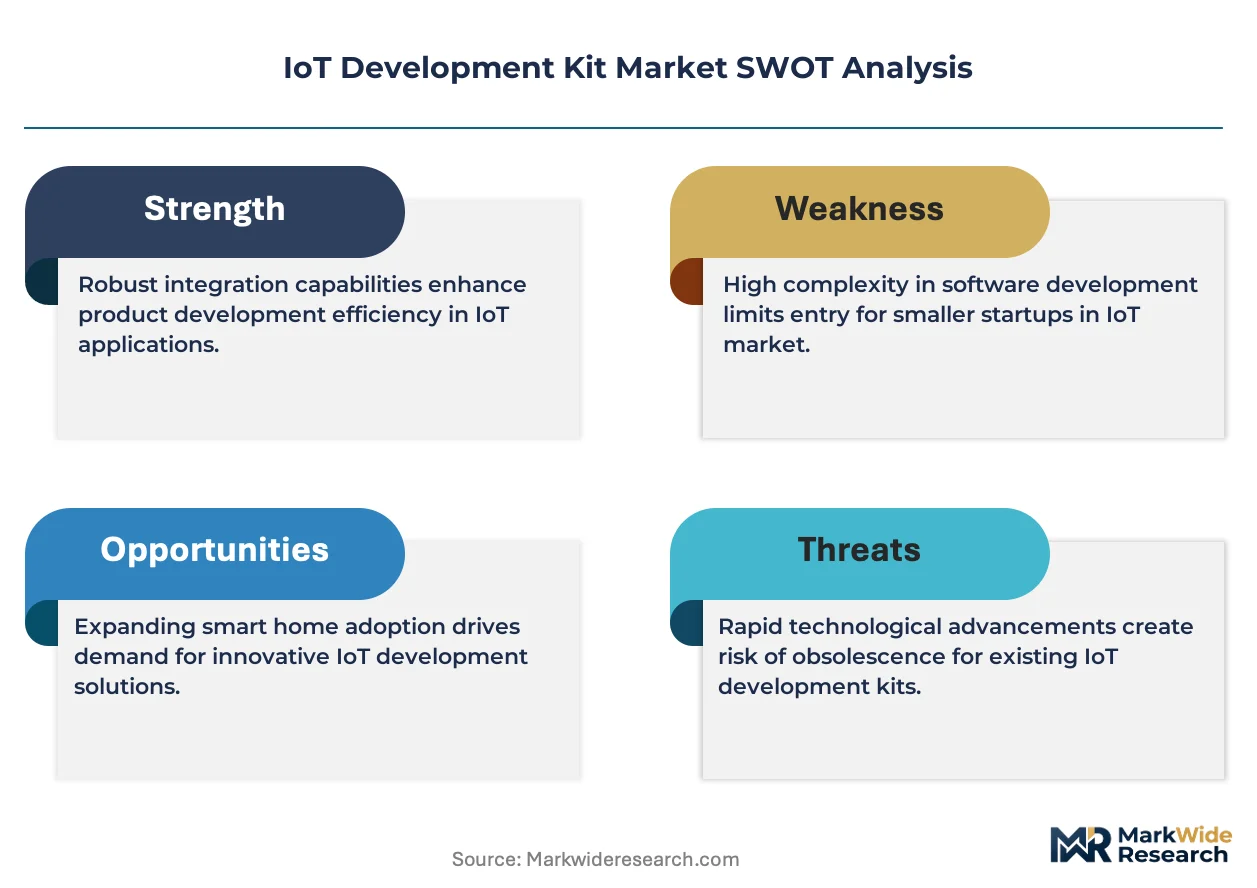
CE marking under the Radio Equipment Directive is unwinding competitive access for vendors lacking certified RF modules. Nordic Semiconductor leverages its integrated transceiver-stack architecture to sustain design-win rates in low-power Bluetooth segments. NXP Semiconductors anchors its position through automotive-grade security cores that dominate industrial gateway applications.
An IoT development kit bundles microcontrollers, wireless radios, sensors, and software SDKs into a programmable prototyping platform, typically supporting sub-1 GHz to 2.4 GHz frequency ranges with milliwatt-scale power budgets, enabling rapid validation of connected device concepts before custom PCB fabrication. Hardware kits carrying pre-certified RF modules command the dominant share of procurement budgets, while software frameworks represent the fastest-expanding margin pool as vendors shift toward recurring licensing models. LPWAN technology segments are maturing in utility metering, whereas Wi-Fi segments are accelerating in smart home applications where throughput requirements dominate.
The FCC in the United States enforces Part 15 emissions rules that dictate modular approval paths for kits targeting the US market, while ETSI harmonized standards in Europe mandate SAR testing and spectrum efficiency benchmarks that reshape product design cycles. China's MIIT issues radio type-approval certificates that gate market entry for imported kits. Stakeholders must monitor divergence between regional certification timelines and pre-integrate multi-band radios to avoid fragmented SKU strategies.
Market Dynamics
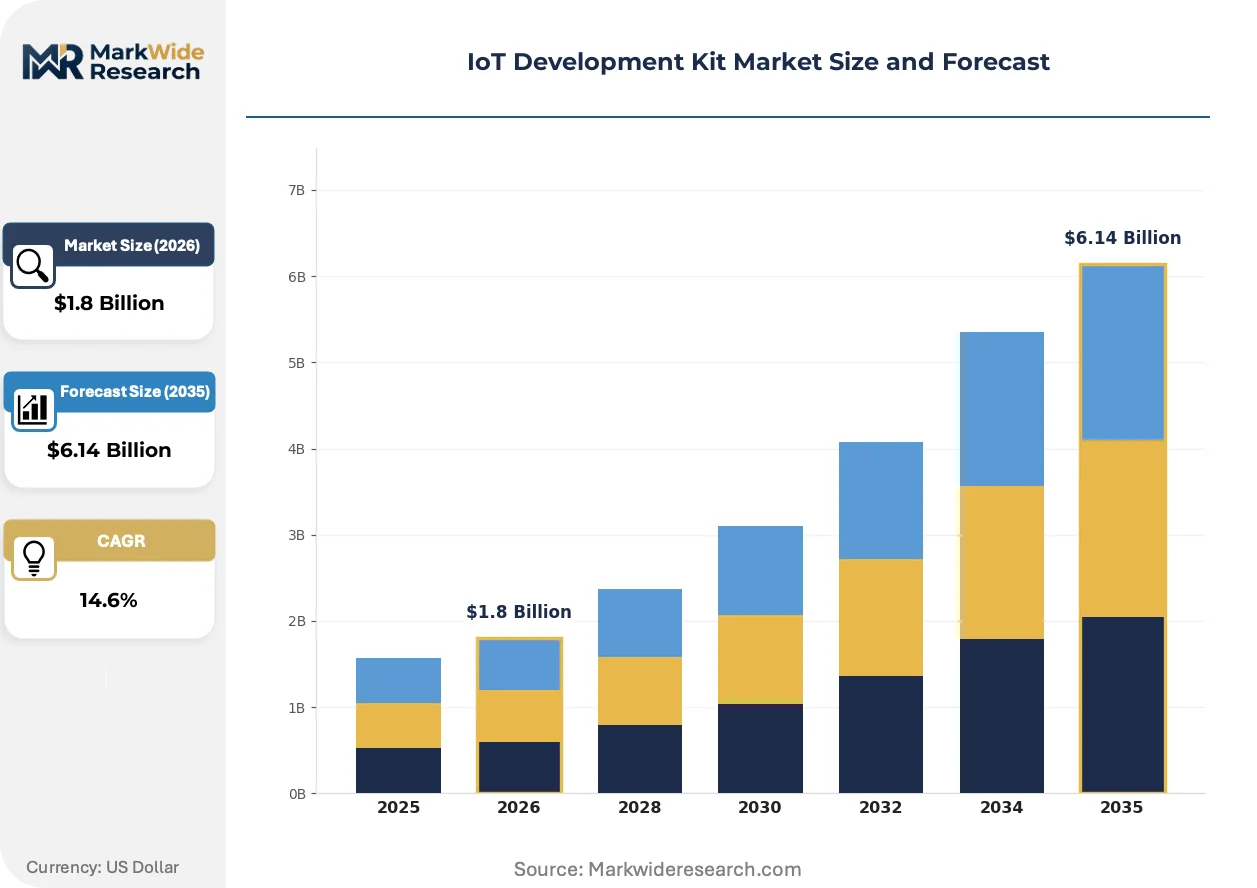
Pre-certified RF modules are compressing design cycles and redistributing margin pools from hardware toward recurring software licensing frameworks, forcing kit vendors to restructure revenue models around SDK subscriptions rather than one-time board sales.
Growth Catalysts
- EU AI Act compliance mandates:Industrial automation buyers in Germany are procuring edge-controller kits with embedded audit trails to satisfy algorithmic transparency requirements for predictive maintenance systems.
- Automotive OEM lab buildouts:Tier-1 suppliers in Stuttgart and Munich are establishing captive IoT prototyping facilities, concentrating demand for automotive-grade security cores and multi-protocol radios.
- LPWAN utility metering maturation:Sub-1 GHz development kits with Sigfox and LoRa stacks are capturing procurement budgets as European water and gas utilities replace mechanical meters with connected endpoints.
Market Restraints
- Silicon foundry concentration:Advanced microcontroller fabrication relies on Taiwan Semiconductor Manufacturing capacity, exposing kit vendors to geopolitical supply interruptions and allocation rationing.
- Multi-jurisdiction certification costs:FCC Part 15 modular approval, ETSI EN 300 328 spectrum efficiency testing, and MIIT radio type-approval certificates collectively add eighteen to twenty-four months to product launch timelines.
- Wi-Fi 6 module substitution:Commoditized USB dongle solutions from consumer electronics supply chains are eroding pricing power in smart home prototyping segments where throughput requirements are modest.
Strategic Opportunities
- India BIS certification pre-positioning:Kit vendors establishing local test labs in Bengaluru and Hyderabad can capture design wins from domestic automotive and agricultural sensor manufacturers ahead of mandatory radio equipment marking.
- Matter protocol convergence:Thread and Wi-Fi unified stacks are opening white space in smart home development platforms where previously fragmented Zigbee, Z-Wave, and proprietary ecosystems required separate hardware validation.
- Edge AI accelerator integration:Neural processing unit coprocessors are converging with traditional microcontroller architectures, enabling voice and vision inference on milliwatt power budgets for battery-constrained industrial wearables.
Industry Challenges
- RF firmware specialization scarcity:Vendors report acute shortages of engineers proficient in BLE 5.3 mesh stack optimization and sub-GHz antenna matching for metal-rich factory environments.
- Legacy PLC integration complexity:Brownfield industrial deployments require protocol bridges between Modbus and OPC-UA endpoints, extending commissioning timelines and eroding kit margin through custom engineering services.
- RoHS exemption cliff:Pending expiration of lead-solder exemptions for high-reliability automotive applications is forcing PCB substrate and component qualification cycles that compress hardware release windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Development Kit Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Kits, Software Frameworks, Connectivity Modules, Firmware Solutions End User: Manufacturers, Developers, Startups, Enterprises Technology: LPWAN, Bluetooth, Zigbee, Wi-Fi Application: Smart Home, Industrial Automation, Healthcare, Agriculture |
| Companies Covered | Google, Intel Corporation, Microsoft, NXP Semiconductors, ARM, Amazon Web Services, Nordic Semiconductor, Silicon Laboratories, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Development Kit Market Shifts & Advancements
Edge-native machine learning inference is compressing the boundary between sensor acquisition and cloud analytics, redefining kit architecture around on-device model execution rather than raw data transmission.
RISC-V open instruction set architectures are displacing proprietary ARM Cortex-M licensing in cost-sensitive volume applications. Chinese white-label electronics manufacturers are adopting T-Head and SiFive cores for sub-dollar sensor nodes. This shift is fragmenting toolchain ecosystems and forcing incumbent vendors to dual-source compiler support or cede low-end design wins.
ETSI harmonized standards for cyber resilience in radio equipment are mandating firmware update mechanisms and secure boot chains for all CE-marked kits entering European distribution. Industrial gateway vendors must now integrate hardware security modules and attestation protocols previously reserved for payment terminals. German automotive OEMs are qualifying suppliers against these requirements eighteen months ahead of enforcement deadlines to lock in preferred vendor status.
Subscription-based SDK licensing is replacing perpetual seat sales as the dominant procurement model for enterprise IoT labs. Siemens, Bosch, and Continental development centers in Bavaria are negotiating multi-year framework agreements that bundle cloud simulation credits with hardware board allocations. This transformation concentrates purchasing authority with procurement functions rather than individual engineering managers, elongating sales cycles but improving vendor revenue predictability.
IoT Development Kit Market Segmentation
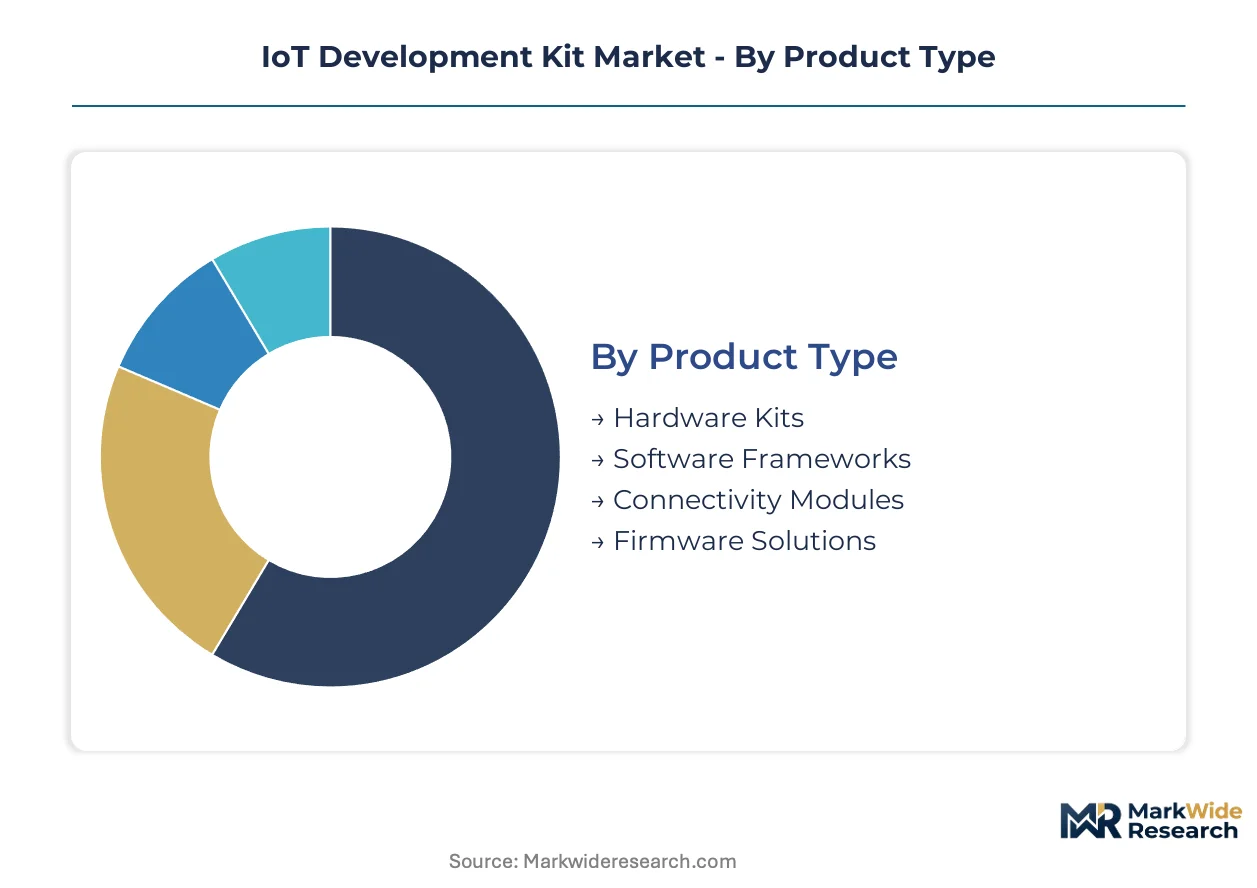
Segmentation in the IoT development kit market reveals where margin pools concentrate and where commoditization pressures erode pricing power. Kit vendors must align R&D roadmaps with the segments where software licensing frameworks can displace one-time hardware sales.
Product Type:
Software frameworks face the most acute substitution pressure as open-source alternatives commoditize middleware stacks, while hardware kits with pre-certified RF modules defend margin through regulatory moats.
- Hardware Kits:Bundled microcontrollers, wireless radios, and sensors with pre-certified RF modules command dominant procurement budgets. German automotive OEMs in Stuttgart and Munich prioritize automotive-grade security cores and multi-protocol radios for captive prototyping facilities.
- Software Frameworks:SDKs and middleware stacks represent the fastest-expanding margin pool as vendors shift toward recurring licensing models. Siemens, Bosch, and Continental development centers in Bavaria negotiate multi-year framework agreements bundling cloud simulation credits with hardware allocations.
- Connectivity Modules:Pre-integrated radio subsystems compress design cycles but face margin compression from commoditized USB dongle solutions.
- Firmware Solutions:Low-level stack implementations and bootloader architectures concentrate expertise scarcity in BLE 5.3 mesh optimization.
Hardware kits retain volume leadership; software frameworks hold the steepest expansion curve.
End User:
Cost tier stratification separates procurement authority between centralized enterprise frameworks and fragmented individual developer purchases.
- Manufacturers:Industrial automation buyers expanding deployment of connected sensors and edge controllers concentrate demand for predictive maintenance validation platforms. EU AI Act compliance mandates drive procurement of edge-controller kits with embedded audit trails.
- Enterprises:Large-scale IoT labs negotiate consolidated purchasing authority, elongating sales cycles but improving vendor revenue predictability through multi-year commitments.
- Developers:Individual practitioners and small teams prioritize rapid prototyping capabilities over certification completeness.
- Startups:Early-stage companies favor low-cost entry points with upgrade paths to production-grade certifications.
Manufacturers dominate absolute spend; enterprises are gaining share fastest through framework consolidation.
Technology:
Application-driven throughput requirements determine technology selection, with low-bandwidth utility applications diverging from high-throughput consumer scenarios.
- LPWAN:Sub-1 GHz development kits with Sigfox and LoRa stacks capture procurement budgets as European water and gas utilities replace mechanical meters with connected endpoints.
- Wi-Fi:Throughput-optimized kits accelerate in smart home applications where bandwidth requirements dominate, though Wi-Fi 6 module substitution from consumer electronics supply chains erodes pricing power.
- Bluetooth:Low-power segments sustain design-win rates through integrated transceiver-stack architectures in milliwatt-scale applications.
- Zigbee:Legacy mesh networking faces displacement from Matter protocol convergence unifying previously fragmented ecosystems.
LPWAN retains volume leadership in utility metering; Wi-Fi holds the steepest expansion curve in residential applications.
Application:
Maturity differentiation separates established industrial deployments from emerging agricultural sensor networks still defining certification requirements.
- Industrial Automation:Brownfield deployments require protocol bridges between Modbus and OPC-UA endpoints, extending commissioning timelines and eroding kit margin through custom engineering services.
- Smart Home:Matter protocol convergence opens white space where Thread and Wi-Fi unified stacks replace previously separate Zigbee, Z-Wave, and proprietary hardware validation requirements.
- Healthcare:Battery-constrained industrial wearables drive edge AI accelerator integration with neural processing unit coprocessors enabling voice and vision inference on milliwatt power budgets.
- Agriculture:Indian domestic sensor manufacturers present pre-positioning opportunities ahead of mandatory BIS radio equipment marking.
Industrial automation retains volume leadership; agriculture holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers in Germany concentrate procurement authority for edge-controller kits, while automotive OEM captive labs in Stuttgart and Munich reshape demand patterns across European distribution channels.
United States
Smart home prototyping segments drive Wi-Fi kit demand as Matter protocol adoption accelerates among residential device manufacturers. FCC Part 15 emissions rules enforce modular approval paths that extend certification timelines for imported radio subsystems. Silicon Valley hardware incubators and Austin-based industrial IoT clusters absorb premium-tier development platforms with pre-certified RF modules.
Germany
Automotive OEMs in Stuttgart and Munich establish captive prototyping facilities requiring automotive-grade security cores and multi-protocol radios. EU AI Act compliance mandates edge-controller kits with embedded audit trails for predictive maintenance validation. Bavarian development centers at Siemens, Bosch, and Continental negotiate multi-year framework agreements bundling cloud simulation credits with hardware allocations.
China
Domestic white-label electronics manufacturers adopt RISC-V architectures for sub-dollar sensor nodes targeting cost-sensitive volume applications. MIIT radio type-approval certificates gate market entry for imported kits, forcing vendors to pre-integrate multi-band radios or fragment SKU strategies. Shenzhen and Shanghai hardware ecosystems concentrate firmware specialization talent for BLE mesh stack optimization.
India
Agricultural sensor manufacturers present pre-positioning opportunities ahead of mandatory BIS radio equipment marking enforcement. Domestic automotive component suppliers in Bengaluru and Hyderabad establish qualification programs for edge AI accelerator integration. TRAI spectrum allocation frameworks for unlicensed sub-GHz bands enable LPWAN utility metering deployments in water and gas distribution networks.
Japan
Industrial wearables manufacturers demand neural processing unit coprocessors enabling voice and vision inference on milliwatt power budgets. METI standardization initiatives for cyber resilience in connected equipment align with ETSI harmonized requirements for firmware update mechanisms. Tokyo and Osaka industrial automation clusters prioritize protocol bridges between legacy Modbus and OPC-UA endpoints for brownfield deployments.
IoT Development Kit Market Competitive Landscape
Player mix skews toward semiconductor specialists with integrated transceiver-stack architectures and cloud-platform vendors bundling hardware with recurring software licensing. Market structure exhibits tiered consolidation around RF module certification holders and open-source toolchain providers. Strategic archetypes include automotive-grade security core suppliers, low-power Bluetooth specialists, and edge AI accelerator integrators. Competitive moves concentrate on SDK subscription model transitions and multi-jurisdiction certification pre-positioning.
Within the integrated semiconductor tier, NXP Semiconductors and Nordic Semiconductor exemplify divergent architectural approaches to RF module dominance. NXP anchors automotive-grade positioning through security core specialization for industrial gateway applications. Nordic occupies a position in low-power Bluetooth segments through transceiver-stack integration. Among cloud-platform entrants, Amazon Web Services represents the subscription-model archetype bundling hardware allocations with cloud simulation credits. Google and Microsoft sit within the software framework tier, leveraging developer ecosystem scale to displace perpetual seat sales with recurring licensing structures.
| Leading Market Players |
|---|
| Intel Corporation |
| Microsoft |
| NXP Semiconductors |
| ARM |
| Amazon Web Services |
| Nordic Semiconductor |
| Silicon Laboratories |
| Broadcom |
| Others |
Supply & Pricing Matrix
CE marking under the Radio Equipment Directive gates both supplier qualification and price differentiation simultaneously, compressing margins for vendors lacking certified RF modules while enabling premium capture for integrated stack providers serving German automotive OEMs.
Pricing Analysis
Long-term framework agreements with semiconductor foundries index wafer costs to commodity silicon pricing, embedding cost-plus structures into kit manufacturing. Three-tier pricing structure across premium automotive-grade, standard industrial, and economy consumer tiers separates procurement budgets by certification completeness and security core integration. Price differentiation centers on RF module pre-certification status and SDK subscription bundling. Margins are tightening in Wi-Fi segments due to USB dongle substitution from consumer electronics supply chains. Individual developers and startup segments exhibit highest price sensitivity, while enterprise framework buyers prioritize predictable multi-year commitments over per-unit discounts.
Supply Chain Analysis
Strategic stockpiling of certified RF modules dominates inventory strategy among German and US kit vendors seeking to buffer eighteen-to-twenty-four-month certification timelines. Advanced microcontroller fabrication draws from Taiwan, South Korea, and the United States, with Taiwan Semiconductor Manufacturing capacity anchoring high-performance node supply. Silicon wafers, RF front-end components, and automotive-grade substrate materials constitute critical input dependencies. Single-source vulnerability in Taiwan-based foundry capacity exposes vendors to geopolitical allocation rationing. Distribution runs through authorized distributor networks serving OEM captive labs and enterprise procurement functions, with direct sales teams handling framework negotiations at Siemens, Bosch, and Continental development centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SDK subscription licensing expands faster than hardware board sales, converting one-time prototyping purchases into recurring revenue streams with cloud simulation credit bundling.
For Market Incumbents: Secure automotive-grade security core certification ahead of EU AI Act enforcement deadlines to lock in preferred supplier status with Stuttgart and Munich OEM labs. Deepen backward integration into RF module design to reduce dependence on third-party certification timelines. Defend against RISC-V commoditization by dual-sourcing compiler support for cost-sensitive volume applications. For New Entrants and Emerging Players: Firmware update mechanism gaps in legacy kit portfolios open white space for cyber-resilient platform entrants targeting ETSI harmonized standard compliance. Indian agricultural sensor manufacturers present the most penetrable geography ahead of mandatory BIS radio equipment marking. Pursue cloud-native SDK bundling with hardware allocation starter packs to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward edge-controller kit vendors with embedded audit trail capabilities and pre-certified RF module portfolios. Long-term viability favors platform plays with recurring licensing infrastructure over pure hardware component suppliers. Monitor Matter protocol certification velocity as inflection indicator for smart home segment consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| RF Module Certification Pre-Positioning | CE marking compliance under ETSI EN 300 328 gates European market access for kit vendors. |
| SDK Subscription Model Transition | Recurring licensing at Siemens and Bosch development centers improves revenue predictability. |
| Edge AI Accelerator Integration | Neural processing unit coprocessors enable voice inference on milliwatt budgets for industrial wearables. |
| Multi-Jurisdiction SKU Consolidation | Pre-integrated multi-band radios reduce fragmentation between FCC Part 15 and MIIT approval paths. |
| India BIS Test Lab Establishment | Local certification capability in Bengaluru captures design wins from domestic automotive suppliers. |
Research Methodology
A spread of perspectives from kit vendor product managers, semiconductor foundry planning officers, enterprise IoT lab procurement leads, and regulatory compliance specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, ETSI harmonized standard publications, MIIT radio type-approval registries, and SEC filings from listed semiconductor suppliers. Bottom-up demand modeling from individual prototyping purchases triangulated against top-down OEM framework spending estimates.
Segmentation dimensions modeled span hardware kit versus software framework product types, LPWAN through Wi-Fi technology categories, and manufacturer through enterprise end-user tiers across the projection horizon. CAGRs derive from regression analysis against historical certification timeline data and foundry capacity expansion announcements. Forecast inputs incorporate EU AI Act compliance deadline proximity and Matter protocol adoption velocity among residential device manufacturers.
Underlying assumptions cover sustained Taiwan foundry allocation access, stable ETSI-FCC regulatory convergence, and linear Matter protocol certification ramp, with deviation risk concentrated in geopolitical supply interruption scenarios. Revision becomes warranted when foundry utilization rates cross threshold levels triggering allocation rationing or when regulatory timeline divergence exceeds six months between major jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
Internet of Things in Energy Market